
 Tangyuan Machine Market | 2026-2036
Tangyuan Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tangyuan Machine Market Insights
Food-grade polymer coatings on forming drums is broadening equipment durability in high-moisture environments. Zhongjia Food Machinery leverages integrated stainless-steel supply chains to control raw material costs. ANKO sustains technology leadership through precision servo-driven filling systems. Rademaker anchors European demand with modular designs that accommodate gluten-free rice flour formulations.
A tangyuan machine is automated food processing equipment that forms glutinous rice dough into uniform spheres, typically achieving outputs of 3,000–12,000 pieces per hour through rotary extrusion or piston-filling mechanisms with programmable filling-to-casing ratios. Its primary commercial purpose is to replace manual shaping in commercial kitchens and industrial facilities producing tangyuan, mochi, and similar filled dumpling products. Fully automatic machines command the largest installed base due to labor cost pressures in East Asian food manufacturing, while custom machines represent the fastest-growing category as specialty producers seek equipment adapted to regional recipes and alternative fillings. Steam cooking technology dominates operational specifications, though freezing-integrated lines are gaining share among exporters requiring extended shelf-life workflows.
China's MIIT and SAMR enforce GB standards for food machinery hygiene and electrical safety, while Japan's METI oversees JIS compliance for imported equipment used in commercial kitchens. These frameworks shape demand by mandating clean-in-place compatibility and traceable material certifications that filter out lower-tier suppliers. Stakeholders must monitor how evolving dual carbon goals in China and carbon border adjustments in Europe reshape equipment energy efficiency requirements and export eligibility criteria.
Market Dynamics
East Asian commercial kitchens face acute labor shortages while MIIT tightens stainless-steel surface specifications, forcing equipment buyers to reconcile automation investments with material compliance costs simultaneously.
Growth Catalysts
- Jiangsu-Zhejiang cluster modernization:Traditional rice-ball manufacturing hubs are retiring manual shaping lines in favor of rotary extrusion systems capable of 3,000–12,000 pieces per hour.
- GB standards compliance:China's MIIT and SAMR mandates for clean-in-place compatibility and traceable material certifications are filtering out lower-tier suppliers, consolidating demand toward certified equipment vendors.
- Steam-to-freezing workflow integration:Export-oriented processors are adopting freezing-integrated production lines to meet extended shelf-life requirements in overseas markets.
Market Restraints
- 316L stainless-steel price volatility:Food-grade contact surface specifications under tightening GB standards expose equipment margins to nickel and molybdenum input cost swings.
- Supply concentration in Yangtze River Delta:Forming drum and servo motor suppliers cluster in a narrow geographic band, creating vulnerability to regional logistics disruptions.
- Gluten-free rice flour formulation limits:Modular machine designs accommodate alternative flours, but precision filling mechanisms struggle with non-glutinous binding properties below certain moisture thresholds.
Strategic Opportunities
- Southeast Asia underpenetration:Vietnam and Thailand's frozen dessert sectors lack indigenous equipment manufacturing, creating import demand for Chinese and Japanese systems.
- EU carbon border adjustment alignment:Chinese exporters can capture premium positioning by certifying equipment energy efficiency ahead of phased CBAM implementation on industrial machinery.
- Servo-pneumatic hybrid filling convergence:Combining precision servo control with pneumatic cost efficiency opens mid-market segments previously priced out of fully automatic systems.
Industry Challenges
- Clean-in-place engineering talent scarcity:Equipment manufacturers struggle to hire fluid dynamics specialists capable of designing spray-ball configurations that satisfy both MIIT hygiene protocols and customer throughput requirements.
- Legacy analog control integration friction:Retrofitting existing production lines with programmable filling-to-casing ratio interfaces requires custom electrical engineering that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tangyuan Machine Market |
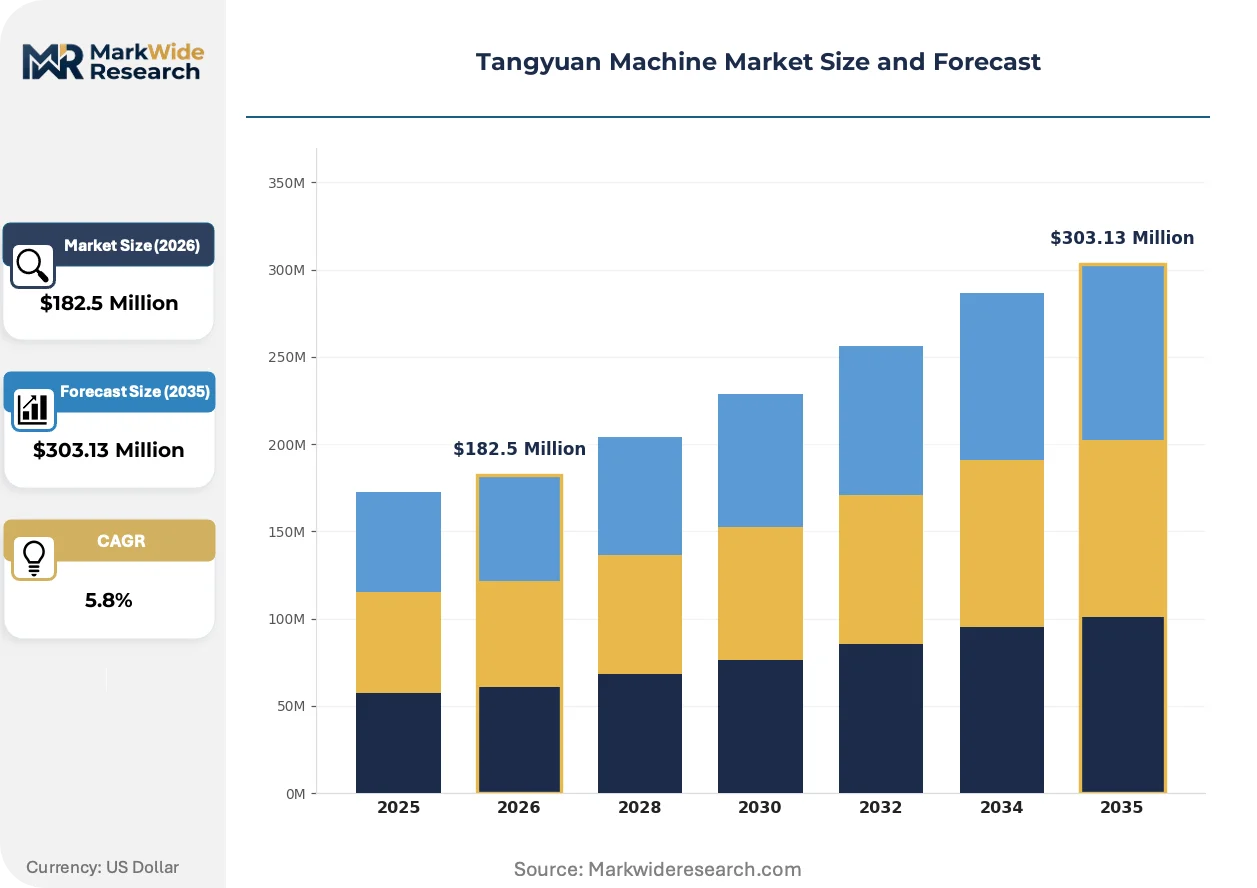
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $303.13 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Machines, Semi-Automatic Machines, Fully Automatic Machines, Custom Machines Technology: Steam Cooking, Boiling, Freezing, Refrigeration End User: Restaurants, Food Processing Companies, Caterers, Supermarkets Size: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | Zhongjia Food Machinery, Jinan Vmetro Machinery, Taizhou, ANKO, Fritsch, AMF Bakery Systems, Rademaker, Rondo, Kaak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tangyuan Machine Market Trends and Innovations
Automation architectures are absorbing moisture-resistant materials while regulatory pressure on contact surfaces intensifies, reshaping how equipment durability and compliance are engineered simultaneously.
Food-grade polymer coatings on forming drums are absorbing high-humidity operational stress that previously degraded uncoated metal surfaces within 18–24 months. Frozen dessert processors in Zhejiang province are adopting these systems at replacement cycles compressed to 14–16 months. The technology is absorbing maintenance budget allocations that formerly flowed to spare drum inventories, compressing aftermarket parts revenue pools for legacy suppliers.
China's MIIT is tightening GB 16798 hygiene specifications for food machinery contact surfaces, mandating Ra 0.8μm surface roughness maximums and 316L stainless-steel minimums for new installations. Equipment importers face extended customs inspection protocols at Shanghai and Ningbo ports. Japanese METI-certified systems command preference among processors seeking expedited compliance verification.
After-sales service unbundling is fragmenting traditional equipment procurement into separate hardware, installation, and maintenance contracts. Mid-sized commercial kitchens in Jiangsu province are sourcing forming modules from one vendor and control systems from another, then contracting third-party integrators. This pattern is most visible among 500–2,000 kg/day output facilities seeking to arbitrage component specialization without single-source dependency.
Tangyuan Machine Market Segmentation
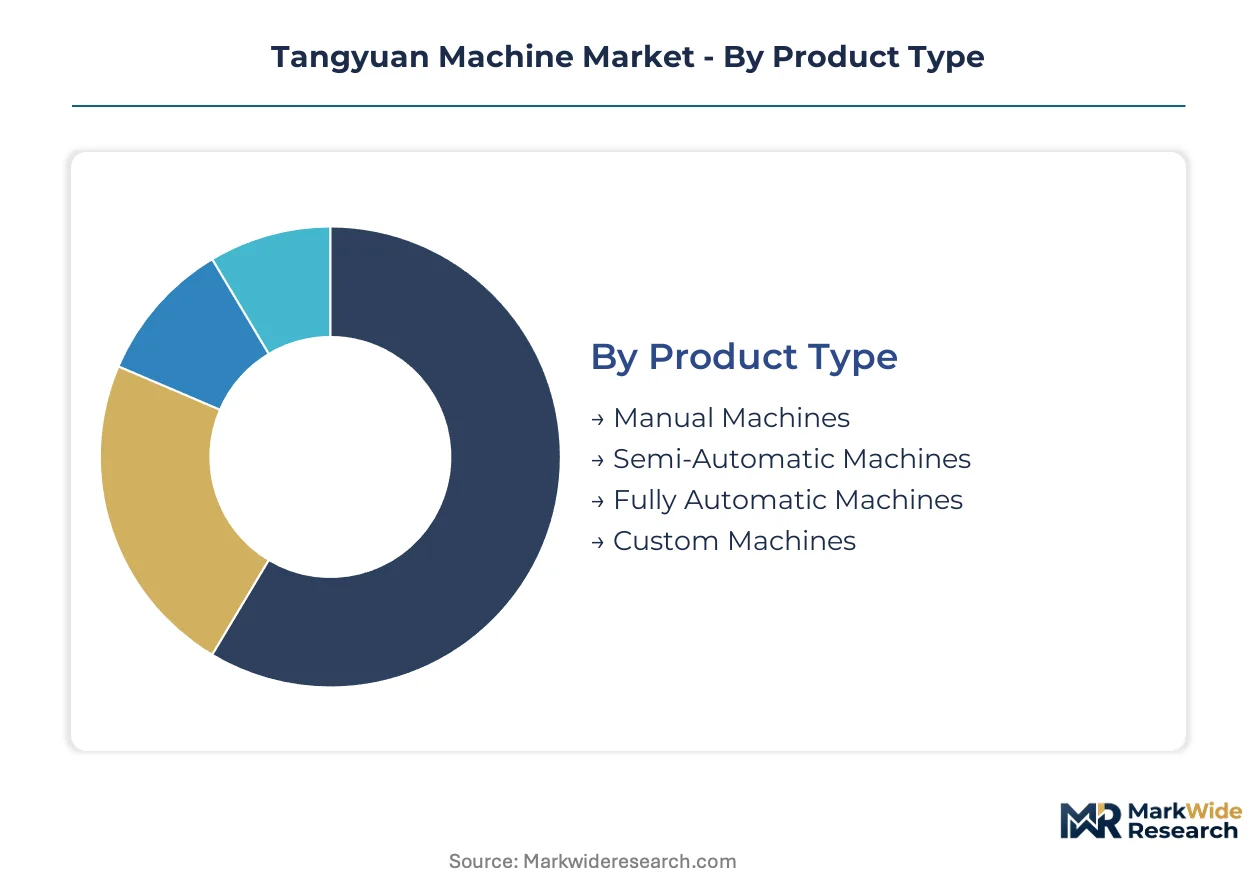
Equipment buyers in the tangyuan machine market face divergent constraints across labor costs, output volumes, and regulatory compliance. Segmentation reveals how automation intensity and thermal processing methods separate price-sensitive commercial kitchens from export-oriented industrial processors.
Product Type:
Cost tier separates buyers seeking labor substitution from those requiring recipe flexibility.
- Fully Automatic Machines:Rotary extrusion and piston-filling systems achieve 3,000–12,000 pieces per hour with programmable filling-to-casing ratios. Demand concentrates among Jiangsu and Zhejiang food processing companies modernizing traditional rice-ball manufacturing clusters under MIIT stainless-steel compliance pressure.
- Custom Machines:Modular architectures accommodate regional recipes, alternative fillings, and gluten-free rice flour formulations. Specialty producers across East Asia commission adapted equipment to differentiate in premium frozen dessert segments.
- Semi-Automatic Machines:Hybrid manual-automation interfaces suit mid-sized commercial kitchens balancing capital constraints with throughput targets.
- Manual Machines:Entry-level forming tools persist in artisanal producers and training facilities where hands-on technique preservation outweighs speed.
Volume sits with fully automatic installations; growth tilts toward custom configurations.
Technology:
Application workflow determines thermal processing architecture selection.
- Steam Cooking:Saturated vapor systems dominate operational specifications for immediate-consumption tangyuan, achieving uniform gelatinization of glutinous rice dough. Restaurants and caterers in China specify steam-integrated lines to satisfy traditional texture requirements.
- Freezing:Blast-freeze and IQF workflows extend shelf-life for export markets, requiring integrated cooling tunnels post-forming. Food processing companies targeting overseas distribution are adopting freezing-integrated production lines to meet extended logistics timelines.
- Boiling:Direct water immersion units serve high-volume institutional kitchens with continuous throughput needs.
- Refrigeration:Controlled chilling maintains formed product integrity during buffer storage before final thermal treatment.
Steam retains the largest installed base; freezing gains share fastest among export-oriented processors.
End User:
Customer type dictates equipment scale, automation level, and after-sales service expectations.
- Food Processing Companies:Industrial-scale rotary extrusion systems with clean-in-place compatibility dominate procurement. These buyers prioritize MIIT GB 16798 compliance and traceable 316L stainless-steel certifications to expedite customs clearance at Shanghai and Ningbo ports.
- Restaurants:Compact steam-cooking units with rapid changeover capabilities suit menu diversification demands in high-turnover commercial kitchens.
- Caterers:Mobile or semi-automatic configurations balance portability with batch consistency for event-based production.
- Supermarkets:In-store production lines emphasize visual appeal and hygiene transparency for consumer-facing operations.
Procurement volume concentrates with food processing companies; supermarkets represent the steepest expansion trajectory as private-label frozen dessert programs proliferate.
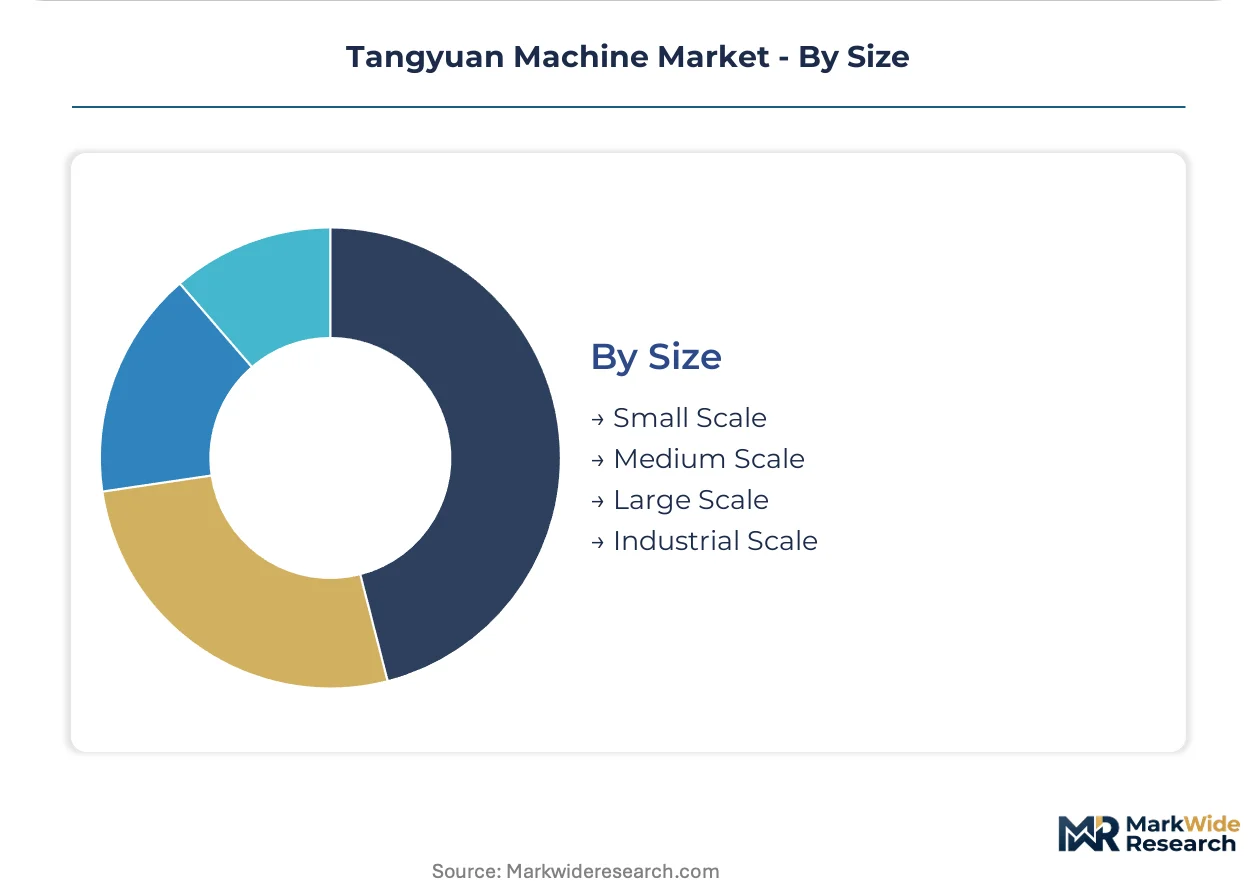
Size:
Production volume anchors capital expenditure thresholds and supply chain integration depth.
- Industrial Scale:Continuous-line systems exceed 10,000 pieces per hour with integrated forming, cooking, and freezing modules. These installations cluster in Yangtze River Delta export zones where supply concentration creates logistics vulnerability.
- Large Scale:Batch-rotary systems serve 5,000–10,000 piece hourly outputs for regional distribution networks.
- Medium Scale:1,000–5,000 piece capacity units suit provincial processors modernizing from manual shaping.
- Small Scale:Tabletop and floor-standing units below 1,000 pieces per hour serve niche producers and R&D facilities.
Industrial scale commands the highest absolute investment; medium scale climbs fastest as traditional manufacturing clusters automate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in East Asian manufacturing clusters where frozen dessert automation is replacing manual shaping lines. Jiangsu and Zhejiang provinces anchor installed capacity, while export demand pulls systems toward Southeast Asian and European compliance specifications.
China
Jiangsu and Zhejiang food processors are modernizing traditional rice-ball manufacturing clusters with rotary extrusion systems. MIIT's tightening GB 16798 hygiene specifications mandate 316L stainless-steel contact surfaces and Ra 0.8μm roughness maximums for new installations. Yangtze River Delta suppliers dominate forming drum and servo motor production, creating geographic concentration risk.
Japan
Commercial kitchens and frozen dessert exporters specify METI-certified equipment to expedite compliance verification. JIS standards for food machinery electrical safety shape import preferences among processors seeking clean-in-place compatibility. Osaka and Nagoya manufacturing zones sustain precision servo-driven filling system demand for high-throughput mochi production.
South Korea
Seoul Capital Area food companies are adopting freezing-integrated production lines for extended shelf-life export workflows. MFDS food equipment safety standards align with international hygiene protocols, filtering supplier selection toward certified vendors. Busan-Ulsan port logistics support outbound frozen dessert distribution to Southeast Asian markets.
Vietnam
Hanoi and Ho Chi Minh City frozen dessert sectors lack indigenous equipment manufacturing, creating import dependency for Chinese and Japanese systems. The country's national food safety regulator is developing machinery hygiene frameworks modeled on GB and JIS precedents. Northern industrial zones are absorbing second-hand rotary extrusion units from Zhejiang facility upgrades.
Germany
Bavaria and Baden-Württemberg baking equipment specialists supply modular designs accommodating gluten-free rice flour formulations. REACH compliance and CE marking requirements shape export eligibility for Asian equipment manufacturers targeting EU markets. Stuttgart industrial clusters sustain engineering talent pools for servo-pneumatic hybrid filling development.
Tangyuan Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fully automatic system vendors commanding volume while custom fabricators capture premium positioning. The vendor base concentrates among East Asian metalworking clusters and European precision engineering centers. Three archetypes dominate: integrated stainless-steel supply chain operators, servo-driven precision specialists, and modular European designers. Competitive moves center on backward integration into raw material sourcing and geographic expansion through distributor partnerships in underpenetrated Southeast Asian markets.
Among Chinese fabricators, Zhongjia Food Machinery and Jinan Vmetro Machinery occupy positions within the integrated supply chain tier, leveraging proximity to Yangtze River Delta stainless-steel processing. ANKO represents the precision-specialist archetype, with Taiwan-based engineering heritage informing servo-driven system development. European positioning anchors through Rademaker, whose modular architecture exemplifies gluten-free formulation accommodation.
| Leading Market Players |
|---|
| Zhongjia Food Machinery |
| Jinan Vmetro Machinery |
| Taizhou |
| ANKO |
| Fritsch |
| AMF Bakery Systems |
| Rademaker |
| Rondo |
| Kaak |
| Others |
Pricing and Supply Chain Analysis
Backward integration into 316L stainless-steel processing anchors both supply security and pricing power for equipment fabricators in the Yangtze River Delta. Captive sourcing of food-grade contact surface materials buffers margin compression from nickel and molybdenum volatility while MIIT certification requirements filter out non-integrated competitors.
Pricing Analysis
Volume-heavy industrial buyers negotiate contract-based long-term offtake agreements that compress unit economics, while specialty custom machine purchasers absorb premium-mid-economy pricing differentiation driven by certification grade and after-sales bundling. Pricing pressure stems from 316L stainless-steel price volatility under tightening GB standards, forcing standard-tier vendors toward cost compression. Food processing companies in Jiangsu and Zhejiang provinces exhibit highest price sensitivity due to cluster-wide modernization timelines, whereas export-oriented processors prioritize METI-certified systems with lower elasticity.
Supply Chain Analysis
Regional distribution centers in Shanghai and Ningbo coordinate hub-and-spoke patterns that feed forming drum and servo motor components to assembly facilities across the Yangtze River Delta. Manufacturing concentrates in China, Japan, and Germany, with raw material dependencies on 316L stainless-steel, food-grade polymer coatings, and precision servo drives. Single-source vulnerability concentrates in Yangtze River Delta forming drum suppliers, where regional logistics disruptions cascade through production schedules. Distribution runs through OEM-direct and third-party integrator channels serving mid-sized commercial kitchens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over 316L stainless-steel supply chains separates margin-defensible incumbents from component-dependent challengers. Players are pursuing upstream raw material security as the decisive lever.
For Market Incumbents: Deepen backward integration into Yangtze River Delta stainless-steel processing to buffer margin erosion from nickel price volatility. Anchor certification investment in MIIT GB 16798 compliance and METI JIS alignment to filter lower-tier competitors. Defend installed base through captive aftermarket service contracts that resist unbundling trends among 500–2,000 kg/day facilities. For New Entrants and Emerging Players: Mid-sized provincial processors modernizing from manual shaping represent the most penetrable buyer archetype in Vietnam and Thailand, where indigenous equipment manufacturing remains absent. Capture import demand through distributor partnerships offering servo-pneumatic hybrid filling systems priced below fully automatic alternatives. Prioritize clean-in-place engineering talent acquisition to overcome fluid dynamics specialist scarcity blocking deployment timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified food equipment conglomerates seeking East Asian market access. Long-term viability favors targets with integrated stainless-steel supply chains and METI certification pathways already initiated. Monitor CBAM energy efficiency compliance progress among Chinese exporters as the inflection signal for premium positioning capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 316L Stainless-Steel Processing | Captive sourcing from Yangtze River Delta mills buffers margin compression from nickel volatility. |
| METI JIS Certification Investment | Expedited customs clearance at Japanese ports commands preference among export-oriented processors. |
| Servo-Pneumatic Hybrid Filling Development | Mid-market segment access opens previously price-excluded provincial automation buyers. |
| Southeast Asian Distributor Partnership | Vietnam and Thailand import dependency creates first-mover positioning in underpenetrated frozen dessert sectors. |
| Clean-in-Place Engineering Talent Acquisition | Fluid dynamics specialist scarcity blocks competitor deployment timelines and secures service contract bundling. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with food processing plant managers, equipment procurement leads at OEMs, aftermarket service heads, and MIIT compliance officers triangulated operational realities. Secondary validation drew from MIIT GB standard publications, SAMR enforcement bulletins, METI JIS certification registries, and Yangtze River Delta stainless-steel trade flow data. Bottom-up equipment shipment analysis and top-down frozen dessert production capacity modeling reconciled volume estimates.
Data-stream reconciliation across shipment records, import-export documentation, and facility expansion announcements informed the analytical framework over the projection horizon. Segmentation dimensions modeled include automation intensity, thermal processing method, end-user scale tier, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and cluster modernization timelines. Forecast inputs incorporated MIIT stainless-steel specification evolution and CBAM energy efficiency phase-in assumptions.
Revisions become necessary when MIIT accelerates GB 16798 surface roughness mandates, CBAM implementation timelines shift, or Yangtze River Delta logistics disruptions persist beyond seasonal patterns. Forecasts reflect documented assumptions regarding cluster modernization pacing and certification cost pass-through elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Oven Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Smart Food Machine Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Kebab Machine Market