
 Residential Food Waste Disposer Market | 2026-2036
Residential Food Waste Disposer Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Food Waste Disposer Market Analytics
Premium continuous-feed specifications with stainless steel grinding chambers is reorganizing the competitive landscape for residential food waste disposers. InSinkErator leverages its century-long specialization in high-torque motor systems to anchor North American distribution channels. Moen competes through integrated kitchen fixture ecosystems that bundle disposers with faucets and filtration units. Franke differentiates via European engineering standards and compact under-sink footprints suited to dense urban housing.
A residential food waste disposer is an electrically powered mechanical device installed beneath a kitchen sink, typically featuring a 0.5 to 1.0 horsepower induction motor rotating hardened steel impellers at 1,700–2,800 RPM to pulverize organic refuse into particles small enough for municipal wastewater processing. Its primary commercial purpose is to reduce household landfill contributions while eliminating odor and pest vectors associated with stored food scraps. Continuous feed units dominate volume sales due to lower price points and simpler installation protocols, though batch feed designs command margin premiums through enhanced safety interlocks that appeal to families with young children. Grinder technology leads the technology segment with mature supply chains and proven reliability, while biochemical processing variants represent an emerging niche targeting net-zero residential developments with on-site composting integration.
The US EPA classifies food waste disposers as acceptable municipal solid waste diversion tools under its Sustainable Materials Management framework, while the EU F-Gas Regulation indirectly shapes motor coolant specifications for units manufactured in or imported to Europe. Health Canada and PMRA coordinate on antimicrobial coating approvals for grinding chamber surfaces, creating compliance thresholds that filter smaller importers from the Canadian market. Stakeholders must monitor evolving plumbing codes in major metro areas and the pace of smart-home integration standards before committing to next-generation product roadmaps.
Market Dynamics
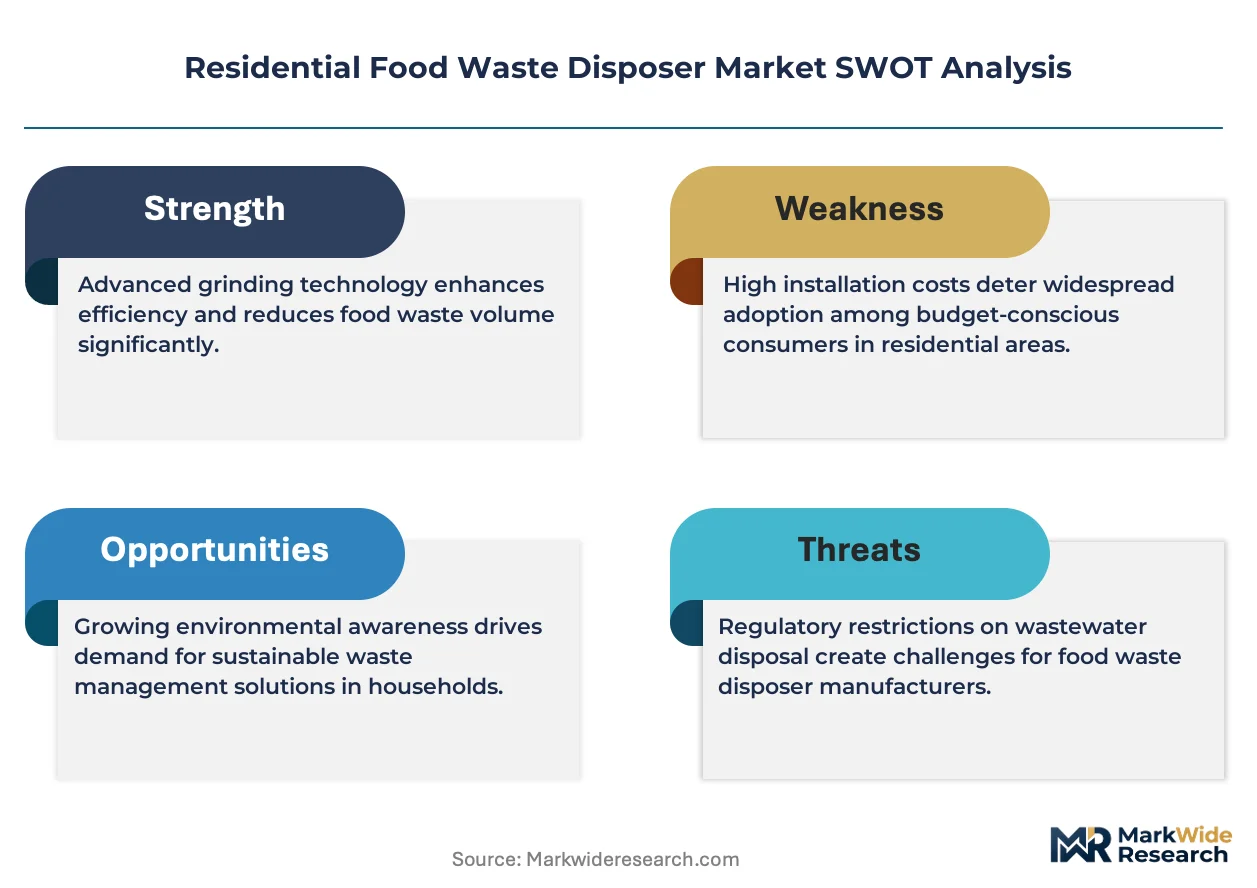
Municipal organic waste diversion mandates are compressing landfill dependency and accelerating disposer adoption in new residential construction across jurisdictions with strict source-separation requirements.
Growth Catalysts
- EPA Sustainable Materials Management framework:The US EPA's classification of food waste disposers as acceptable diversion tools validates homeowner investment and steers municipal procurement toward grinder-based solutions over collection-only programs.
- Single-family residential construction:Builders in Australia, Canada, and the United States are specifying continuous-feed electric grinders as standard equipment to preempt tenant complaints about organic waste storage.
- Batch feed safety interlocks:Enhanced child-protection mechanisms in premium batch feed designs are capturing family-segment demand that previously avoided disposers due to safety concerns.
Market Restraints
- Copper and electrical steel volatility:Induction motor cores depend on commodity-priced laminations and windings, exposing manufacturers to input cost swings that compress margin on economy-tier units.
- Legacy plumbing infrastructure:Pre-1980s municipal sewer systems in older US and European cities lack the hydraulic capacity to transport pulverized organic loads, blocking retrofits in dense historic districts.
- On-site composting systems:Biochemical processing variants and countertop dehydrators are capturing net-zero residential developments that prioritize zero-waste certification over wastewater-based diversion.
Strategic Opportunities
- Smart-home integration protocols:Disposers with load-sensing motors and app-connected maintenance alerts are opening premium price tiers among tech-forward homeowners in Australia and the United States.
- EU F-Gas Regulation alignment:Motor coolant specification harmonization for European imports creates a compliance moat that rewards early-adapting manufacturers with streamlined cross-border distribution.
- Multi-family housing retrofits:Compact under-sink footprints engineered for dense urban kitchens are penetrating apartment renovation markets in Canada and European metropolitan cores.
Industry Challenges
- Antimicrobial coating certification:Health Canada and PMRA approval timelines for grinding chamber surface treatments create 18-24 month lag times that freeze product refresh cycles for smaller importers.
- Skilled plumber scarcity:Installation complexity for batch feed units with dedicated electrical circuits exceeds the capacity of generalist contractors in rapid-growth housing markets, elongating project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Food Waste Disposer Market |
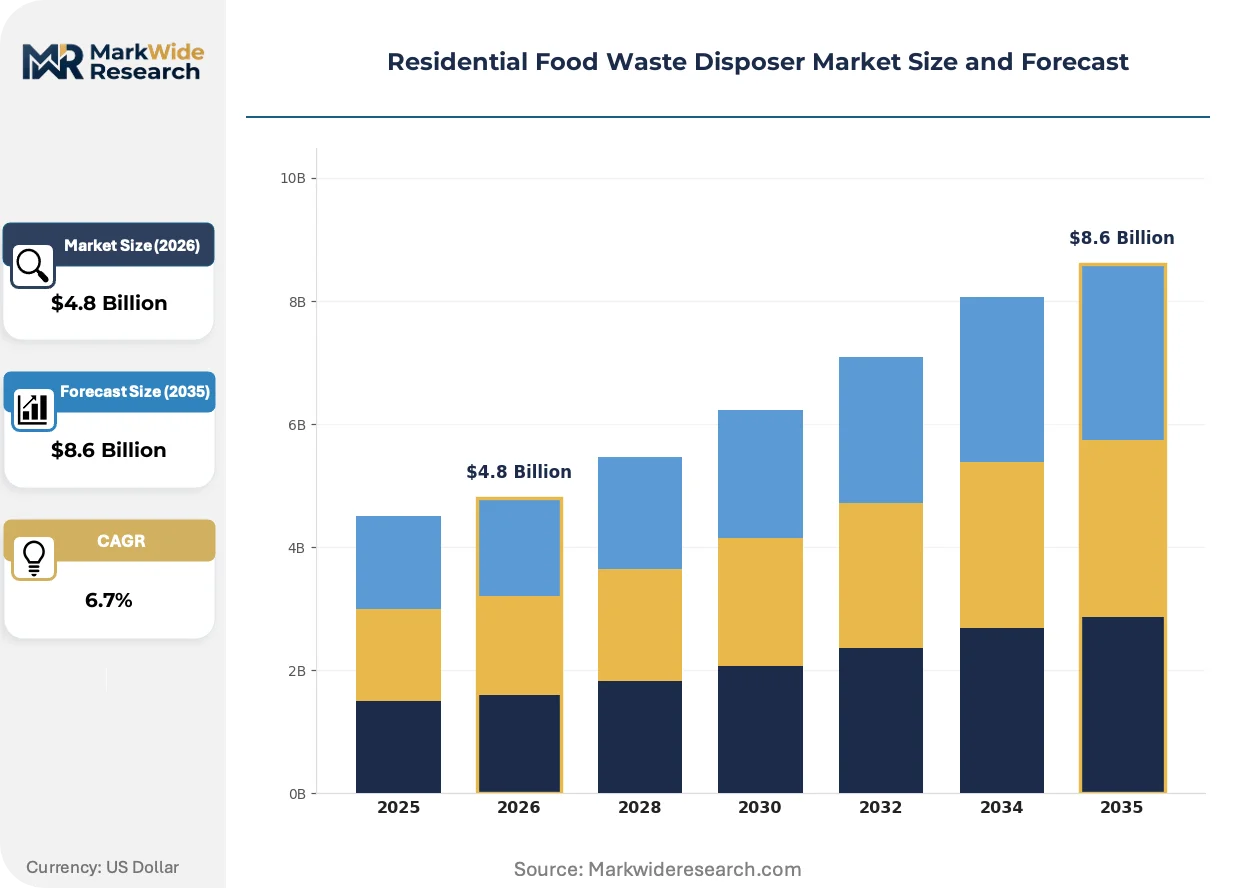
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Feed, Batch Feed, Plug-In, In-Sink End User: Homeowners, Renters, Property Managers, Builders Technology: Grinder, Shredder, Biochemical, Electric Installation: Under-Sink, Standalone, Wall-Mounted, Integrated |
| Companies Covered | GE, KitchenAid, InSinkErator, Anaheim Manufacturing, Frigidaire, Waste King, Whirlpool, Franke, Moen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Food Waste Disposer Market Evolving Landscape
Electrification of grinding mechanisms and tightening wastewater regulations are converging to reshape product specifications, distribution priorities, and buyer expectations across residential construction and renovation channels.
High-torque induction motor systems with stainless steel grinding chambers are displacing legacy shredder designs in new construction specifications. Single-family builders in the United States, Canada, and Australia are specifying these units as standard equipment to meet municipal organic waste diversion thresholds. The shift is compressing demand for lower-RPM shredder technology and concentrating supplier relationships with motor specialists.
The EU F-Gas Regulation is reshaping coolant specifications for disposers manufactured in or imported to Europe. Motor thermal management systems must now use lower-GWP refrigerants or air-cooled designs, adding engineering cost but creating regulatory alignment with broader appliance decarbonization mandates. European-engineered units are adapting faster than import-dependent competitors, shifting competitive advantage toward regional manufacturing footprints.
Buyer preference is rotating toward integrated kitchen fixture ecosystems that bundle disposers with faucets, filtration, and sensor-activated controls. Kitchen renovation contractors in Australia and North American metropolitan markets are specifying these packages to reduce subcontractor coordination overhead. The unbundling of standalone disposer sales through traditional plumbing supply houses is compressing volume through legacy wholesale channels.
Residential Food Waste Disposer Market Segmentation
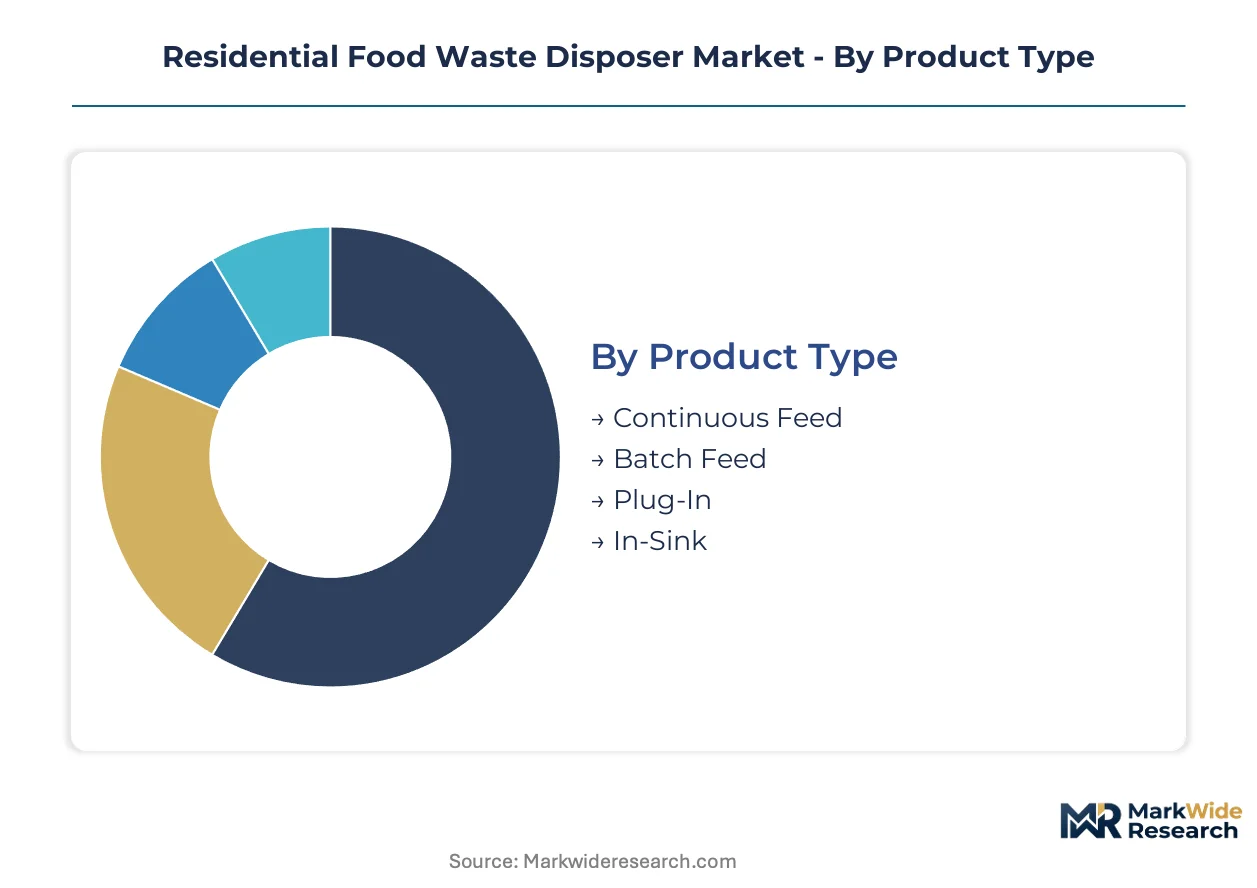
Segmentation in the residential food waste disposer market reveals distinct procurement patterns across buyer types and installation contexts. Product specifications diverge sharply between new construction and retrofit channels, while technology choices track regional infrastructure maturity and regulatory pressure.
Product Type:
Domestic demand concentrates in continuous-feed units across the United States, Canada, and Australia, while batch-feed specifications find stronger export traction in European markets with stricter safety codes.
- Continuous Feed:These units operate via wall switch or air-activation, allowing steady scrap disposal during food preparation. Demand clusters with single-family builders in Australia, Canada, and the United States who specify them as standard equipment to preempt organic waste storage complaints. The lower price point and simpler installation protocol compress project timelines for production homebuilders.
- Batch Feed:A stopper mechanism covers the grinding chamber and must be locked to activate the motor, creating enhanced child-protection interlocks. Family-segment demand previously avoided disposers due to safety concerns now flows toward these premium specifications, particularly in jurisdictions with stringent product liability frameworks.
- Plug-In:Units with corded electrical connections suit rental property retrofits where hardwiring is impractical.
- In-Sink:Compact designs integrate directly with specific sink basins, penetrating European urban kitchen renovations.
Continuous Feed holds the largest share; momentum sits with Batch Feed.
End User:
Cost tier stratification separates premium integrated systems for builders from economy retrofit units targeting price-sensitive renters.
- Homeowners:Owner-occupiers drive specification upgrades toward stainless steel grinding chambers and smart-home connectivity. Renovation spending in Australian and North American metropolitan markets channels toward premium continuous-feed units with load-sensing motors and app-connected maintenance alerts.
- Builders:Production homebuilders standardize grinder-based electric units to satisfy municipal organic waste diversion mandates. Procurement concentrates with motor specialists capable of meeting volume delivery schedules across the United States, Canada, and Australia.
- Renters:Leasehold constraints limit installation flexibility, channeling demand toward plug-in portable units.
- Property Managers:Multi-family housing operators prioritize compact under-sink footprints and antimicrobial surface treatments to reduce maintenance calls.
Builders dominate volume procurement; homeowners generate the steepest expansion trajectory for premium specifications.
Technology:
Volume concentration favors mature grinder technology, while margin expansion concentrates in electric motor systems displacing legacy designs.
- Grinder:High-torque induction motors rotating hardened steel impellers at 1,700–2,800 RPM pulverize organic refuse into particles suitable for municipal wastewater processing. Mature supply chains and proven reliability anchor specification in new residential construction across North America and Australia.
- Electric:Next-generation motor systems with optimized thermal management and reduced copper dependency are gaining specification share. The EU F-Gas Regulation alignment creates compliance moats that reward early-adapting manufacturers with streamlined cross-border distribution into Europe.
- Shredder:Lower-RPM mechanical designs persist in legacy installations but face compression as grinder technology advances.
- Biochemical:On-site processing variants target net-zero residential developments prioritizing zero-waste certification over wastewater-based diversion.
Grinder technology commands installed base dominance; electric systems are climbing the fastest on specification sheets.
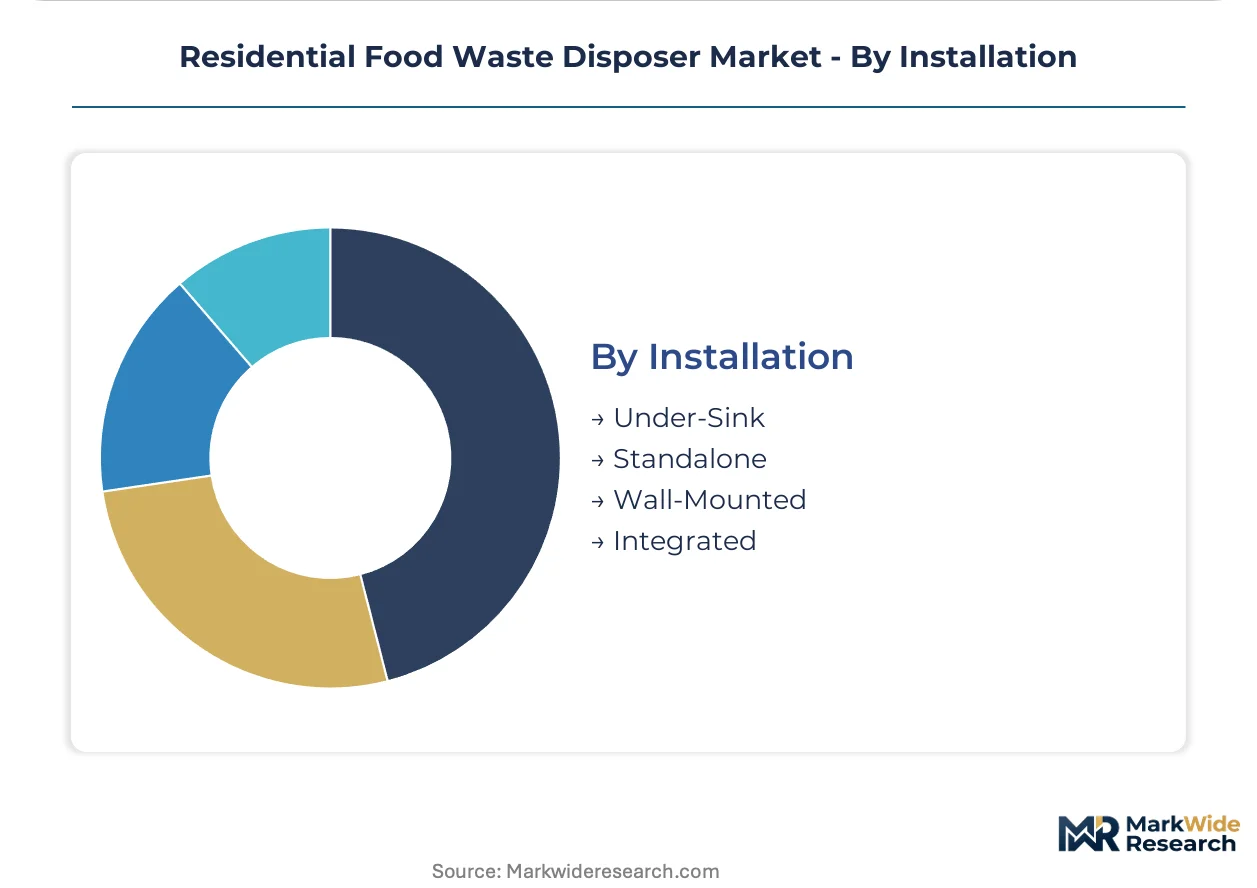
Installation:
Application context separates under-sink retrofits in dense urban housing from integrated new-construction specifications.
- Under-Sink:The standard configuration mounts beneath kitchen sink basins, connecting to drain lines and electrical supply. Compact footprints engineered for dense urban kitchens are penetrating apartment renovation markets in Canada and European metropolitan cores.
- Integrated:Factory-installed units bundled with kitchen fixture ecosystems reduce subcontractor coordination overhead. Kitchen renovation contractors in Australia and North American metropolitan markets specify these packages to compress project timelines.
- Standalone:Freestanding units suit utility room installations where under-sink space is unavailable.
- Wall-Mounted:Elevated placement configurations address accessibility requirements and specialized commercial-residential hybrid spaces.
Under-Sink installations retain volume leadership; integrated specifications gain share fastest among premium renovation projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from North American motor specialists concentrate in Australia and Canada, while European manufacturers face import friction from F-Gas Regulation compliance costs. Trade patterns reflect divergent regulatory maturity across wastewater infrastructure standards.
United States
Single-family construction in Texas and Florida drives specification of continuous-feed electric grinders. The EPA Sustainable Materials Management framework validates disposer-based diversion for municipal procurement. Dallas-Fort Worth builders standardize stainless steel chamber units to preempt organic waste storage complaints in master-planned communities.
Canada
Toronto and Vancouver metro areas retrofit compact under-sink units into dense urban housing stock. Health Canada and PMRA antimicrobial coating approvals create compliance thresholds that filter smaller importers. Calgary's suburban expansion channels demand toward batch-feed designs with enhanced safety interlocks for family-segment buyers.
Australia
Sydney and Melbourne renovation contractors specify integrated kitchen fixture ecosystems bundling disposers with sensor-activated controls. TGA-aligned product standards shape import specifications for electric motor systems. Brisbane's new residential construction accelerates grinder adoption as municipalities tighten source-separation mandates.
Germany
Bavaria and North Rhine-Westphalia concentrate European-engineered manufacturing with compact footprints suited to dense urban housing. The EU F-Gas Regulation reshapes motor coolant specifications, adding engineering cost but creating regulatory alignment with appliance decarbonization mandates. Hamburg's multi-family retrofit market penetrates with under-sink configurations engineered for space constraints.
United Kingdom
London's historic district legacy plumbing infrastructure blocks retrofits in pre-1980s municipal sewer systems. The country's national wastewater regulator maintains divergent standards from continental Europe, fragmenting product specification. Southeast England new-build developments specify grinder technology to satisfy organic waste diversion thresholds in growth corridors.
Residential Food Waste Disposer Market Competitive Landscape
Listed leaders compete with private specialists across motor technology and fixture integration dimensions. The vendor base stratifies into three tiers: diversified appliance conglomerates with captive distribution, plumbing fixture specialists bundling disposers into kitchen ecosystems, and dedicated grinder manufacturers with century-long specialization. Strategic moves concentrate on portfolio diversification toward smart-home connectivity and geographic expansion into F-Gas-aligned European markets.
Within the dedicated manufacturer tier, InSinkErator anchors North American distribution through high-torque motor specialization. Among fixture-integrated competitors, Moen and Franke occupy positions bundling disposers with faucets and filtration units—Moen through North American kitchen renovation channels, Franke via European engineering standards and compact footprints for dense urban housing.
| Leading Market Players |
|---|
| GE |
| KitchenAid |
| InSinkErator |
| Anaheim Manufacturing |
| Frigidaire |
| Waste King |
| Whirlpool |
| Franke |
| Moen |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between motor specialists and North American appliance OEMs lock in copper and electrical steel access while insulating procurement teams from commodity volatility visible in spot laminations markets. These contracts bundle volume commitments with price visibility, compressing margin risk for grinder manufacturers serving Australian and Canadian construction channels.
Pricing Analysis
Production homebuilders anchor a three-tier pricing structure across premium, standard, and economy levels. Stainless steel grinding chambers and smart-home connectivity command tier-one positioning, while plug-in portable units serve price-sensitive rental retrofits. Cost compression in economy-tier electric motors is intensifying because copper and electrical steel volatility feeds directly into bill-of-materials pressure. Property managers exhibit the highest price sensitivity due to multi-unit procurement scale, whereas renovation contractors in Sydney and Melbourne show tolerance for premium integrated fixture ecosystems.
Supply Chain Analysis
Inventory buffers for induction motor cores stretch 12-16 weeks as manufacturers balance just-in-time assembly against electrical steel tariff exposure. Supply concentrates in China for stamped laminations, Mexico for final motor assembly, and the United States for high-torque system integration. Raw material dependencies center on copper windings, cold-rolled electrical steel, and rare-earth magnet alternatives. Single-source vulnerability in laminated steel imports from specific Chinese mills creates chokepoint risk. Distribution runs through plumbing supply houses and direct-builder procurement channels, with integrated kitchen fixture ecosystems bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where smart-home interoperability standards are redefining competitive moats. Winners will anchor kitchen fixture ecosystems rather than standalone disposer sales.
For Market Incumbents: Secure exclusive distribution lock-ups with top-ten US production homebuilders before biochemical processing variants capture net-zero certification demand. Deepen backward integration into motor core manufacturing to offset copper volatility compressing economy-tier margins. Antimicrobial coating certification timelines from Health Canada and PMRA represent a regulatory moat worth reinforcing through dedicated compliance teams. For New Entrants and Emerging Players: CE marking fast-track for EU F-Gas-aligned motor coolant specifications opens streamlined cross-border distribution into Bavaria and North Rhine-Westphalia manufacturing clusters. Compact under-sink footprints for Toronto and Vancouver apartment retrofits offer the most penetrable white-space. Target kitchen renovation contractors in Australian metropolitan markets with app-connected maintenance alert bundles as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward motor specialists with captive high-torque induction technology and established North American builder relationships. Long-term viability over the coming decade hinges on smart-home protocol integration and European regulatory alignment. Watch for inflection when municipal organic waste diversion mandates cross 75% coverage in major US metro areas, signaling specification tipping point.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Home Protocol Integration | Load-sensing motors with app connectivity capture premium price tiers in Australian and US renovation channels. |
| EU F-Gas Regulatory Alignment | Lower-GWP coolant specifications create compliance moats for streamlined European import distribution. |
| Antimicrobial Surface Certification | Health Canada and PMRA approvals filter smaller importers from Canadian multi-family housing procurement. |
| Backward Integration into Motor Cores | In-house lamination stamping insulates margins from copper and electrical steel commodity volatility. |
| Integrated Fixture Ecosystem Bundling | Kitchen renovation contractors in North America specify disposer-faucet-filtration packages to compress project timelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA diversion framework documentation, municipal plumbing code databases, and customs trade records for electrical steel and copper winding imports. Interviews with production homebuilder procurement directors, kitchen renovation contractors, motor manufacturing plant managers, and plumbing supply house category managers informed demand-side validation. Secondary sources include SEC 10-K filings from listed appliance conglomerates, TGA product registration databases, and EU F-Gas Regulation implementation guidance. Bottom-up unit shipment modeling triangulates against top-down construction permit flow analysis.
Segmentation dimensions modeled span product type, end user archetype, motor technology, and installation configuration across the projection horizon. Grinder versus electric motor system adoption curves, batch feed safety interlock penetration in family segments, and integrated versus standalone installation mix inform volume build-ups. CAGRs derive from regression against municipal organic waste diversion mandate adoption timelines and single-family construction permit trajectories in Texas, Florida, and Queensland.
Decision-makers should treat outputs as directional under sustained municipal regulatory tightening and copper price stability assumptions; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
Global Food Deaerators Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Pasteuriser Market