
 Soy and Milk Protein Ingredients Market | 2026-2036
Soy and Milk Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Soy and Milk Protein Ingredients Market Intelligence
Sports nutrition is expanding as the fastest-growing end-use vertical for soy and milk protein ingredients, displacing traditional bakery applications in volume growth priority. Archer Daniels Midland Company leverages its North American oilseed processing network to sustain cost-competitive isolate supply. Kerry Group Plc anchors its position through flavor-protein co-development capabilities that shorten formulation cycles for beverage clients. Cargill Incorporated dominates South American soy concentrate output through integrated crushing and extraction assets.
Soy and milk protein ingredients comprise fractionated and refined protein extracts derived from defatted soybean meal and bovine milk, typically achieving protein concentrations ranging from 34% in soy flour to over 90% in soy protein isolate through alkaline extraction and isoelectric precipitation. These ingredients function primarily as emulsifiers, gelling agents, and nutritional fortifiers across formulated foods and supplements. Soy protein isolate leads in margin contribution due to premium pricing in sports nutrition and meat alternative applications, while milk protein concentrate retains structural importance in infant formula and clinical nutrition where regulatory barriers limit substitution. Powder form captures the dominant share of shipment volume owing to superior shelf stability and lower logistics cost per protein unit.
The FDA maintains identity standards for milk protein concentrates under 21 CFR, while EFSA evaluates novel protein health claims through its NDA panel, creating divergent compliance pathways for multinational suppliers. China's SAMR enforces GB standards for plant protein labeling that restrict amino acid fortification claims, shaping product positioning in Asia's largest import market. Stakeholders must monitor evolving protein quality scoring methodologies as FAO digestibility metrics replace traditional PER ratios, forcing reformulation investments across legacy portfolios.
Market Dynamics
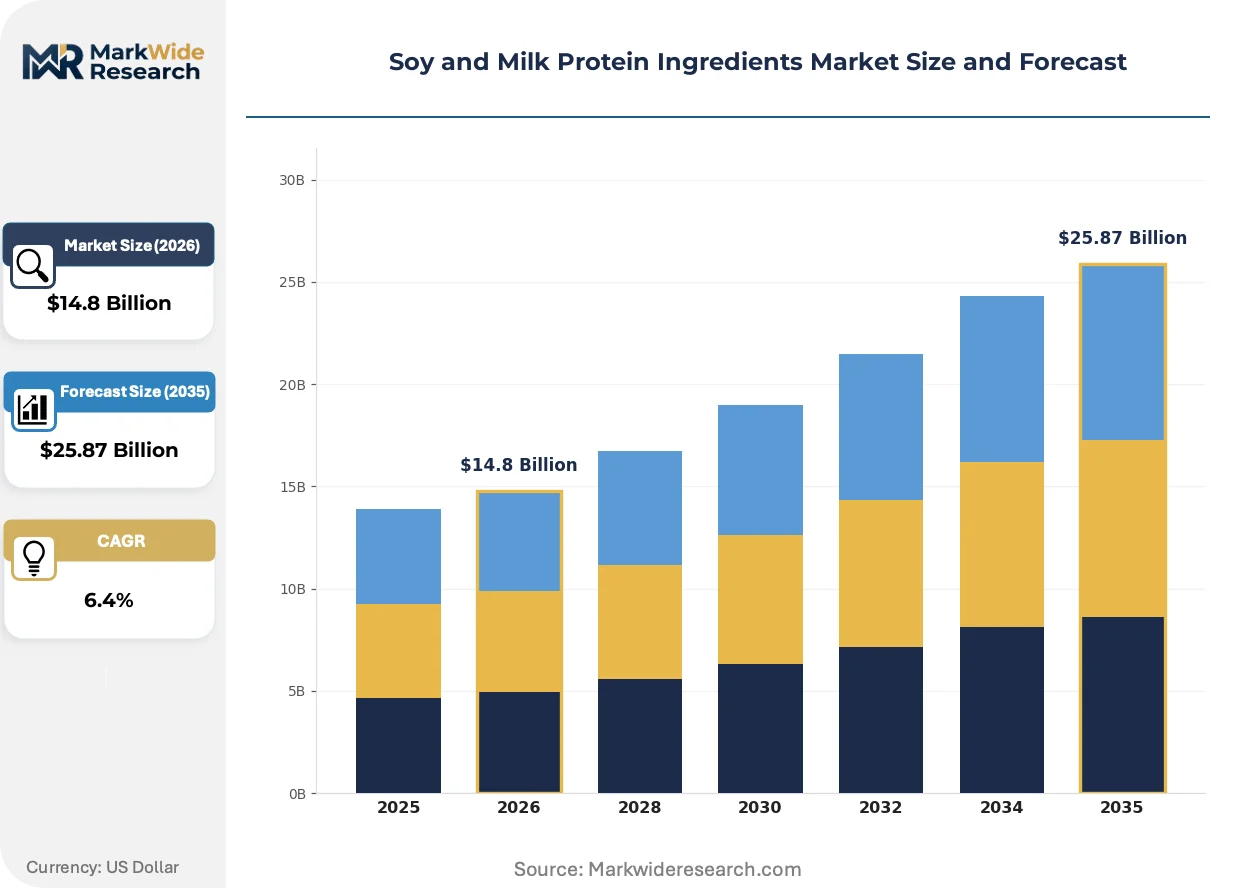
The soy and milk protein ingredients market is being reshaped by the tightening of protein purity thresholds under FDA and EFSA labeling frameworks, which forces suppliers to invest in fractionation upgrades while sports nutrition brands accelerate isolate uptake.
Growth Catalysts
- Sports Nutrition Vertical Expansion:Formulators targeting muscle protein synthesis are specifying soy protein isolates above 90% concentration, creating pull-through demand for high-purity extraction capacity.
- EFSA Novel Food Pathways:The NDA panel's evolving health claim evaluations for plant proteins are enabling positioning strategies that command premium pricing in European functional foods.
- Germany's Functional Food Corridor:Concentrated R&D activity between Cologne and Düsseldorf is generating co-development partnerships that compress beverage formulation cycles.
Market Restraints
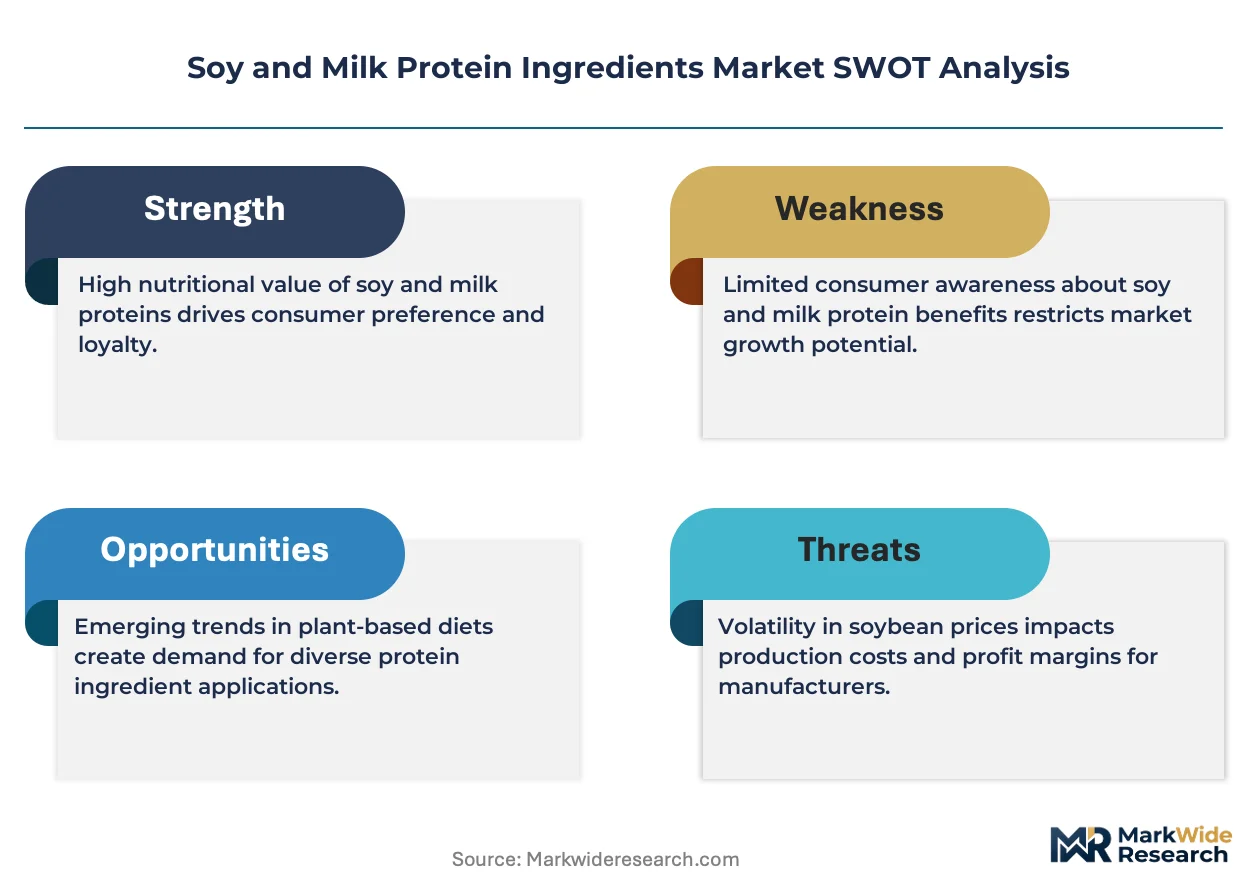
- Input Cost Volatility in Soybeans:Defatted soybean meal prices fluctuate with Argentine and Brazilian harvest cycles, compressing margin predictability for concentrate processors.
- Supply Concentration Risk:South American soy crushing assets are dominated by integrated agribusiness operators, limiting second-tier access to competitively priced raw isolate.
- Regulatory Friction from SAMR:China's GB standards restrict amino acid fortification claims on plant protein labels, constraining product positioning in the import-heavy Asian market.
Strategic Opportunities
- Underpenetrated Clinical Nutrition:Milk protein concentrate retains structural importance in medical foods where regulatory barriers limit soy substitution, creating defendable niche positioning.
- Technology Convergence:Precision fermentation capabilities are converging with traditional extraction infrastructure, enabling hybrid production models that reduce capital intensity for novel proteins.
- F-Gas Regulation Tailwinds:The EU's phasedown of fluorinated greenhouse gases is accelerating investment in mechanical vapor recompression for spray-drying operations, favoring early equipment adopters.
Industry Challenges
- Protein Quality Scoring Transition:The FAO's digestibility-corrected amino acid score is replacing PER ratios, forcing legacy portfolio reformulation investments and analytical capability upgrades.
- Fractionation Capex Intensity:Alkaline extraction and isoelectric precipitation equipment for 90%+ isolate production requires substantial capital deployment with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy and Milk Protein Ingredients Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein Isolate, Soy Protein Concentrate, Milk Protein Concentrate, Casein Application: Dairy Alternatives, Nutritional Supplements, Bakery Products, Meat Alternatives End User: Food Manufacturers, Beverage Companies, Health Food Brands, Dietary Supplement Producers Form: Powder, Liquid, Granules, Capsules |
| Companies Covered | Bunge Global SA, Kerry Group Plc, Archer Daniels Midland Company, International Flavors & Fragrances Inc., Arla Foods amba, Cargill Incorporated, Fuji Oil Holdings Inc., The Scoular Company, Wilmar International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy and Milk Protein Ingredients Market Strategic Shifts & Innovations
Protein ingredient markets are experiencing active transformation through three concurrent shifts: extraction technology advancement, regulatory scoring methodology overhaul, and procurement pattern evolution toward direct supplier relationships.
Membrane filtration systems with ceramic microfiltration are overtaking traditional acid-wash precipitation in isolate production. Sports nutrition manufacturers in North America are specifying these higher-purity inputs for ready-to-mix powders. This technology compression is enabling smaller batch runs with faster product rotation cycles.
REACH compliance requirements for processing aids used in protein extraction are tightening purity documentation standards for European imports. Manufacturers must now submit extended safety data sheets for surfactants and pH adjusters. Infant formula suppliers are responding by qualifying alternative processing chemistries ahead of 2025 dossier deadlines.
Direct procurement relationships between protein ingredient suppliers and finished goods manufacturers are shortening traditional distribution channels. Beverage brands are establishing captive supply agreements that bypass regional distributors. This channel compression is most visible in Germany's functional food corridor where co-location of R&D and production accelerates specification alignment.
Soy and Milk Protein Ingredients Market Segmentation
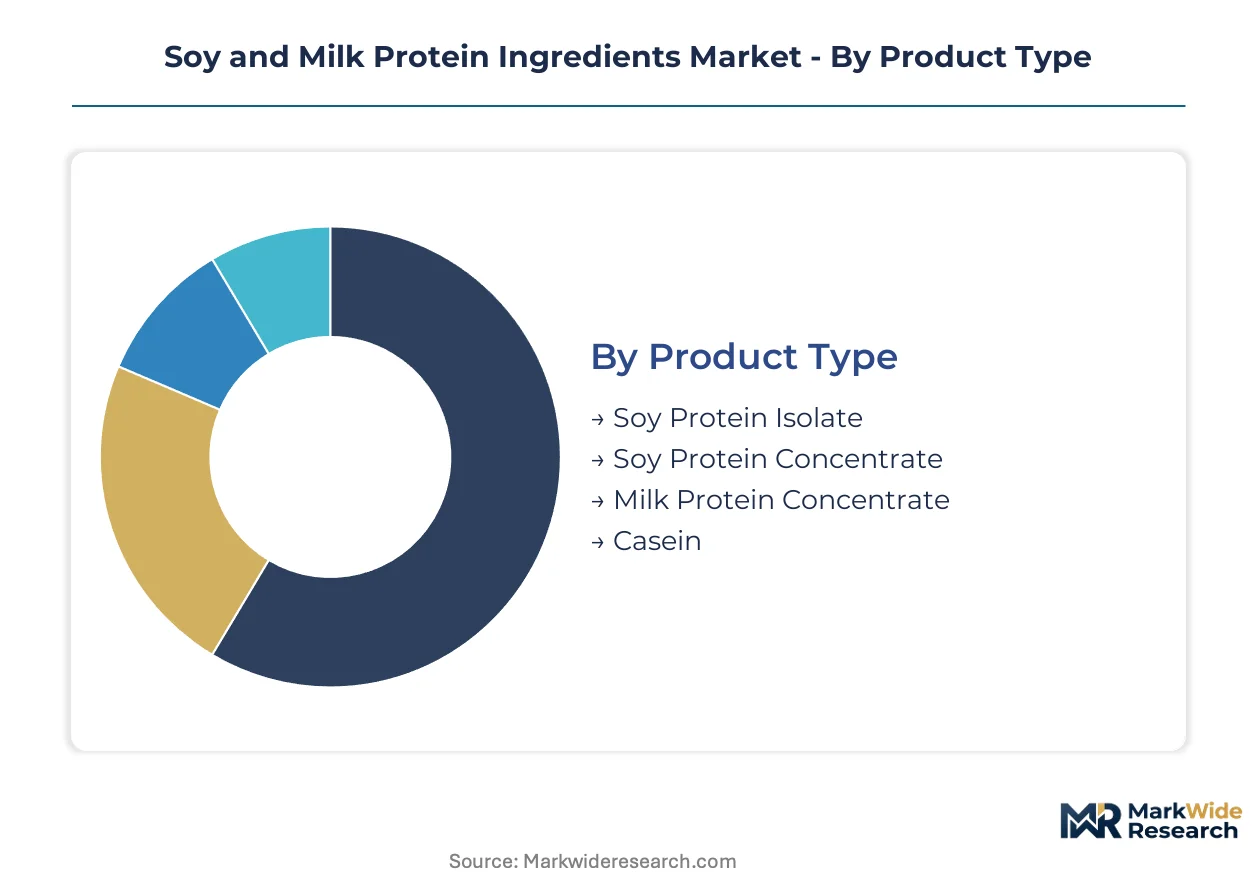
Protein ingredient segmentation determines compliance pathways and margin structures across the value chain. FDA identity standards for milk-derived fractions diverge sharply from EFSA novel food evaluations for plant proteins, creating divergent investment requirements by segment.
Product Type:
FDA 21 CFR identity standards govern milk protein concentrates, while EFSA NDA panel evaluations apply to soy isolates, creating asymmetric certification burdens across this category.
- Soy Protein Isolate:Achieves protein concentrations exceeding 90% through alkaline extraction and isoelectric precipitation. Sports nutrition brands in Germany's functional food corridor are specifying these high-purity inputs for muscle protein synthesis applications, though fractionation capex intensity limits supplier entry.
- Milk Protein Concentrate:Retains structural importance in infant formula where regulatory barriers limit soy substitution. Clinical nutrition manufacturers prioritize this segment for medical food applications, with FDA identity standards creating defendable niche positioning.
- Soy Protein Concentrate:Derived from defatted soybean meal at 65-70% protein content. Cargill dominates South American output through integrated crushing assets.
- Casein:Micellar structure enables sustained amino acid release in sports recovery formulations. Kerry Group leverages flavor-protein co-development capabilities for beverage applications.
Soy protein isolate sits at the top of the volume ranking, with milk protein concentrate climbing the fastest in clinical nutrition positioning.
Application:
Application segments stratify by formulation complexity, with beverage applications demanding the tightest specification alignment between supplier R&D and brand product development.
- Dairy Alternatives:Plant-based milk and yogurt applications require emulsion stability and neutral flavor profiles. Germany's Cologne-Düsseldorf corridor concentrates co-development activity for oat-soy protein blends.
- Nutritional Supplements:Ready-to-mix powders and ready-to-drink formats drive isolate uptake. Sports nutrition vertical expansion is accelerating specifications above 90% concentration.
- Bakery Products:Dough conditioning and shelf-life extension remain primary functional roles. Traditional volume leadership is shifting to sports nutrition in growth priority.
- Meat Alternatives:Texturization and water-binding properties command premium isolate grades. EFSA novel food pathways enable positioning strategies with differentiated health claims.
Nutritional supplements lead current volume, with meat alternatives gaining share fastest on alternative protein tailwinds.
End User:
End user segments diverge by procurement sophistication, with direct supplier relationships compressing traditional distribution channels for the largest beverage and supplement brands.
- Food Manufacturers:Bakery and meat alternative processors prioritize cost-competitive concentrate supply. Argentine and Brazilian harvest cycles introduce input cost volatility.
- Beverage Companies:Flavor-protein compatibility drives co-development partnerships. Germany's functional food corridor exemplifies compressed formulation cycles through co-location.
- Health Food Brands:Clean label positioning demands identity-preserved sourcing documentation. REACH compliance requirements tighten purity documentation for European imports.
- Dietary Supplement Producers:Sports nutrition brands specify isolate grades for amino acid scoring optimization. FAO digestibility metrics are replacing PER ratios in formulation specifications.
Food manufacturers retain the largest procurement volume, with dietary supplement producers expanding most quickly on sports nutrition demand.
Form:
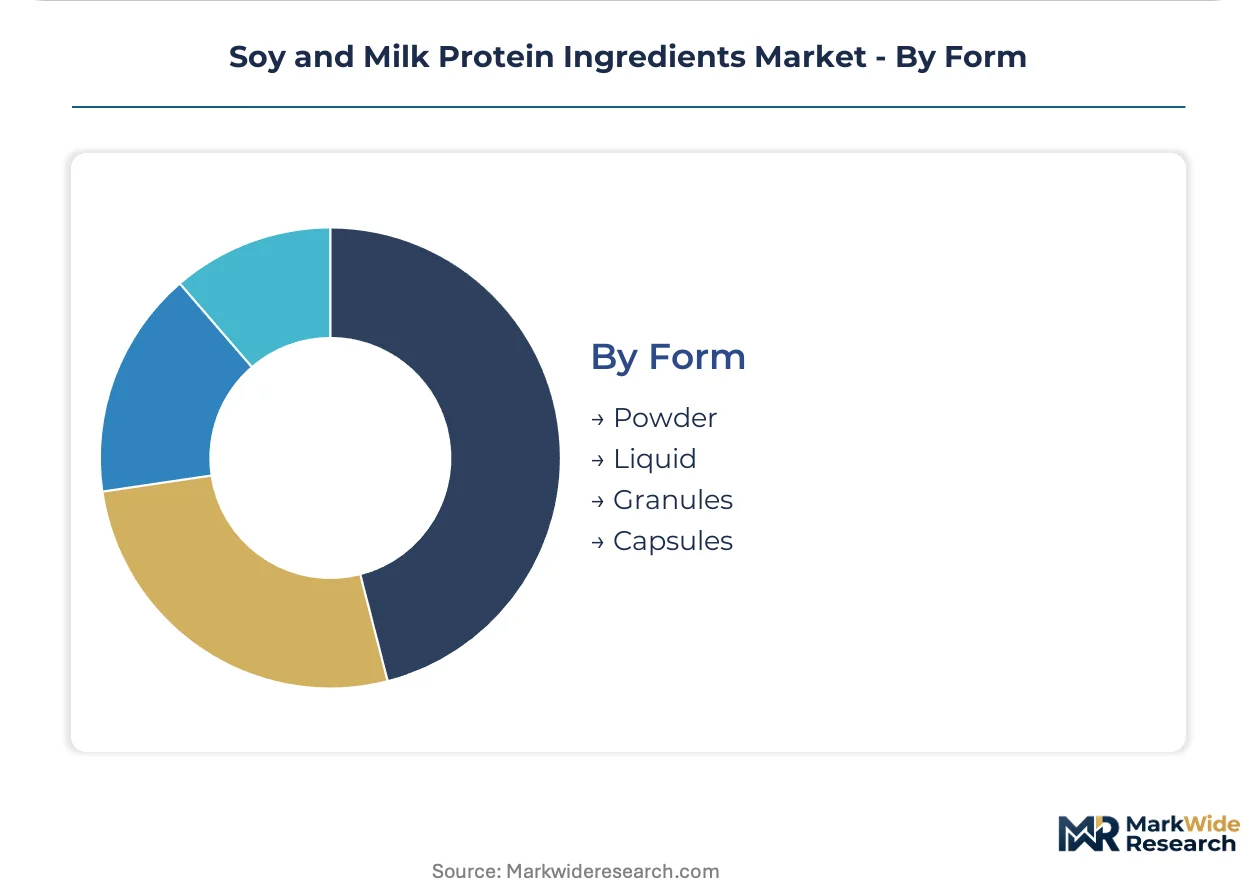
Form selection determines logistics economics and shelf stability, with powder formats dominating intercontinental shipment due to lower cost per protein unit.
- Powder:Spray-dried isolates and concentrates achieve superior shelf stability. EU F-Gas Regulation is accelerating mechanical vapor recompression investment for drying operations.
- Liquid:Pre-hydrated concentrates reduce manufacturing step count for beverage processors. Cold chain requirements limit geographic reach.
- Granules:Intermediate dissolvability for instant beverage applications. Smaller batch production enables faster product rotation cycles.
- Capsules:Unit-dose delivery for supplement convenience positioning. Encapsulation equipment adds downstream processing cost.
Powder commands the dominant shipment share, with liquid formats climbing fastest in captive supply agreements for beverage co-manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as fractionation capacity migrates toward jurisdictions with favorable energy costs and streamlined novel-food approval pathways. Suppliers are optimizing asset placement across compliance-cost gradients while demand concentrates in clusters with co-located R&D and manufacturing.
United States
Sports nutrition brands in the Mountain West and Pacific Northwest are specifying soy protein isolates above 90% concentration for ready-to-mix powders. FDA maintains identity standards for milk protein concentrates under 21 CFR, creating certification clarity for clinical nutrition applications. Chicago anchors North American oilseed processing with integrated crushing and extraction infrastructure serving beverage and supplement manufacturers.
Germany
Functional food formulators between Cologne and Düsseldorf are compressing beverage development cycles through co-location partnerships with protein suppliers. EFSA's NDA panel evaluates novel plant protein health claims, enabling premium positioning strategies in European markets. The North Rhine-Westphalia corridor concentrates Europe's highest density of flavor-protein co-development facilities.
China
Domestic brands are expanding isolate uptake for sports nutrition despite import dependency for high-purity grades. SAMR enforces GB standards restricting amino acid fortification claims on plant protein labels, constraining positioning options. Yangtze River Delta clusters around Shanghai concentrate beverage manufacturing and co-manufacturing capacity for Asia-Pacific distribution.
Brazil
Integrated agribusiness operators dominate defatted soybean meal supply for concentrate production, though isolate fractionation remains import-reliant. Harvest cycle volatility in Mato Grosso and Paraná introduces margin unpredictability for processors. São Paulo state anchors South American crushing capacity with logistics infrastructure serving Atlantic export routes.
India
Dairy cooperative networks supply milk protein concentrate for domestic infant formula and nutritional supplement applications. FSSAI labeling requirements for protein quality claims are tightening analytical documentation standards. Gujarat's Anand district concentrates dairy processing infrastructure with backward integration into milk collection networks.
Soy and Milk Protein Ingredients Market Key Industry Players
Capacity expansion dominates the current landscape as suppliers deploy fractionation assets to capture sports nutrition demand growth. The market structures around three tiers: integrated agribusiness operators with crushing-to-isolate control, specialized ingredient houses with flavor-protein co-development capabilities, and regional dairy processors with milk protein concentrate specialization. Strategic archetypes include North American oilseed processors leveraging origination networks, European flavor houses anchoring beverage partnerships, and Asian plantation-to-protein integrators. Competitive moves concentrate on captive supply agreements with beverage brands and co-development partnerships compressing formulation cycles.
Among integrated agribusiness operators, Bunge Global SA and Archer Daniels Midland Company exemplify the oilseed-processing archetype with North American network density. Kerry Group Plc occupies a position within the European flavor-protein co-development tier, anchoring relationships in Germany's functional food corridor. Cargill Incorporated represents South American integrated operations with crushing and extraction asset control. These three patterns illustrate how geographic asset placement and downstream partnership depth determine competitive positioning.
| Leading Market Players |
|---|
| Bunge Global SA |
| Kerry Group Plc |
| Archer Daniels Midland Company |
| International Flavors & Fragrances Inc. |
| Arla Foods amba |
| Cargill Incorporated |
| Fuji Oil Holdings Inc. |
| The Scoular Company |
| Wilmar International Ltd |
| Others |
Cost & Logistics Intelligence
Sports nutrition brands commanding isolate specifications above 90% protein concentration anchor pricing power toward premium-tier extraction capacity, compressing margin capture for second-tier concentrate suppliers.
Pricing Analysis
Distributor margins for soy protein isolates widen in direct procurement relationships where beverage brands bypass regional intermediaries. Three-tier pricing structure across premium isolate grades, standard concentrates, and economy soy flour segments reflects protein concentration purity and certification documentation depth. Cost compression in standard concentrates intensifies because Argentine and Brazilian harvest volatility feeds raw material unpredictability. Food manufacturers remain most price-sensitive due to bulk procurement scale, while clinical nutrition formulators exhibit lowest sensitivity given regulatory substitution barriers.
Supply Chain Analysis
Defatted soybean meal supply rests on crushing assets concentrated in Brazil, Argentina, and the United States, with isolate fractionation capacity clustering in Germany and North American processing corridors. Critical inputs span specialty enzyme preparations for extraction, ceramic membrane filtration systems, and mechanical vapor recompression equipment for spray-drying operations. Single-source vulnerability runs through South American integrated agribusiness operators controlling raw isolate access. Distribution runs through direct captive supply agreements that compress traditional channel structures for largest beverage and supplement manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EFSA novel food approval pathways in Europe command premium positioning against SAMR-restricted claim environments in China.
For Market Incumbents: Cement isolate fractionation capacity in Germany's functional food corridor to capture co-development partnership density. Deepen backward integration into South American crushing assets to secure raw material cost predictability against harvest cycle volatility. Prioritize FAO digestibility scoring analytical capabilities as PER ratio obsolescence threatens legacy portfolio repositioning. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for mechanical vapor recompression equipment specialists to penetrate spray-drying upgrade cycles. Target clinical nutrition white space where milk protein concentrate substitution barriers limit soy competition. Pursue precision fermentation hybrid models to reduce alkaline extraction capital intensity for isolate production. For Investors and Strategic Acquirers: Integrated beverage conglomerates are the most active acquirer in this space, seeking captive supply security for sports nutrition vertical expansion. Acquisition focus centers on mid-cap isolate specialists with EFSA health claim dossier capabilities. Watch FAO protein quality scoring adoption velocity as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Fractionation Capacity Expansion | Captures sports nutrition isolate demand concentrated in Germany's Cologne-Düsseldorf corridor. |
| Backward Integration into Crushing | Secures defatted soybean meal cost predictability against Argentine harvest volatility. |
| Co-Development Partnership Formation | Compresses beverage formulation cycles through R&D co-location with flavor houses. |
| Precision Fermentation Hybridization | Reduces capital intensity for novel protein production alongside traditional extraction. |
| Mechanical Vapor Recompression Investment | Aligns spray-drying operations with EU F-Gas Regulation phasedown requirements. |
Research Approach
Multiple input streams — protein ingredient procurement managers, sports nutrition formulators, clinical nutrition regulatory affairs leads, and fractionation equipment engineers — were reconciled against trade flow databases, EFSA NDA panel dossier filings, and customs documentation. Primary fieldwork with beverage brand R&D directors and dairy cooperative supply heads supplemented secondary validation through FAO protein quality guidelines, FDA 21 CFR identity standards, and SAMR GB labeling regulations. Bottom-up volume modeling across isolate, concentrate, and casein segments triangulated with top-down expenditure analysis from finished goods manufacturers.
Historical volume trajectories were cross-referenced against expert panel assessments of sports nutrition demand acceleration and clinical nutrition substitution barriers across the projection horizon. Segmentation dimensions modeled encompass product type tiers, application complexity levels, end-user procurement sophistication, and regional regulatory cluster variations. CAGRs were derived through elasticity-adjusted extrapolation of isolate uptake rates in ready-to-mix powders and medical food positioning premiums for milk protein concentrates.
Revisions become necessary when protein quality scoring methodology transitions, novel food approval pathway divergences, or input cost volatility spikes materialize beyond modeled ranges. Forecasts reflect documented assumptions regarding fractionation capacity deployment timelines and co-development partnership formation velocity. A small set of named triggers — EFSA health claim expansion velocity, SAMR labeling enforcement intensity, and South American harvest disruption frequency — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Meat Tenderizer Powder Market
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
Dill Seed Oil Market
Ingredients
North America Feed Yeast Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
North America Vegetable Oils Market
Ingredients
Global Starch Derivatives Market
Ingredients
Kilned Malt Market
Ingredients
Commercial Amino Acids Market
Ingredients
US Choline Bitartrate Market
Ingredients
Yeast Peptide Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Edible Halal Gelatin Market
Ingredients
Corn Oil Market
Ingredients
Anhydrous Caffeine Market