
 Breakfast Drink Market | 2026-2036
Breakfast Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Breakfast Drink Market Intelligence
Premium functional-grade formulations is redrawing competitive boundaries in breakfast beverages. Nestlé leverages its dairy-protein research infrastructure to anchor shelf-stable nutrition lines across European retail channels. PepsiCo competes through sports-nutrition positioning, while Danone specializes in fermented plant-base drink systems for health-food store distribution.
Breakfast drinks comprise liquid or ready-to-mix beverages formulated with proteins, vitamins, minerals, and functional additives, typically manufactured via UHT processing, high-pressure homogenization, or cold-aseptic filling to deliver convenient morning nutrition. Smoothies and protein shakes lead volume as margin pools concentrate in functional-ingredient tiers with clinical validation. Plant-based ingredient types expand fastest where oat and pea-protein extraction technologies improve mouthfeel, though dairy-based lines sustain dominant share in family-oriented consumer segments.
FDA nutrition-labeling rules and EFSA health-claim frameworks constrain formulation marketing, while China's SAMR and GB standards govern import access and additive permissions for foreign brands. Stakeholders must monitor evolving protein-source regulations and processing-equipment standards that determine which suppliers qualify for retail placement in priority markets.
Market Dynamics
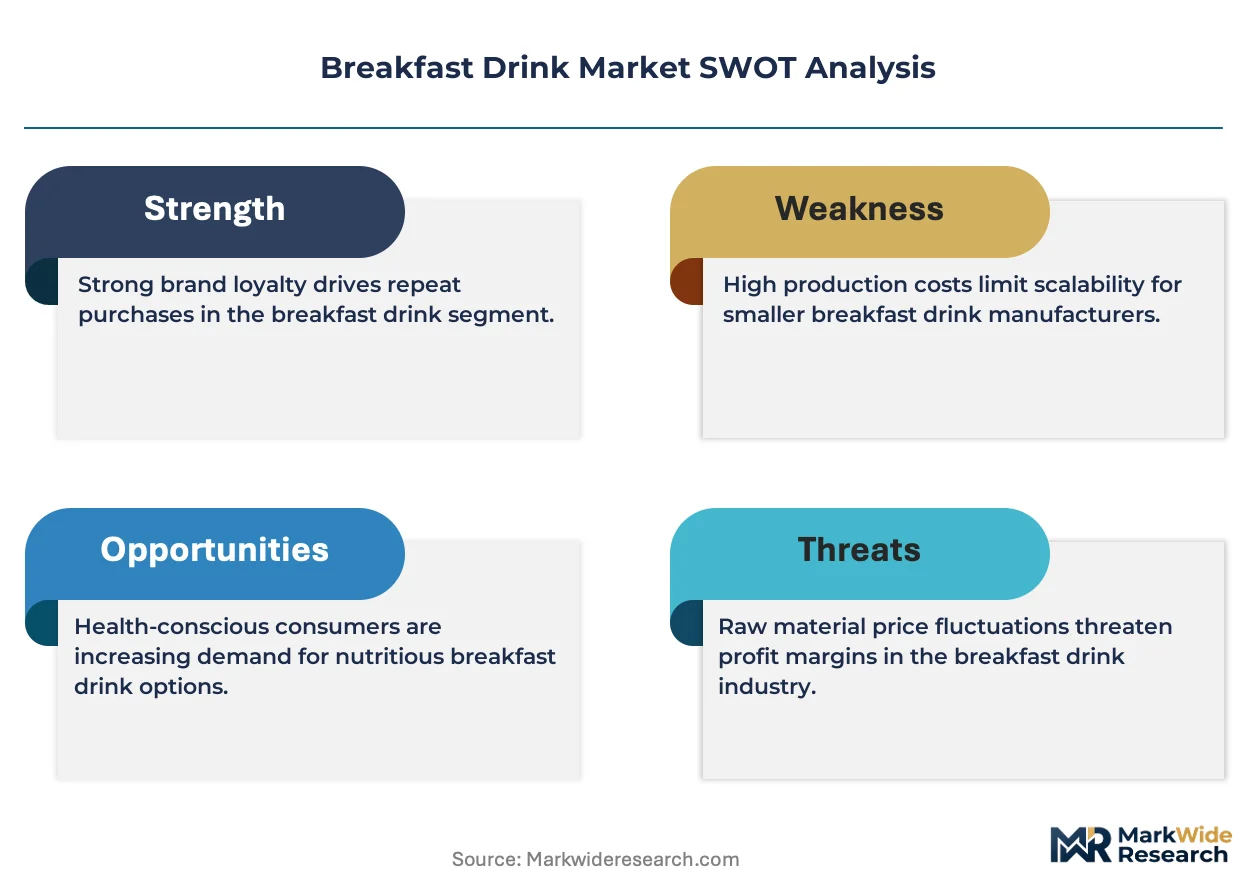
Clean-label regulations in the European Union are forcing breakfast drink manufacturers to reformulate around synthetic additive bans while maintaining shelf stability, compressing R&D cycles and redirecting capital toward natural preservation systems.
Growth Catalysts
- FSSAI fortification mandates:India's food safety regulator now requires micronutrient enrichment in packaged beverages, opening formulation contracts for premix suppliers and contract manufacturers serving South Asian export channels.
- Oat-protein extraction advances:Enzymatic hydrolysis improvements in Nordic processing facilities are yielding neutral-tasting plant proteins that replicate dairy mouthfeel without allergen labeling triggers.
- SAMR import pathway streamlining:China's State Administration for Market Regulation has consolidated registration procedures for functional beverages, reducing time-to-shelf for foreign brands entering tier-one city retail.
Market Restraints
- Aluminum can sheet concentration:Three smelters control two-thirds of food-grade supply in North America, exposing brands to input cost volatility when energy markets spike.
- UHT equipment lead times:Aseptic filling line delivery stretches eighteen months due to precision engineering bottlenecks at German and Italian machinery builders.
- EFSA health-claim substantiation:European Food Safety Authority's strict clinical evidence requirements block marketing of gut-health positioning that dominates US and Asian markets.
Strategic Opportunities
- German pharmacy channel expansion:Apotheken distribution networks remain underutilized for medical-nutrition breakfast drinks despite reimbursement eligibility for diabetic and geriatric formulations.
- Cold-aseptic plus HPP hybrid processing:Convergence of ambient-stable and fresh-pressed technologies enables clean-label positioning with ninety-day shelf life, bridging refrigerated and shelf-stable segments.
- PLI scheme alignment:India's production-linked incentive program for food processing offers capital subsidies for domestic manufacturing of fortified beverages, reducing import dependency.
Industry Challenges
- Clean-label preservative gaps:Natural antimicrobial systems lack the broad pH tolerance of potassium sorbate, forcing brands to sacrifice shelf life or accept ingredient lists that trigger consumer rejection.
- Cross-border formulation drift:Divergent additive permissions between FDA, EFSA, and SAMR require maintaining three distinct SKUs for ostensibly identical products, fragmenting production scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breakfast Drink Market |
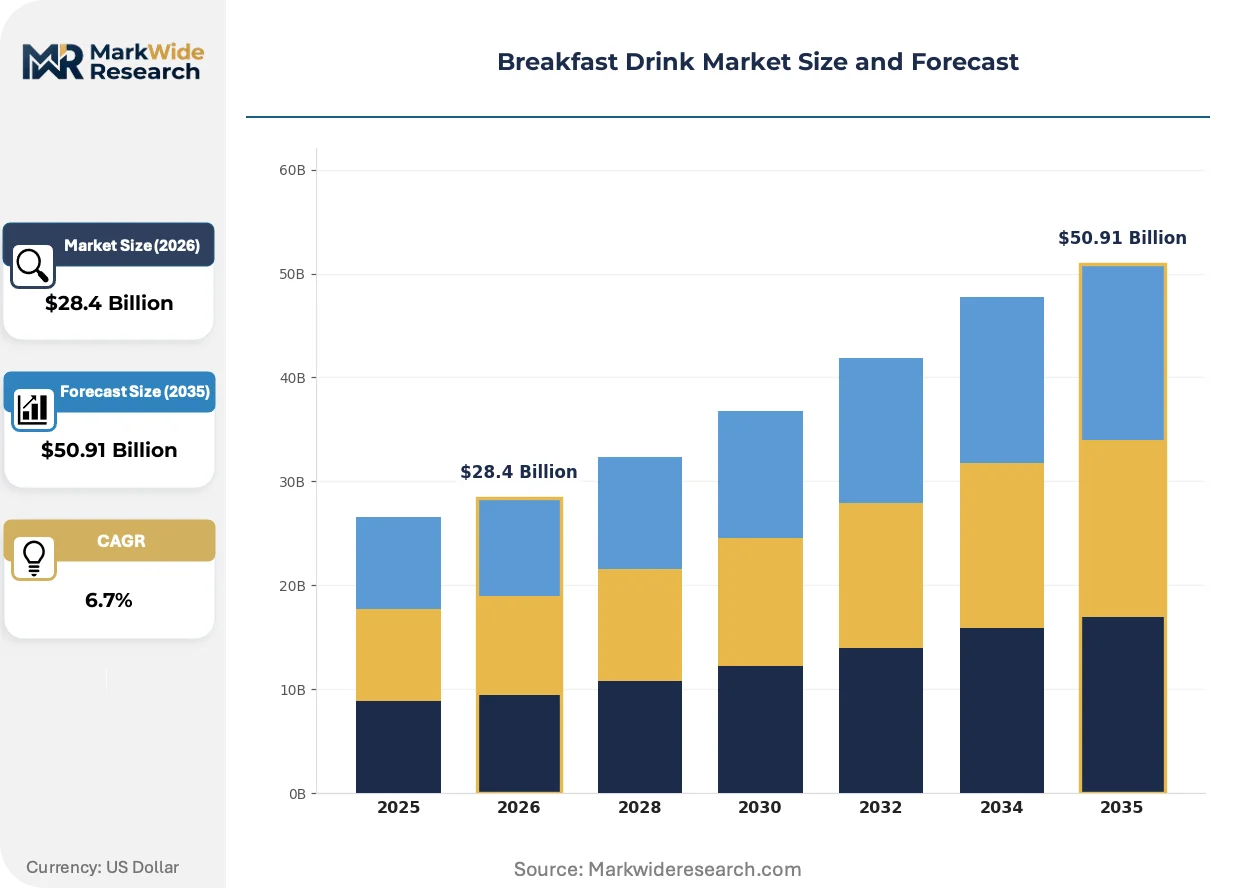
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $50.91 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
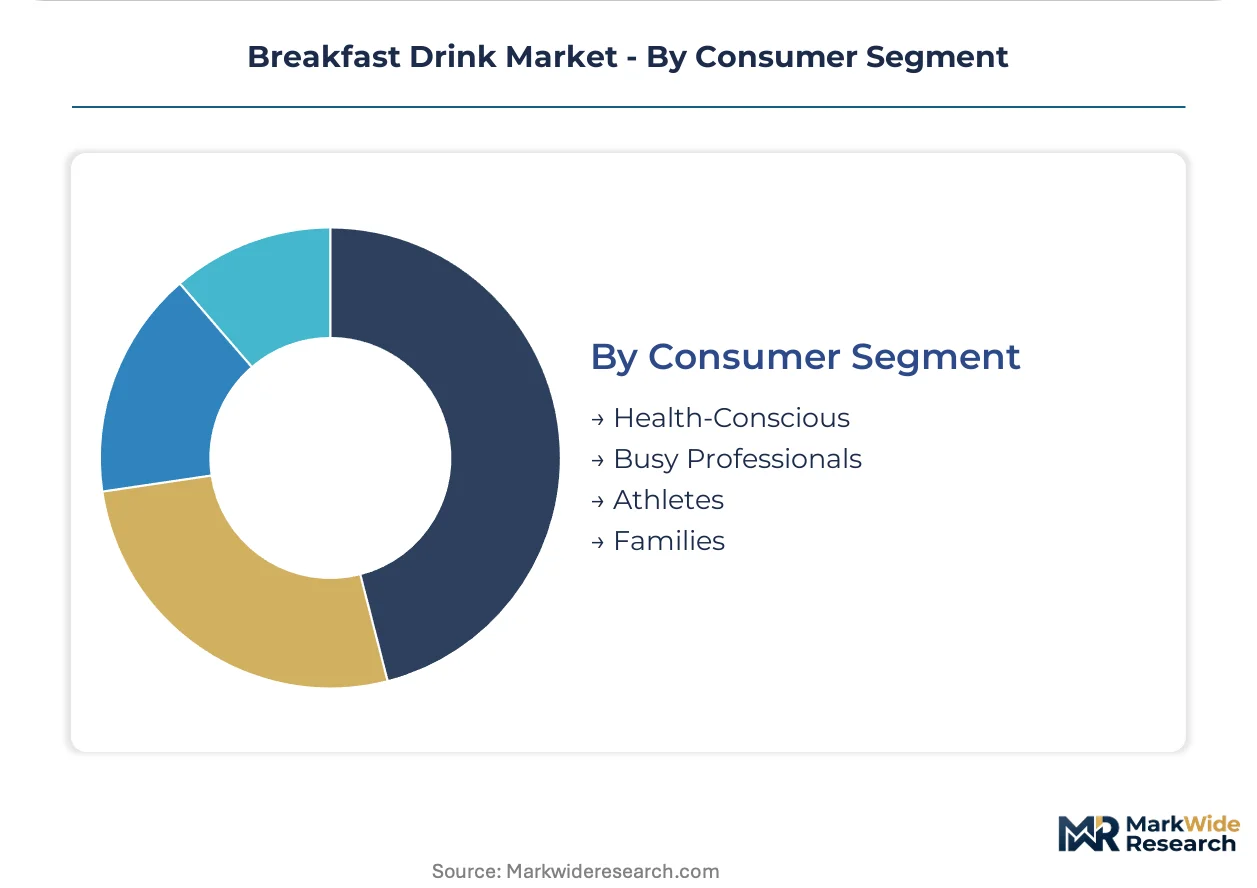
| Segmentation | Product Type: Smoothies, Protein Shakes, Juices, Meal Replacement Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores Ingredient Type: Dairy-Based, Plant-Based, Nutritional Powders, Functional Ingredients Consumer Segment: Health-Conscious, Busy Professionals, Athletes, Families |
| Companies Covered | Nestlé, PepsiCo, Kellogg, General Mills, Danone, Quaker Oats, Sanitarium, MOMA, Post Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breakfast Drink Market Strategic Shifts & Innovations
Formulation science is pivoting toward fermentation-derived ingredients and precision nutrition, collapsing the distinction between conventional beverages and clinical nutrition while opening new distribution channels previously reserved for pharmaceuticals.
Precision fermentation for whey protein identicals is decomposing the traditional dairy supply chain advantage. Biotech startups in California and Singapore are scaling animal-free dairy proteins that bypass lactose and hormone concerns entirely. Sports-nutrition brands are adopting these inputs fastest, forcing conventional dairy processors to defend their ingredient sourcing narratives or lose shelf space in premium retail.
EFSA's updated guidance on novel food authorizations is tightening timelines for cell-cultured and fermentation-derived ingredients entering European markets. Manufacturers must now submit comprehensive toxicology dossiers earlier in development, compressing product launch windows. Brands targeting Germany and France are front-loading regulatory consultation costs to avoid mid-cycle reformulation.
Direct-to-subscription models are displacing traditional retail stocking agreements for functional breakfast drinks. Urban professionals in London, New York, and Shanghai are prioritizing personalized nutrition subscriptions over supermarket convenience. This channel shift rewards brands with flexible manufacturing and punishes those locked into rigid retail distribution contracts.
Breakfast Drink Market Segmentation
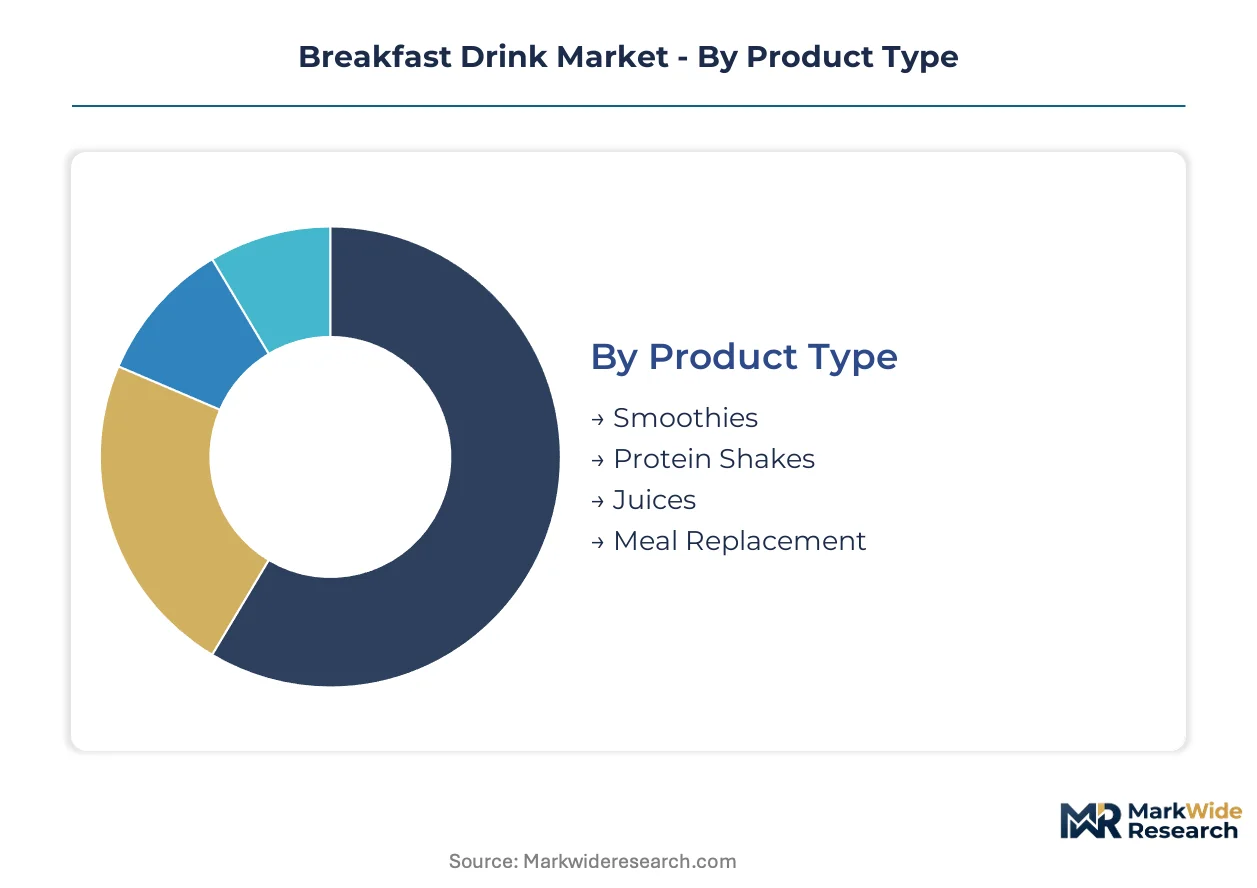
Segmentation in breakfast drinks reveals how formulation priorities and channel access determine margin capture. Each dimension exposes different vulnerability to substitute products—from homemade alternatives to competing convenience formats.
Product Type:
Substitution pressure runs highest in commoditized liquid formats where private-label juice and dairy drinks compete on price. Premium positioned segments with functional ingredient density defend share more effectively against homemade smoothie alternatives.
- Smoothies:Blended fruit-vegetable beverages with fiber and micronutrient density, typically HPP-processed or flash-pasteurized for refrigerated distribution. Demand concentrates in urban coastal United States and German metropolitan areas where grab-and-go breakfast culture dominates morning routines. Cold chain infrastructure gaps in emerging markets constrain penetration.
- Protein Shakes:Dairy or plant-protein fortified beverages targeting post-workout and meal-replacement occasions, manufactured via UHT aseptic filling for ambient stability. Sports nutrition positioning drives adoption among gym-affiliated consumers in China and the United Kingdom, though EFSA health-claim restrictions limit European marketing of muscle-recovery benefits.
- Juices:Pressed or extracted fruit beverages with varying pulp content and fortification levels. Commoditization pressure from fresh-squeezed juice bars and private-label alternatives compresses branded margins in supermarket channels.
- Meal Replacement:Complete-nutrition formulations with calibrated macronutrient profiles and vitamin premixes. Clinical nutrition credibility requirements restrict formulation marketing to specific patient populations in regulated European pharmacy channels.
Smoothies retain volume leadership; protein shakes hold the steepest expansion curve.
Distribution Channel:
Channel cost structures determine which product formats achieve viable unit economics, with refrigerated logistics imposing the steepest barrier to entry for emerging brands.
- Supermarkets:Multi-temperature zone retail with dedicated refrigerated beverage sections and promotional slotting fee structures. Volume concentrates in family-oriented purchasing occasions where bundle pricing and loyalty program integration drive repeat purchase in United States and German hypermarket chains.
- Online Retail:Direct-to-consumer and third-party marketplace distribution enabling subscription models and personalized nutrition bundles. Urban professionals in Shanghai and London metro areas drive fastest adoption, though ambient-stable formats dominate due to shipping cost constraints.
- Convenience Stores:Limited refrigeration capacity with grab-and-go positioning for immediate consumption. Single-serve pricing premiums support margin despite lower basket values in high-traffic urban locations.
- Health Food Stores:Curated specialty retail with educated staff and clean-label certification requirements. Fermented and plant-based formulations gain disproportionate shelf space relative to mainstream channels, particularly in French and Italian organic retail networks.
Supermarkets anchor volume throughput; online retail delivers the most rapid share gain.
Ingredient Type:
Raw material sourcing geography and processing technology requirements create divergent margin profiles across ingredient categories.
- Dairy-Based:Milk protein concentrates and isolates leveraging established dairy processing infrastructure. Family consumer segments in the United States and Germany sustain dominant share despite lactose intolerance prevalence in Asian markets limiting expansion potential.
- Plant-Based:Oat, pea, and soy protein extractions with enzymatic hydrolysis for improved solubility and mouthfeel. Nordic processing technology advances enable neutral taste profiles that accelerate adoption among flexitarian consumers in United Kingdom and Dutch urban centers.
- Nutritional Powders:Dry premix formats requiring reconstitution, offering shipping cost advantages and extended shelf stability. Emerging market penetration in India accelerates under FSSAI fortification mandates for packaged beverages.
- Functional Ingredients:Probiotic cultures, adaptogens, and nootropic compounds with clinical validation requirements. Regulatory fragmentation between FDA, EFSA, and SAMR forces parallel formulation tracks for multi-regional brands.
Dairy-based formulations maintain revenue concentration; plant-based inputs climb the fastest.
Consumer Segment:
Occasion specificity and price sensitivity vary sharply across demographic targets, requiring distinct value proposition architecture.
- Health-Conscious:Label-attentive consumers prioritizing clean ingredient lists and third-party certifications. German and French markets show highest willingness-to-pay for organic and non-GMO positioning, though verification cost burdens squeeze mid-tier brand economics.
- Busy Professionals:Time-constrained urban workers seeking portable nutrition with minimal preparation. Subscription model adoption concentrates in London, New York, and Shanghai where direct-to-consumer brands displace traditional retail stocking.
- Athletes:Performance-oriented consumers with protein gram targets and recovery timing requirements. Sports nutrition specialty retail and gym-affiliated distribution dominate purchase occasions, with precision fermentation proteins gaining traction in California and Singapore markets.
- Families:Multi-person households prioritizing value formats and child-acceptable taste profiles. Bulk sizing and familiar flavor profiles drive supermarket channel concentration in suburban United States and Australian markets.
Health-conscious consumers anchor premium pricing power; busy professionals generate the steepest subscription growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Breakfast drink manufacturing clusters concentrate where dairy processing infrastructure and aseptic filling capabilities overlap. Germany, the United States, China, India, and the United Kingdom each host distinct competitive ecosystems shaped by local regulation and consumer occasion patterns.
United States
Grab-and-go breakfast culture drives refrigerated smoothie and protein shake adoption in urban coastal corridors. FDA nutrition-labeling rules mandate disclosure of added sugars and serving sizes, compressing formulation flexibility for brands targeting health-conscious segments. Chicago and Minneapolis-St. Paul anchor dairy-protein processing infrastructure serving national retail chains.
Germany
Apotheken distribution networks create unique pharmacy-channel opportunities for medical-nutrition breakfast formulations targeting diabetic and geriatric populations. EFSA health-claim substantiation requirements block gut-health marketing that dominates other regions, forcing brands toward clinical validation investments. Bavaria and North Rhine-Westphalia concentrate UHT processing equipment manufacturing and dairy research facilities.
China
Tier-one city professionals drive demand for portable nutrition as traditional breakfast routines fragment. SAMR import pathway streamlining has consolidated registration procedures for functional beverages, reducing foreign brand entry timelines. Shanghai and Beijing retail channels prioritize ambient-stable formats compatible with direct-to-consumer subscription logistics.
India
FSSAI fortification mandates for packaged beverages create formulation contract opportunities for premix suppliers and contract manufacturers. The PLI scheme for food processing offers capital subsidies for domestic fortified beverage manufacturing, reducing import dependency. Maharashtra and Karnataka host emerging cold-chain infrastructure supporting refrigerated format penetration.
United Kingdom
Flexitarian consumers accelerate oat-protein adoption as enzymatic hydrolysis improvements yield neutral-tasting plant alternatives. Clean-label certification requirements from major retailers constrain preservative selection, compressing shelf-life targets for ambient products. London metro subscription models displace traditional retail stocking for busy professional segments.
Breakfast Drink Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the breakfast drink market. Multinational conglomerates leverage dairy-protein research infrastructure and aseptic processing scale to dominate shelf-stable nutrition lines, while specialized plant-based formulators compete through fermentation-derived ingredient innovation. Three strategic archetypes define competitive positioning: diversified food conglomerates with dairy heritage, sports-nutrition specialists with precision fermentation partnerships, and plant-based pure-plays with enzymatic hydrolysis capabilities. Dominant competitive moves include backward integration into protein extraction technologies and geographic expansion through pharmacy-channel partnerships.
Within the diversified conglomerate tier, Nestlé and PepsiCo exemplify scale-driven positioning anchored by dairy-protein research infrastructure and sports-nutrition brand portfolios respectively. Danone occupies a distinct position as a fermentation and plant-base specialist targeting health-food store distribution networks. These three entities represent contrasting responses to precision fermentation disruption—incumbent infrastructure defense versus biotech partnership strategies versus dedicated plant-based system architecture.
| Leading Market Players |
|---|
| Nestlé |
| PepsiCo |
| Kellogg |
| General Mills |
| Danone |
| Quaker Oats |
| Sanitarium |
| MOMA |
| Post Holdings |
| Others |
Cost & Logistics Intelligence
EFSA health-claim substantiation requirements gate both supplier qualification for European retail placement and the price premiums brands can command for functional positioning. Clean-label certification tiers in Germany and France simultaneously determine manufacturing cost structures and consumer willingness-to-pay, compressing margin pools for mid-tier players caught between commodity juice pricing and clinical-grade validation investments.
Pricing Analysis
FDA nutrition-labeling rules dictate the pricing tier structure across United States retail channels, separating premium functional formulations with clinical validation from standard fortified juices and economy private-label alternatives. Three-tier pricing stratifies across premium subscription-direct models, standard supermarket ambient formats, and economy convenience-store single-serve units. Cost compression in the standard tier intensifies because aluminum can sheet concentration exposes brands to energy-market volatility. Family-oriented consumer segments in suburban United States markets show highest price sensitivity, while health-conscious urban professionals in London and Shanghai accept subscription premiums for personalized nutrition bundles.
Supply Chain Analysis
UHT equipment lead times from German and Italian machinery builders create a chokepoint that constrains capacity expansion for ambient-stable breakfast drink lines. Raw material sourcing draws from dairy-protein processing clusters in the United States and Germany, plant-protein extraction facilities in Nordic countries, and functional ingredient suppliers in China and India. Single-source vulnerability concentrates in food-grade aluminum can sheet supply, where three North American smelters control two-thirds of capacity. Distribution runs through refrigerated logistics networks for HPP-processed smoothies in coastal urban United States and German metropolitan areas, while ambient-stable formats feed direct-to-consumer subscription channels in Shanghai and London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation for animal-free dairy proteins is collapsing the traditional supply chain advantage in breakfast drinks, creating a high-growth disruption window as biotech startups in California and Singapore scale production.
For Market Incumbents: Compound defensive positioning by backward integration into oat-protein extraction technologies and captive supply of enzymatic hydrolysis capacity in Nordic processing facilities. Secure pharmacy-channel partnerships in Germany's Apotheken networks before medical-nutrition positioning becomes saturated. Priority lever rests on locking UHT equipment delivery slots with Italian and German machinery builders amid eighteen-month lead times.
For New Entrants and Emerging Players: Lead with cold-aseptic plus HPP hybrid processing to bridge refrigerated and shelf-stable segments with ninety-day clean-label shelf life. Target India's fortified beverage manufacturing under FSSAI mandates and PLI scheme subsidies, where domestic production reduces import dependency. Go-to-market angle centers on contract manufacturing partnerships with premix suppliers serving South Asian export channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation infrastructure as biotech startups require scale-up investment before reaching cost parity with conventional dairy proteins. Long-term viability favors acquisition targets with enzymatic hydrolysis capabilities and established health-food store distribution in French and Italian organic retail networks. Signal to monitor: SAMR registration timelines for foreign brands entering tier-one Chinese cities, which indicate regulatory pathway efficiency for functional beverage entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Biotech collaboration with California or Singapore startups bypasses lactose concerns while securing novel protein supply. |
| Pharmacy Channel Expansion | Apotheken distribution in Germany unlocks reimbursement eligibility for diabetic and geriatric formulations. |
| Hybrid Processing Investment | Cold-aseptic plus HPP convergence enables clean-label positioning with extended ambient stability. |
| Backward Integration into Protein Extraction | In-house oat or pea-protein processing insulates margin from Nordic technology licensing costs. |
| Direct-to-Consumer Subscription Launch | Urban professional segments in London and Shanghai displace traditional retail with personalized nutrition models. |
Research Approach
The analysis maps dairy-based, plant-based, nutritional powder, and functional ingredient sub-sectors, each validated through formulation scientists at contract manufacturers, regulatory affairs specialists navigating FDA and EFSA frameworks, and category buyers at German and United States supermarket chains. Primary interviews with supply chain managers at aseptic filling equipment manufacturers and procurement leads at aluminum can sheet distributors combined with secondary validation from FSSAI fortification mandate documentation, SAMR registration databases, EFSA novel food authorization guidance, and Nielsen retail audit data. Bottom-up volume builds triangulated against top-down macroeconomic consumption trend analysis.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon, with analytical framework approach modeling product type, ingredient source, distribution channel, and consumer occasion dimensions. CAGRs derived from segment-level growth rate analysis applied to base-year market sizing, incorporating UHT equipment capacity expansion timelines, cold-chain infrastructure development in India, and precision fermentation protein cost curves as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA nutrition-labeling rules, EFSA health-claim frameworks, and SAMR import procedures; material policy shifts would require re-modeling of foreign brand entry timelines and functional ingredient marketing permissions. Scenario risks include synthetic additive ban expansions in the European Union, aluminum supply disruptions from energy market spikes, and divergence in additive permissions between FDA, EFSA, and SAMR forcing SKU fragmentation. Practitioners should keep alternative scenarios live as clean-label preservative technology and cross-border formulation harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Italy Probiotic Drinks Market
Beverages
Soy Drinks Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Oat Based Beverages Market
Beverages
Maple Water Market
Beverages
Herb Infused Water Market
Beverages
Soft Serves Market
Beverages
Global Bottled Water Market
Beverages
Kombucha Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Water Flavor Market
Beverages
North America Energy Drink Market
Beverages
BBQ Charcoal Market
Beverages
Freezer & Beverage and Wine Cooler Market