
 Antistatic Device for Ultrapure Water Market | 2026-2036
Antistatic Device for Ultrapure Water Market Size, Share, and Industry Trends Forecast 2026-2036
Antistatic Device for Ultrapure Water Market Insights
The premium-to-commodity split in antistatic ultrapure water hardware is shifting along the fault line of ionization precision versus basic conductivity control. DIC Corporation leverages its polymer chemistry heritage to dominate membrane-electrode assembly supply for inline devices. NGK Insulators anchors the ceramic electrode segment with alumina-based substrates that sustain longer duty cycles in corrosive UPW loops. Nomura Micro Science competes through extreme-precision calibration services that extend equipment life in 300mm wafer fabs.
An antistatic device for ultrapure water is a specialized treatment unit that neutralizes electrostatic charge in deionized water streams through controlled ionization, typically maintaining resistivity between 15-18 MΩ·cm while eliminating static potentials that damage semiconductor wafers during rinsing and cleaning operations. Inline Devices lead the product hierarchy due to their integration into continuous-flow UPW distribution networks, whereas Plasma Technology segments are gaining fastest as fabs adopt non-contact ionization to avoid metallic contamination from electrode degradation. Semiconductor Manufacturing end users command the deepest margin pools because their yield-loss economics justify premium pricing for sub-particle-grade antistatic performance.
EPA effluent guidelines and REACH Annex XVII restrictions on halogenated discharge shape equipment design by mandating closed-loop ion recovery, while SEMI F104 standards for ultrapure water quality establish the electrostatic benchmarks that OEMs must certify against. Japan's METI circular economy directives and South Korea's K-Battery and K-Semiconductor bills are accelerating replacement demand for energy-efficient antistatic modules. Stakeholders must weigh electrode material selection against emerging plasma-based alternatives as regulatory thresholds on metallic leachates tighten across major fabrication jurisdictions.
Market Dynamics
Sub-10nm semiconductor node migration is compressing antistatic water treatment tolerances, forcing fabs to retire legacy ionization hardware before depreciation cycles complete.
Growth Catalysts
- EPA Effluent Guidelines:Closed-loop ion recovery mandates under US discharge rules are compelling fabs to upgrade to certified antistatic systems that capture metallic leachates.
- Semiconductor Yield Economics:Taiwan and South Korean 300mm wafer facilities prioritize electrostatic discharge elimination over capital preservation, shortening replacement cycles.
- Plasma Ionization:Non-contact charge neutralization eliminates electrode degradation risks, attracting fabs running corrosive UPW chemistries.
Market Restraints
- Alumina Substrate Concentration:Ceramic electrode supply chains concentrate in Japanese specialty ceramics producers, exposing buyers to single-source fragility.
- Platinum Group Metal Costs:Membrane-electrode assemblies rely on iridium and ruthenium catalysts, subjecting hardware pricing to volatile precious metal markets.
- REACH Annex XVII:Halogenated compound restrictions complicate electrode cleaning chemistries, extending qualification timelines for new installations.
Strategic Opportunities
- India Semiconductor Mission:Greenfield fab construction under PLI incentives creates first-mover positioning for antistatic system vendors before local supply chains mature.
- Photovoltaic Cell Manufacturing:Silicon wafer cleaning for heterojunction solar cells applies semiconductor-grade UPW standards, opening adjacent demand.
- AI-Driven Predictive Maintenance:Machine learning calibration services extend equipment life, shifting revenue from hardware sales to recurring service contracts.
Industry Challenges
- SEMI F104 Certification Timelines:Third-party validation for sub-particle-grade electrostatic performance consumes 14-18 months, delaying revenue recognition.
- Legacy UPW Loop Integration:Retrofitting plasma ionization into 1990s-era distribution architecture requires custom manifold redesigns that disrupt fab operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antistatic Device for Ultrapure Water Market |
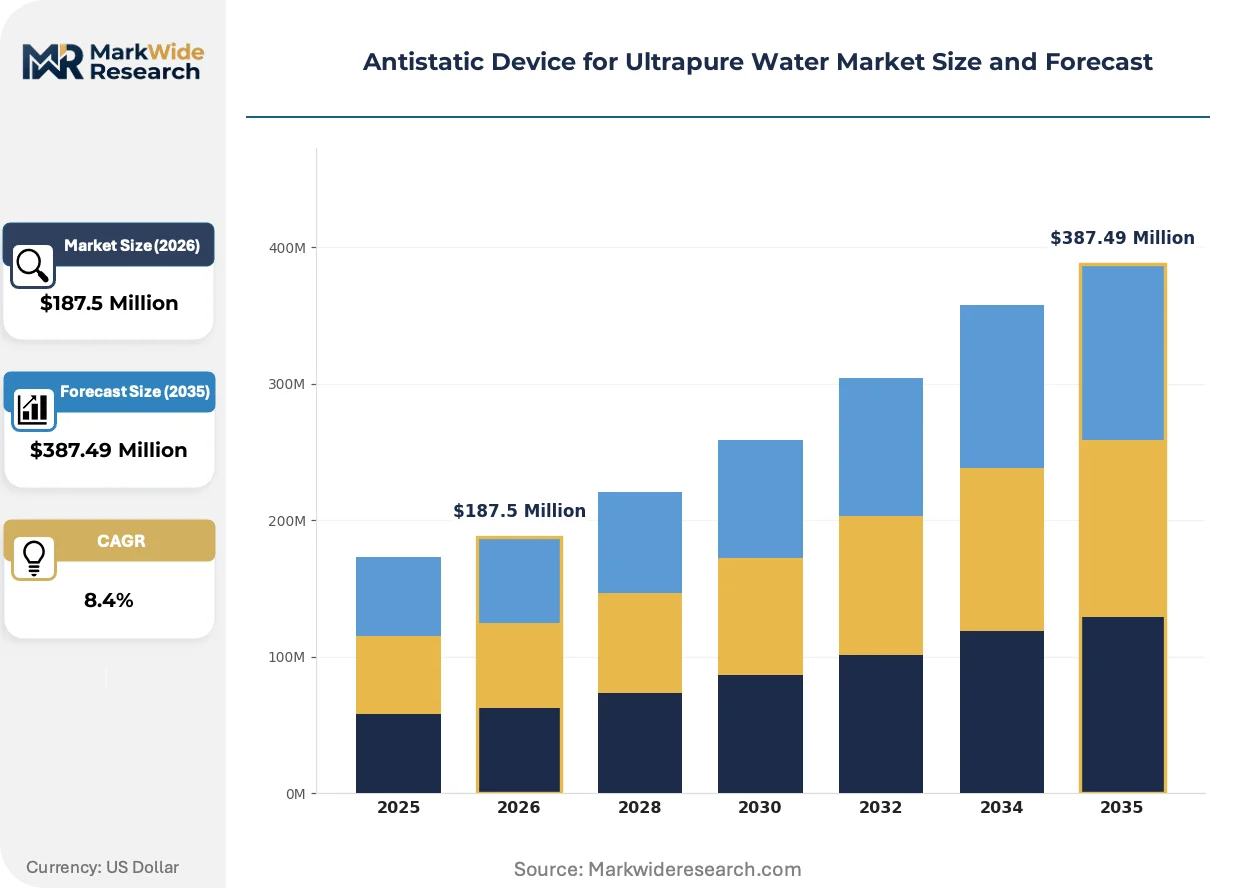
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $387.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Devices, Handheld Units, Automatic Systems, Static Neutralizers Technology: Ionization, Plasma Technology, Conductive Coatings, Electrode Systems End User: Semiconductor Manufacturing, Pharmaceutical Plants, Research Laboratories, Electronics Industry Application: Water Treatment, Equipment Cooling, Process Control, Chemical Processing |
| Companies Covered | DIC Corporation, NGK Insulators, Nomura Micro Science, AVVA R&D Corporation, Advanced Dicing Technologies, DISCO Corporation, AIRRANE, Suzhou SLD Electronic, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antistatic Device for Ultrapure Water Market Trends and Innovations
Antistatic ultrapure water treatment is pivoting from electrode-based hardware toward field-ionization architectures, with regulatory chemistry restrictions and yield-loss economics jointly accelerating hardware obsolescence.
Dielectric barrier discharge plasma modules are rewriting competitive positioning in high-volume UPW loops. These non-contact ionizers eliminate metallic electrode surfaces entirely, removing contamination risks that degrade sub-10nm yield. Leading memory fabs in South Korea are standardizing plasma architectures for new 300mm lines, compressing demand for traditional membrane-electrode devices.
REACH Annex XVII halogen restrictions are reshaping electrode maintenance protocols across European semiconductor installations. The regulation bans specific chlorinated and fluorinated cleaning agents previously used to restore membrane conductivity, forcing fabs to adopt aqueous cleaning chemistries with longer cycle times. German and Dutch facilities report 15-20% throughput penalties during transition periods.
Calibration-as-a-service contracts are displacing capital purchase models among mature 200mm fabs. Equipment vendors retain hardware ownership while charging per-liter-treated fees, transferring electrode degradation risk from fabs to suppliers. This shift concentrates most visibly in Japanese analog and power semiconductor facilities seeking to preserve cash for node migration investments.
Antistatic Device for Ultrapure Water Market Segmentation
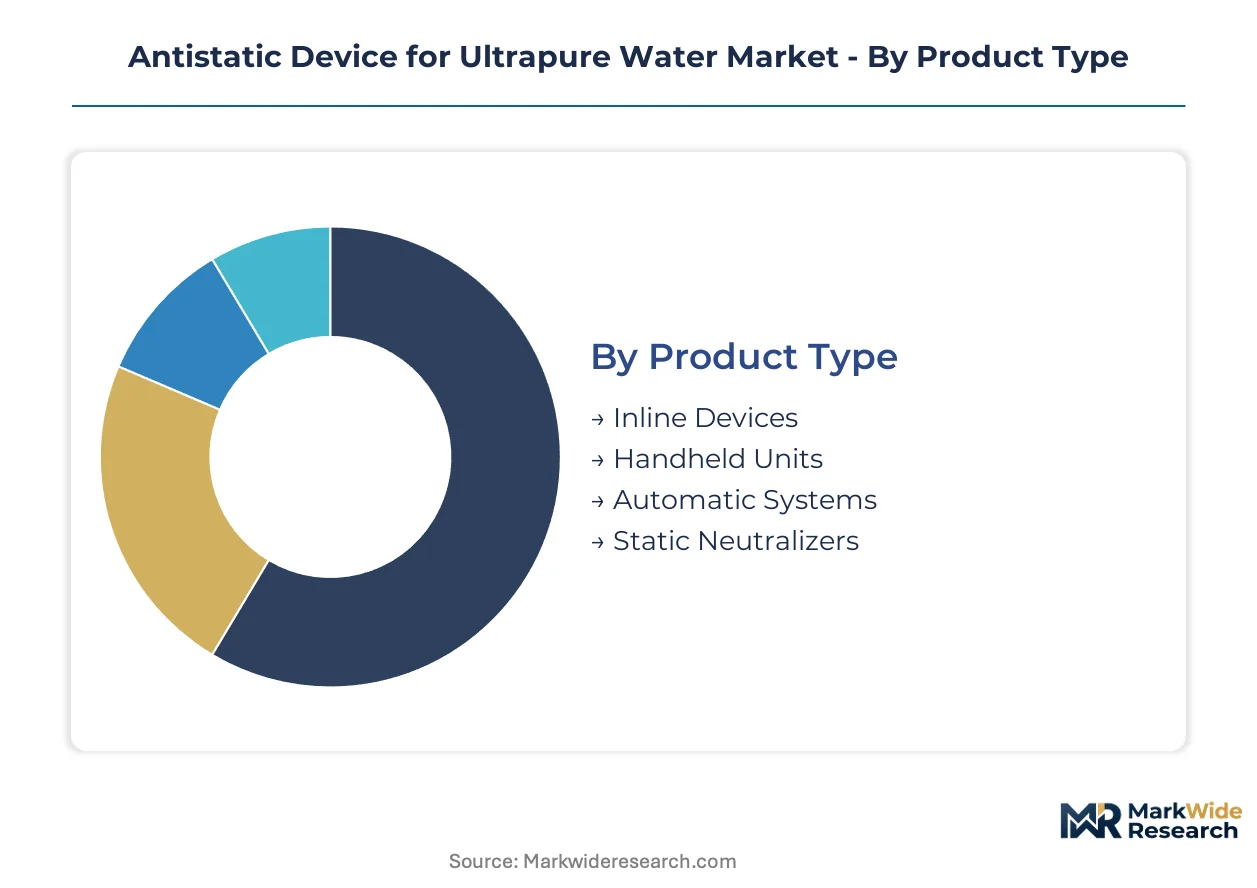
Antistatic ultrapure water hardware fragments across four structural dimensions that determine procurement priorities. Semiconductor fabs weight ionization precision against metallic contamination risk, while pharmaceutical operators prioritize validation documentation over raw throughput capacity.
Product Type:
Cost tier separates buyers most sharply in this category, with capital intensity and integration depth driving divergent purchasing patterns.
- Inline Devices:These units integrate permanently into UPW distribution loops, maintaining continuous resistivity between 15-18 MΩ·cm through membrane-electrode or plasma architectures. Demand concentrates in Taiwan and South Korean 300mm wafer fabs where uninterruptible charge neutralization justifies premium positioning. EPA closed-loop ion recovery mandates are accelerating replacement of legacy units that leak metallic catalysts into effluent streams.
- Automatic Systems:Self-calibrating architectures with AI-driven predictive maintenance modules reduce manual intervention in high-throughput facilities. Japanese analog semiconductor plants favor these for 200mm line retrofits where labor constraints intersect with yield preservation requirements.
- Handheld Units:Portable verification tools for spot-checking UPW resistivity at point-of-use. Research laboratories and small-batch pharmaceutical operations deploy these for flexibility without infrastructure commitment.
- Static Neutralizers:Point-source discharge elimination devices mounted at critical wafer transfer stations. Electronics assembly facilities outside semiconductor fabrication use these for downstream protection.
Volume sits with Inline Devices; growth tilts toward Automatic Systems.
Technology:
Application chemistry determines technology selection, with corrosive UPW formulations and sub-10nm contamination thresholds eliminating legacy options.
- Plasma Technology:Dielectric barrier discharge modules ionize water without metallic electrode contact, eliminating particle shedding that degrades advanced node yield. South Korean memory fabs are standardizing this architecture for new 300mm lines running aggressive chemistries. REACH Annex XVII halogen restrictions reinforce plasma adoption by complicating electrode maintenance protocols.
- Ionization:Traditional membrane-electrode assemblies using polymer electrolyte membranes with precious metal catalysts dominate installed base. Taiwan foundries retain these for mature node lines where capital preservation outweighs contamination risk.
- Electrode Systems:Ceramic-substrate ionizers with alumina-based architectures sustain longer duty cycles in standard UPW chemistries. Japanese specialty ceramics producers anchor supply for these units.
- Conductive Coatings:Surface-treatment approaches for legacy equipment retrofit, extending service life without full replacement. Mature fabs in analog and power semiconductor segments apply these as bridge solutions.
Revenue concentrates in Ionization; Plasma Technology is climbing the fastest.
End User:
Margin structure differentiates buyers, with yield-loss economics justifying premium pricing in semiconductor while validation costs dominate pharmaceutical procurement.
- Semiconductor Manufacturing:Sub-10nm node requirements demand sub-particle-grade electrostatic performance with SEMI F104 certification. Taiwan and South Korean facilities command the deepest margin pools and shortest replacement cycles.
- Pharmaceutical Plants:Injectable drug manufacturing requires UPW meeting pharmacopeial conductivity specifications with full batch documentation. FDA validation timelines extend qualification periods versus semiconductor benchmarks.
- Electronics Industry:Printed circuit board and display manufacturing applies less stringent resistivity standards, prioritizing capital efficiency over extreme precision.
- Research Laboratories:Variable demand patterns and grant-funded procurement favor flexible, lower-volume configurations with multi-protocol compatibility.
Semiconductor Manufacturing captures the largest revenue share; Pharmaceutical Plants offer the steepest expansion trajectory.
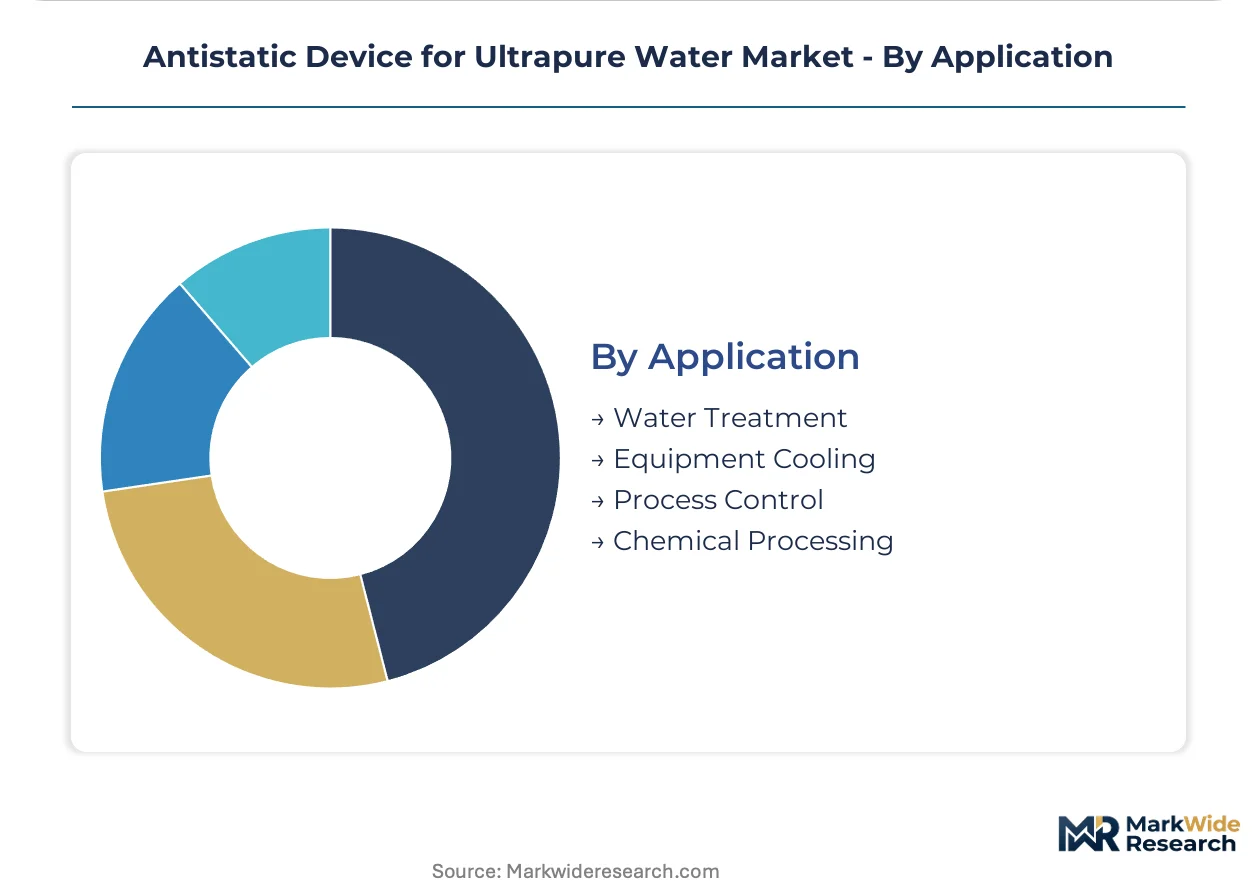
Application:
Customer maturity shapes demand, with greenfield fabs adopting integrated solutions while legacy facilities pursue modular upgrades.
- Water Treatment:Primary UPW loop charge neutralization represents the core use case, spanning distribution, storage, and point-of-use protection. All semiconductor fabs require this capability.
- Process Control:Real-time resistivity monitoring with automated feedback loops enables closed-loop quality management. Advanced facilities deploy these for predictive yield optimization.
- Equipment Cooling:Thermal management systems for lithography and etch tools require antistatic coolant to prevent electrostatic damage to precision optics.
- Chemical Processing:UPW blending and chemical dilution operations need charge neutralization to prevent static ignition in solvent handling.
Water Treatment anchors volume; Process Control is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors global antistatic ultrapure water demand, with Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation expanding sub-3nm fabrication lines that require non-contact ionization systems.
United States
Intel's Ohio and Arizona mega-fabs drive procurement of SEMI F104-certified antistatic modules for advanced packaging operations. EPA effluent guidelines under the Clean Water Act mandate closed-loop ion recovery systems that capture metallic catalysts from membrane-electrode assemblies. The Phoenix-Tucson corridor in Arizona concentrates new 300mm wafer capacity where plasma ionization architectures are displacing legacy hardware.
South Korea
Samsung Electronics and SK Hynix are standardizing dielectric barrier discharge plasma modules across Pyeongtaek and Yongin memory complexes to eliminate electrode contamination risks at sub-10nm nodes. The K-Semiconductor Bill provides tax incentives for energy-efficient water treatment equipment that reduces fab carbon intensity. The Gyeonggi-do province surrounding Seoul hosts the densest cluster of antistatic system retrofits as older 200mm lines upgrade to meet export quality standards.
Japan
Tokyo Electron and Shin-Etsu Chemical drive demand for extreme-precision calibration services that extend equipment life in mature analog fabs. METI circular economy directives accelerate replacement cycles for energy-inefficient ionization hardware through subsidy programs targeting 20% power reduction. The Kyushu region, anchored by Kumamoto and Saga prefectures, concentrates ceramic electrode production where NGK Insulators and specialty ceramics suppliers serve domestic and export markets.
China
SMIC and Hua Hong Semiconductor expand 28nm and 14nm lines in Shanghai and Beijing that require imported antistatic systems meeting domestic GB/T standards for ultrapure water quality. MIIT localization policies incentivize joint ventures with foreign equipment vendors to transfer membrane-electrode assembly technology. The Yangtze River Delta, spanning Suzhou, Wuxi, and Hangzhou, hosts the fastest-growing cluster of indigenous antistatic device manufacturing as domestic supply chains mature.
Germany
Bosch and Infineon prioritize REACH Annex XVII-compliant plasma ionization for automotive and power semiconductor fabs in Dresden and Regensburg. ECHA restrictions on halogenated electrode cleaning agents force 15-20% throughput penalties during chemistry transitions. The Saxony region, centered on Dresden's Silicon Saxony cluster, leads European adoption of non-contact charge neutralization systems for silicon carbide wafer processing.
Antistatic Device for Ultrapure Water Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the ionization precision spectrum, with sub-particle-grade certification separating pricing tiers by 40-60%. The vendor base consolidates around three strategic archetypes: polymer chemistry specialists supplying membrane-electrode assemblies, ceramic substrate manufacturers anchoring electrode durability, and precision calibration service providers extending equipment lifecycle value. Capacity expansion and strategic technology licensing dominate competitive moves, with plasma architecture partnerships accelerating as fabs abandon metallic electrode systems.
Within the materials-specialist tier, DIC Corporation and NGK Insulators occupy positions that exemplify divergent substrate strategies, while Nomura Micro Science anchors the precision-calibration service archetype. Japanese corporate structures dominate the premium segment, with kabushiki gaisha and specialized ceramics producers leveraging domestic semiconductor relationships. Suzhou SLD Electronic represents Chinese indigenous manufacturing capabilities targeting cost-optimized segments. The competitive dynamic pits polymer-electrode heritage against ceramic durability and plasma non-contact architectures, with technology licensing agreements increasingly bridging these approaches.
| Leading Market Players |
|---|
| DIC Corporation |
| NGK Insulators |
| Nomura Micro Science |
| AVVA R&D Corporation |
| Advanced Dicing Technologies |
| DISCO Corporation |
| AIRRANE |
| Suzhou SLD Electronic |
| 3M |
| Others |
Pricing and Supply Chain Analysis
Dielectric barrier discharge plasma modules are simultaneously compressing manufacturing costs and dispersing supplier concentration away from Japanese ceramic-electrode incumbents. This technology transition reconfigures procurement economics as fabs abandon precious-metal catalyst assemblies for non-contact ionization architectures.
Pricing Analysis
Yield-loss economics anchor pricing power for SEMI F104-certified systems, with semiconductor fabs absorbing 40-60% premiums for sub-particle-grade electrostatic performance. Three-tier pricing structure across premium, standard, and economy levels separates plasma-based non-contact systems from membrane-electrode assemblies and conductive coating retrofits. Cost compression in standard ionization tiers is intensifying because iridium and ruthenium catalyst prices feed directly into membrane-electrode assembly costs. Research laboratories and small-batch pharmaceutical operators exhibit the highest price sensitivity, while Taiwan and South Korean 300mm wafer fabs prioritize uptime guarantees over capital preservation.
Supply Chain Analysis
Refurbishment flows for legacy membrane-electrode assemblies are creating secondary supply channels that compete with new equipment sales in mature 200mm fab markets. Manufacturing concentrates in Japan, South Korea, and Taiwan, with ceramic substrate production anchored in Kyushu and polymer electrolyte membrane fabrication centered in Osaka-Kobe corridors. Iridium catalysts, alumina ceramic substrates, and fluorinated polymer membranes constitute critical input dependencies. Single-source vulnerability runs through Japanese specialty ceramics producers dominating alumina electrode substrates. Distribution runs through direct OEM-fab relationships for inline systems, with calibration services delivered through regional technical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma ionization standardization at sub-10nm nodes is forcing consolidation among electrode-dependent hardware suppliers unable to pivot manufacturing capabilities. This technology displacement eliminates weaker players lacking R&D scale to develop non-contact architectures.
For Market Incumbents: To counter plasma architecture displacement, membrane-electrode specialists must secure licensing partnerships with dielectric barrier discharge technology holders or risk stranded capacity in ceramic substrate production. Backward integration into iridium catalyst recycling capabilities preserves margin structure against precious metal volatility. Certification investment in SEMI F104 sub-particle-grade validation extends pricing power in legacy node retrofit markets.
For New Entrants and Emerging Players: Mature 200mm analog semiconductor facilities in Japan represent the most penetrable buyer archetype, with calibration-as-a-service contracts displacing capital purchase models and creating recurring revenue footholds. Photovoltaic cell manufacturing for heterojunction solar cells applies semiconductor-grade UPW standards with less stringent vendor qualification barriers. Go-to-market positioning through AI-driven predictive maintenance modules differentiates against incumbent hardware-centric sales approaches.
For Investors and Strategic Acquirers: Re-rating potential sits with precision-calibration service providers given the shift from capital sales to per-liter-treated fee structures across mature fab installations. Long-term viability over the next decade favors vendors with plasma architecture partnerships and recurring service contract portfolios rather than pure hardware manufacturers. Watch for REACH Annex XVII enforcement acceleration in European semiconductor clusters as the inflection indicator for plasma ionization adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Architecture Licensing | Technology partnerships with South Korean memory fabs accelerate non-contact ionization standardization. |
| Calibration-as-a-Service Expansion | Recurring revenue models capture mature 200mm fab maintenance budgets in Japan. |
| Precious Metal Recycling Integration | Captive iridium recovery reduces membrane-electrode assembly cost volatility. |
| India Greenfield Fab Positioning | First-mover supply relationships under PLI incentives establish local presence before indigenous competition. |
| Photovoltaic Adjacent Market Entry | Heterojunction solar cell UPW requirements open volume demand outside semiconductor cyclicality. |
Research Methodology
Independent corroboration across equipment vendor technical documentation, semiconductor fab engineering specifications, and regulatory filing databases underwrites the qualitative findings in this study. Primary interviews with UPW system design engineers, fab facilities managers, and environmental compliance officers at semiconductor manufacturing sites were combined with secondary validation from EPA effluent guideline records, SEMI standards publications, and ECHA REACH restriction documentation. Bottom-up demand modeling across inline device, automatic system, and handheld unit categories was triangulated against top-down market sizing from precious metal consumption data and ceramic substrate trade flows.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price-mix effects in antistatic ultrapure water hardware. The analytical framework models technology type, product configuration, end-user segment, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from installed base turnover analysis and replacement cycle compression at sub-10nm node transitions. Forecast inputs incorporate EPA closed-loop ion recovery mandate compliance timelines and METI circular economy subsidy program uptake rates.
Revisions become necessary when semiconductor node migration pauses, precious metal catalyst prices destabilize membrane-electrode economics, or REACH Annex XVII restrictions expand beyond halogenated compounds. Forecasts reflect assumptions about plasma technology cost curves and fab retrofit willingness-to-pay thresholds. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
IR Detector Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Europe Trace Detection Market