
 Voltage Detector Market | 2026-2036
Voltage Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Voltage Detector Market Intelligence
The EU Green Deal's mandate for grid modernization and renewable energy integration is repositioning the need for advanced electrical safety equipment. Fluke Corporation leverages its strong brand and distribution channels in the professional electrical contractor segment. Honeywell International Inc. specializes in integrated safety solutions for demanding industrial environments. ABB competes with its comprehensive portfolio designed for utility-scale power transmission and distribution applications.
A voltage detector is an electrical testing instrument that confirms the presence or absence of voltage in conductors, often specified for ranges below 1000V for residential use or higher for industrial settings. Its fundamental purpose is to ensure electrical safety by verifying that equipment is de-energized before service. Smart and wireless detectors represent the fastest-growing technology category, offering data logging and remote monitoring capabilities. The utilities and professional contractors end-user segments constitute the largest and most mature share of the market.
Product design and market access are governed by stringent safety standards, including the international IEC 61010 for measurement equipment and regional certifications like CE marking in Europe. In the United States, OSHA regulations mandate the use of such devices for lockout/tagout procedures, directly preventing workplace accidents. Vendor success will depend on aligning product development with the demand for integrated, data-capable devices that enhance technician safety and operational efficiency.
Market Dynamics
The imperative for grid reliability and worker safety is the central force shaping the voltage detector market. This is driven by national energy policies mandating smart grid upgrades and stringent occupational safety regulations that require verifiable electrical isolation before maintenance.
Growth Catalysts
- Grid Modernization Mandates:The EU Green Deal and similar policies in other regions necessitate extensive grid upgrades and renewable energy integration, directly stimulating demand for advanced electrical testing tools for maintenance and installation crews.
- Utilities Sector Expansion:In countries like India and China, massive investment in expanding and upgrading power transmission and distribution infrastructure creates a foundational demand for voltage detectors to ensure operational safety.
- Smart Grid Technology:The global transition towards smart grids requires more sophisticated diagnostic instruments, including detectors with data logging, to manage complex, digitally controlled power networks effectively and safely.
Market Restraints
- Compliance Costs:The high cost and complexity of achieving and maintaining compliance with multiple international standards, such as IEC 61010 and regional certifications like CE marking, can be a significant barrier for smaller manufacturers.
- Product Cannibalization:The increasing integration of voltage detection capabilities into more complex, multifunction electrical testers poses a substitution threat, potentially eroding the market for standalone, single-purpose devices.
- Technical Limitations:Ensuring consistent accuracy and preventing false readings in environments with high electromagnetic interference, common in industrial plants and substations, remains a persistent technical challenge for product designers.
Strategic Opportunities
- Renewable Energy Sector:The rapid build-out of solar and wind energy installations presents an opportunity for specialized detectors designed for high-voltage DC systems and the unique maintenance requirements of renewable power generation assets.
- IoT and Software Integration:Integrating detectors with mobile applications and cloud platforms for automated safety logging, asset management, and remote monitoring offers a significant value-add for enterprise customers in the utilities sector.
- Underpenetrated Geographies:Markets in Southeast Asia and Africa, where grid infrastructure is still developing, offer long-term growth potential for vendors that can establish early distribution channels and brand presence.
Industry Challenges
- Certification Timelines:Navigating the lengthy and rigorous testing and certification processes required by bodies like UL in the United States and for CE marking in Europe can significantly delay product launches and increase development costs. *Legacy System Integration: The difficulty of integrating data from new smart detectors into older, existing enterprise asset management (EAM) and safety software platforms used by large utilities can slow adoption rates.
- Technician Skill Gaps:A shortage of technicians trained to effectively use and interpret data from advanced, data-logging detectors can limit the realization of their full safety and efficiency benefits, particularly in emerging economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voltage Detector Market |
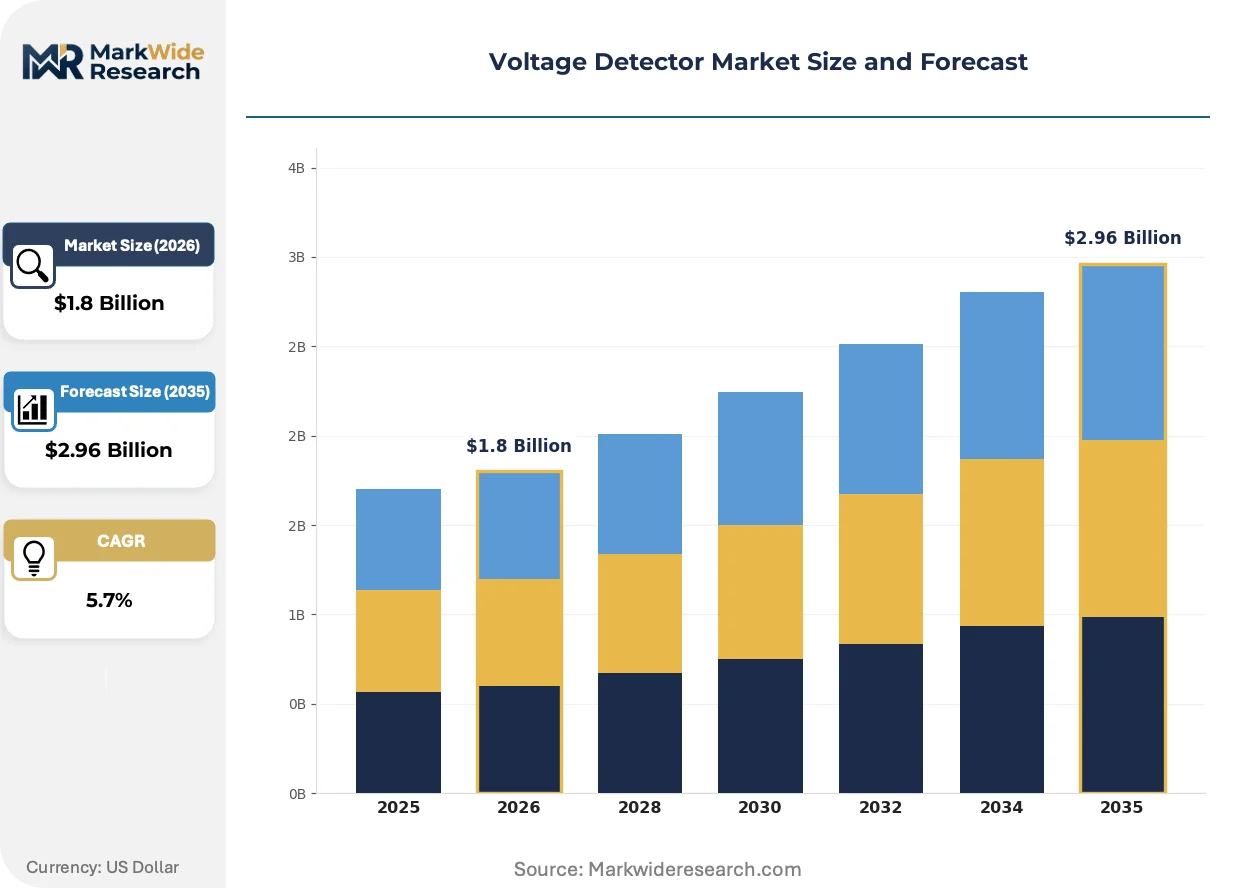
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed, Inductive, Non-Contact End User: Utilities, Contractors, DIY Enthusiasts, Maintenance Technicians Technology: Analog, Digital, Smart, Wireless Application: Electrical Testing, Maintenance, Safety Inspections, Equipment Diagnostics |
| Companies Covered | Renesas Electronics Corporation, Hioki E.E. Corporation, Honeywell International Inc., Amprobe co., Megger Ltd., Fluke Corporation, ABB, UNI-TREND TECHNOLOGY CO. LTD., Analog Devices Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voltage Detector Market Strategic Shifts & Innovations
The market's evolution is defined by the transformation of voltage detectors from simple go/no-go indicators into intelligent, connected components of a broader digital safety ecosystem. This shift is driven by the need for verifiable, data-backed safety compliance in high-risk environments.
Wireless connectivity, primarily Bluetooth, is being embedded directly into modern voltage detectors to enable real-time data transfer. Utilities and large industrial maintenance teams are the primary adopters, seeking to improve safety protocols and operational efficiency. This integration of wireless technology is automating the logging of safety verifications, which creates an indelible digital audit trail for compliance with OSHA lockout/tagout procedures.
Stricter regulatory frameworks, such as the safety measures enforced by India's Central Electricity Authority (CEA) for grid work, are compelling changes in equipment standards. These mandates necessitate verifiable proof of de-energization, elevating the legal and financial risks associated with non-compliance. Consequently, the professional contractor segment is most affected, now required to procure devices that meet specific BIS and CEA certifications.
A notable behavioral change is emerging as large utility and industrial clients bundle equipment acquisition with software and training services. This moves the transaction away from one-off hardware purchases toward integrated safety solution contracts that emphasize total lifecycle value. This model is most prominent in North America and Europe, where mature end-users prioritize auditable compliance and risk reduction over the initial device cost.
Voltage Detector Market Segmentation
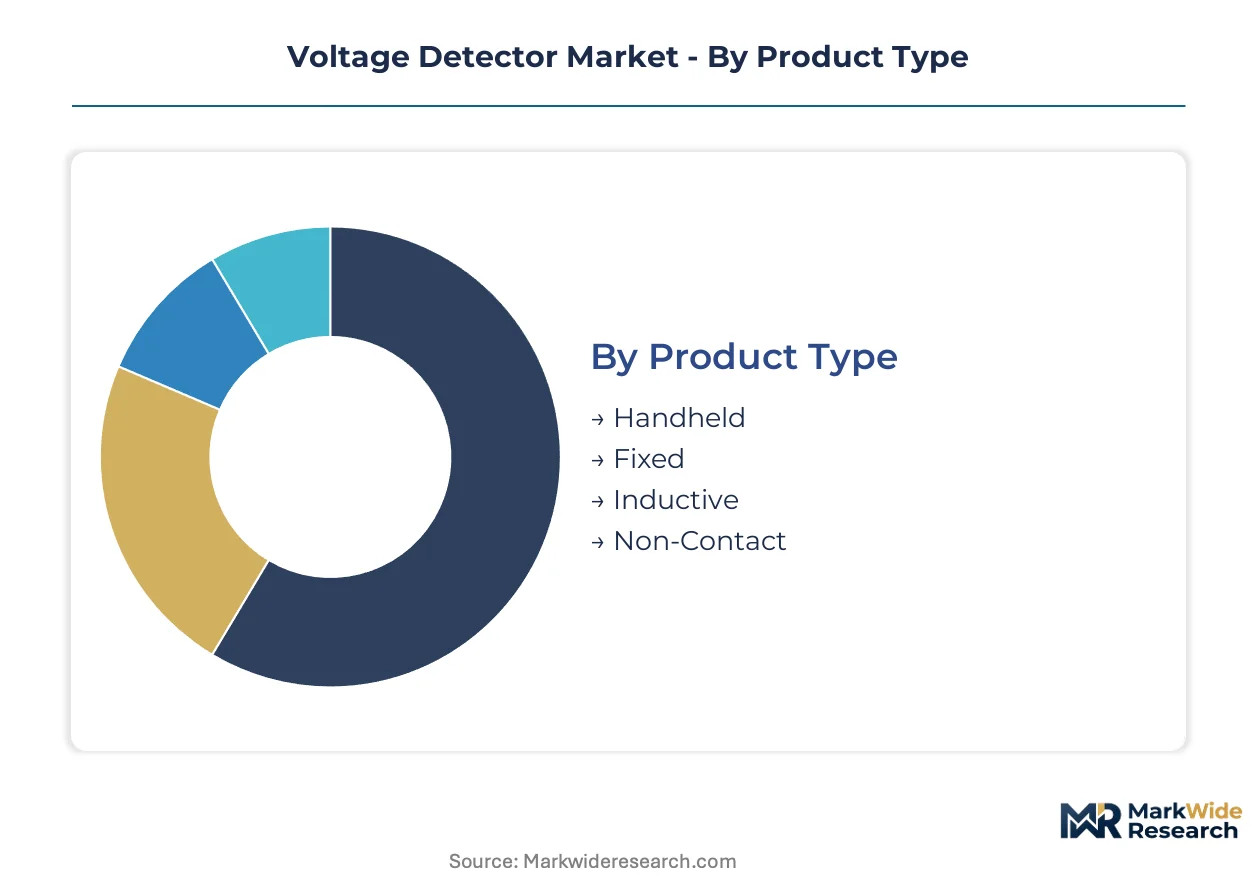
The Voltage Detector Market exhibits distinct segmentation across product type, end-user categories, underlying technology, and specific applications. Understanding these segments is crucial for identifying areas of concentrated demand, technological innovation, and strategic market entry. Each segment addresses varying operational needs and regulatory compliance requirements within the global electrical infrastructure.
Product Type:
Product type variations in voltage detectors span from highly standardized tools for routine tasks to specialized instruments tailored for unique industrial requirements.
- Handheld:These portable devices offer electricians and technicians immediate voltage verification, designed for ease of use in diverse field environments. Demand concentrates in the professional contractor segment for daily troubleshooting and safety checks across Europe and North America.
- Non-Contact:Utilizing electromagnetic fields, these detectors identify voltage presence without direct contact, enhancing safety by minimizing arc flash risks. Utilities in China and India increasingly adopt non-contact solutions for live-line work and grid maintenance, driven by worker safety mandates.
- Fixed:Permanently installed in electrical panels or machinery, fixed detectors provide continuous monitoring of voltage status within industrial facilities.
- Inductive:These tools detect current flow through electromagnetic induction, often used for identifying live circuits and tracing wires in residential and commercial installations.
Most installed capacity flows through Handheld devices. Expansion is steepest in Non-Contact solutions.
End User:
The end-user landscape for voltage detectors reflects varying levels of market maturity and operational sophistication across different customer groups.
- Utilities:These large-scale operators require robust, high-voltage detectors for transmission and distribution network maintenance, ensuring grid reliability and worker protection. National energy policies in Germany and Japan mandate advanced safety tools for infrastructure upgrades, stimulating demand.
- Contractors:Professional electricians and service providers utilize versatile voltage detectors for installation, repair, and inspection tasks in residential, commercial, and industrial settings. OSHA regulations in the United States and CE marking requirements in Europe directly influence their equipment procurement for lockout/tagout procedures.
- DIY Enthusiasts:Homeowners and hobbyists employ basic, low-voltage detectors for simple household electrical tasks, prioritizing affordability and ease of operation.
- Maintenance Technicians:Industrial and facility maintenance personnel use detectors for equipment troubleshooting and preventative checks, ensuring operational continuity and safety.
Demand for Utilities remains foundational, while Contractors drive innovation.
Technology:
Technological advancements in voltage detectors are directly influenced by the increasing complexity of electrical systems and the need for enhanced diagnostic capabilities.
- Smart:These detectors integrate microprocessors for advanced features like data logging, remote monitoring, and diagnostic capabilities, providing verifiable safety records. Utilities in the UK and Canada adopt smart technologies for compliance with evolving grid management protocols and predictive maintenance programs.
- Wireless:Offering Bluetooth or other wireless connectivity, these devices enable remote readings and integration with mobile applications, enhancing technician safety by maintaining distance from live circuits. The professional contractor segment in Australia and South Korea increasingly procures wireless solutions for improved efficiency and digital audit trails.
- Analog:Representing traditional designs, analog detectors provide basic visual or audible indications of voltage presence, often favored for their simplicity and durability.
- Digital:These devices display precise voltage readings on an LCD screen, offering greater accuracy and quantitative data compared to analog counterparts.
The largest installed base is found within Digital technology, with Wireless experiencing the most significant growth.
Application:
Applications for voltage detectors range from routine checks to critical safety interventions, reflecting the diverse operational demands across industries.
- Safety Inspections:These applications prioritize verifying de-energization before maintenance, crucial for preventing electrical accidents and ensuring compliance with occupational safety standards. OSHA in the United States and the CEA in India mandate rigorous safety protocols, driving demand for verifiable detection tools.
- Electrical Testing:This core application involves checking circuit continuity, identifying live wires, and troubleshooting electrical faults in various installations. The professional contractor market across France and Italy relies on accurate testing tools for daily operational efficiency.
- Maintenance:Voltage detectors support preventative and corrective maintenance routines on electrical equipment, helping to diagnose issues before they escalate.
- Equipment Diagnostics:Specialized detectors assist in identifying specific electrical anomalies or failures within complex machinery and systems, enabling precise fault location.
Core functional requirements are met by Electrical Testing, with evolving needs driving adoption in Safety Inspections.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The foundational demand for electrical safety equipment initially scaled in industrialized nations, particularly in North America and Europe, where early grid expansion and robust safety standards emerged. These regions established initial benchmarks for voltage detection technology and its application in utility and industrial settings. Today, global grid modernization efforts continue to drive advanced detector adoption.
United States
Demand for advanced voltage detectors in the United States stems from ongoing grid infrastructure upgrades and stringent occupational safety mandates. OSHA regulations strictly enforce lockout/tagout procedures, directly influencing equipment procurement by professional contractors. Major utility hubs in Texas and California are implementing smart grid technologies, requiring sophisticated diagnostic tools.
Germany
Grid modernization initiatives in Germany, driven by the EU Green Deal, necessitate high-precision voltage detection for renewable energy integration. CE marking and other European safety standards govern product design and market access for electrical testing equipment. The industrial heartland of Bavaria and North Rhine-Westphalia sees significant adoption for plant safety.
China
Massive investments in power transmission and distribution infrastructure in China create substantial demand for voltage detectors. National energy policies, including dual carbon goals, mandate smart grid upgrades and enhanced safety protocols. Industrial zones in the Yangtze River Delta and Pearl River Delta are key areas for equipment deployment during new construction.
India
Expanding electricity access and upgrading aging infrastructure across India drive foundational demand for voltage detection tools. The Central Electricity Authority (CEA) mandates rigorous safety measures for grid work, compelling utilities and contractors to adopt certified equipment. Major metropolitan areas like Delhi-NCR and Mumbai are witnessing significant infrastructure development.
Japan
Aging infrastructure replacement and the integration of renewable energy sources in Japan fuel demand for reliable voltage detectors. METI guidelines and JIS standards ensure high quality and safety compliance for electrical testing instruments. Utility companies in the Kanto region, including Tokyo, lead in deploying smart and wireless detectors for enhanced operational efficiency.
Voltage Detector Market Key Industry Players
Premium-margin players sit above commodity-margin players across product innovation and compliance with stringent safety standards. The market exhibits a tiered structure, with established global manufacturers dominating the high-end segment for utilities and industrial applications. Mid-tier specialists focus on specific technologies like wireless connectivity, while smaller regional players compete on price for basic handheld devices. Strategic partnerships with grid operators and portfolio diversification into integrated safety solutions are dominant competitive moves.
Within the integrated solutions archetype, Fluke Corporation and Honeywell International Inc. represent companies with strong brand recognition and extensive distribution networks across professional contractor and industrial segments. Fluke Corporation, a US-based entity, anchors the market for portable and precise electrical testing equipment. Honeywell International Inc., a diversified American conglomerate, exemplifies a provider of comprehensive safety solutions for demanding industrial environments. ABB, a Swiss-Swedish multinational corporation, occupies a position among utility-scale power transmission and distribution specialists, offering broad portfolios for critical infrastructure.
| Leading Market Players |
|---|
| Renesas Electronics Corporation |
| Hioki E.E. Corporation |
| Honeywell International Inc. |
| Amprobe co. |
| Megger Ltd. |
| Fluke Corporation |
| ABB |
| UNI-TREND TECHNOLOGY CO. LTD. |
| Analog Devices Inc. |
| Others |
Cost & Logistics Intelligence
Utility and industrial procurement of integrated safety solutions influences a value-based pricing model. This approach prioritizes auditable compliance and risk reduction over initial hardware cost for enterprise customers.
Pricing Analysis
Value-based pricing dominates the high-end segment, where advanced features and verifiable safety records command premium margins. Price differentiation stems from specialized certifications like UL and CE marking, alongside bundled software and training services. Pricing pressure arises from the increasing integration of voltage detection into multifunction testers, leading to potential product cannibalization, particularly for standalone devices. DIY enthusiasts represent the most price-sensitive segment, while utilities prioritize reliability and compliance over initial cost.
Supply Chain Analysis
Component supply for advanced voltage detectors draws from specialized electronics manufacturers in Japan and the United States. Key raw material dependencies include microprocessors, precision sensors, and specialized plastics required for durable casings. A structural risk is single-source vulnerability for highly specialized integrated circuits, impacting production timelines and costs. Downstream distribution runs through established professional electrical supply channels and direct sales to large utility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Voltage Detector Market is transitioning into a late-cycle quality story, driven by a demand-shift toward verifiable, data-backed safety compliance. This necessitates advanced diagnostic capabilities and integrated solutions.
For Market Incumbents: Hedge against product cannibalization by accelerating R&D into integrated, multifunction electrical testers with advanced voltage detection. Invest in securing specialized certifications like UL and BIS to maintain market access and competitive positioning in regulated markets. Deepen channel control with major utilities and professional contractor networks by offering comprehensive safety solution contracts that emphasize lifecycle value.
For New Entrants and Emerging Players: Specialized electrical distributors represent a viable entry point for innovative wireless and smart detector solutions. Target underpenetrated geographies in Southeast Asia and Africa, where grid infrastructure is developing rapidly and safety mandates are emerging. Focus on offering IoT and software integration for automated safety logging, providing a distinct value proposition to enterprise customers.
For Investors and Strategic Acquirers: Diversified industrial conglomerates are the most active acquirers in this space, seeking to expand their integrated safety solution portfolios. Long-term viability hinges on companies that can provide verifiable compliance and enhance operational efficiency through data-capable devices and software. The signal to watch is the adoption rate of cloud-integrated safety platforms by major utility companies, indicating a shift in procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Development for High-Voltage DC | Addresses the unique safety requirements of the growing renewable energy sector. |
| Software Integration for Data Logging | Enhances compliance and operational efficiency for utilities through auditable safety records. |
| Strategic Partnerships with Grid Operators | Secures long-term contracts and market access within the foundational utilities segment. |
| Investment in CE Marking and BIS Certification | Ensures market entry and competitive advantage in highly regulated European and Indian markets. |
| Expansion into Southeast Asian Markets | Captures early growth opportunities in regions with developing electrical infrastructure. |
Research Approach
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core for this market study. Primary interviews with utility engineers, professional contractors, R&D leads, and regulatory body representatives provided critical qualitative insights. Secondary validation drew from national energy policies, IEC standards, OSHA reports, and company financial filings. This dual approach ensured comprehensive data triangulation.
An input-output matrix framework underpinned the quantitative analysis, integrating various market dynamics across the modeling period. Segmentation dimensions included product type, end-user, technology, application, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected future demand. Key forecast inputs included smart grid investment levels and renewable energy capacity additions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving safety standards and the pace of grid modernization. These projections reflect assumptions regarding technological adoption and policy stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
Transient Voltage Suppressor (TVS) Diode Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Global Surge Protection Devices Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Moisture Detection Stickers Market
Detection and Regulation Devices
Temperature Detection Screen Market
Detection and Regulation Devices
Gas Detectors Market
Detection and Regulation Devices
Handheld Optical Gas Imaging Camera Market
Detection and Regulation Devices
Audio Signaling Devices Market
Detection and Regulation Devices
Global Gas Leak Detectors Market