
 Frequency Counter Market | 2026-2036
Frequency Counter Market Size, Share, and Industry Trends Forecast 2026-2036
Frequency Counter Market Analysis
Software-defined calibration and remote diagnostics is shifting how vendors monetize frequency counter deployments. Keysight Technologies leverages its R&D intensity to anchor premium benchtop portfolios across North American research labs. Rohde & Schwarz sustains manufacturing scale advantages in European telecommunications test environments. Stanford Research Systems specializes in time-interval analysis architectures for quantum research buyers.
A frequency counter measures the number of cycles per second in an electronic signal, typically operating from millihertz to tens of gigahertz with resolution down to fractional hertz through gate-time averaging and interpolation algorithms. Its primary purpose is precision signal characterization in calibration laboratories, broadcast transmitters, and semiconductor wafer test stations. Benchtop configurations dominate margin pools in aerospace and defense procurement channels, while handheld units compete on channel density for field technicians in telecommunications. Pulse counting technology leads in mature industrial automation settings, whereas time interval analysis commands premium positioning in research and development applications.
The FCC equipment authorization framework governs electromagnetic compatibility testing that frequency counters support in United States telecommunications certification. ISO/IEC 17025 laboratory accreditation standards shape metrological traceability requirements that instrument vendors must satisfy for defense and automotive supplier qualification. Buyers should monitor how spectrum allocation rulings from national regulators in Germany, Japan, and South Korea redirect demand toward higher-frequency measurement architectures.
Market Dynamics
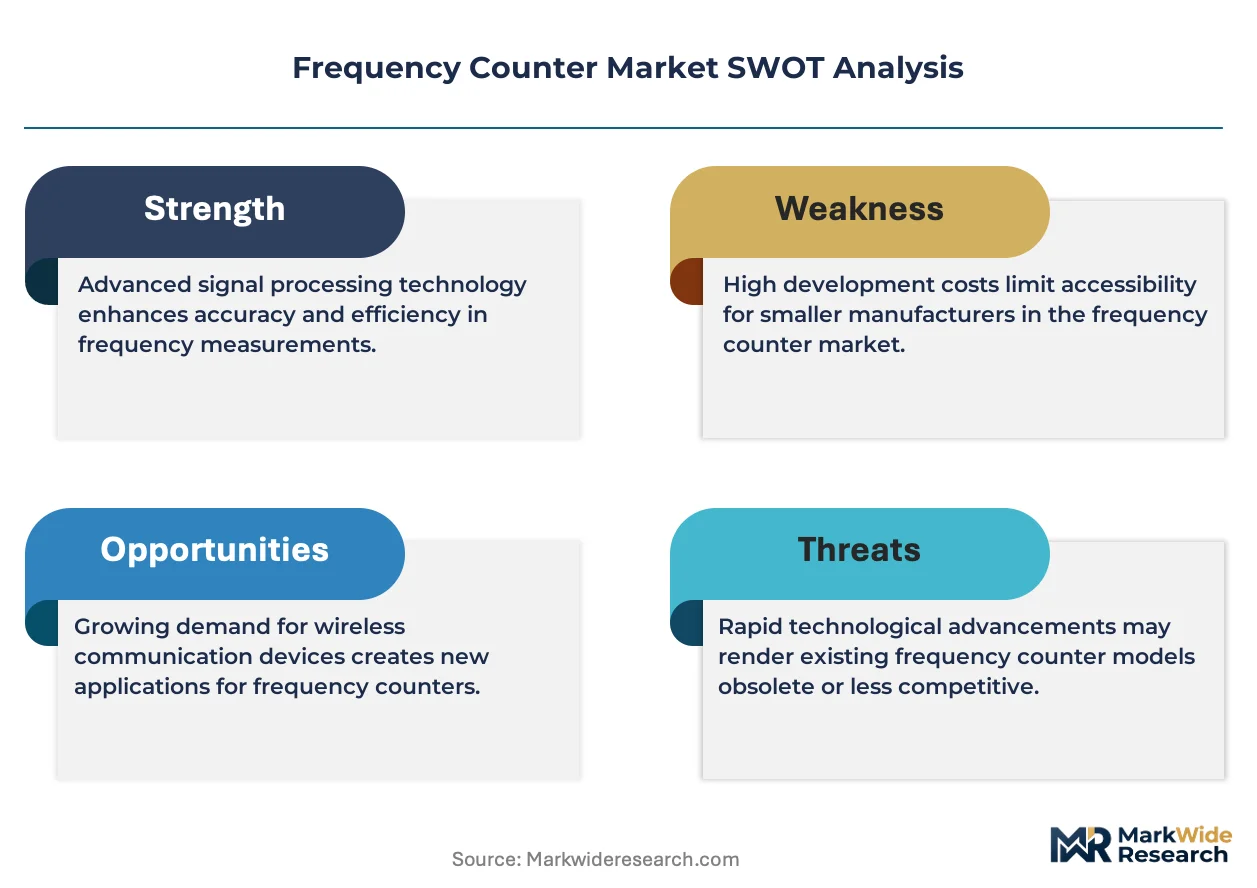
Telecommunications infrastructure modernization is compressing replacement cycles for precision measurement equipment, while software-defined architectures enable remote calibration services that reshape vendor-customer relationships.
Growth Catalysts
- 5G network densification:Base station deployments in South Korea and Japan require field-portable frequency counters for real-time signal verification.
- ISO/IEC 17025 accreditation mandates:Metrology laboratories in Germany must upgrade instrumentation to maintain defense supplier qualification status.
- Quantum computing research:Time-interval analysis architectures command premium positioning as national labs in the United States expand qubit characterization programs.
Market Restraints
- High-purity oscillator supply concentration:Precision crystal manufacturing clusters in Switzerland and Japan create single-source vulnerability for sub-picosecond resolution instruments.
- FCC equipment authorization complexity:Electromagnetic compatibility testing protocols extend product launch timelines for benchtop configurations.
- Software-defined radio substitution:General-purpose vector signal analyzers capture mid-range frequency measurement applications previously served by dedicated counters.
Strategic Opportunities
- India's semiconductor test expansion:PLI scheme incentives for domestic chip fabrication create demand for wafer-level frequency characterization stations.
- Automotive radar validation:77-81 GHz module testing for advanced driver-assistance systems opens new end-use verticals beyond traditional telecommunications.
- Cloud-connected diagnostics:Subscription-based remote calibration services monetize installed base while reducing field service dispatch costs.
Industry Challenges
- Specialized firmware engineering scarcity:Gate-time averaging algorithm development requires rare expertise combining digital signal processing with precision timing physics.
- Multi-standard certification stacking:Simultaneous CE marking, FCC authorization, and BIS registration for Indian market entry strain quality assurance bandwidth.
- Legacy GPIB interface integration:Automated test equipment environments in aerospace maintain decades-old bus architectures that constrain modern USB-C and Ethernet-native designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frequency Counter Market |
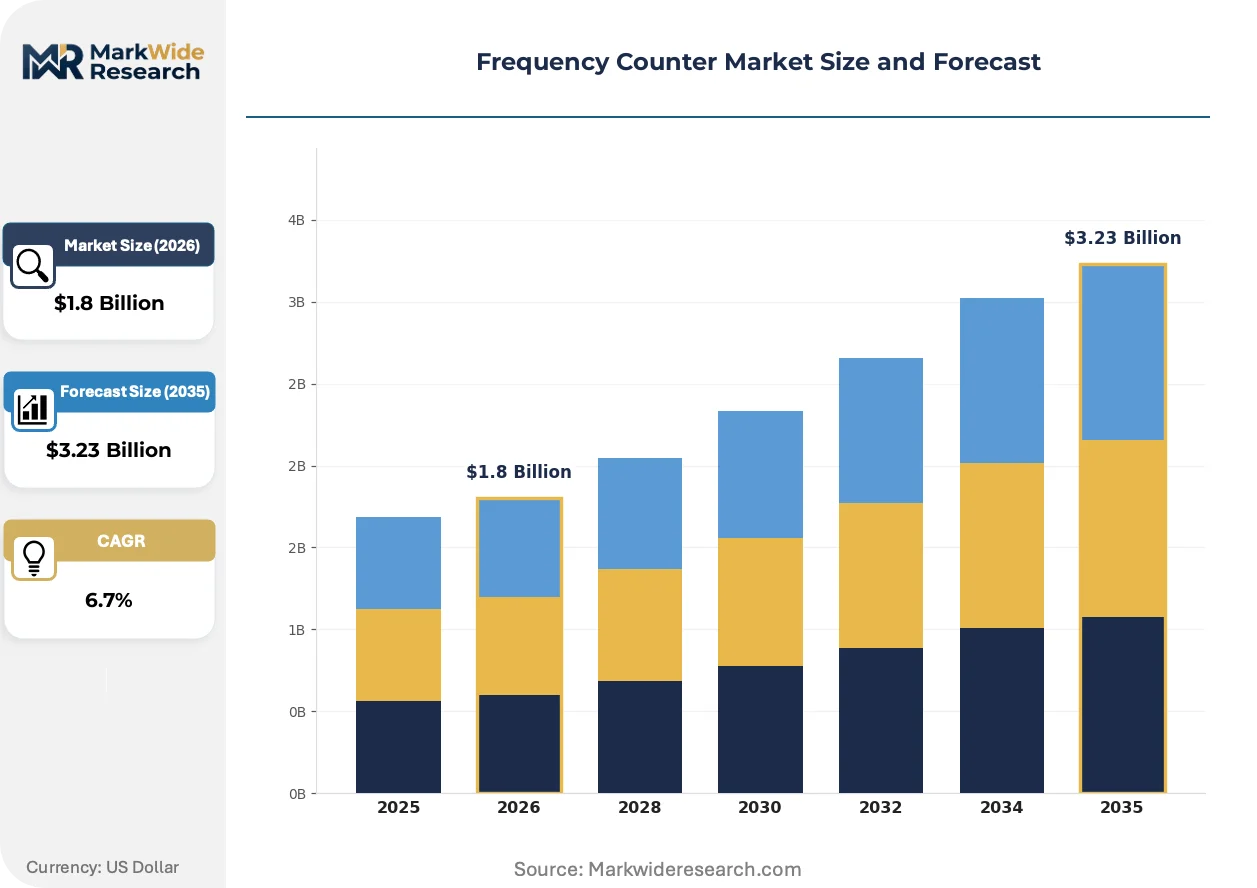
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Benchtop, Digital, Analog End User: Telecommunications, Aerospace, Automotive, Education Technology: Direct Frequency Synthesis, Pulse Counting, Spectrum Analyzing, Time Interval Analysis Application: Signal Testing, Frequency Measurement, Function Generation, Research & Development |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, B&K Precision Corporation, National Instruments, Anritsu, Stanford Research Systems, Berkeley Nucleonics Corporation, Tektronix, OMRON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frequency Counter Market Emerging Trajectories
Measurement architectures are converging around software-defined platforms that separate hardware acquisition from analysis layers, enabling feature updates without instrument replacement.
Direct digital synthesis technology is consolidating frequency generation and counting functions into unified signal processing chains. Research laboratories in the United States adopt these integrated architectures to reduce rack space and simplify system synchronization. The consolidation is compressing demand for standalone function generators in favor of multi-instrument modules.
REACH substance restrictions on lead-based solders and cadmium-plated shielding are forcing component redesigns across European supply chains. Instrument vendors must qualify alternative thermal interface materials and conformal coatings without degrading phase noise specifications. German precision manufacturers are responding fastest, leveraging existing green chemistry expertise from automotive sector compliance programs.
Buying committees now unbundle hardware acquisition from calibration service contracts, treating metrology traceability as a separable procurement category. Systems integrators in Japan's telecommunications sector lead this shift, negotiating multi-year calibration subscriptions independent of initial capital expenditure. The practice is spreading to South Korean semiconductor fabs seeking operational expenditure predictability.
Frequency Counter Market Segmentation
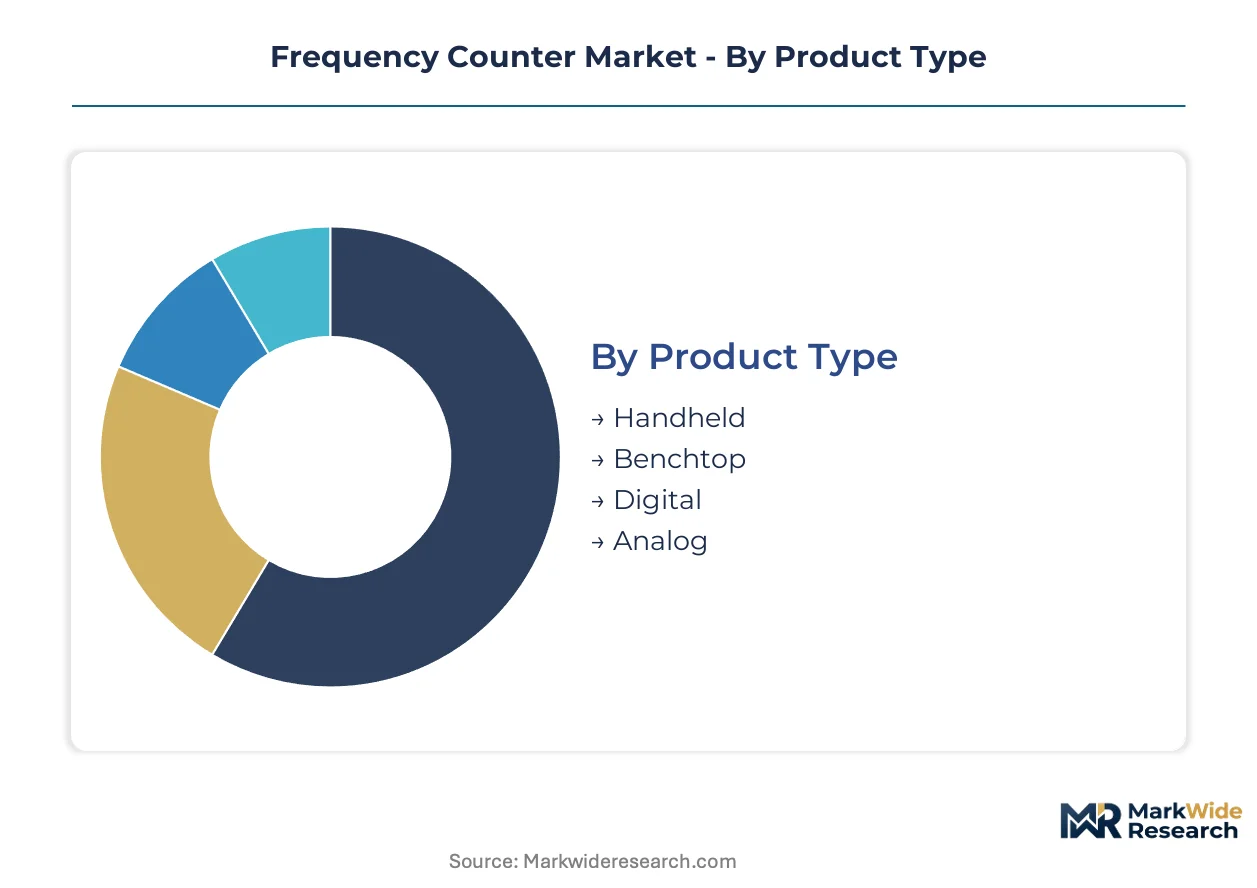
Frequency counter procurement varies sharply by deployment environment, with benchtop units commanding aerospace qualification premiums while handheld configurations compete on channel density for telecommunications field crews. Understanding these segment boundaries clarifies how vendors allocate R&D resources across precision tiers and end-use certifications.
Product Type:
Buyers select form factor based on portability requirements versus measurement precision, with calibration traceability needs often overriding upfront cost considerations.
- Benchtop:Rack-mounted instruments integrate oven-controlled crystal oscillators achieving sub-picosecond resolution for metrology laboratories and semiconductor wafer test stations. ISO/IEC 17025 accreditation mandates in Germany's precision instrumentation cluster around Munich and Berlin sustain replacement demand for these high-margin units.
- Handheld:Battery-powered designs prioritize channel density and field durability for base station technicians performing real-time signal verification. 5G network densification in South Korea and Japan accelerates procurement cycles for these portable configurations.
- Digital:Microprocessor-based architectures with LCD interfaces dominate mid-range industrial automation settings where GPIB bus compatibility remains essential.
- Analog:Vacuum fluorescent display units persist in legacy aerospace test environments requiring decades-long maintenance support.
Benchtop leads on scale; handheld leads on momentum.
End User:
Application-specific certification requirements fragment demand, with defense supplier qualification status filtering vendor eligibility across aerospace and telecommunications procurement channels.
- Telecommunications:Equipment manufacturers and network operators require field-portable and rack-mounted units for electromagnetic compatibility testing under FCC authorization frameworks. Infrastructure modernization compresses replacement cycles as carriers validate 5G signal integrity.
- Aerospace:Defense contractors and satellite manufacturers demand benchtop configurations with extended temperature ranges and shock-hardened enclosures. MIL-STD-810 qualification requirements sustain premium pricing for qualified suppliers.
- Automotive:Radar module suppliers for advanced driver-assistance systems validate 77-81 GHz frequency stability, opening new demand beyond traditional RF test applications.
- Education:University laboratories and technical training institutes prioritize cost-optimized digital units for undergraduate instruction in electronic engineering programs.
Telecommunications leads on scale; automotive leads on momentum.
Technology:
Measurement architecture selection determines resolution limits and software upgrade pathways, with algorithm sophistication separating research-grade from industrial-grade procurement tiers.
- Time Interval Analysis:Interpolation algorithms achieve fractional hertz resolution through gate-time averaging, serving quantum computing research programs at United States national laboratories characterizing qubit coherence times.
- Pulse Counting:Mature digital logic architectures dominate factory automation and process control environments where millihertz precision satisfies monitoring requirements.
- Direct Frequency Synthesis:Integrated signal generation and measurement chains consolidate rack space for research laboratories adopting software-defined instrument platforms.
- Spectrum Analyzing:FFT-based architectures capture frequency-domain characterization needs previously served by dedicated counters, competing for mid-range applications against standalone frequency counters.
Time Interval Analysis leads on scale; Direct Frequency Synthesis leads on momentum.
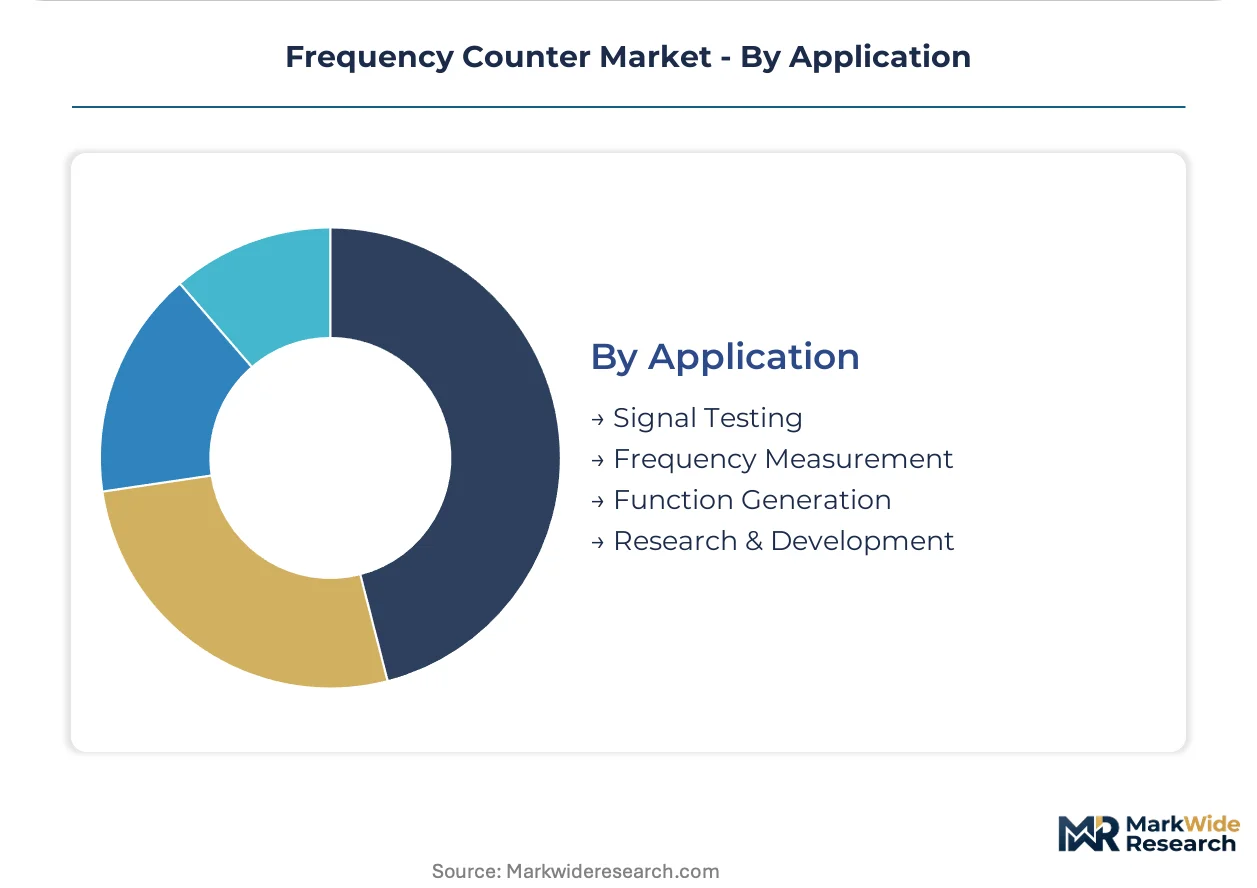
Application:
Workflow integration requirements shape instrument specification, with automated test equipment environments demanding legacy interface compatibility that constrains modern hardware designs.
- Research & Development:National laboratories and corporate innovation centers specify time-interval analysis architectures with remote diagnostics capability for distributed quantum computing programs.
- Signal Testing:Broadcast transmitter maintenance and telecommunications certification require calibrated traceability to national standards, sustaining demand for accredited metrology services.
- Frequency Measurement:Calibration laboratories and manufacturing test stations perform routine oscillator characterization, representing steady replacement demand.
- Function Generation:Integrated signal source applications consolidate into multi-instrument modules, compressing standalone demand as direct digital synthesis technology matures.
Signal Testing leads on scale; Research & Development leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision instrumentation cluster sustains higher replacement rates than Japan's telecommunications test environment, though both markets demand ISO/IEC 17025-accredited metrology traceability. South Korea and India are accelerating procurement through semiconductor fabrication incentives, while the United States anchors quantum research applications. Switzerland's oscillator manufacturing concentration creates supply-side dependencies across all regions.
United States
National laboratories in California and New Mexico expand qubit characterization programs requiring time-interval analysis architectures. FCC equipment authorization rules govern electromagnetic compatibility testing protocols for telecommunications certification. Boston's research corridor and Austin's semiconductor test cluster sustain demand for benchtop configurations with remote diagnostics capability.
Germany
Defense supplier qualification mandates under ISO/IEC 17025 drive metrology laboratory upgrades in precision manufacturing regions. REACH substance restrictions on lead-based solders force component redesigns across instrument supply chains. Munich and Berlin host the dominant European cluster for oven-controlled crystal oscillator integration into sub-picosecond resolution instruments.
Japan
5G network densification compresses replacement cycles for field-portable frequency counters serving base station technicians. METI standards shape domestic electromagnetic compatibility testing requirements for telecommunications equipment manufacturers. Tokyo-Osaka industrial corridor buyers unbundle hardware acquisition from calibration service contracts, treating metrology traceability as separable procurement.
South Korea
Semiconductor wafer test station expansion creates demand for high-channel-density digital frequency counters in domestic fabrication facilities. MFDS-equivalent technical regulations align with international metrology standards for export-oriented electronics manufacturers. Seoul Capital Area and Busan-Ulsan electronics clusters prioritize software-defined architectures enabling remote calibration services.
India
PLI scheme incentives for domestic chip fabrication generate procurement demand for wafer-level frequency characterization stations. BIS registration requirements strain quality assurance bandwidth for multi-standard certification stacking. Karnataka and Telangana semiconductor test facilities represent the fastest-growing end-use vertical beyond traditional telecommunications applications.
Frequency Counter Market Vendor Landscape
Top-tier vendors anchor premium benchtop portfolios, while mid-tier specialists compete on channel density for telecommunications field crews. The vendor base stratifies across three tiers: precision metrology incumbents with R&D-intensive product lines, telecommunications test equipment generalists with manufacturing scale advantages, and quantum research specialists with time-interval analysis expertise. M&A activity concentrates on software-defined calibration capabilities, while strategic partnerships target cloud-connected diagnostics platforms.
Within the precision metrology tier, Keysight Technologies and Rohde & Schwarz exemplify divergent geographic anchoring strategies. Keysight occupies a position representative of North American research lab penetration, while Rohde & Schwarz sits within the European telecommunications test archetype. Stanford Research Systems represents the quantum research specialist model with time-interval analysis positioning.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| B&K Precision Corporation |
| National Instruments |
| Anritsu |
| Stanford Research Systems |
| Berkeley Nucleonics Corporation |
| Tektronix |
| OMRON Corporation |
| Others |
Supply Flow & Price Mechanics
REACH substance restrictions on lead-based solders and cadmium-plated shielding gate both qualified European supply and premium-tier pricing access for oven-controlled crystal oscillator integration. German precision manufacturers leverage existing green chemistry expertise to capture margin premiums while competitors face qualification delays.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for mid-range digital frequency counters as domestic semiconductor test expansion creates localized procurement competition. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 17025-accredited benchtop units from field-portable handheld configurations and industrial automation digital models. Cost compression in standard-tier instruments is intensifying because software-defined radio substitution erodes dedicated counter demand. Education sector buyers exhibit highest price sensitivity, while aerospace defense contractors accept premium positioning for MIL-STD-810 qualification.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and Japan anchor hub-and-spoke patterns for precision oscillator components and final instrument assembly. High-purity crystal manufacturing draws from Swiss and Japanese clusters, while conformal coating and thermal interface materials feed from German chemical suppliers. Single-source vulnerability for sub-picosecond resolution instruments creates structural risk if geopolitical disruption affects Swiss oscillator exports. Distribution runs through authorized metrology distributors serving calibration laboratories and direct OEM relationships for semiconductor test station integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on cloud-connected calibration services transforming capital expenditure into recurring revenue, while REACH compliance investments filter out sub-scale competitors.
For Market Incumbents: Deepen software-defined calibration capabilities to defend against general-purpose vector signal analyzer substitution in mid-range applications. Prioritize backward integration into precision oscillator supply through strategic partnerships with Swiss manufacturers to reduce single-source exposure. Fortify ISO/IEC 17025 accreditation maintenance as defense supplier qualification status becomes the primary vendor filter in German procurement channels. For New Entrants and Emerging Players: Capture India's semiconductor test expansion under PLI scheme incentives before incumbent distribution networks solidify. Target wafer-level frequency characterization stations in Karnataka and Telangana where BIS registration complexity strains established quality assurance bandwidth. Pursue channel partnerships with domestic systems integrators rather than direct sales to navigate multi-standard certification stacking. For Investors and Strategic Acquirers: Valuations sit cheapest among quantum research specialists with time-interval analysis expertise as national laboratory funding accelerates. Long-term viability favors vendors with software-defined architectures enabling subscription-based remote diagnostics monetization. Watch for spectrum allocation rulings from German, Japanese, and South Korean regulators as the inflection signal redirecting demand toward higher-frequency measurement architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Diagnostics Platform | Transforms hardware margins into recurring calibration subscription revenue streams. |
| REACH Compliance Certification | Qualifies vendors for German precision instrumentation cluster procurement access. |
| Time-Interval Analysis R&D Investment | Positions suppliers for United States national laboratory qubit characterization programs. |
| Semiconductor Test Channel Partnership | Captures India's PLI-driven wafer-level frequency characterization station demand. |
| Multi-Standard Certification Stacking | Accelerates market entry across FCC, CE marking, and BIS registration jurisdictions. |
Methodological Framework
Direct dialogue with frequency counter product managers, metrology laboratory directors, semiconductor test engineers, and telecommunications procurement officers grounded qualitative findings. Secondary validation drew from FCC equipment authorization databases, ISO/IEC 17025 accreditation registries, SEC filings of listed test equipment vendors, and Indian PLI scheme beneficiary disclosures. Bottom-up demand modeling across end-use verticals triangulated against top-down market sizing from instrument shipment tracking.
Unit and value projections across the analysis window reflect econometric modeling of 5G infrastructure capex cycles, semiconductor fabrication capacity expansion, and quantum research funding appropriations. Segmentation dimensions include product type, end user, measurement technology, and application workflow integration. CAGRs were derived from regression analysis of historical replacement cycle compression and technology substitution elasticities, incorporating REACH compliance cost pass-through and software-defined architecture adoption curves.
Regulatory delay in FCC equipment authorization, oscillator supply disruption from Swiss manufacturing concentration, and faster-than-expected software-defined radio substitution are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Spark Detector Market
Detection and Regulation Devices
EMEA Frequency Control and Timing Devices Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
X-Ray Detectors Market
Detection and Regulation Devices
Digital Attenuators Market
Detection and Regulation Devices
Arc Fault Detection Market
Detection and Regulation Devices
IR Detector Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Noise Monitoring Device Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Active Buzzer Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market