
 Global Hybrid Vehicle Transmission Market | 2026-2036
Global Hybrid Vehicle Transmission Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hybrid Vehicle Transmission Market Outlook
ISO 26262 functional safety certification is unwinding competitive access across electrified powertrain supply chains, forcing tier-one suppliers to absorb multi-year qualification cycles before securing platform nominations. Aisin Seiki Co. Ltd. leverages captive integration with Toyota's hybrid architecture to sustain dominant share in planetary gear-set e-CVT production. ZF Friedrichshafen AG anchors European supply through its 800-volt-compatible hybrid transmission family, while BorgWarner Inc. competes via modular P2 hybrid modules that retrofit existing front-wheel-drive platforms.
A hybrid vehicle transmission couples an internal combustion engine with one or more electric motors through a torque-splitting or clutch-managed geartrain, typically operating at system voltages between 48V and 800V depending on architecture class. The assembly modulates mechanical and electrical power paths to optimize thermal efficiency across variable load cycles, with multi-plate wet clutches and hollow-shaft motor designs enabling packaging within standard transaxle envelopes. Parallel Hybrid systems occupy the largest installed base among product type categories, reflecting two decades of Toyota and Honda production scale. Plug-in Hybrid configurations represent the fastest-expanding margin pool, as larger battery capacities demand reinforced torque converter lockup strategies and expanded electric-only speed ranges. DCT technology leads technology segment growth for performance-oriented applications where rapid shift speed preserves driver engagement during blended power transitions.
EPA corporate average fuel economy standards and California Air Resources Board zero-emission vehicle mandates directly shape OEM transmission procurement specifications, pushing suppliers toward electrified ratios above 40 kW electric contribution. EMA's evolving requirements for electrified vehicle type approval in Europe, alongside China's MIIT NEV credit thresholds, create divergent compliance targets that fragment platform engineering budgets. Stakeholders must monitor how battery-electric range extension in plug-in architectures reshapes transmission ratio spread requirements and clutch duty cycles.
Market Dynamics
ISO 26262 functional safety certification is compressing supplier qualification timelines and forcing tier-one transmission manufacturers to absorb multi-year engineering cycles before securing platform nominations from electrified powertrain programs.
Growth Catalysts
- EPA Corporate Average Fuel Economy Standards:OEM procurement specifications now mandate electrified powertrain ratios above 40 kW electric contribution, redirecting transmission engineering budgets toward hybrid architectures.
- China's MIIT NEV Credit Thresholds:Updated dual carbon goals and credit rules are redirecting supplier investment toward electrified powertrain architectures in the world's largest automotive production base.
- 48V Mild-Hybrid Proliferation:Belt-integrated starter-generator systems are expanding addressable market volume by retrofitting existing internal combustion platforms without full powertrain redesign.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium processing capacity concentrates in China's Inner Mongolia and Jiangxi provinces, exposing motor manufacturers to export quota volatility.
- Multi-Plate Wet Clutch Cost Structure:Friction material formulations containing copper and advanced resin binders face input cost pressure from mining supply constraints and chemical feedstock inflation.
- Power Semiconductor Shortage:Silicon carbide and IGBT module availability remains constrained, limiting 800V transmission production scaling for performance hybrid applications.
Strategic Opportunities
- India's FAME-II Subsidy Extension:The country's heavy industry incentive scheme creates procurement pull for localized hybrid transmission assembly serving domestic OEM electrification roadmaps.
- Commercial Fleet Electrification:North American freight operators are expanding hybrid truck procurement as state-level fuel-efficiency mandates tighten beyond federal baselines.
- Dual-Clutch Hybrid Convergence:Integration of P2 motor modules with seven-speed DCT geartrains enables packaging efficiency gains for European performance vehicle segments.
Industry Challenges
- Functional Safety Engineering Talent Scarcity:ISO 26262 ASIL-D certification expertise concentrates at Aisin Seiki and ZF Friedrichshafen, forcing mid-tier suppliers into expensive external consultancy engagements.
- Legacy Platform Integration Complexity:Retrofitting electrified transmissions into existing front-wheel-drive architectures requires hollow-shaft motor designs that conflict with established transaxle packaging envelopes.
- Powertrain Software Stack Harmonization:Torque-splitting algorithms must synchronize across engine control modules, motor inverters, and battery management systems, extending validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hybrid Vehicle Transmission Market |
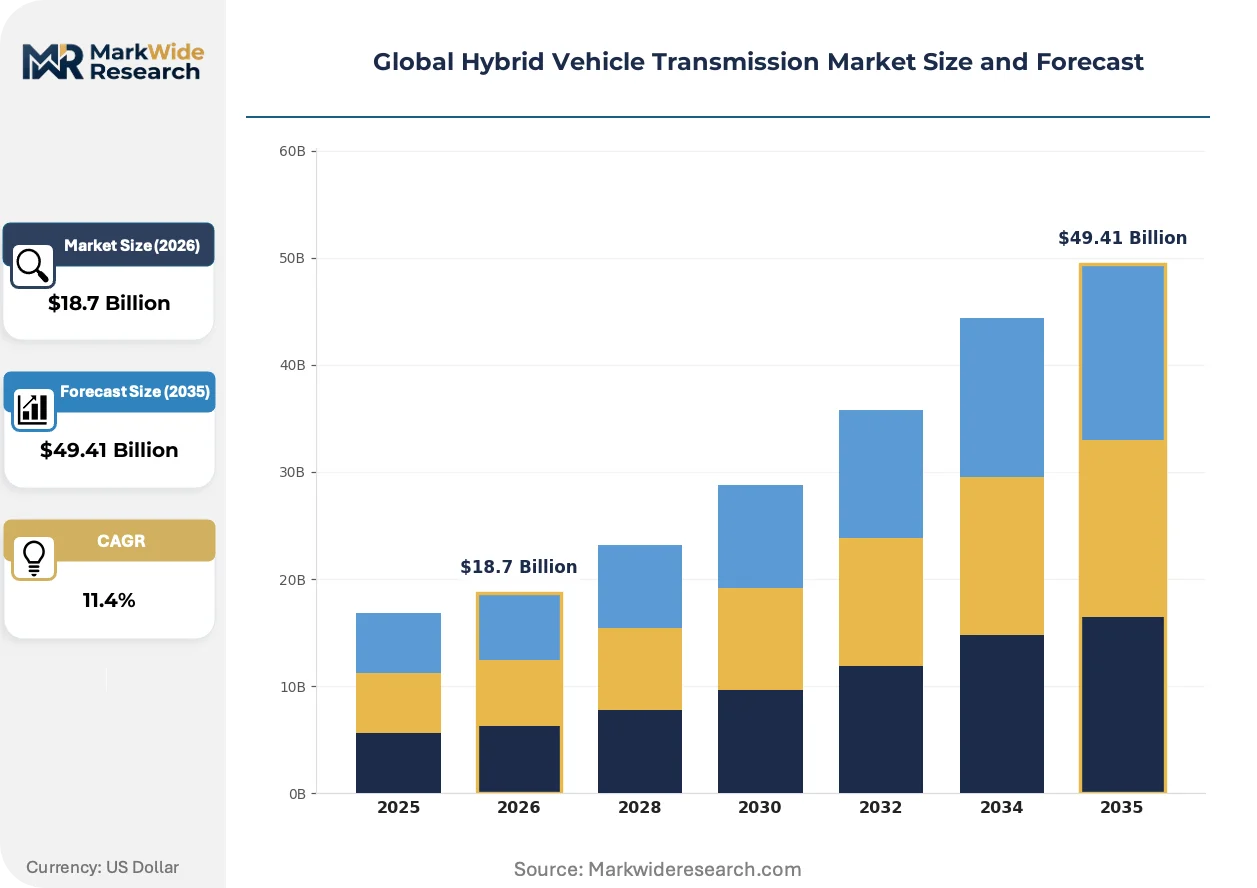
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CVT, AMT, DCT, Torque Converter Product Type: Parallel Hybrid, Series Hybrid, Plug-in Hybrid, Mild Hybrid End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Aisin Seiki Co. Ltd., ZF Friedrichshafen AG, BorgWarner Inc., Schaeffler AG, Allison Transmission Holdings Inc., Hyundai Transys Inc., JATCO Ltd., Magna International Inc., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hybrid Vehicle Transmission Market Strategic Shifts
Electrified powertrain architectures are compressing mechanical complexity while expanding software-defined torque management, reshaping how transmission suppliers allocate R&D resources across hardware and control systems.
Integrated e-axle modules combining motor, inverter, and reduction gear within a single housing are displacing discrete component sourcing for dedicated hybrid electric vehicle platforms. European OEMs are adopting these units at accelerating pace for C-segment and D-segment vehicle lines. This consolidation is miniaturizing packaging envelopes while eliminating intermediate shafts and couplings previously required in multi-source architectures.
China's MIIT has tightened NEV credit calculation methodologies to favor longer electric-only range thresholds, directly altering transmission ratio spread requirements for plug-in hybrid programs. Suppliers must now engineer expanded electric-only speed ranges above 130 km/h without mechanical engine engagement. PHEV architectures destined for the Chinese domestic market are responding with reinforced torque converter lockup strategies and expanded battery thermal management integration.
Fleet procurement departments are unbundling powertrain service contracts from vehicle acquisition agreements, creating direct commercial relationships with transmission remanufacturers and aftermarket software calibration providers. This disintermediation of traditional dealer service networks is most visible in North American commercial vehicle segments where total cost of ownership calculations dominate procurement criteria. Independent service chains are capturing preventive maintenance revenue previously retained by OEM captive finance operations.
Global Hybrid Vehicle Transmission Market Segmentation
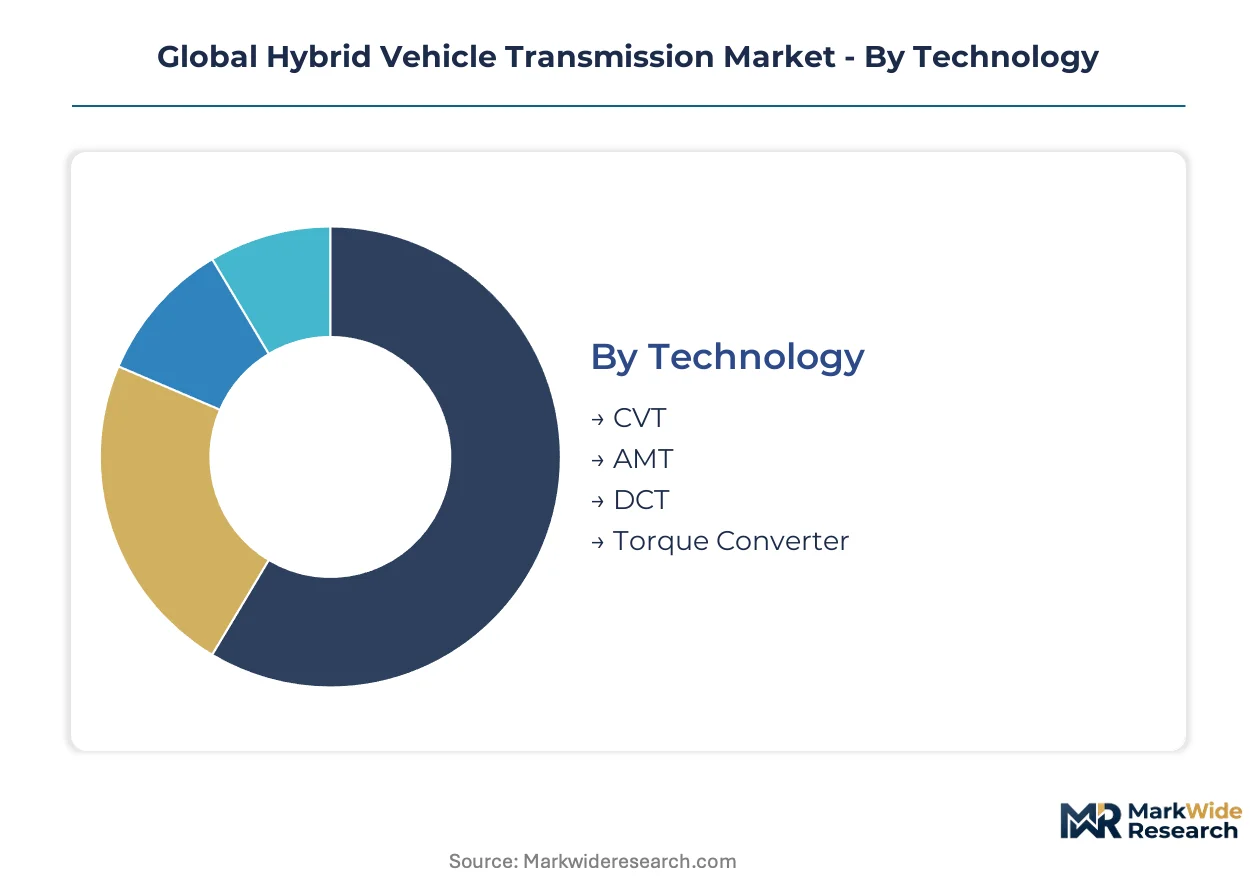
Segmentation in hybrid vehicle transmission markets reveals how regulatory pressure and electrification architecture choices split procurement specifications across incompatible engineering pathways. Understanding these divisions exposes where supplier R&D budgets concentrate and which compliance frameworks dominate platform nominations.
Technology:
EPA fuel-economy mandates and China's MIIT dual carbon thresholds are fragmenting transmission technology procurement, with each regulator favoring distinct efficiency-validation test cycles that reward different geartrain architectures.
- DCT:Dual-clutch architectures deliver sub-100-millisecond shift speeds that preserve driver engagement during blended power transitions. European OEMs in Germany and France are concentrating procurement here for performance C-segment and D-segment lines, driven by WLTP test cycle requirements that penalize torque interruption. DCT handles the majority of throughput; Torque Converter is the fastest mover on share.
- CVT:Continuously variable ratios via planetary gear-sets or pulley systems optimize thermal efficiency across variable load cycles without discrete shift events. Japan's Aichi Prefecture anchors concentrated demand, with Toyota City's engineering density sustaining dominant production scale for hybrid-optimized e-CVT variants.
- AMT:Automated manual transmissions use electromechanical actuators to eliminate clutch pedal operation while retaining dry-clutch efficiency.
- Torque Converter:Lockup clutch strategies in conventional automatic architectures are being reinforced for plug-in hybrid electric-only speed range expansion.
Cost tier differentiation separates premium multi-clutch DCT systems from value-engineered AMT variants serving emerging market price points.
Product Type:
Architecture classification determines battery capacity integration depth and electric-only operating envelope, with Chinese NEV credit rules and California ZEV mandates pulling development in divergent directions.
- Parallel Hybrid:Mechanical and electrical power paths operate simultaneously through torque-splitting geartrains, with the internal combustion engine and electric motor both capable of direct wheel propulsion. Two decades of Toyota and Honda production scale in Japan and the US have built the largest installed base here, though EPA standards now mandate higher electric contribution ratios that strain legacy architectures.
- Plug-in Hybrid:Expanded battery capacities enable 50+ km electric-only ranges, demanding reinforced torque converter lockup strategies and transmission ratio spreads supporting 130+ km/h speeds without engine engagement. China's MIIT tightened credit calculations now favor these longer thresholds, redirecting supplier engineering toward PHEV-optimized geartrains.
- Series Hybrid:The internal combustion engine operates exclusively as a generator, with electric motors providing sole propulsion torque.
- Mild Hybrid:48V belt-integrated starter-generator systems retrofit existing internal combustion platforms without full powertrain redesign, expanding addressable volume in cost-sensitive segments.
Parallel Hybrid retains volume leadership across production lines; Plug-in Hybrid is gaining share fastest as credit thresholds tighten.
End User:
Procurement authority fragmentation is reshaping commercial relationships, with fleet operators unbundling service contracts from vehicle acquisition and creating direct supplier linkages.
- OEMs:Original equipment manufacturers specify transmission architectures during platform development, with ISO 26262 functional safety certification requirements compressing tier-one supplier qualification timelines into multi-year cycles before securing nominations.
- Fleet Operators:North American freight operators are expanding hybrid truck procurement as state-level fuel-efficiency mandates in California and New York tighten beyond federal EPA baselines, with total cost of ownership calculations dominating sourcing decisions.
- Aftermarket Providers:Independent remanufacturers and software calibration specialists are capturing preventive maintenance revenue previously retained by OEM captive finance operations.
- Dealerships:Traditional dealer service networks face disintermediation as procurement departments centralize powertrain service contract negotiations.
OEMs dominate specification authority; Fleet Operators are expanding procurement fastest as commercial electrification accelerates.
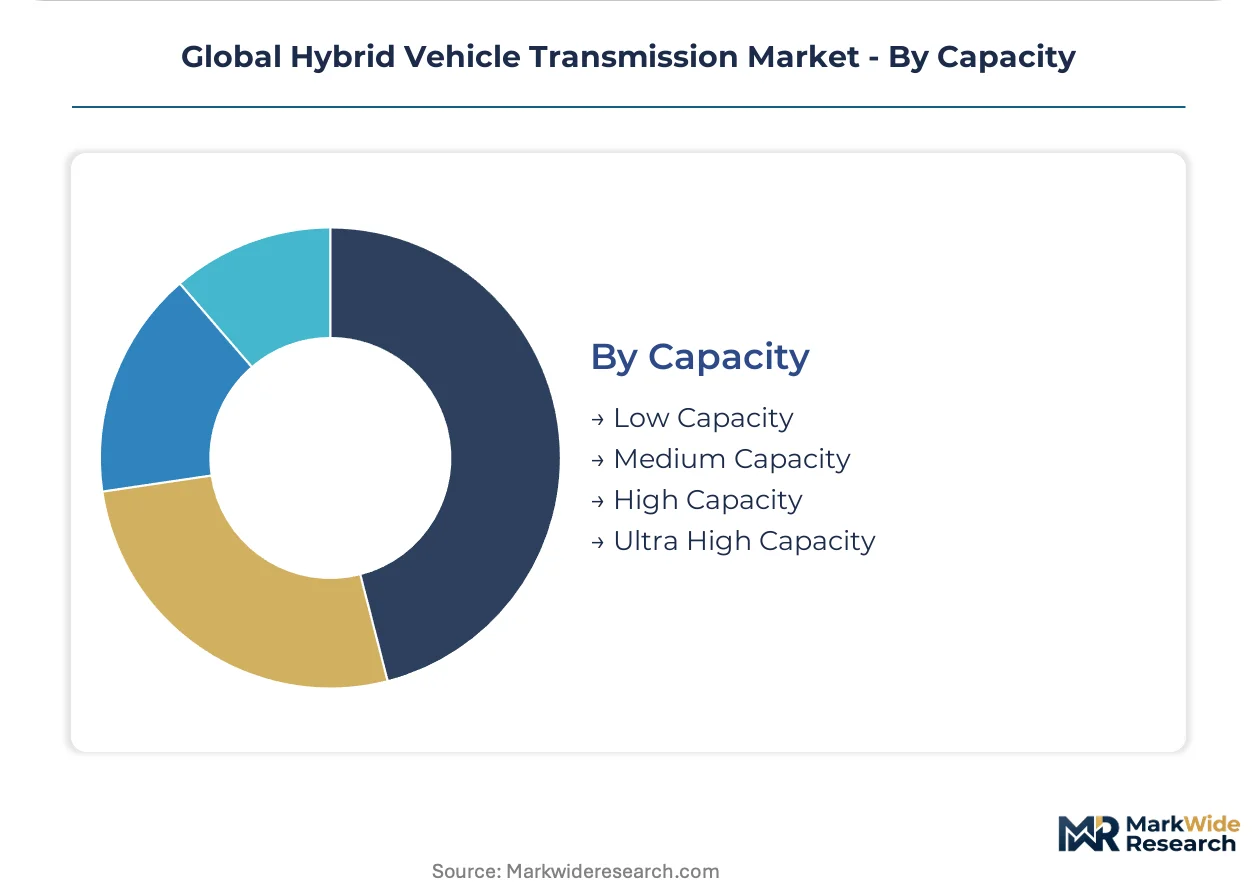
Capacity:
Vehicle weight class and towing requirements segment torque-handling specifications, with commercial applications driving divergence from passenger car architectures.
- Medium Capacity:Transmissions rated for C-segment and D-segment passenger vehicles with system voltages between 200V and 400V represent the core volume segment, with ZF Friedrichshafen's 800-volt-compatible family now pressuring this tier from above.
- High Capacity:Heavy-duty pickup and commercial van applications require reinforced clutch packs and expanded cooling circuits to manage sustained torque loads. North American fleet procurement in Michigan and Texas is concentrating demand here as state-level mandates tighten.
- Low Capacity:A-segment and B-segment urban vehicles prioritize packaging efficiency over absolute torque capacity.
- Ultra High Capacity:Class 4-8 commercial trucks demand specialized architectures with integrated thermal management for continuous-duty cycles.
Medium Capacity carries the highest unit volume; High Capacity is climbing fastest as commercial fleet electrification expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT dual carbon goals and updated NEV credit rules are redirecting supplier investment toward electrified powertrain architectures. Fleet operators across the United States are expanding hybrid truck procurement as fuel-efficiency mandates tighten. Demand concentrates in Japan's Aichi Prefecture, where Toyota City anchors concentrated transmission engineering and tier-one supplier density.
China
Domestic OEM electrification roadmaps are accelerating PHEV platform development to capture MIIT credit thresholds favoring longer electric-only ranges. The country's updated NEV credit calculation methodologies now require transmissions supporting 130 km/h speeds without engine engagement. Yangtze River Delta manufacturing clusters around Shanghai host concentrated supplier engineering centers optimizing ratio spreads for these specifications.
United States
North American freight operators are expanding hybrid truck procurement as California and New York state-level mandates tighten beyond federal EPA baselines. EPA corporate average fuel economy standards now mandate electrified powertrain ratios above 40 kW electric contribution. Michigan and Texas industrial corridors concentrate demand for high-capacity transmissions serving heavy-duty pickup and commercial van applications.
Germany
European OEM procurement specifications favor dual-clutch architectures delivering sub-100-millisecond shift speeds under WLTP test cycle requirements. EMA's evolving electrified vehicle type approval standards create compliance targets fragmenting platform engineering budgets. Stuttgart and Munich engineering centers anchor ZF Friedrichshafen's 800-volt-compatible hybrid transmission family development.
Japan
Two decades of Toyota and Honda production scale have built the largest installed base of parallel hybrid architectures. METI industrial policy supports continuous refinement of planetary gear-set e-CVT production. Aichi Prefecture's Toyota City maintains dominant engineering density with tier-one suppliers co-located for captive integration.
India
The FAME-II subsidy extension creates procurement pull for localized hybrid transmission assembly serving domestic OEM electrification roadmaps. The country's national automotive regulator is aligning type approval standards with emerging electrification requirements. Tamil Nadu and Gujarat manufacturing belts are attracting transmission assembly investments targeting cost-sensitive segment volumes.
Global Hybrid Vehicle Transmission Market Competitive Environment
Player mix skews toward integrated powertrain specialists with captive OEM relationships and multi-national component conglomerates with modular platform strategies. Market structure concentrates around tier-one suppliers possessing ISO 26262 ASIL-D certification expertise, compressing qualification timelines for mid-tier competitors. Dominant archetypes include captive-integrated Japanese specialists, European multi-clutch system developers, and North American commercial vehicle transmission houses. Competitive moves center on 800-volt architecture scaling and P2 module retrofit partnerships for existing front-wheel-drive platforms.
Within the captive-integrated tier, Aisin Seiki Co. Ltd. and JATCO Ltd. exemplify Japanese specialists leveraging co-location with domestic OEM engineering centers. ZF Friedrichshafen AG occupies a position representing European multi-clutch and torque-vectoring expertise. BorgWarner Inc. anchors the modular retrofit archetype, with its corporate structure indicating North American origins and diversified powertrain component positioning.
| Leading Market Players |
|---|
| Aisin Seiki Co. Ltd. |
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Schaeffler AG |
| Allison Transmission Holdings Inc. |
| Hyundai Transys Inc. |
| JATCO Ltd. |
| Magna International Inc. |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month qualification cycles for ISO 26262 ASIL-D certification compress supplier pricing power while concentrating procurement leverage among Japanese and German tier-one manufacturers with captive OEM relationships. This lead-time band shapes how transmission suppliers allocate engineering resources and where buyers extract volume discounts.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ASIL-D qualified suppliers commanding project-based long-term contracts against transactional spot purchasing for uncertified alternatives. Price differentiation hinges on functional safety grade and hollow-shaft motor packaging complexity, with fleet operators showing highest sensitivity due to total cost of ownership calculations. Cost compression in mild-hybrid 48V modules is intensifying because belt-integrated starter-generator commoditization erodes margin buffers.
Supply Chain Analysis
China and Japan anchor rare earth magnet processing and planetary gear-set manufacturing respectively, with Germany supplying multi-plate wet clutch friction materials. The chain draws from neodymium concentrates in Inner Mongolia, advanced resin binders from European chemical feedstocks, and silicon carbide substrates from South Korean foundries. Single-source vulnerability concentrates in dysprosium export quotas. Distribution runs through OEM captive supply networks with direct fleet procurement bypassing traditional dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined torque management and predictive maintenance subscriptions expand addressable recurring revenue faster than hardware unit sales, creating service-attach economics that reshape supplier valuation models.
For Market Incumbents: Consolidate backward integration into rare earth magnet supply through offtake agreements with Chinese processors, buffering against export quota volatility. Deepen certification investment in 800-volt architectures to defend against ZF Friedrichshafen's voltage scalability lead. Lock hollow-shaft motor packaging expertise through capacity addition in Aichi Prefecture supplier parks. For New Entrants and Emerging Players: ISO 26262 ASIL-B fast-track programs open qualification pathways for Indian and Southeast Asian suppliers targeting FAME-II subsidy windows. Fleet operator direct procurement in Michigan and Texas represents the most penetrable channel, bypassing entrenched OEM supply relationships. Lead with remanufacturing and software calibration services rather than greenfield transmission manufacturing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming powertrain divisions lacking electrification roadmaps. Five-to-ten-year viability hinges on 800-volt platform nominations and PHEV ratio spread engineering capabilities. Watch for MIIT credit threshold recalibration as the inflection signal redirecting supplier R&D budgets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Toyota's e-CVT architecture licensing reduces engineering duplication across hybrid programs. |
| Battery Supply Agreement | Cell sourcing partnerships secure thermal management integration for 130 km/h electric-only operation. |
| Software-Defined Vehicle Investment | Torque-splitting algorithm harmonization extends validation cycles but locks supplier switching costs. |
| Geographic Manufacturing Footprint | Tamil Nadu assembly investments capture FAME-II procurement pull for cost-sensitive segments. |
| Charging Infrastructure Partnership | Fleet depot electrification aligns transmission duty cycles with commercial vehicle utilization patterns. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted, including OEM platform engineers, tier-one supplier procurement directors, fleet maintenance managers, and aftermarket remanufacturing specialists. Secondary validation drew from EPA fuel economy filings, MIIT NEV credit databases, vehicle production registries, and customs trade records. Bottom-up unit forecasts triangulated against top-down OEM electrification spend projections.
Across the analysis window, volume and value outputs segment by propulsion architecture, system voltage tier, and regional regulatory cluster. CAGRs derived from production ramp curves and content-per-vehicle trajectories incorporate battery capacity expansion rates and torque converter lockup strategy evolution as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable rare earth export policy and sustained EPA CAFE stringency; material deviation in either driver would warrant model refresh. Recalibration cycles align with MIIT credit methodology updates and state-level fleet mandate adoptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
North America Mild Hybrid Vehicles Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
Smart Hybrid Vehicle Market