
 High-Voltage Hybrid Vehicle Market | 2026-2036
High-Voltage Hybrid Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
High-Voltage Hybrid Vehicle Market Intelligence
Silicon carbide inverter integration is reshaping high-voltage hybrid architectures by cutting switching losses and enabling smaller thermal management packages. Toyota Motor Corporation leverages its two-decade Prius powertrain lineage to sustain manufacturing scale across Japanese and North American assembly plants. BYD Company Limited anchors vertical control over blade battery cell production, while BMW Group differentiates through modular Gen-5 eDrive architectures that span plug-in hybrid and battery-electric variants from a shared platform.
High-voltage hybrid vehicles combine internal combustion engines with electric motors operating above 60 volts, typically incorporating lithium-ion battery packs between 200 and 800 volts to deliver torque-fill, regenerative braking energy capture, and limited all-electric range. The primary commercial purpose centers on emissions reduction without range anxiety penalties, serving fleet operators and private buyers facing urban low-emission zone mandates. Plug-in hybrid electric vehicles occupy the dominant revenue position due to larger battery capacities and eligibility for purchase incentives, while mild hybrid electric vehicles lead unit volume through lower incremental cost and simpler integration into existing vehicle platforms. Power electronics represents the fastest-growing technology segment as inverter and DC-DC converter suppliers race to qualify silicon carbide and gallium nitride components.
The EPA tailpipe standards, California Air Resources Board zero-emission vehicle mandates, and China's MIIT new energy vehicle credit system collectively determine which powertrain configurations qualify for regulatory relief and market access. EMA's evolving carbon dioxide fleet targets and REACH chemical compliance for battery materials add European compliance layers that shape cell chemistry selection and recycling obligations. Stakeholders must monitor how pending revisions to fuel-economy test cycles in major markets redefine the real-world electric range that determines both consumer utility and regulatory credit generation.

Market Dynamics
Silicon carbide inverter adoption is compressing thermal management footprints and forcing incumbent suppliers to requalify power electronics architectures around 800-volt operating thresholds.
Growth Catalysts
- California's Advanced Clean Trucks Regulation:Fleet operators face binding zero-emission sales quotas that channel procurement dollars toward plug-in hybrid commercial platforms.
- Cell chemistry advancement:Lithium iron phosphate formulations from China's Yangtze River Delta manufacturing cluster are reducing battery pack costs while improving thermal stability.
- Fleet TCO recalculation:Logistics operators in Germany and the Netherlands are rewriting procurement criteria as diesel fuel taxation and urban access fees tilt lifetime cost models toward electrified powertrains.
Market Restraints
- Raw material concentration:Cobalt and refined lithium supply routes through the Democratic Republic of Congo and Chilean salt flats expose cell manufacturers to geopolitical disruption and price volatility.
- Power electronics qualification timelines:Silicon carbide module validation cycles stretch 18-24 months, gating platform launches for OEMs locked into legacy insulated-gate bipolar transistor supply agreements.
- Charging infrastructure asymmetry:Apartment dwellers and urban commercial depots lack reliable 240-volt or DC fast-charging access, constraining plug-in hybrid utility for the highest-mileage user segments.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic cell and module manufacturing incentives are attracting joint ventures that could localize high-voltage pack assembly for price-sensitive fleet segments.
- Vehicle-to-grid integration:Bidirectional charging hardware creates new revenue streams for fleet operators selling grid services during peak demand windows.
- Commercial van electrification:Last-mile delivery contractors in France and the United Kingdom face tightening urban access rules that favor plug-in hybrid panel vans with sufficient electric range for city-center operations.
Industry Challenges
- Power electronics engineering scarcity:OEMs and Tier-1 suppliers compete for limited pools of silicon carbide gate driver and thermal packaging specialists, extending development timelines.
- Battery recycling compliance:EU Battery Regulation mandates for recycled content quotas and producer responsibility schemes force manufacturers to build reverse logistics networks before scale economics justify the investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Voltage Hybrid Vehicle Market |
| Market Size in 2026 | $218.4 Billion |
| Market Size in 2035 | $502.47 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Mild Hybrid Electric Vehicle, Fuel Cell Electric Vehicle Technology: Regenerative Braking, Electric Drive, Energy Recovery Systems, Power Electronics End User: Public Transport, Personal Use, Commercial Fleets, Ride-Sharing Services Application: Urban Mobility, Long-Distance Travel, Cargo Transport, Emergency Services |
| Companies Covered | Hyundai Motor Company, Volkswagen Group, Toyota Motor Corporation, BMW Group, Kia Corporation, Honda Motor Co., Ltd, General Motors Company, BYD Company Limited, Ford Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Voltage Hybrid Vehicle Market Strategic Shifts & Innovations
Power semiconductor material transitions and software-defined thermal management are rewriting system integration requirements across high-voltage hybrid architectures.
Silicon carbide metal-oxide-semiconductor field-effect transistors are replacing silicon insulated-gate bipolar transistors in traction inverters, cutting switching losses by two-thirds and enabling liquid-cooled packages half the size of previous generations. Tier-1 suppliers in Japan and Germany are shipping 800-volt-qualified modules to OEM platform teams targeting 2027-2028 production ramps. This transition is virtualizing the boundary between power electronics and thermal engineering disciplines, collapsing what were separate supplier tiers into integrated subsystem sourcing.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in battery thermal management systems, forcing OEMs to qualify carbon dioxide or propane heat pump circuits. Engineering teams in Stuttgart and Munich are redesigning pack enclosures to accommodate higher-pressure refrigerant lines and revised crash safety margins. European plug-in hybrid platforms launching after 2027 will carry this hardware burden, compressing development budgets for other subsystems.
Fleet leasing companies are unbundling battery residual value risk from vehicle financing contracts, creating separate asset classes for high-voltage pack second-life applications. Lessors in the Netherlands and California are negotiating direct offtake agreements with stationary storage developers, bypassing OEM trade-in channels. This restructuring is most advanced among municipal bus operators with predictable duty cycles and centralized depot charging infrastructure.
High-Voltage Hybrid Vehicle Market Segmentation
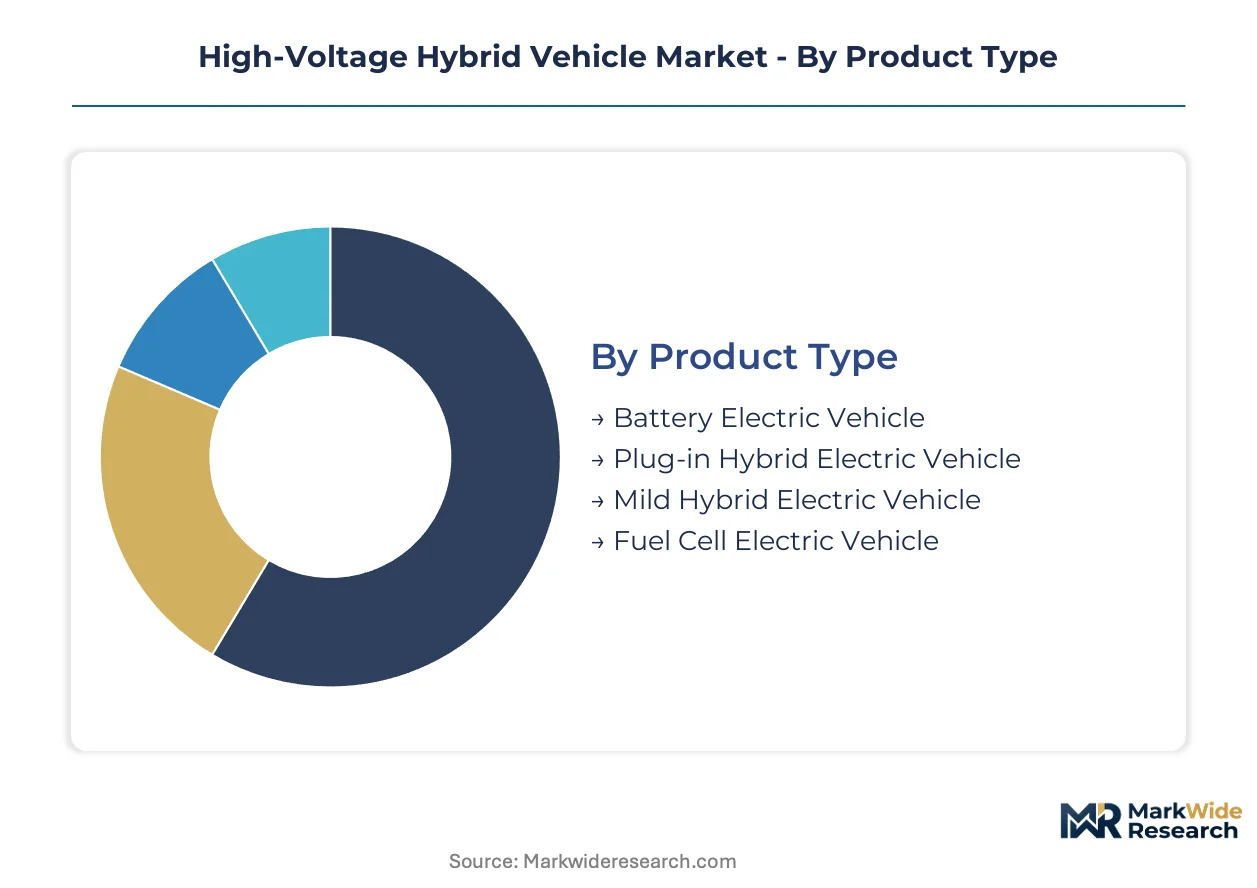
Segmentation in high-voltage hybrid vehicles exposes divergent service lifecycle economics across powertrain architectures. Fleet operators and private buyers face fundamentally different battery degradation curves, thermal management service intervals, and power electronics warranty exposure depending on which configuration they procure.
Product Type:
After-sales service intensity varies dramatically across electrification levels, with battery thermal management and inverter replacement cycles defining lifetime maintenance burden.
- Plug-in Hybrid Electric Vehicle:Combines internal combustion engine with 200-800 volt battery packs enabling 30-80 kilometer electric-only range. Commercial fleet operators in Germany and the Netherlands concentrate procurement here as urban low-emission zone mandates intensify and diesel taxation erodes total cost of ownership calculations.
- Mild Hybrid Electric Vehicle:Integrates 48-volt belt-driven starter-generators for torque-fill and stop-start functionality without plug-in capability. Entry-level passenger car buyers in India's price-sensitive market gravitate toward this architecture where the country's PLI scheme for automotive manufacturing supports localized assembly cost structures.
- Battery Electric Vehicle:Eliminates internal combustion entirely through 400-800 volt dedicated electric architectures.
- Fuel Cell Electric Vehicle:Employs hydrogen fuel cells paired with small buffer batteries for heavy-duty and long-haul applications.
By volume, Mild Hybrid Electric Vehicle leads. By growth pace, Plug-in Hybrid Electric Vehicle is ahead.
Technology:
Cost tier separation in powertrain electronics determines which thermal management and semiconductor technologies reach mass-market price points versus premium vehicle applications.
- Power Electronics:Silicon carbide traction inverters and DC-DC converters operating at 800 volts slash switching losses by two-thirds versus silicon predecessors. OEM platform teams in Japan and Germany are qualifying these modules for production ramps, with supply constraints from 18-24 month validation cycles limiting near-term availability.
- Regenerative Braking:Captures kinetic energy during deceleration through motor-generator units feeding high-voltage battery packs. China's MIIT new energy vehicle credit system rewards systems with higher energy recovery efficiency, concentrating supplier engineering resources in the Yangtze River Delta manufacturing cluster.
- Electric Drive:Permanent magnet synchronous and induction motor configurations delivering torque to wheels.
- Energy Recovery Systems:Auxiliary thermal and electrical energy capture from exhaust heat and climate systems.
Power Electronics commands the steepest expansion trajectory as silicon carbide displacement accelerates. Regenerative Braking maintains the largest installed base across current production.
End User:
Customer type dictates charging infrastructure access patterns, which in turn shapes viable battery capacities and electric range specifications.
- Commercial Fleets:Logistics operators and delivery contractors with centralized depot charging and predictable duty cycles. California's Advanced Clean Trucks regulation imposes binding zero-emission sales quotas that channel fleet procurement dollars toward plug-in hybrid platforms with sufficient electric range for urban access compliance.
- Public Transport:Municipal bus operators with fixed routes and overnight depot infrastructure. Dutch and California lessors are pioneering battery residual value unbundling, negotiating direct offtake agreements with stationary storage developers for second-life pack applications.
- Personal Use:Individual buyers with residential or workplace charging availability.
- Ride-Sharing Services:High-utilization drivers requiring rapid charging compatibility and durability.
Commercial Fleets generate the highest revenue per unit through premium powertrain specifications. Personal Use delivers the greatest absolute volume.
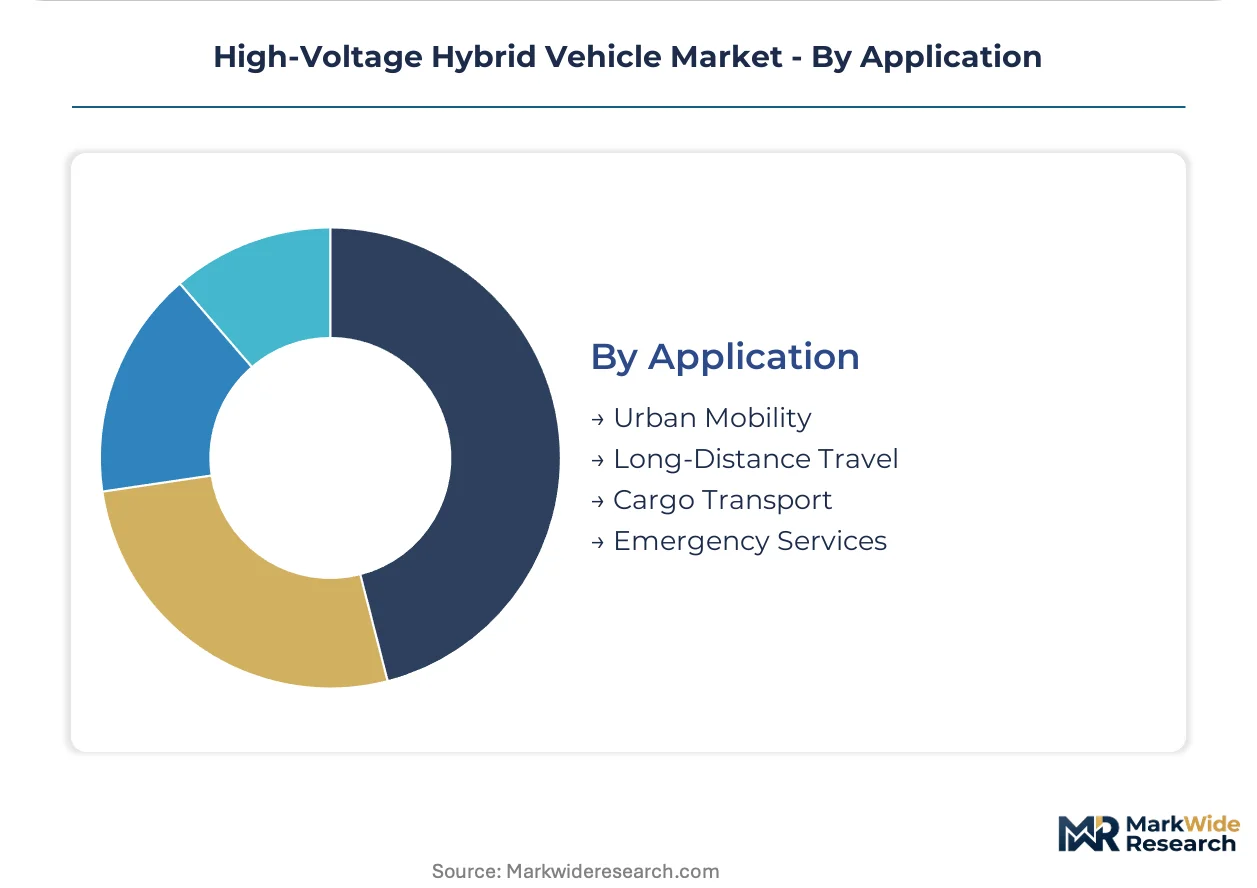
Application:
Geography of operation determines thermal management requirements, with climate extremes and urban congestion patterns dictating battery cooling and heating loads.
- Urban Mobility:Stop-start traffic patterns favoring frequent regenerative braking events and short electric-only trips. France and United Kingdom last-mile delivery contractors face tightening city-center access rules that favor plug-in hybrid panel vans with calibrated electric range for zero-emission zone compliance.
- Cargo Transport:Medium-duty commercial applications requiring sustained power delivery and payload capacity. The EU's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants, forcing redesign of battery thermal management systems with carbon dioxide or propane heat pump circuits for platforms launching after 2027.
- Long-Distance Travel:Highway cruising with minimal regenerative braking opportunity.
- Emergency Services:First-responder vehicles requiring guaranteed availability and rapid response.
Urban Mobility dominates current procurement volumes. Cargo Transport is climbing the fastest as commercial van electrification accelerates under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet buyers and private consumers cluster differently across major markets, with commercial operators driving procurement in Germany and California while price-sensitive passenger demand concentrates in India and China's manufacturing clusters.
China
MIIT's new energy vehicle credit system rewards manufacturers for higher-efficiency electrified platforms, channeling engineering resources toward silicon carbide inverter development. The Yangtze River Delta manufacturing cluster anchors high-voltage battery pack assembly, with BYD and SAIC-GM-Wuling operating at scale to serve domestic and export demand.
Germany
Logistics operators in the Netherlands-adjacent Rhine-Ruhr corridor are rewriting procurement criteria as diesel fuel taxation and urban access fees tilt total cost of ownership models toward plug-in hybrid commercial platforms. EMA's evolving carbon dioxide fleet targets and REACH chemical compliance for battery materials shape cell chemistry selection and recycling obligations for Stuttgart and Munich engineering teams.
United States
California's Advanced Clean Trucks regulation imposes binding zero-emission sales quotas that channel fleet procurement dollars toward plug-in hybrid commercial vehicles with sufficient electric range for urban compliance. The EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates collectively determine which powertrain configurations qualify for regulatory relief and market access.
Japan
METI industrial policy supports sustained manufacturing scale across domestic and North American assembly plants, leveraging two-decade powertrain lineage advantages. Tier-1 suppliers in Japan are shipping 800-volt-qualified silicon carbide modules to OEM platform teams targeting 2027-2028 production ramps.
India
The PLI scheme for automotive manufacturing attracts joint ventures that could localize high-voltage pack assembly for price-sensitive fleet segments. Entry-level passenger car buyers gravitate toward mild hybrid architectures where localized assembly cost structures support market penetration.
High-Voltage Hybrid Vehicle Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages in battery cell production and power electronics qualification create separation. The vendor base organizes around three strategic archetypes: vertically integrated battery specialists, modular platform architects, and legacy powertrain adaptors. Competitive moves concentrate on strategic partnerships for silicon carbide supply security and geographic expansion into India's PLI-subsidized manufacturing zones.
Within the integrated battery specialist tier, BYD Company Limited exemplifies upstream control over blade battery cell production. Among modular platform architects, BMW Group occupies a position spanning plug-in hybrid and battery-electric variants from shared Gen-5 eDrive architectures. Toyota Motor Corporation represents the legacy powertrain adaptor archetype, sustaining manufacturing scale through established Prius lineage advantages.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| Volkswagen Group |
| Toyota Motor Corporation |
| BMW Group |
| Kia Corporation |
| Honda Motor Co., Ltd |
| General Motors Company |
| BYD Company Limited |
| Ford Motor Company |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta manufacturing cluster concentrates high-voltage battery cell output, anchoring margin capture downstream at OEMs and Tier-1 power electronics suppliers who negotiate long-term offtake terms against volatile lithium and cobalt benchmarks.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate cell procurement, with pricing stratifying across premium 800-volt silicon carbide platforms, standard 400-volt lithium-ion architectures, and economy mild-hybrid 48-volt systems. Price differentiation hinges on thermal management certification grade and volume scale commitments. Cost compression in the economy tier is intensifying because India's PLI-subsidized local assembly erodes import parity. Fleet operators in Germany and California exhibit the lowest price sensitivity due to regulatory compliance mandates, while India's entry-level passenger buyers face acute budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for North American OEMs qualifying alternative cell sources. Manufacturing concentrates in China, South Korea, and Japan for lithium-ion cells and power electronics modules. The sector draws from refined lithium brine in Chile, cobalt concentrate from the Democratic Republic of Congo, and processed cathode materials from China's Hunan and Fujian provinces. Single-source vulnerability around silicon carbide wafer fabrication threatens inverter qualification timelines. Distribution runs through captive OEM supply agreements and Tier-1 subsystem integrators rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across powertrain electrification levels creates niche opportunities as fleet procurement criteria diverge from private buyer priorities under divergent regulatory compliance burdens.
For Market Incumbents: Build captive silicon carbide supply moats through direct wafer foundry investments or exclusive tolling arrangements, insulating platform launch timelines from 18-24 month qualification bottlenecks. Deepen backward integration into battery thermal management hardware to capture margin pools shifting from cell chemistry to system integration. Prioritize certification investment for EU F-Gas Regulation compliance ahead of 2027 platform deadlines.
For New Entrants and Emerging Players: Build out vehicle-to-grid bidirectional charging capabilities as a differentiated service layer for commercial fleet operators in the Netherlands and California, where grid services revenue streams remain underdeveloped. Target India's PLI-subsidized manufacturing zones for localized mild-hybrid pack assembly serving price-sensitive fleet segments. Pursue direct lessor partnerships that unbundle battery residual value risk from vehicle financing contracts.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed power electronics specialists holding silicon carbide gate driver IP and thermal packaging expertise accumulated through automotive qualification cycles. The five-to-ten year viability window favors platforms with demonstrated 800-volt production ramps and established OEM supply relationships. Monitor silicon carbide module spot pricing as the inflection signal for supply-demand rebalancing and margin normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term offtake contracts with Yangtze River Delta cell manufacturers secure volume allocation amid raw material volatility. |
| Silicon Carbide Foundry Partnership | Direct wafer supply relationships with Japanese and German substrate specialists compress inverter qualification timelines. |
| Platform Standardization | Modular Gen-5 eDrive architectures spanning PHEV and BEV variants reduce engineering overhead per powertrain configuration. |
| Charging Infrastructure Partnership | Depot fast-charging installations for commercial fleets in California and Germany unlock plug-in hybrid utility for high-mileage segments. |
| Software-Defined Thermal Management | Virtualized control systems integrating power electronics and battery cooling collapse separate supplier tiers into subsystem sourcing. |
Research Approach
Desk research of automotive production databases, IHS Markit registration data, and MIIT new energy vehicle credit disclosures preceded structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, fleet operator sustainability directors, and power electronics R&D heads. Primary fieldwork combined telephone and video interviews with secondary validation against regulatory filings from EPA, CARB, and EMA. Bottom-up vehicle production forecasts triangulated against top-down powertrain content value estimates.
Assumptions held fixed include existing tailpipe emissions frameworks and current battery chemistry cost curves, while variables tested included silicon carbide adoption pace, charging infrastructure deployment density, and raw material price volatility. The analytical framework segments by propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs were derived from logistic diffusion modeling of technology substitution rates applied to fleet turnover dynamics and consumer purchase intent surveys.
Sensitivities concentrate around silicon carbide supply constraints, EU Battery Regulation recycling mandate timelines, and potential revisions to fuel-economy test cycles in major markets. Forecasts reflect documented assumptions about technology cost reduction trajectories and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Truck Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market