
 Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market | 2026-2036
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market Foresight
Advanced packaging engineering talent is bifurcating the competitive landscape, with foundries in Taiwan and South Korea capturing the bulk of TSV and hybrid bonding expertise. Samsung Electronics leverages captive DRAM supply and in-house logic foundry capacity to control HBM3E production ramps. SK Hynix anchors the premium stack layer count race through proprietary MR-MUF technology. Micron Technology competes via Boise-based R&D and strategic foundry partnerships for HBM4 roadmaps.
Hybrid Memory Cube and High-Bandwidth Memory denote 3D-stacked memory architectures employing through-silicon vias to achieve bandwidth densities exceeding 1 TB/s, primarily serving AI accelerators and graphics processors where conventional DDR interfaces create thermal and pin-count bottlenecks. The HBM product type dominates value capture as AI training clusters consume 12-Hi and 16-Hi configurations, while HMC persists in niche aerospace and networking sockets where deterministic latency matters. End user segmentation tilts sharply toward AI Systems and Data Centers, with Graphics applications sustaining stable but slower expansion as gaming refresh cycles elongate.
US export controls administered by the Department of Commerce and South Korea's Ministry of Trade, Industry and Energy (METI-aligned industrial policy) are fragmenting equipment procurement and customer access tiers, compelling vendors to maintain dual compliance tracks. REACH substance restrictions and the EU F-Gas Regulation are adding material qualification burdens for fluorinated solvents used in advanced packaging cleanrooms. Stakeholders must monitor how sovereign AI infrastructure buildouts in Saudi Arabia, India, and Japan reshape long-term offtake commitments and localization requirements.
Market Dynamics
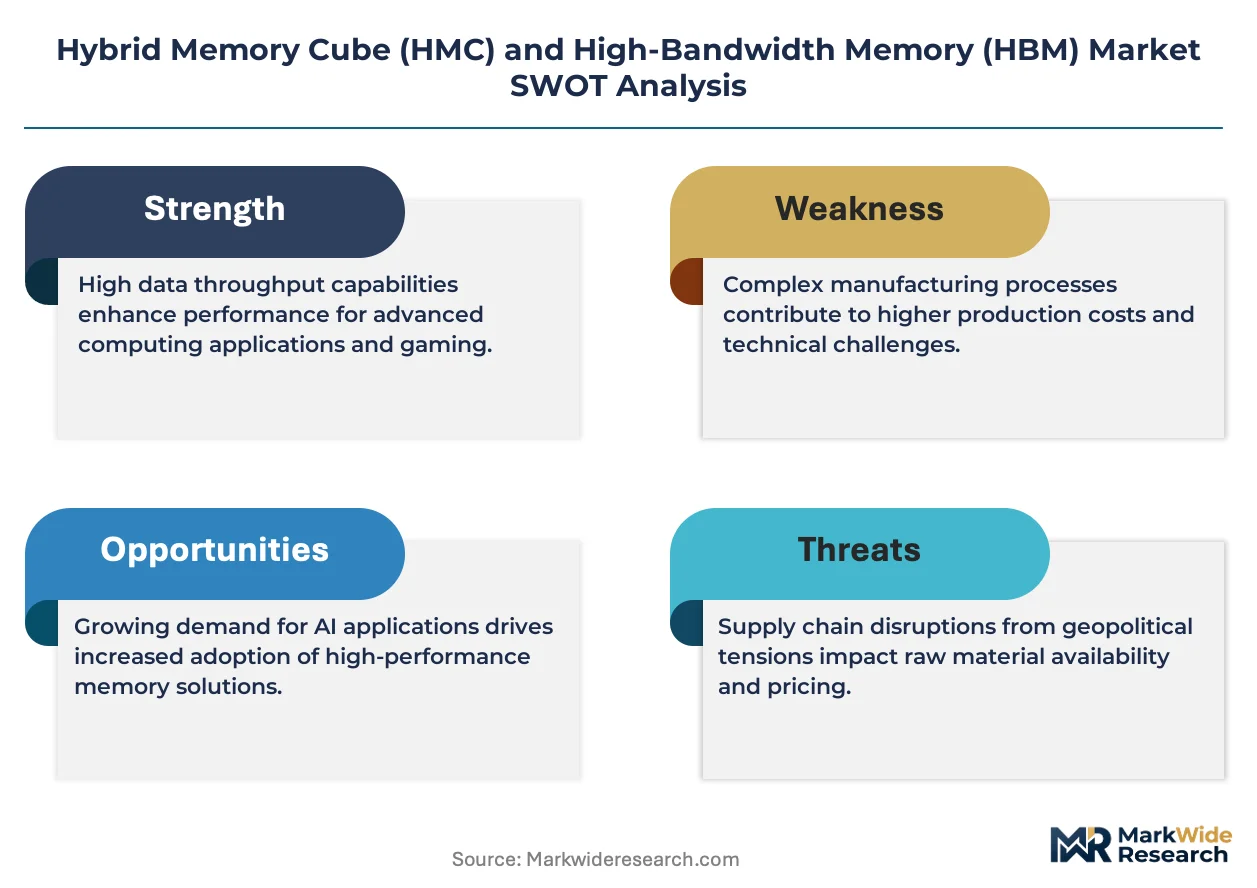
AI accelerator deployments by hyperscale operators are compressing procurement cycles for high-stack-count HBM configurations, concentrating demand around Taiwan's advanced packaging foundries and South Korea's memory fabrication corridor.
Growth Catalysts
- US CHIPS Program:Domestic advanced packaging subsidies are accelerating foundry investments in through-silicon via capacity, reducing reliance on offshore assembly for strategic AI chip production.
- EU AI Act:Compliance requirements for high-risk AI systems are mandating verifiable compute infrastructure, driving certified memory subsystem procurement for European sovereign cloud deployments.
- Hybrid bonding:Die-to-wafer hybrid bonding processes are enabling 16-Hi and future 20-Hi stack configurations, extending bandwidth density scaling beyond traditional microbump limitations.
Market Restraints
- Fluorinated solvent supply:REACH substance restrictions and the EU F-Gas Regulation are constraining cleanroom chemical availability, extending material qualification timelines for advanced packaging facilities.
- TSV etch equipment concentration:Deep reactive ion etching systems for high-aspect-ratio vias are sourced from a concentrated vendor base in Japan and the United States, creating procurement bottlenecks during demand surges.
- GDDR6X persistence:Graphics card manufacturers continue specifying conventional memory for mid-range gaming SKUs, limiting HBM penetration in price-sensitive discrete GPU segments.
Strategic Opportunities
- Saudi sovereign AI infrastructure:NEOM and related data center buildouts are generating long-term offtake commitments for high-bandwidth memory in regional AI training clusters.
- Automotive ADAS convergence:L3+ autonomous driving systems are integrating AI accelerators requiring deterministic memory bandwidth, opening HMC sockets where latency predictability outweighs density.
- Japan's semiconductor revitalization:METI-backed subsidies for Kioxia and domestic foundry investments are creating alternative advanced packaging capacity for HBM4 generation products.
Industry Challenges
- MR-MUF process engineering:SK Hynix's proprietary mass reflow molded underfill expertise remains concentrated among a limited talent pool, constraining rapid workforce scaling for competing foundries.
- Dual compliance track maintenance:Vendors must simultaneously satisfy US Department of Commerce export controls and South Korean Ministry of Trade, Industry and Energy industrial policy, fragmenting customer access tiers and equipment procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market |
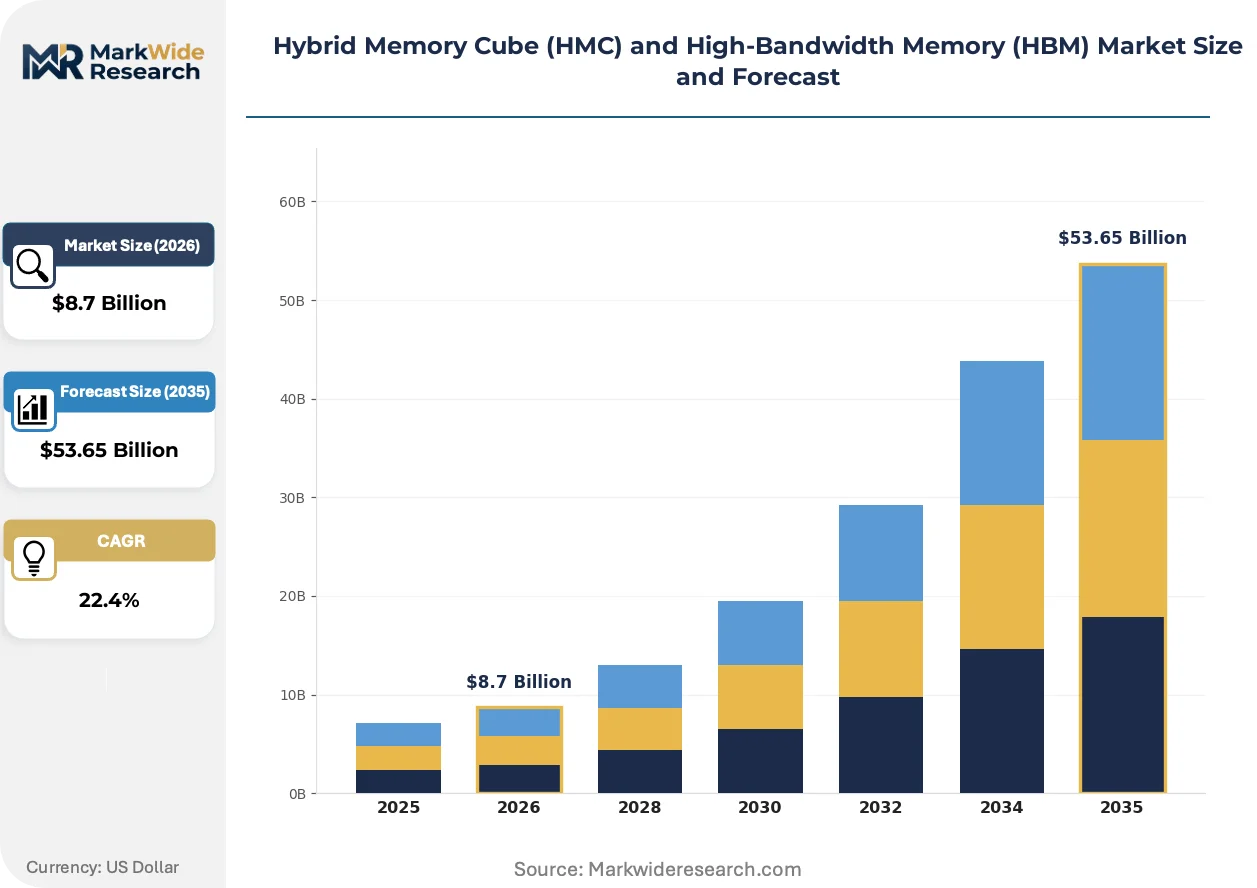
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HMC, HBM, DRAM, SDRAM Integration Level: On-chip, Off-chip, Package, Module End User: High-Performance Computing, Data Centers, Graphics, AI Systems Usage Scenario: Gaming, Data Processing, Machine Learning, Cloud Computing |
| Companies Covered | Samsung Electronics, Micron Technology, SK Hynix, Advanced Micro Devices, Intel Corporation, NVIDIA, IBM, Fujitsu, Rambus Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market Shifts & Advancements
Memory architecture roadmaps are diverging between bandwidth-maximizing AI training configurations and latency-optimized inference deployments, with packaging technology choices increasingly determining competitive positioning.
Hybrid bonding is replacing conventional microbump interconnects in the highest-layer-count HBM stacks. AI training chip designers at hyperscale operators are specifying hybrid-bonded memory subsystems for next-generation accelerators. This transition is bifurcating the supplier base between foundries with installed hybrid bonding capacity and those dependent on legacy interconnect methods.
REACH substance restrictions are tightening qualification requirements for fluorinated solvents used in TSV formation and wafer cleaning steps. European packaging facilities face extended environmental compliance reviews before process qualification. Memory vendors are responding by qualifying alternative chemistries and relocating high-volume production to jurisdictions with streamlined chemical approval pathways.
Hyperscale operators are consolidating memory procurement around direct foundry relationships, bypassing traditional DRAM module vendors. Cloud AI infrastructure divisions are negotiating stack-level supply agreements with Samsung and SK Hynix rather than sourcing through channel intermediaries. This concentration is most pronounced in North American data center buildouts, where vertical integration between chip design and memory supply is becoming standard practice.
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market Segmentation
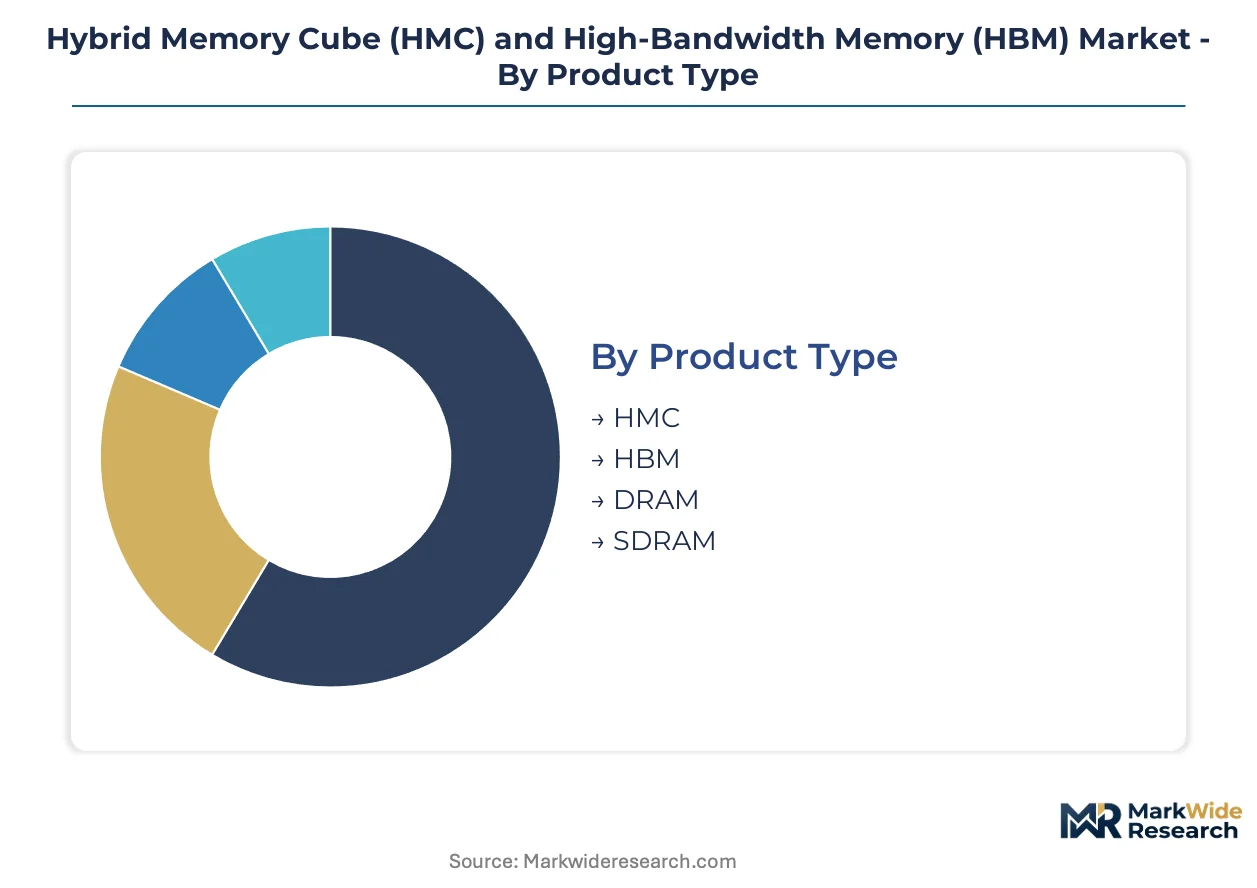
Memory architecture choices determine thermal budgets, pin counts, and bandwidth ceilings for AI accelerators. Segmentation reveals where packaging technology investments concentrate and which end-use verticals command premium stack configurations.
Product Type:
HBM captures the dominant margin pool through AI training cluster procurement, while HMC retains niche premiums in latency-sensitive applications.
- HMC:3D-stacked memory employing through-silicon vias with a serial interface, optimized for deterministic latency rather than peak bandwidth. Aerospace and high-frequency trading systems in the United States and Switzerland specify HMC where jitter tolerance matters more than density.
- HBM:Wide-interface 3D memory stacks delivering bandwidth densities exceeding 1 TB/s through parallel TSV interconnects. Hyperscale operators in Taiwan's semiconductor fabrication cluster and South Korea's memory corridor are absorbing 12-Hi and 16-Hi configurations for GPU-based AI training infrastructure.
- DRAM:Conventional planar memory serving cost-optimized computing where bandwidth requirements stay below DDR5 limits. Mid-range gaming SKUs and enterprise storage controllers in Japan's industrial electronics sector continue specifying discrete DRAM packages.
- SDRAM:Synchronous dynamic memory with external clock synchronization, persisting in legacy networking equipment and embedded control systems where interface simplicity outweighs bandwidth scaling.
HBM holds installed capacity. HMC is rotating up the share rankings in aerospace and financial computing sockets.
Integration Level:
Package-level integration commands the steepest price premiums as foundries compete for TSV and hybrid bonding expertise.
- On-chip:Memory cells fabricated directly atop logic die through monolithic 3D integration, currently limited to research demonstrations and prototype AI accelerators at Intel and TSMC.
- Off-chip:Discrete memory subsystems connected through interposer or substrate routing, dominating current HBM2E and HBM3 production where yield management favors separated die processing.
- Package:Multi-die assemblies integrating logic and memory within a single substrate, capturing the bulk of AI accelerator value as NVIDIA and AMD specify custom CoWoS and EMIB configurations from TSMC and Intel Foundry.
- Module:Standardized memory subsystems on DIMM or SO-DIMM form factors, serving data center servers where socket compatibility and field serviceability constrain integration depth.
Package commands the highest average selling prices. Module is climbing fastest in cloud server refresh cycles.
End User:
AI Systems concentrate procurement volume and pricing power, while Graphics sustains stable but slower expansion.
- High-Performance Computing:National laboratories and weather simulation centers specifying HBM2E and HBM3 for exascale system deployments. Oak Ridge National Laboratory and RIKEN in Japan are absorbing high-stack-count configurations for fusion energy and climate modeling workloads.
- Data Centers:Cloud infrastructure operators consolidating memory procurement around direct foundry relationships. Amazon Web Services, Microsoft Azure, and Google Cloud Platform are negotiating stack-level supply agreements with Samsung and SK Hynix for training cluster buildouts.
- Graphics:Discrete GPU manufacturers balancing HBM against GDDR6X for gaming and professional visualization. NVIDIA's RTX Pro series and AMD's Radeon Pro workstation cards specify HBM for memory bandwidth-intensive rendering, while consumer gaming SKUs remain on conventional memory.
- AI Systems:Dedicated training and inference accelerators from hyperscale silicon divisions and semiconductor vendors. Google's TPU, Amazon's Trainium, and SambaNova Systems' DataScale platforms are driving 16-Hi HBM3E adoption for large language model training.
Data Centers hold installed procurement scale. AI Systems is expanding most quickly in training cluster deployments.
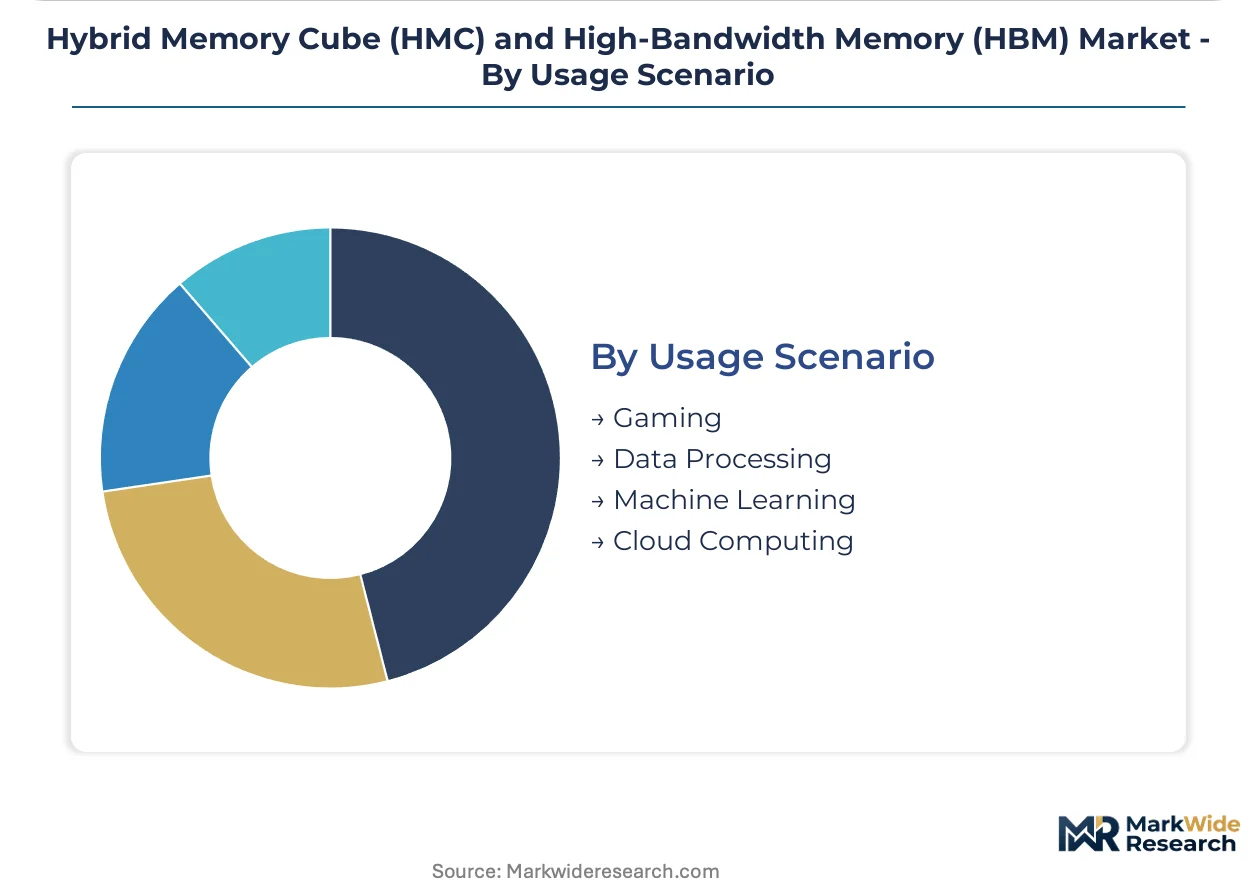
Usage Scenario:
Machine Learning commands the steepest memory bandwidth requirements, while Gaming remains price-sensitive and conventionally supplied.
- Gaming:Real-time rendering workloads where frame buffer capacity and cost efficiency dominate over bandwidth scaling. GDDR6X persists in mid-range discrete GPUs from NVIDIA and AMD, limiting HBM penetration.
- Data Processing:In-memory analytics and transaction processing where latency predictability matters. SAP HANA deployments and financial risk calculation engines in Frankfurt and Singapore specify HMC for deterministic response times.
- Machine Learning:Model training and fine-tuning operations saturating memory bandwidth with parameter and activation storage. OpenAI, Anthropic, and DeepSeek are consuming 12-Hi and 16-Hi HBM stacks for transformer model training runs.
- Cloud Computing:General-purpose virtualized infrastructure where memory configurations balance cost against performance tiers. Alibaba Cloud and Tencent Cloud are standardizing HBM3 for premium compute instances while retaining DDR5 for baseline offerings.
Machine Learning holds the highest bandwidth intensity. Cloud Computing is gaining share fastest in enterprise AI service deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between AI training clusters demanding maximum bandwidth density and aerospace systems prioritizing deterministic latency, with procurement concentrating in East Asian fabrication corridors and North American cloud infrastructure hubs.
United States
Hyperscale operators including Amazon Web Services and Microsoft Azure are absorbing 16-Hi HBM3E stacks for training cluster expansion. The Department of Commerce export controls administered through the Bureau of Industry and Security are fragmenting equipment procurement for advanced packaging. Austin and Phoenix are emerging as domestic advanced packaging investment zones as Intel Foundry and TSMC Arizona ramp TSV capacity.
South Korea
Memory manufacturers are capturing premium stack layer count leadership through proprietary mass reflow molded underfill expertise. The Ministry of Trade, Industry and Energy is aligning industrial policy with METI-coordinated supply chain resilience initiatives. The Seoul Capital Area and Yongin corridor host concentrated HBM3E and HBM4 pilot line investments from Samsung Electronics and SK Hynix.
Taiwan
Foundries are dominating CoWoS and hybrid bonding capacity for AI accelerator packaging where logic-memory integration commands premium pricing. National Development Council subsidies are accelerating through-silicon via equipment procurement for strategic semiconductor production. The Hsinchu Science Park and Taichung Precision Machinery Innovation Technology Park anchor global advanced packaging output for NVIDIA and AMD silicon.
Japan
Domestic foundry investments are creating alternative advanced packaging capacity for next-generation memory products. METI-backed subsidies for Kioxia and Rapidus are reshaping regional supply chain configurations for HBM4 roadmaps. The Ibaraki Tsukuba region and Hiroshima prefecture are concentrating deep reactive ion etching equipment installations and materials qualification laboratories.
Saudi Arabia
NEOM and related sovereign AI infrastructure buildouts are generating long-term offtake commitments for high-bandwidth memory in regional training clusters. The Saudi Data and Artificial Intelligence Authority is mandating verifiable compute infrastructure for government cloud deployments. Riyadh and the NEOM northwest zone are attracting direct foundry negotiations bypassing traditional DRAM channel intermediaries.
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive memory supply and in-house logic foundry capacity determining stack-level pricing power. The upper tier controls hybrid bonding and TSV process engineering through concentrated talent pools. Three archetypes populate the competitive map: integrated memory-foundry hybrids, fabless accelerator designers, and intellectual property licensors. Capacity expansion and strategic foundry partnerships represent the dominant competitive moves as vendors secure advanced packaging allocation.
Among integrated memory manufacturers, Samsung Electronics, SK Hynix, and Micron Technology exemplify the captive supply archetype where DRAM fabrication and advanced packaging investments are coordinated under unified corporate structures. Samsung Electronics occupies a position spanning memory production and logic foundry services. SK Hynix anchors the premium stack layer count specialization through proprietary process expertise. Micron Technology represents the geographically diversified R&D model with Boise-based development and strategic foundry partnerships for roadmap execution.
| Leading Market Players |
|---|
| Samsung Electronics |
| Micron Technology |
| SK Hynix |
| Advanced Micro Devices |
| Intel Corporation |
| NVIDIA |
| IBM |
| Fujitsu |
| Rambus Incorporated |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between hyperscale cloud operators and HBM stack manufacturers lock in multi-year supply visibility while capping price volatility exposure for AI training cluster buildouts. These contracts tether procurement volumes to hybrid bonding capacity ramps in Taiwan and South Korea, embedding geographic concentration directly into pricing power dynamics.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement between hyperscale operators and memory manufacturers, with pricing stratifying across premium, standard, and economy tiers based on stack layer count and hybrid bonding certification. Price differentiation hinges on TSV yield rates and volume scale commitments, with 16-Hi configurations commanding substantial premiums over 12-Hi stacks. Cost compression in mid-layer-count tiers is intensifying because competing foundries are qualifying alternative microbump processes. Gaming GPU manufacturers exhibit the highest price sensitivity, while AI Systems buyers prioritize bandwidth density over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication and advanced packaging output for HBM stack production, with Japan emerging as an alternative node for deep reactive ion etching equipment and materials qualification. The supply chain draws from fluorinated solvents for TSV formation, silicon interposers for CoWoS integration, and DRAM die from captive memory fabs. Single-source vulnerability concentrates in Japanese suppliers of high-aspect-ratio etch systems. Distribution runs through direct foundry relationships rather than traditional DRAM channel intermediaries, with hyperscale operators negotiating stack-level agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are multiplying as sovereign AI infrastructure buildouts in Saudi Arabia, India, and Japan create demand niches outside the dominant Taiwan-South Korea supply axis. Divergent regulatory compliance tracks between US export controls and South Korean industrial policy are forcing vendors to architect region-specific product variants.
For Market Incumbents: Shield hybrid bonding and MR-MUF process expertise through targeted retention of advanced packaging engineering talent concentrated in Hsinchu and Yongin. Deepen backward integration into TSV etch equipment procurement to reduce exposure to Japanese vendor bottlenecks during demand surges. Lock in long-term offtake commitments with emerging sovereign AI operators before alternative packaging capacity matures in Japan and Saudi Arabia.
For New Entrants and Emerging Players: Differentiate on deterministic latency specifications for aerospace and financial computing sockets where HMC retains niche premiums against bandwidth-maximizing HBM stacks. Target automotive ADAS convergence applications requiring predictable memory response times for L3+ autonomous systems. Pursue qualification partnerships with European packaging facilities seeking alternative chemistries under REACH and F-Gas regulatory constraints.
For Investors and Strategic Acquirers: Advanced packaging engineering boutiques with installed hybrid bonding capacity represent the most defensible acquisition profile as foundry competition intensifies for 16-Hi and 20-Hi stack configurations. Monitor workforce mobility between TSMC, Samsung, and SK Hynix as an inflection indicator for process technology diffusion rates. Frame long-term viability around captive DRAM supply integration and geographic diversification of TSV capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | Enables 16-Hi and 20-Hi HBM stack configurations for next-generation AI accelerators at hyperscale operators. |
| Dual Compliance Track Architecture | Satisfies simultaneous US Bureau of Industry and Security and South Korean Ministry of Trade, Industry and Energy requirements. |
| Alternative Chemistry Qualification | Addresses REACH substance restrictions and EU F-Gas Regulation constraints on fluorinated solvent availability. |
| Sovereign AI Infrastructure Partnership | Secures long-term offtake commitments from Saudi Data and Artificial Intelligence Authority and NEOM data center buildouts. |
| MR-MUF Process Engineering Acquisition | Captures scarce talent pools for mass reflow molded underfill expertise concentrated at SK Hynix. |
Research Methodology
A standing panel of advanced packaging process engineers, hyperscale cloud procurement officers, memory fab operations directors, and semiconductor equipment vendor sales executives provided ongoing calibration against market developments. Primary interview intelligence combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, Bureau of Industry and Security export control updates, and METI industrial policy announcements. Bottom-up stack shipment tallies triangulated against top-down AI accelerator production forecasts.
Consistency checks validated volume and value outputs against external benchmarks including foundry revenue disclosures and memory manufacturer earnings calls across the analysis window. Segmentation dimensions modeled encompass product type, integration level, end user vertical, and regional regulatory cluster. CAGRs were derived from slope-intercept fitting of annualized shipment trajectories. Forecast inputs incorporated hybrid bonding yield learning curves and sovereign AI infrastructure commitment timelines.
Material uncertainties — abrupt export control expansions, fluorinated solvent supply disruptions, or hybrid bonding equipment delivery delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued TSMC CoWoS capacity expansion and stable South Korean industrial policy alignment. Recalibration cycles align with material shifts in US Department of Commerce licensing thresholds and METI-backed subsidy disbursement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Wi-Fi Chipset Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
Car Chip Market
Chipset and Processors
Global Battery Management IC Market