
 First and Last Mile Delivery Market | 2026-2036
First and Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
First and Last Mile Delivery Market Intelligence
E-commerce retail is consolidating as the dominant client type in first and last mile delivery, pulling volume away from traditional courier networks. Amazon Prime Air leverages autonomous drone development to extend same-day reach into suburban zones. FedEx Corporation anchors its position through massive ground hub infrastructure that sustains next-day reliability at scale. Nuro specializes in zero-occupant electric vehicle design, differentiating its regulatory approach against conventional van-based competitors.
First and last mile delivery encompasses the movement of goods from distribution points to end consumers and from origins to primary transit hubs, typically covering distances under 50 miles using vehicles ranging from cargo bicycles to autonomous robots with payloads between 20 and 500 pounds. The service type dimension shows express and same-day offerings commanding premium pricing while standard delivery occupies the volume base with thinner margins. Electric vehicle and cargo robot delivery modes are attracting capital as cities tighten emissions rules, whereas van and bike segments retain cost advantages in dense and developing markets respectively.
The Federal Aviation Administration governs drone altitude corridors and beyond-visual-line-of-sight waivers in the United States, while the European Union's F-Gas Regulation and vehicle CO2 standards push logistics operators toward electric drivetrains. India's Central Electricity Authority frames charging infrastructure standards that determine where EV fleets can deploy profitably. Stakeholders must monitor how municipal low-emission zone expansions alter route cost structures and whether autonomous vehicle liability frameworks crystallize before technology readiness peaks.
Market Dynamics
Electric vehicle mandates in the European Union and California are compressing fleet replacement timelines, forcing logistics operators to restructure capital deployment around charging infrastructure rather than vehicle procurement alone.
Growth Catalysts
- E-commerce fulfillment density:Urban corridors in Germany, India, and Brazil are generating sufficient parcel volume to justify dedicated micro-fulfillment networks that bypass traditional courier handoffs.
- F-Gas Regulation:The European Union's tightening standards on fluorinated greenhouse gases are accelerating refrigeration unit electrification in cold-chain last mile vehicles.
- Autonomous navigation:Beyond-visual-line-of-sight waivers from the Federal Aviation Administration are expanding drone delivery corridors into suburban zones previously unreachable within same-day windows.
Market Restraints
- Lithium supply concentration:Battery raw material processing concentrates in China, exposing fleet electrification timelines to geopolitical friction and input cost volatility.
- Congestion pricing regimes:Municipal low-emission zones in London, Stockholm, and Milan impose daily access fees that erode margin on standard delivery tiers.
- Payload-range tradeoffs:Electric van platforms sacrifice cargo capacity for battery weight, compressing per-vehicle revenue potential in bulky goods segments.
Strategic Opportunities
- India charging infrastructure:Central Electricity Authority standards are unlocking profitable EV fleet deployment in tier-2 cities where real estate costs support hub-and-spoke density.
- Refrigerated robotics:Convergence of solid-state cooling and autonomous ground vehicles creates white space in pharmaceutical and meal-kit delivery where temperature excursion liability currently blocks automation.
- California ZEV mandate:The state's Advanced Clean Trucks regulation creates guaranteed demand pull for electric van and medium-duty truck platforms through 2035.
Industry Challenges
- Telematics integration:Legacy warehouse management systems require expensive API reconfiguration to ingest real-time autonomous vehicle location and exception data.
- Autonomous liability frameworks:Unclear fault allocation between vehicle manufacturers, fleet operators, and municipal regulators is delaying commercial deployment at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | First and Last Mile Delivery Market |
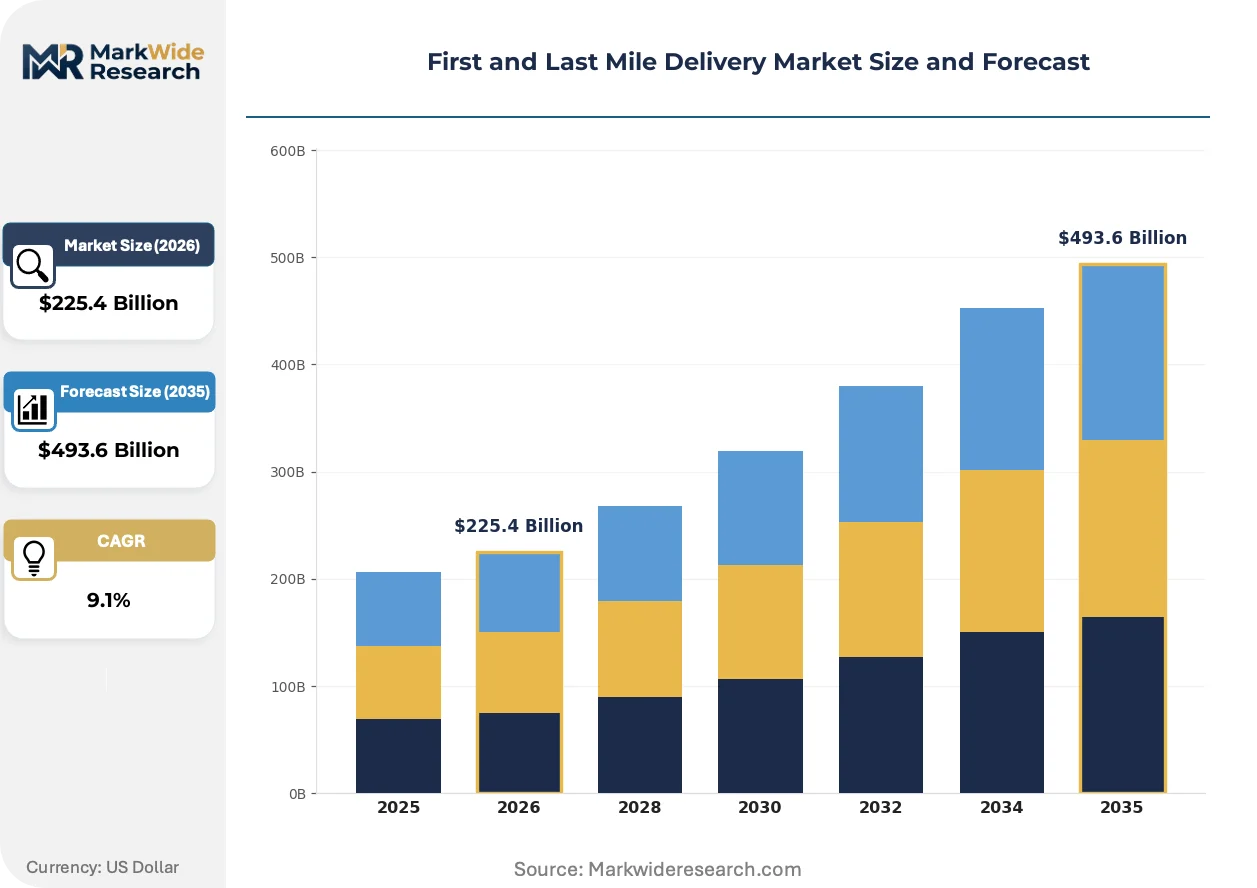
| Market Size in 2026 | $225.4 Billion |
| Market Size in 2035 | $493.6 Billion |
| CAGR (2026 – 2036) | 9.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Bike, Van, Drone, Cargo Robot, Electric Vehicle Service Type: Same Day, Next Day, Scheduled, Express, Standard Client Type: E-commerce Retailers, Third-Party Logistics, Food Chains, Courier Companies, Wholesalers Technology: Route Optimization, Real-time Tracking, Automated Dispatch, AI Analytics, Mobile Apps |
| Companies Covered | Amazon Prime Air, OneRail, FedEx Corporation, Zipline, Veho, United Parcel Service (UPS), Starship Technologies, Nuro, DHL Global Forwarding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
First and Last Mile Delivery Market Strategic Shifts & Innovations
Route optimization algorithms trained on congestion pricing data are reshaping how operators sequence deliveries, compressing dwell time in penalty zones while extending range through predictive charging.
Autonomous ground robots with curb-to-doorstep capability are absorbing short-haul residential volume that electric vans cannot serve profitably. Grocery and pharmacy chains in dense Japanese and Dutch suburbs are piloting these platforms at 50-vehicle scale. The technology is absorbing delivery cost structures below the threshold where human drivers remain viable.
The European Union's Corporate Sustainability Reporting Directive now mandates scope 3 emissions disclosure from logistics providers serving listed clients. Fleet operators must install telematics capable of granular CO2 calculation per parcel. Third-party carriers serving German and French retail are responding by accelerating electric vehicle share faster than total cost of ownership parity would otherwise justify.
Buyer procurement is consolidating around outcome-based contracts that penalize missed delivery windows rather than paying per-parcel rates. Large European appliance retailers are shifting from courier networks to captive or dedicated fleets that absorb reliability risk. This compression of switching cycles is most visible in Germany, where same-day promises have become table stakes for white-goods categories.
First and Last Mile Delivery Market Segmentation
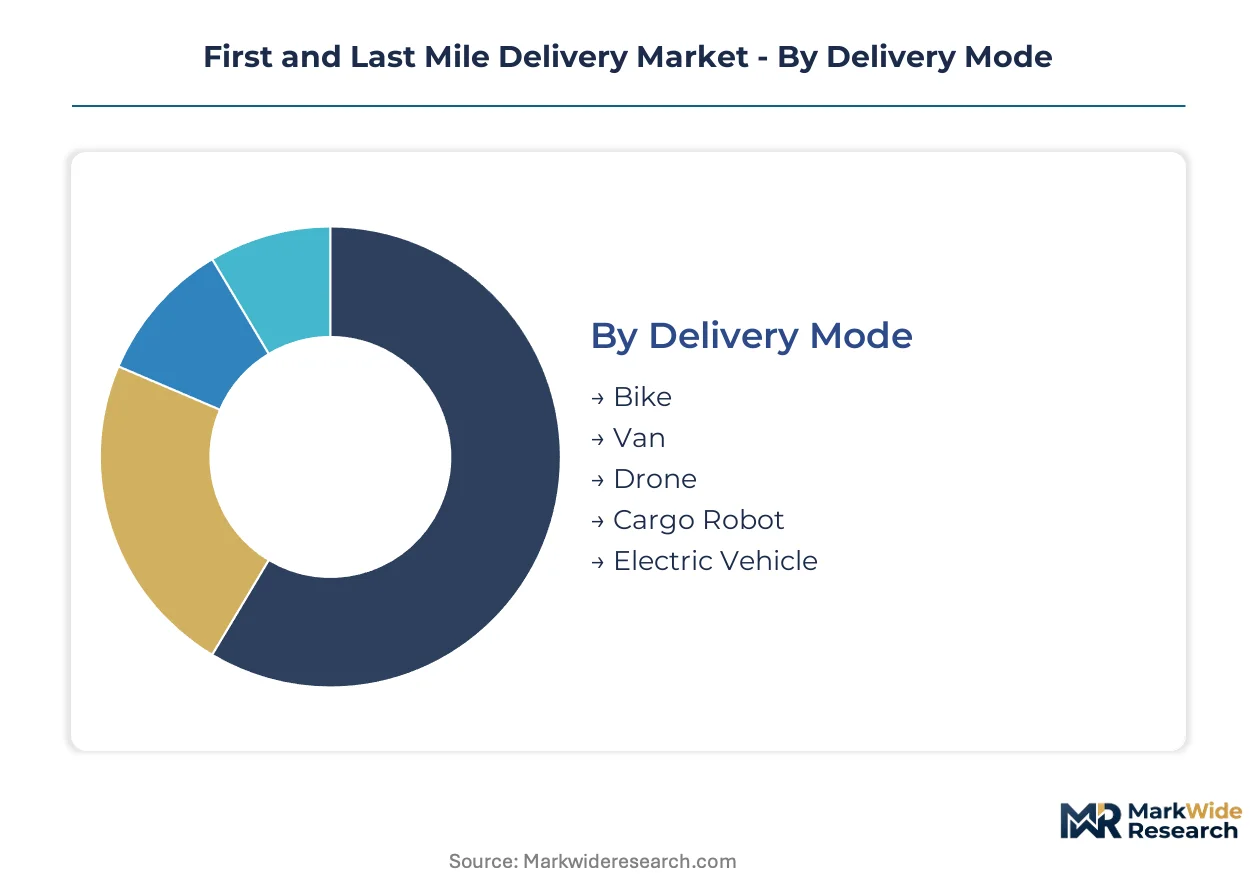
Delivery mode selection determines capital intensity and regulatory exposure for logistics operators. Service tier differentiation separates premium reliability guarantees from cost-optimized bulk movement. Client procurement patterns are consolidating around outcome-based contracts that penalize missed windows rather than rewarding parcel volume.
Delivery Mode:
Buyers in this category differentiate by payload requirements, emissions compliance deadlines, and urban access restrictions imposed by municipal regulators.
- Electric Vehicle:Battery-electric vans and trucks with 150-300 mile range dominate fleet replacement schedules in California and the European Union where zero-emission mandates compress procurement timelines. German logistics operators are absorbing premium vehicle costs to maintain access to Berlin and Munich low-emission zones where daily entry fees would otherwise erode route economics.
- Van:Internal combustion and hybrid panel vans retain cost advantages in developing markets and bulky goods segments where battery weight sacrifices cargo capacity. Indian third-party carriers deploy diesel vans across tier-2 and tier-3 corridors where charging infrastructure remains sparse and acquisition cost sensitivity blocks EV adoption.
- Bike:Cargo bicycles with 100-400 pound payloads serve dense urban cores in Amsterdam, Copenhagen, and central Tokyo where congestion pricing and narrow street grids block motorized access. Human-powered last mile absorbs pharmaceutical and meal-kit volume where temperature-controlled containers fit within payload limits.
- Drone:Autonomous aerial platforms with 5-10 pound payloads require FAA beyond-visual-line-of-sight waivers for suburban corridor expansion. Regulatory fragmentation across national aviation authorities delays cross-border standardization.
- Cargo Robot:Zero-occupant ground vehicles with curb-to-doorstep capability pilot at 50-unit scale in Japanese and Dutch suburbs. Solid-state cooling integration creates white space in pharmaceutical delivery where temperature excursion liability currently blocks automation.
Volume sits with Van; growth tilts toward Electric Vehicle.
Service Type:
Margin structure separates guaranteed delivery windows from flexible scheduling that optimizes fleet utilization across demand peaks.
- Same Day:Premium-priced fulfillment promises within 4-8 hours command 40-60% price multiples over standard tiers. Amazon Prime Air and captive e-commerce networks absorb reliability risk to secure customer loyalty in German and Brazilian urban corridors where courier handoffs introduce failure points.
- Express:Next-flight-out and dedicated vehicle dispatch for urgent documents and medical specimens sustain pricing power in B2B segments. FedEx ground hub infrastructure anchors next-day reliability at scale across North American metropolitan zones.
- Next Day:Guaranteed 24-hour delivery occupies the middle tier where warehouse positioning and route density determine profitability. Consolidation around regional fulfillment centers in India and Brazil compresses last-mile distances to enable cost-competitive overnight service.
- Scheduled:Appointment-based delivery for appliances and furniture reduces redelivery costs through precise customer coordination. White-goods retailers in France and Germany are shifting from courier networks to captive fleets that absorb reliability risk.
- Standard:2-5 day delivery with flexible windows optimizes truckload consolidation and minimizes per-parcel handling costs. Thin margins require volume density that concentrates with e-commerce platforms operating proprietary sortation infrastructure.
Revenue concentrates in Standard; margin expansion favors Same Day.
Client Type:
Procurement sophistication ranges from captive network operators seeking vertical control to asset-light intermediaries managing courier relationships.
- E-commerce Retailers:Amazon, Alibaba, and regional platforms are expanding proprietary delivery networks to reduce third-party carrier dependence. Captive fleet investments prioritize customer data capture and delivery experience control over pure cost minimization.
- Third-Party Logistics:DHL Supply Chain and GXO Logistics manage multi-client networks where shared infrastructure amortizes fixed costs. Outcome-based contracts with European appliance retailers are compressing switching cycles and accelerating dedicated fleet deployment.
- Food Chains:Quick-service and grocery operators require temperature-controlled last mile with 30-60 minute windows. Solid-state cooling convergence with autonomous ground vehicles addresses pharmaceutical and meal-kit segments where spoilage liability blocks full automation.
- Courier Companies:Traditional parcel carriers face volume diversion as e-commerce platforms internalize delivery. FedEx and UPS are restructuring ground hub networks to defend next-day reliability positioning against captive competitors.
- Wholesalers:B2B distribution networks serving independent retailers prioritize pallet-level efficiency over parcel granularity. Route optimization algorithms trained on congestion pricing data reshape sequencing to minimize dwell time in penalty zones.
Volume concentrates with E-commerce Retailers; contract value expands fastest with Third-Party Logistics.
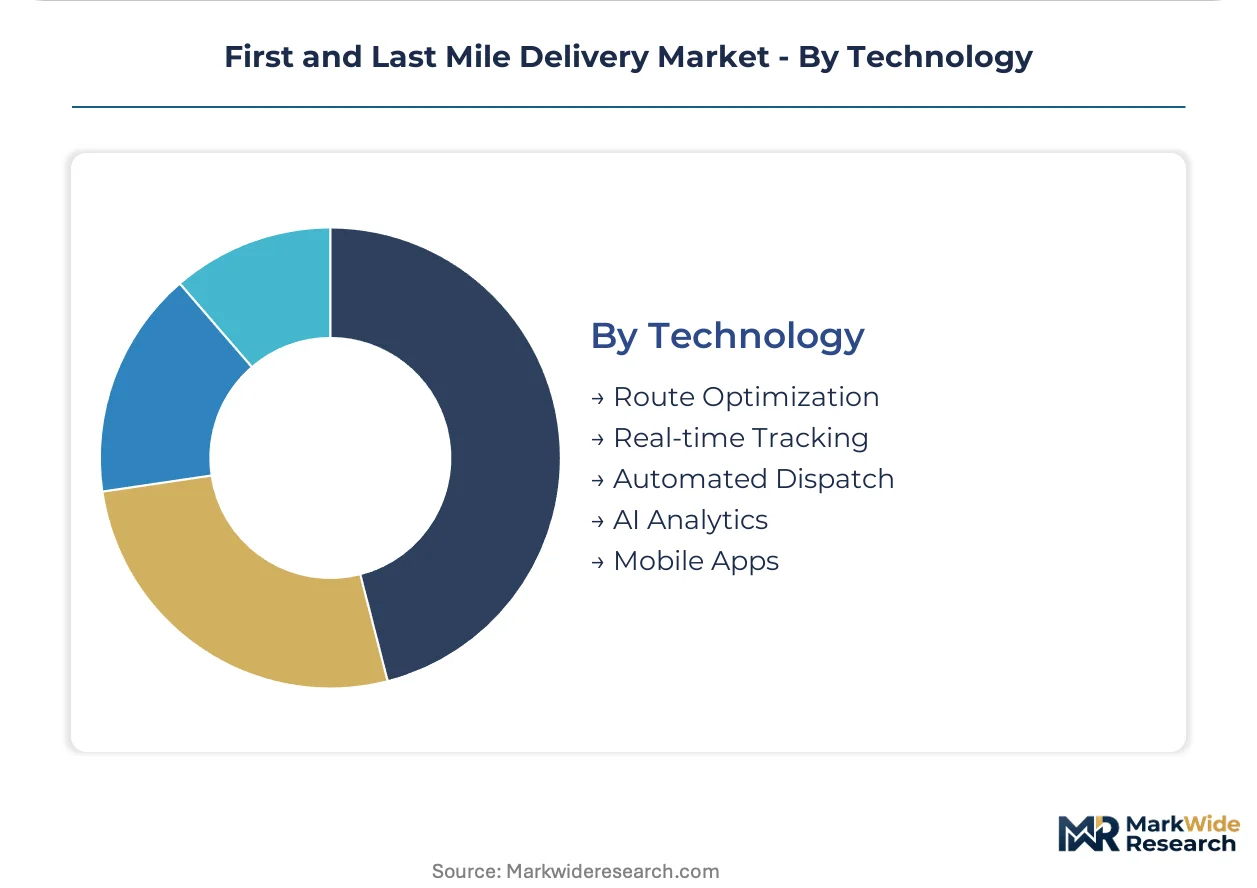
Technology:
Technology deployment separates operators capable of real-time network reconfiguration from those managing static route plans.
- Route Optimization:Machine learning algorithms ingest congestion pricing, weather, and demand signals to dynamically sequence deliveries. Predictive charging integration extends electric vehicle range by positioning stops near available infrastructure.
- Real-time Tracking:GPS and telematics platforms provide parcel-level visibility that underpins outcome-based contract enforcement. EU Corporate Sustainability Reporting Directive mandates scope 3 emissions disclosure requiring granular CO2 calculation per parcel.
- Automated Dispatch:AI-driven vehicle assignment matches shipment characteristics to available capacity without human intervention. Legacy warehouse management systems require expensive API reconfiguration to ingest autonomous vehicle exception data.
- AI Analytics:Demand forecasting models predict neighborhood-level volume to position inventory before orders materialize. Micro-fulfillment networks in German and Indian urban corridors bypass traditional courier handoffs through forward-stocked inventory.
- Mobile Apps:Driver-facing interfaces streamline proof-of-delivery capture and exception reporting. Customer apps with precise arrival windows reduce failed delivery rates and associated redelivery costs.
Adoption concentrates in Route Optimization; capability differentiation is shifting toward AI Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Dubai and Jebel Ali concentrate last-mile infrastructure investment across the Middle East corridor. Special economic zones in Shenzhen and Guangzhou anchor Asia-Pacific fulfillment density. India's Delhi-Mumbai Industrial Corridor reshapes logistics capital deployment through dedicated freight corridors and customs automation.
United States
E-commerce fulfillment density in Dallas-Fort Worth and Atlanta generates sufficient parcel volume for dedicated micro-fulfillment networks. The FAA governs drone altitude corridors and beyond-visual-line-of-sight waivers that determine suburban autonomous delivery expansion. Amazon Prime Air leverages regulatory progress to extend same-day reach into Arizona and Texas exurbs previously outside courier coverage windows.
Germany
Appliance retailers in Berlin and Munich are consolidating procurement around outcome-based contracts that penalize missed delivery windows. The EU F-Gas Regulation accelerates refrigeration unit electrification in cold-chain vehicles serving pharmaceutical distribution. DHL Supply Chain operates dedicated fleets for white-goods categories where same-day promises have become competitive table stakes.
India
Tier-2 cities including Pune and Hyderabad now generate enough e-commerce volume to justify hub-and-spoke EV deployment. The Central Electricity Authority frames charging infrastructure standards that determine profitable fleet positioning outside Delhi-Mumbai corridors. Flipkart and Amazon India expand captive last-mile networks to reduce third-party carrier dependence in Karnataka and Maharashtra.
Brazil
Urban corridors in São Paulo and Rio de Janeiro concentrate demand for express delivery in dense favela networks inaccessible to conventional vans. ANVISA regulates pharmaceutical cold-chain standards that shape refrigerated vehicle specifications for vaccine distribution. Mercado Libre invests in fulfillment center positioning to compress last-mile distances across Southeast metropolitan zones.
Japan
Aging demographics in Tokyo and Osaka suburbs drive demand for autonomous ground robots with curb-to-doorstep pharmacy delivery capability. METI oversees standards for zero-occupant vehicle testing that determines commercial deployment timelines. Starship Technologies pilots 50-vehicle fleets in dense Yokohama residential districts where labor costs block human-driver viability.
First and Last Mile Delivery Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with captive e-commerce networks pulling volume away from traditional courier infrastructure. The market structure tilts toward consolidation as Amazon, FedEx, and UPS absorb reliability risk through dedicated fleet investments. Three archetypes dominate: vertically integrated retailers operating proprietary logistics, asset-light technology platforms orchestrating third-party capacity, and legacy carriers defending hub-and-spoke density. Competitive moves concentrate on micro-fulfillment network expansion and autonomous vehicle regulatory pre-positioning.
Within the technology-platform tier, Nuro and Starship Technologies occupy positions defined by zero-occupant vehicle design and curb-to-doorstep automation. Among legacy carriers, FedEx Corporation and United Parcel Service anchor ground infrastructure investments that sustain next-day reliability at scale. Amazon Prime Air represents the vertically integrated retailer archetype, leveraging autonomous drone development to bypass traditional courier handoffs entirely.
| Leading Market Players |
|---|
| Amazon Prime Air |
| OneRail |
| FedEx Corporation |
| Zipline |
| Veho |
| United Parcel Service (UPS) |
| Starship Technologies |
| Nuro |
| DHL Global Forwarding |
| Others |
Cost & Logistics Intelligence
E-commerce platform procurement concentration tilts pricing power toward volume buyers who negotiate outcome-based contracts penalizing missed delivery windows rather than paying per-parcel rates. This buyer leverage compresses margins for third-party carriers while rewarding captive fleet operators who absorb reliability risk.
Pricing Analysis
Lead-time-driven pricing stratification separates premium same-day tiers commanding substantial multiples from standard delivery absorbing volume at thinner margins. Price differentiation hinges on delivery window guarantees and emissions compliance certification, with zero-emission vehicle access to municipal low-emission zones becoming a tier-defining factor. Cost compression in standard tiers intensifies as e-commerce retailers internalize delivery networks and squeeze third-party carrier rates. Third-party logistics providers face acute price sensitivity, while captive e-commerce fleets prioritize customer data capture over pure cost minimization.
Supply Chain Analysis
Lithium-ion battery supply rests on Chinese cathode processing and South Korean cell manufacturing, with Australian spodumene mining feeding upstream material flows. Electric drivetrain components and solid-state cooling systems for refrigerated robotics constitute critical dependencies alongside charging infrastructure hardware. Single-source vulnerability in battery raw material processing exposes fleet electrification timelines to geopolitical friction and input cost volatility. Distribution runs through regional fulfillment center networks that compress last-mile distances and bypass traditional courier handoffs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
First and last mile delivery is becoming a vertical-integration race where e-commerce retailers pursue captive fleet control to capture customer data and guarantee delivery experience, displacing traditional carrier intermediation.
For Market Incumbents: Acquire charging infrastructure assets and micro-fulfillment real estate to defend against e-commerce platform internalization. Lock in long-term access to Berlin, Munich, and California low-emission zones through zero-emission fleet commitments. Secure API integration capabilities with legacy warehouse management systems to maintain relevance as autonomous vehicle deployment scales. For New Entrants and Emerging Players: The gap between premium same-day pricing and economy standard tiers creates entry space for specialized autonomous ground vehicle operators. Target tier-2 Indian cities where Central Electricity Authority charging standards unlock profitable EV deployment ahead of incumbent saturation. Lead with pharmaceutical and meal-kit cold-chain automation where temperature excursion liability currently blocks full market penetration. For Investors and Strategic Acquirers: The window for entry favors technology-platform archetypes orchestrating third-party capacity rather than asset-heavy fleet operators. Solid-state cooling convergence with autonomous navigation represents the most defensible capability stack over the medium term. Watch FAA beyond-visual-line-of-sight waiver expansion as the signal indicating regulatory readiness for suburban autonomous delivery at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Network Expansion | Flipkart and Amazon India compress last-mile distances through forward-stocked inventory in Pune and Hyderabad. |
| Zero-Emission Fleet Procurement | DHL Supply Chain absorbs premium vehicle costs to maintain access to German low-emission zones. |
| Autonomous Vehicle Regulatory Pre-Positioning | Nuro and Starship Technologies secure testing permits ahead of commercial liability framework crystallization. |
| API Integration with Legacy WMS | Telematics providers reconfigure data ingestion architectures to capture autonomous vehicle exception signals. |
| Cold-Chain Robotics Development | Convergence of solid-state cooling and ground autonomy addresses pharmaceutical temperature excursion liability. |
Research Approach
Trade databases, regulatory filings, and fleet operator disclosures formed the secondary backbone, supplemented by primary interviews with logistics procurement directors, fleet operations managers, charging infrastructure developers, and municipal transport planners. Triangulation across bottom-up volume modeling and top-down macroeconomic validation anchored market sizing. Primary fieldwork captured outcome-based contract structures and electrification capex timelines from German, Indian, and Brazilian operators.
Historical trendline analysis of parcel volume density and fleet composition shifts informed projection frameworks across delivery mode, service tier, and client type segmentation dimensions. Modeled CAGRs derived from urban corridor saturation curves, regulatory mandate phase-in schedules, and autonomous vehicle readiness assessments. Forecast inputs incorporated EU F-Gas Regulation compliance costs and FAA waiver expansion trajectories.
Underlying measurement precision varies by segment; electric vehicle and cargo robot adoption curves carry tighter precision than drone deployment given regulatory uncertainty. Forecasts reflect assumptions around charging infrastructure buildout pace and municipal low-emission zone expansion schedules. Geopolitical friction in battery supply chains and autonomous liability framework delays warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
Repositioning and Offloading Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market