
 Hungary Facility Management Market | 2026-2036
Hungary Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary Facility Management Market Foresight
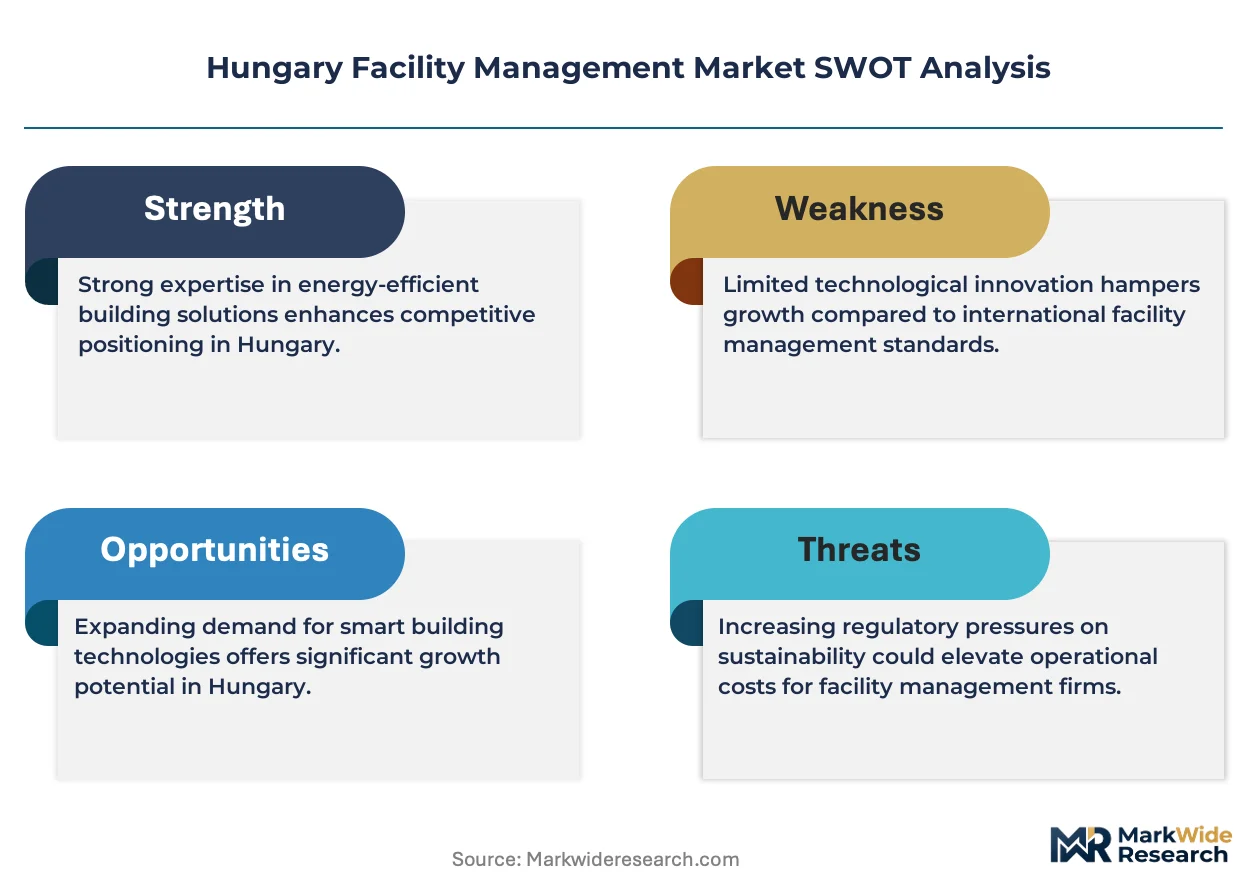
EU Energy Performance of Buildings Directive transposition into Hungarian law is hardening compliance thresholds for commercial building operators. B+N Referencia Zrt leverages its domestic service network to anchor large institutional contracts across Budapest's hospital and university estates. ISS Global competes through integrated service bundles that span cleaning, security, and technical maintenance under single-account structures. Future FM Zrt specializes in smart building technology deployment, positioning itself ahead of software-driven procurement trends.
Facility management encompasses the coordination of physical workplace services including HVAC maintenance, cleaning protocols, security operations, and energy systems oversight, typically governed by service level agreements specifying response times and performance metrics. The field serves to optimize building lifecycle costs while ensuring regulatory compliance and occupant productivity across commercial and institutional assets. Cleaning and maintenance services within the Service Type dimension occupy the largest contract value share due to recurring labor requirements and mandatory hygiene standards. IoT Solutions and Smart Building Systems across the Technology dimension represent the fastest-growing procurement category as Hungarian property managers seek predictive maintenance capabilities and real-time energy monitoring. The Commercial end-user segment sustains the deepest margin pools, driven by multinational tenants demanding standardized service levels across regional office portfolios.
BIS certification requirements for building systems equipment intersect with Hungary's adoption of EU Green Deal implementation frameworks, tightening product standards for HVAC and automation components entering the market. Hungary's national building energy regulator enforces progressive audit cycles that directly expand recurring FM contract scopes for compliance documentation and retrofit execution. Stakeholders must monitor how EU CSRD reporting obligations cascade into tenant demands for verified building performance data, reshaping provider capability requirements and contract pricing structures.
Market Dynamics
EU Energy Performance of Buildings Directive transposition is compressing procurement cycles for Hungarian commercial real estate operators, forcing rapid technology upgrades across Budapest's aging office stock and institutional portfolios.
Growth Catalysts
- EU Green Deal implementation frameworks:Hungary's national building energy regulator enforces progressive audit cycles that expand recurring FM contract scopes for compliance documentation and retrofit execution.
- Smart building technology deployment:IoT-enabled predictive maintenance systems are displacing reactive service models across Central Hungary's industrial parks and logistics facilities.
- Central Hungary concentration:Budapest's office stock and university estates generate contract volume that anchors provider network investments and service capability builds.
Market Restraints
- Skilled technician scarcity:HVAC and automation specialist wages are rising faster than contract pricing allows, compressing margins for labor-intensive maintenance services.
- BIS certification compliance costs:Equipment import standards for building systems tighten product qualification timelines and raise procurement thresholds for mid-sized operators.
- Energy price volatility:Natural gas and electricity input cost swings destabilize energy performance guarantees that underpin long-term FM contracts.
Strategic Opportunities
- Western Hungary industrial corridor:Underpenetrated manufacturing zones near Győr and Székesfehérvár present whitespace for integrated FM providers with automotive sector expertise.
- CSRD reporting obligations:EU Corporate Sustainability Reporting Directive mandates cascade into tenant demands for verified building performance data, creating premium service tiers.
- Digital twin convergence:Building information modeling fused with real-time sensor networks enables outcome-based contracting that ties provider compensation to measurable efficiency gains.
Industry Challenges
- Bilingual technical workforce gaps:Multinational tenant requirements for English-speaking engineering staff outstrip supply in secondary Hungarian cities outside Budapest.
- Legacy system integration friction:Soviet-era building infrastructure resists sensor retrofit, forcing costly parallel monitoring architectures during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary Facility Management Market |
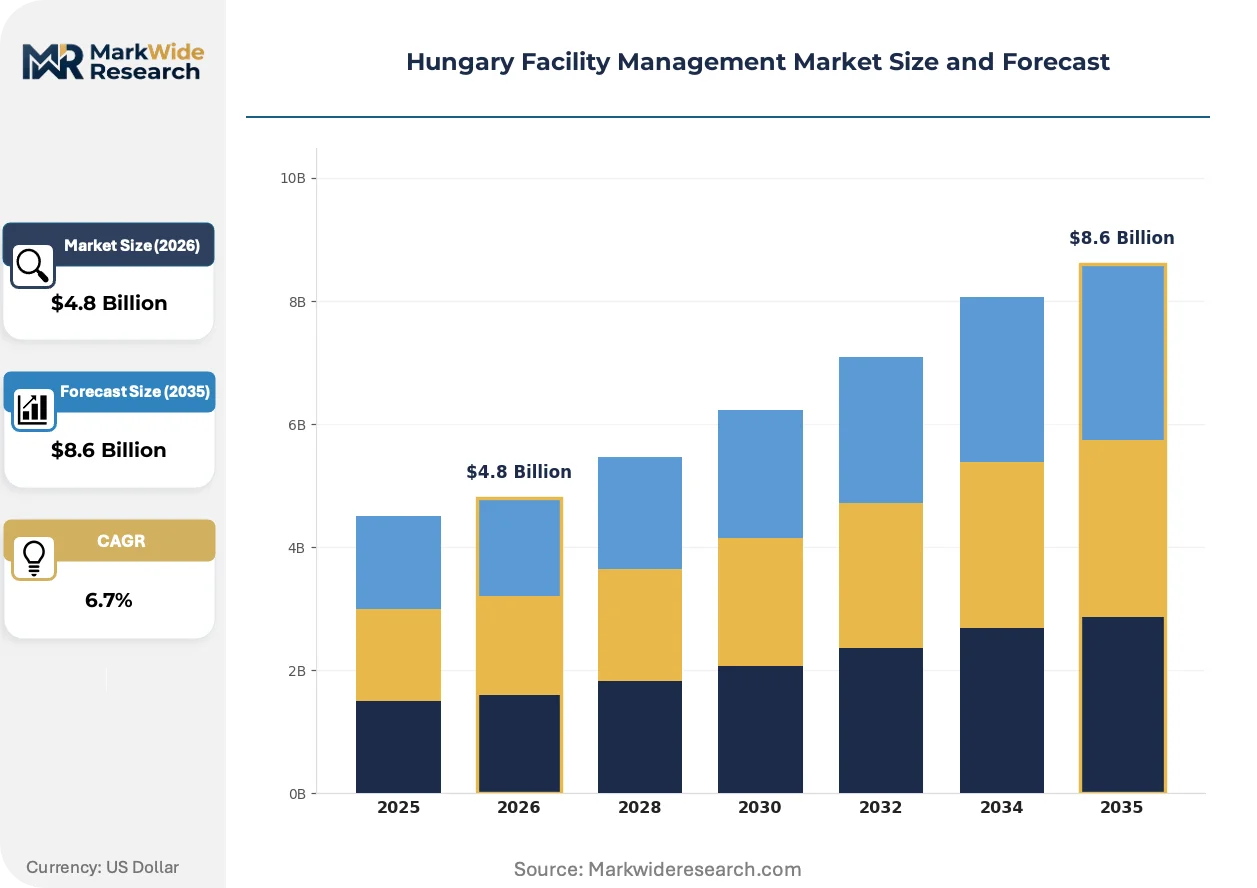
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Waste Management End User: Commercial, Residential, Institutional, Industrial Technology: IoT Solutions, Software, Smart Building Systems, Automation Facility Type: Office, Retail, Hospital, Educational |
| Companies Covered | CBRE Group, B+N Referencia Zrt, ISS Global, Future FM Zrt, Apleona GmbH, Jones Lang LaSalle IP Inc, Sodexo Facilities Management Services, Compass Group PLC, Vinci Facilities Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary Facility Management Market Shifts & Advancements
Software-defined building operations are displacing schedule-based maintenance across Hungarian commercial real estate, compressing response times while raising data architecture requirements for FM providers.
Predictive analytics platforms are integrating machine learning models with HVAC sensor networks to flag equipment degradation before failure. Budapest office landlords with multinational tenants are adopting these systems fastest, driven by lease clauses penalizing downtime. The technology is integrating facilities teams into tenant sustainability reporting workflows, blurring traditional service boundaries.
Hungary's transposition of EU Energy Performance of Buildings Directive requirements hardens compliance thresholds for commercial building operators. The national regulator mandates progressive energy audits that expand documentation burdens and retrofit execution scopes. Hospital and university estates in Central Hungary face the tightest deadlines, accelerating procurement for bundled technical and compliance services.
Facility management contracting is fragmenting into specialized service modules as tenants unbundle integrated agreements. Multinational corporations with regional Hungarian operations now source cleaning, security, and technical maintenance through separate vendor relationships. This pattern concentrates in Budapest's premium office segment, where standardized global procurement policies override local bundled offerings.
Hungary Facility Management Market Segmentation
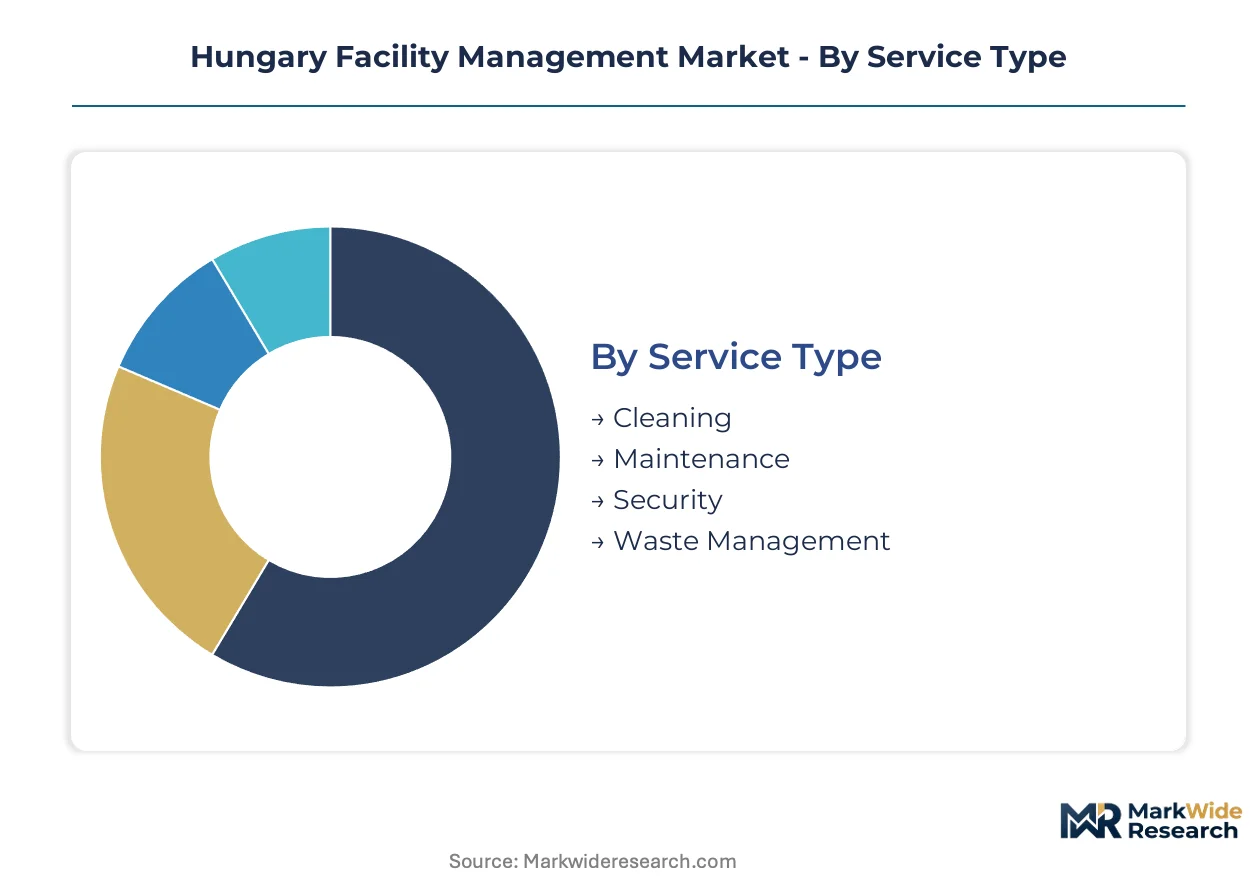
Facility management providers in Hungary configure service portfolios around distinct operational requirements. Each segmentation dimension reveals divergent margin structures and capability demands that shape competitive positioning.
Service Type:
Volume-heavy labor services dominate contract value, while technology-enabled offerings command premium pricing tiers.
- Cleaning:Labor-intensive protocols governed by mandatory hygiene standards across Budapest's hospital and university estates. Recurring staffing requirements generate predictable revenue streams but compress margins as wage inflation outpaces contract escalation clauses.
- Maintenance:HVAC and building systems oversight tied to EU Energy Performance of Buildings Directive compliance deadlines. Central Hungary's aging office stock drives demand for bundled technical and retrofit execution services.
- Security:Personnel-based guarding and access control systems deployed across commercial portfolios. Multinational tenants demand standardized protocols that override local provider preferences.
- Waste Management:Collection and disposal services integrated with sustainability reporting requirements. Regulatory documentation burdens expand contract scopes beyond pure logistics.
Mature deployment sits with Cleaning. Newer deployment is concentrated in Maintenance.
End User:
Customer concentration patterns split between yield-focused commercial operators and compliance-driven institutional estates.
- Commercial:Office and retail landlords with multinational tenants demanding standardized service levels. Lease structures penalize downtime, accelerating procurement of predictive maintenance capabilities.
- Industrial:Manufacturing and logistics facilities in Central Hungary's industrial parks. Energy performance guarantees underpin long-term contracts with volatile input cost exposure.
- Institutional:Hospital and university estates facing the tightest EU directive transposition deadlines. Public procurement cycles favor established domestic networks with compliance documentation expertise.
- Residential:Property management companies and homeowner associations with cost-sensitive procurement. Fragmented ownership structures resist bundled service adoption.
Revenue concentration rests with Commercial. Capability investment is accelerating fastest in Institutional.
Technology:
Procurement cycles separate legacy infrastructure retrofits from native smart building deployments.
- IoT Solutions:Sensor networks enabling predictive maintenance and real-time energy monitoring. Budapest office landlords adopt these systems fastest to satisfy lease penalty clauses and sustainability reporting workflows.
- Smart Building Systems:Integrated platforms spanning HVAC, lighting, and access control with centralized oversight. Western Hungary's newer industrial corridor developments deploy these natively.
- Software:Computerized maintenance management systems and asset tracking platforms. Mid-sized operators face qualification timeline pressures from tightening BIS certification requirements.
- Automation:Robotic cleaning systems and unmanned security patrols. Labor scarcity in secondary cities drives pilot deployments despite integration friction with Soviet-era building infrastructure.
Installed base concentrates in Software. Steepest expansion trajectory belongs to IoT Solutions.
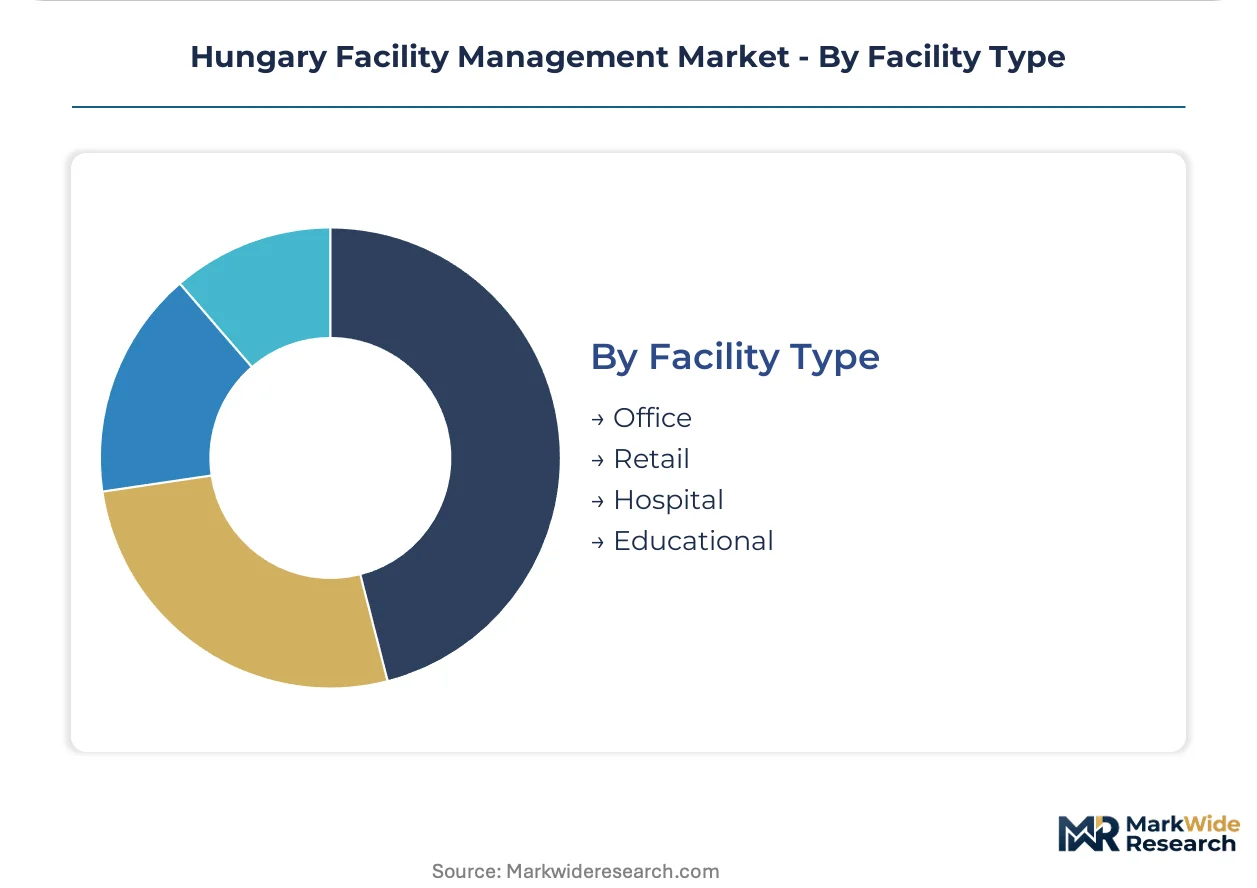
Facility Type:
Asset vintage and tenant sophistication create divergent technology readiness profiles across building categories.
- Office:Premium stock in Budapest's central business district with multinational occupancy. Standardized global procurement policies fragment contracts into specialized service modules.
- Hospital:Public health estates with stringent hygiene and equipment uptime requirements. Progressive audit cycles from Hungary's national building energy regulator expand compliance documentation scopes.
- Educational:University campuses combining aging infrastructure with sustainability commitments. Energy retrofit mandates tighten as EU Green Deal implementation frameworks harden.
- Retail:Shopping centers and high-street formats with high footfall cleaning demands. Lease structures tie service levels to tenant revenue performance.
Contract maturity sits with Office. Technology procurement is advancing fastest in Hospital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Budapest's special economic zones and industrial parks concentrate Hungary's facility management contract value, with Central Hungary generating the majority of procurement volume through its office stock and logistics corridors.
Central Hungary
Budapest's premium office districts and university estates drive bundled FM service demand. The national building energy regulator enforces progressive audit cycles that expand compliance documentation scopes. Váci Corridor industrial parks anchor integrated maintenance contracts for automotive and electronics manufacturing facilities.
Western Hungary
Manufacturing zones near Győr and Székesfehérvár present whitespace for automotive-sector FM specialists. EU Green Deal implementation frameworks tighten energy retrofit mandates across this industrial corridor. Audi Hungaria's supplier network generates demand for predictive maintenance and energy performance guarantees.
Southern Hungary
Pécs and Szeged university hospitals face accelerated EU Energy Performance of Buildings Directive compliance deadlines. Public procurement cycles favor established domestic networks with regulatory documentation expertise. Clinical facility energy audits expand recurring contract scopes for technical and compliance services.
Northern Hungary
Miskolc's legacy industrial infrastructure resists smart building retrofits, forcing parallel monitoring architectures during transition periods. Skilled technician scarcity compresses margins for HVAC and automation services outside Budapest. Soviet-era building stock creates integration friction for IoT-enabled predictive maintenance deployment.
Lake Balaton Region
Seasonal hospitality and residential property management resists year-round bundled service adoption. Fragmented ownership structures favor cost-sensitive procurement of discrete cleaning and maintenance modules. Tourism-driven facility cycles concentrate demand in peak summer months with limited contract continuity.
Hungary Facility Management Market Competitive Landscape
Domestic Hungarian providers anchor the mid-market tier; international specialists hold premium positions in Budapest's multinational-occupied commercial stock. The vendor base splits between integrated service bundlers and technology-focused niche operators. Three archetypes dominate: compliance-heavy institutional specialists, scale-driven integrated multinationals, and smart-building technology deployers. Competitive moves center on M&A for geographic coverage and strategic partnerships for digital capability access.
Within the domestic specialist tier, B+N Referencia Zrt exemplifies the institutional compliance archetype through its hospital and university estate concentration. ISS Global and Future FM Zrt occupy differentiated positions—ISS representing integrated service bundling across cleaning, security, and technical maintenance, while Future FM anchors the smart-building technology deployment vector. These three companies collectively illustrate the competitive segmentation between labor-intensive compliance services and software-driven procurement trends reshaping Hungarian FM contracting.
| Leading Market Players |
|---|
| CBRE Group |
| B+N Referencia Zrt |
| ISS Global |
| Future FM Zrt |
| Apleona GmbH |
| Jones Lang LaSalle IP Inc |
| Sodexo Facilities Management Services |
| Compass Group PLC |
| Vinci Facilities Limited |
| Others |
Supply & Pricing Matrix
IoT-enabled predictive maintenance deployment across Budapest's commercial portfolios compresses cost economics for sensor hardware while concentrating procurement power among technology-integrated FM providers capable of bundling software with labor services. Hungary's national building energy regulator mandates progressive audit cycles that simultaneously expand compliance documentation scopes and reward providers with established regulatory relationships.
Pricing Analysis
Short lead-time premiums for BIS-certified HVAC and automation components command 15-25% markups over standard procurement timelines, while spot inventory of Soviet-era building system spares trades at distressed discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in labor-intensive maintenance tiers is intensifying because skilled technician wages outpace contract escalation clauses. Multinational tenants in Budapest's premium office segment exhibit least price sensitivity due to standardized global procurement policies; residential property management companies and homeowner associations demonstrate highest sensitivity with fragmented, cost-driven purchasing.
Supply Chain Analysis
Freight cost volatility from German and Austrian HVAC component suppliers into Central Hungary compresses margins for mid-sized operators lacking volume-scale logistics contracts. Equipment sourcing draws from Germany, Austria, and Czech Republic for building automation systems; sensor hardware feeds from Chinese and Taiwanese manufacturers. Single-source vulnerability concentrates in BIS certification compliance for imported building systems equipment. Distribution runs through Budapest-based technical distributors serving Váci Corridor industrial parks, with secondary logistics nodes in Győr and Székesfehérvár anchoring Western Hungary manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into software development capabilities and captive technician training programs defines competitive positioning as EU Energy Performance of Buildings Directive compliance hardens capability requirements. Providers are racing upstream into predictive analytics platforms and downstream into outcome-based contracting structures.
For Market Incumbents: To counter unbundling pressure from multinational tenants fragmenting integrated FM contracts into specialized service modules, anchor Budapest hospital and university estates through compliance documentation expertise while building backward integration into smart building software development. Deepen technician training pipelines to offset wage inflation compression in HVAC and automation services.
For New Entrants and Emerging Players: Capture whitespace in Western Hungary's automotive supplier corridor near Győr and Székesfehérvár, where predictive maintenance and energy performance guarantees outstrip established provider coverage. Target institutional healthcare estates in Pécs and Szeged facing accelerated EU directive deadlines. Lead with energy audit compliance bundling to bypass incumbent relationship advantages.
For Investors and Strategic Acquirers: Exit pathways concentrate in technology-enabled FM specialists with proven IoT deployment track records and established regulatory documentation capabilities. Long-term viability hinges on software-driven procurement trends displacing schedule-based maintenance models. Watch for inflection when EU CSRD reporting obligations cascade into mandatory verified building performance data requirements, reshaping provider capability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building Technology Acquisition | Accelerates predictive maintenance deployment ahead of EU Green Deal retrofit mandates tightening across Budapest office stock. |
| Technician Training Pipeline Buildout | Offsets skilled labor scarcity compressing margins in HVAC and automation services outside Central Hungary. |
| Compliance Documentation Platform Development | Captures recurring revenue from Hungary's national building energy regulator audit cycle expansion. |
| Western Hungary Geographic Expansion | Penetrates under-served automotive supplier corridor near Győr with integrated FM and energy performance guarantees. |
| Outcome-Based Contracting Structure Pilot | Ties provider compensation to measurable efficiency gains through digital twin convergence with real-time sensor networks. |
Research Methodology
Independent corroboration across FM provider executives, building portfolio managers, and national regulator officials underwrites the qualitative findings, validated against Hungary's building energy audit disclosure records, EU Energy Performance of Buildings Directive transposition documentation, and commercial real estate leasing databases. Primary interviews with hospital estate directors, university facility managers, and industrial park operators combined with secondary validation from Hungarian Central Statistical Office construction activity reports and Budapest Chamber of Commerce service sector analyses. Bottom-up contract value aggregation and top-down market sizing triangulation anchor quantitative outputs.
Comparable-period anchoring to historical facility management procurement cycles across Budapest's office stock and Central Hungary industrial parks established baseline growth trajectories. Segmentation modeling spans service type, end user category, technology deployment tier, and facility vintage across the projection horizon. CAGRs derive from regression analysis of contract value expansion correlated with EU Green Deal implementation milestones and energy retrofit mandate acceleration. Forecast inputs incorporate skilled technician wage trajectory assumptions and BIS certification timeline compression for building systems equipment.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to energy price volatility destabilizing performance guarantees and EU CSRD reporting obligation enforcement timing. Forecasts reflect documented assumptions about technology adoption curves and regulatory compliance acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Europe Soft Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Chile Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Spain Facility Management Market
Facility Management
Indonesia Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Japan Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
Bahrain Facility Management Market
Facility Management
GCC Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Asia Pacific Facility Management Market