
 Chile Facility Management Market | 2026-2036
Chile Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Facility Management Market Outlook
Building automation integration with legacy HVAC infrastructure is narrowing the technical gap between premium and mid-tier facility service providers in Chile. Sodexo Servicios de Gestión Chile SpA leverages its energy management expertise to anchor long-term contracts with mining camp operators in the north. ISS Chile S.A. competes through specialized security and cleaning bundles tailored to Santiago's financial district towers. CBRE Group extends its platform into hybrid delivery models that blend on-site staffing with remote building analytics.
Facility management encompasses the coordinated oversight of physical assets, operational services, and building systems to ensure safe, efficient, and compliant commercial and industrial environments. Technical parameters include energy performance benchmarking, preventive maintenance scheduling, and integrated workplace management systems that monitor occupancy, air quality, and equipment lifecycle. Outsourced service delivery dominates contract value as mining corporations and commercial landlords seek to transfer capital risk and labor compliance to specialized operators. Automation and IoT deployment within the technology segment represents the fastest-expanding margin pool, though HVAC and energy management retain the largest installed base across Chile's aging building stock.
Chile's Superintendencia de Electricidad y Combustibles enforces energy efficiency standards that shape retrofit demand and equipment specification for commercial buildings. The Ministerio del Trabajo y Previsión Social regulates subcontracting arrangements, directly influencing whether facility services remain in-house or shift to outsourced managed services. Labor code reforms and municipal environmental ordinances in Valparaíso, Santiago, and Antofagasta add compliance layers that favor established providers with legal and safety infrastructure. Stakeholders must weigh automation investment cycles against the fragmented subcontractor landscape when structuring service partnerships across Chile's geographically dispersed industrial footprint.
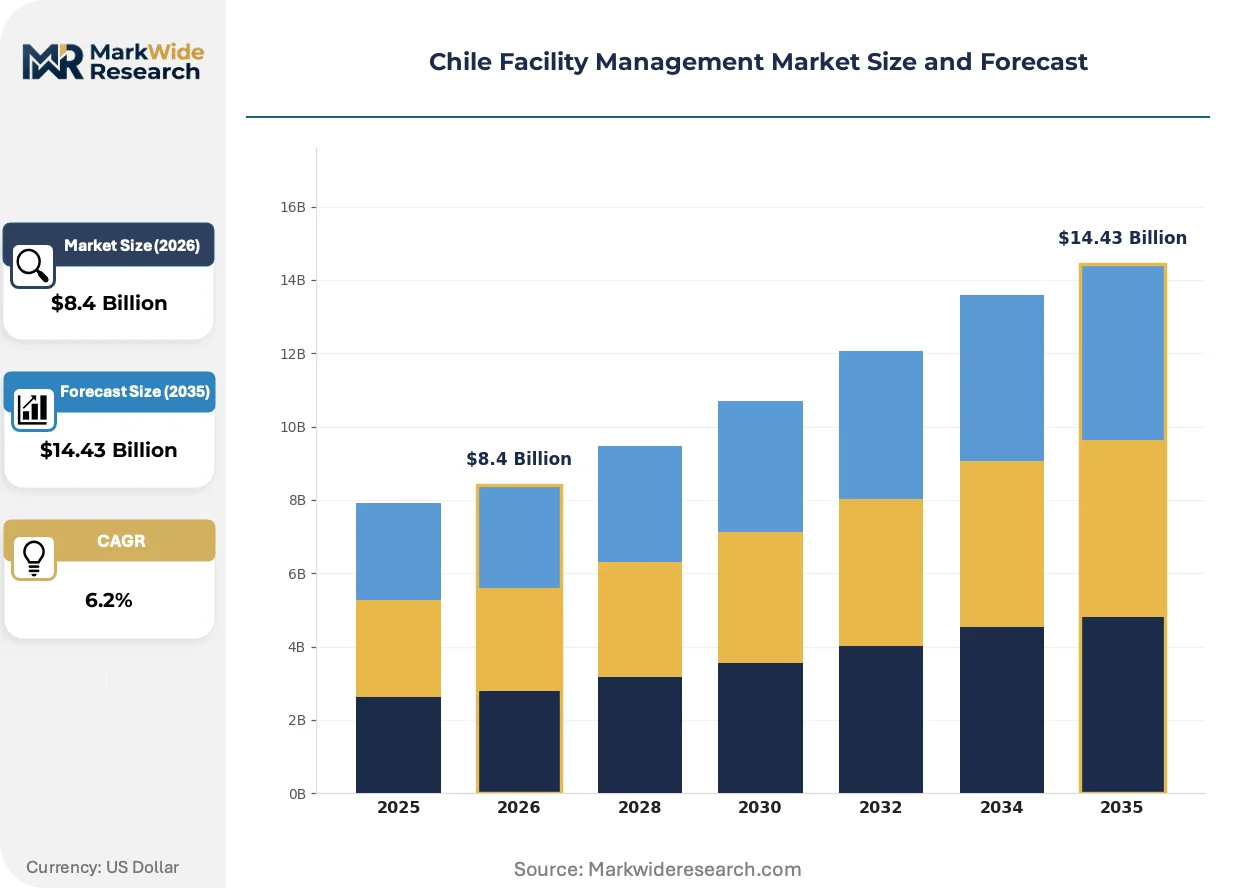
Market Dynamics
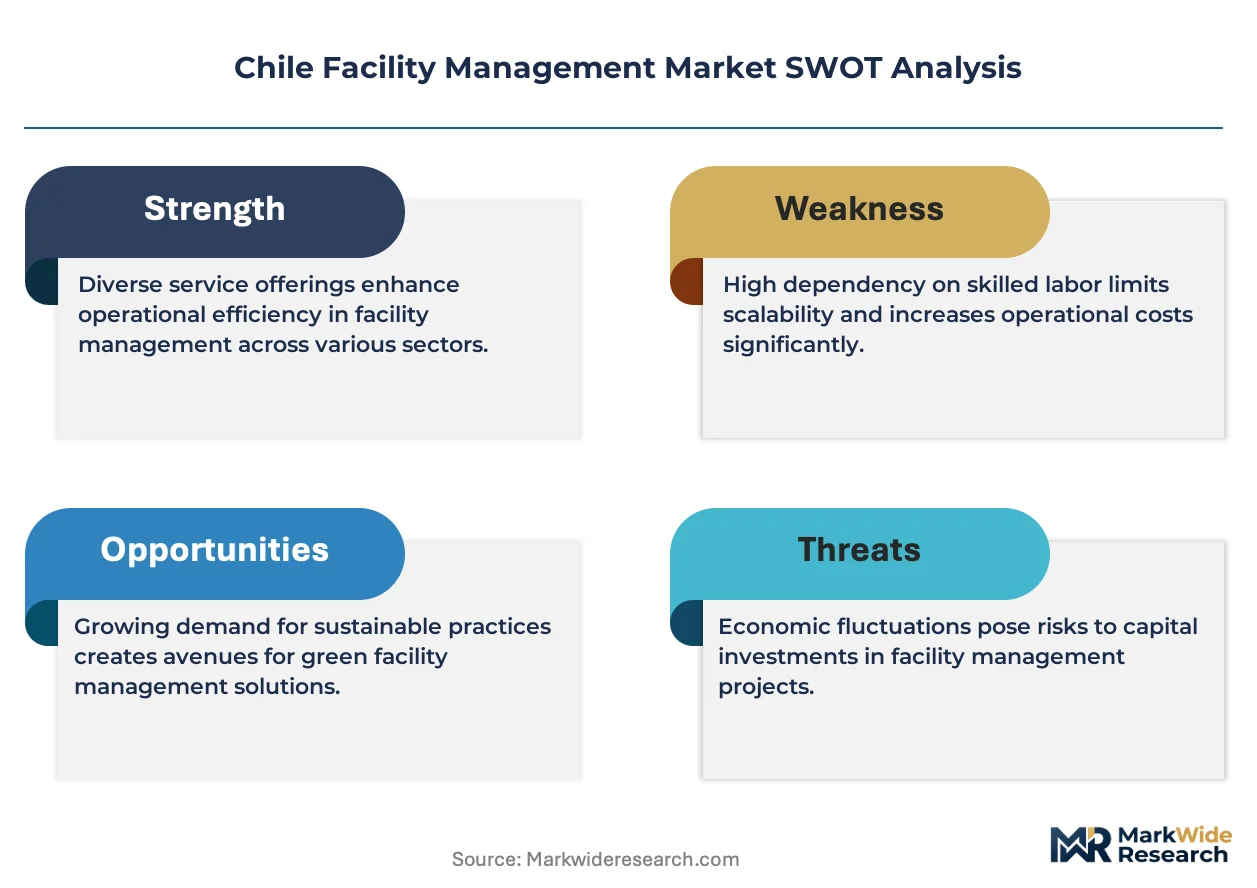
Chile's facility management sector faces structural pressure from the Ministerio de Energía's escalating efficiency mandates, which force rapid building automation deployment against aging HVAC infrastructure and fragmented subcontractor networks.
Growth Catalysts
- Atacama Mining Expansion:Copper and lithium extraction operators across Chile's northern desert are outsourcing entire camp operations to specialized facility managers, transferring labor compliance and capital risk.
- Ministerio de Energía Retrofit Mandates:Updated efficiency standards are accelerating building automation tenders in Santiago's commercial towers, creating sustained equipment upgrade cycles.
- IoT Sensor Networks:Predictive maintenance platforms using real-time equipment monitoring are reducing downtime for Antofagasta processing facilities and Valparaíso logistics hubs.
Market Restraints
- Copper Price Volatility:Mining sector capital budgets fluctuate with London Metal Exchange pricing, compressing multi-year facility service contracts during downturns.
- Santiago Subcontractor Fragmentation:Small regional maintenance providers lack certification depth for integrated workplace management systems, limiting quality standardization.
- Legacy HVAC Interoperability:Proprietary control protocols from 1990s-era installations block seamless integration with modern building automation platforms.
Strategic Opportunities
- Antofagasta Renewable Integration:Solar and wind facility management contracts are emerging as energy developers require specialized asset oversight for remote generation sites.
- Ministerio del Trabajo Compliance Bundles:Outsourced providers can capture value by packaging safety certification, payroll administration, and environmental reporting for mid-sized industrial clients.
- Digital Twin Convergence:Combining BIM models with live sensor feeds enables remote facility diagnostics, reducing on-site staffing requirements for dispersed mining operations.
Industry Challenges
- Certified Automation Technician Shortage:Chile's vocational pipeline produces insufficient building systems specialists familiar with BACnet and Modbus protocols.
- Municipal Ordinance Variability:Valparaíso, Santiago, and Antofagasta maintain divergent environmental and safety enforcement standards, complicating national contract standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Facility Management Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping Customer Type: Commercial, Residential, Government, Educational Technology: Automation, IoT, Energy Management, HVAC Delivery Model: Outsourced, In-House, Hybrid, Managed Services |
| Companies Covered | Grupo EULEN Chile S.A., Jones Lang LaSalle IP, Inc., ISS Chile S.A., Compass Group Chile Ltda., Cushman & Wakefield, Sodexo Servicios de Gestión Chile SpA, CBRE Group, Mancorp, Aramark Servicios y Aseo Chile SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Facility Management Market Strategic Shifts
Facility management in Chile is pivoting from labor-intensive service delivery toward technology-augmented oversight, driven by mining sector remote operations requirements and metropolitan energy compliance deadlines.
Cloud-based building management platforms are virtualizing control room functions for Santiago commercial towers and northern mining camps. Codelco and BHP are piloting centralized monitoring hubs that aggregate HVAC, security, and fire safety data from dispersed sites. This architecture is virtualizing the traditional on-site facility manager role, compressing headcount requirements while expanding geographic coverage per operator.
Chile's Superintendencia de Electricidad y Combustibles is tightening enforcement of energy efficiency standards for commercial buildings over 500 square meters. The regulation is triggering wholesale automation retrofits in Santiago's financial district, where landlords must demonstrate compliance to maintain operating licenses. Property managers are responding by bundling energy performance guarantees into long-term service contracts with technology-anchored providers.
Buyers are unbundling integrated facility contracts into specialized component purchases. Mining corporations now separately procure security, catering, maintenance, and energy management rather than accepting single-provider bundles. This fragmentation is most visible in Antofagasta and Atacama, where operators seek best-in-class performance for each function and are willing to coordinate multiple vendor relationships to achieve it.
Chile Facility Management Market Segmentation
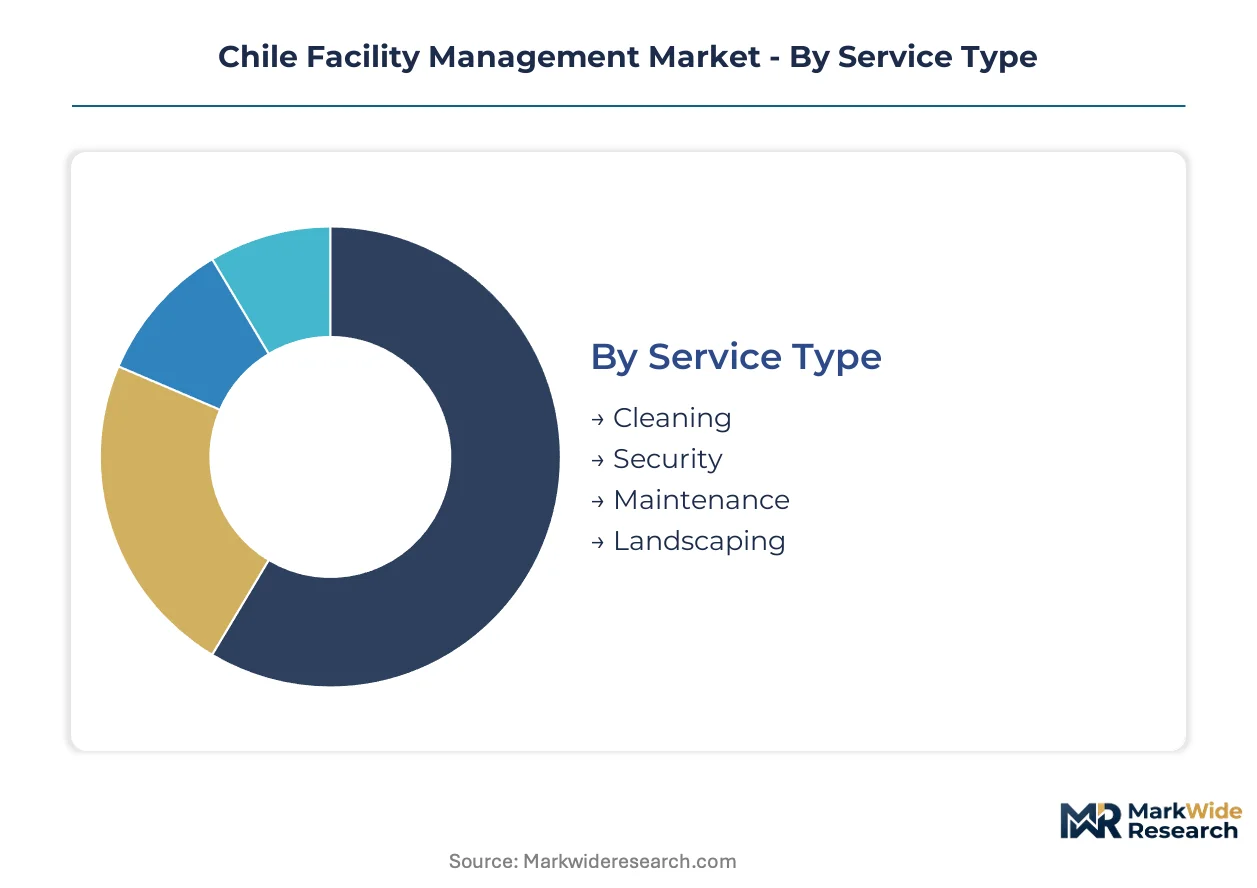
Chile's facility management market fragments across service delivery methods, customer verticals, and technology integration levels. Understanding these divisions reveals where capital concentrates and which segments capture efficiency mandates from Santiago's commercial towers to Atacama mining camps.
Service Type:
Mature labor-intensive services dominate contract value while specialized technical services emerge as margin expansion vectors.
- Maintenance:Encompasses preventive and corrective servicing of mechanical, electrical, and plumbing systems across commercial and industrial assets. Demand concentrates in Antofagasta mining processing facilities where equipment uptime directly correlates with copper output volumes.
- Security:Delivers manned guarding, access control, and surveillance systems for corporate and critical infrastructure clients. Santiago's financial district towers drive premium contract values as landlords bundle cybersecurity-adjacent physical protection with traditional perimeter defense.
- Cleaning:Janitorial and specialized sanitation services for commercial, healthcare, and industrial environments.
- Landscaping:Grounds maintenance and exterior aesthetic management for corporate campuses and municipal properties.
Maintenance handles the majority of throughput; Security is the fastest mover on share.
Customer Type:
Contract structures vary sharply between public-sector compliance requirements and private-sector cost optimization priorities.
- Commercial:Encompasses office towers, retail centers, and hospitality properties requiring integrated facility oversight. Santiago's central business district generates sustained demand as landlords retrofit aging HVAC systems to meet Ministerio de Energía efficiency deadlines.
- Government:Public administration buildings, courthouses, and municipal facilities subject to procurement transparency rules. Contracts emphasize labor compliance and environmental reporting under Ministerio del Trabajo oversight.
- Residential:Condominium management and multi-family housing maintenance services.
- Educational:School and university campus facility operations with seasonal demand fluctuations.
Commercial absorbs the largest contract volume; Government is climbing the fastest on procurement reform momentum.
Technology:
Technology deployment separates premium providers from commodity competitors across Chile's geographically dispersed building stock.
- Energy Management:Systems monitoring consumption patterns, optimizing load distribution, and automating demand response. Mining camp operators in the Atacama prioritize diesel generator efficiency and solar hybrid integration for remote power reliability.
- Automation:Building management systems controlling lighting, access, and environmental parameters through centralized platforms. Santiago commercial landlords deploy these to satisfy Superintendencia de Electricidad y Combustibles enforcement actions.
- IoT:Sensor networks enabling predictive maintenance and real-time asset condition monitoring.
- HVAC:Heating, ventilation, and air conditioning equipment maintenance and control system upgrades.
Energy Management commands the highest margin expansion; Automation is gaining share fastest on regulatory compliance pressure.
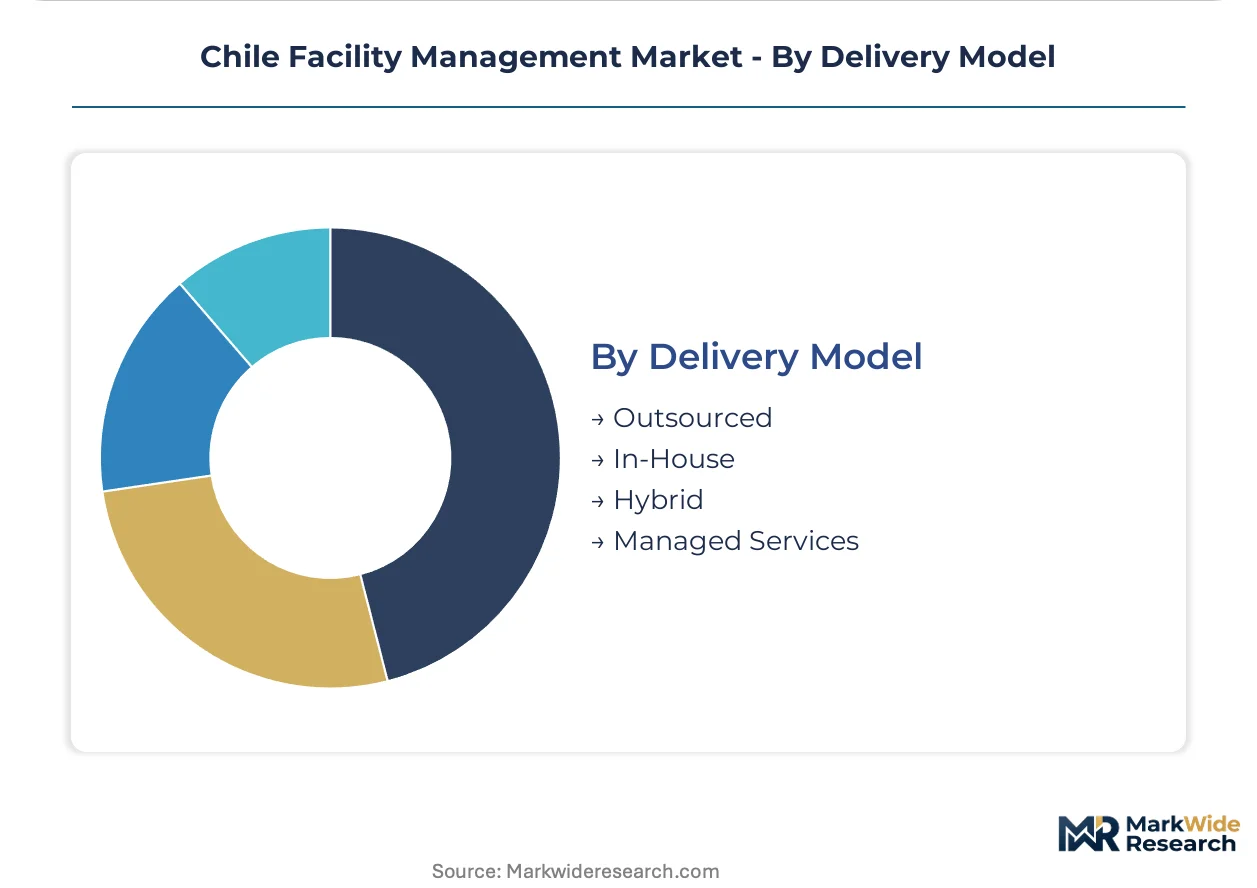
Delivery Model:
Risk transfer preferences shift capital allocation between internal staffing and external specialist engagement.
- Outsourced:Full facility operations transferred to third-party providers assuming labor compliance and capital risk. Copper and lithium extraction operators across northern Chile favor this model to isolate operational volatility from core mining activities.
- Managed Services:Outcome-based contracts tying provider compensation to measurable performance metrics. Santiago financial district towers adopt these structures to align facility costs with occupancy rates and energy benchmarks.
- In-House:Direct employment of facility staff retaining operational control internally.
- Hybrid:Blended arrangements combining internal oversight with selective external specialist deployment.
Outsourced captures the dominant share of new contract value; Managed Services is expanding most quickly on performance guarantee adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's facility management services flow northward to supply mining camps across the Atacama Desert and southward to Santiago's commercial towers, with cross-border demand emerging from Peruvian and Bolivian extraction operators seeking proven remote-site expertise.
Antofagasta Region
Copper processing facilities and lithium brine operations drive outsourced maintenance contracts across the northern mining corridor. The Superintendencia de Electricidad y Combustibles enforces standby power regulations for remote industrial sites. Antofagasta city anchors specialized service provider clusters serving Escondida and Spence mine complexes.
Metropolitan Santiago
Financial district landlords retrofit aging HVAC systems to meet Ministerio de Energía efficiency deadlines for buildings exceeding 500 square meters. Municipal environmental ordinances in Providencia and Las Condes mandate real-time energy monitoring for commercial towers. Santiago's central business district concentrates integrated workplace management system deployments.
Atacama Region
Solar hybrid power integration and diesel generator optimization dominate facility service specifications for off-grid mining camps. The Ministerio del Trabajo y Previsión Social regulates labor subcontracting arrangements in remote extraction zones. Copiapó and Caldera host maintenance provider networks supporting Codelco and BHP operations.
Valparaíso Region
Port logistics facilities and chemical processing plants require specialized security and environmental compliance bundling. Regional environmental enforcement varies from Santiago standards, complicating national contract standardization. Valparaíso and Quintero industrial zones attract integrated facility managers with maritime safety certifications.
Chile Facility Management Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability tiers: multinational platform operators with energy management expertise, regional specialists with mining sector relationships, and fragmented local maintenance subcontractors. Strategic archetypes include technology-anchored providers pursuing automation-led contracts, labor-intensive operators competing on compliance bundling, and hybrid models blending remote analytics with on-site staffing. Dominant competitive moves encompass portfolio diversification into renewable energy asset management and geographic expansion through municipal ordinance specialization.
Within the multinational platform tier, Sodexo Servicios de Gestión Chile SpA and ISS Chile S.A. exemplify divergent positioning strategies, with the former anchoring energy management capabilities and the latter representing security-centric service bundling. CBRE Group occupies a position bridging commercial real estate relationships with technology-augmented delivery models. These three entities collectively illustrate how global brand recognition, sector-specific expertise, and regulatory compliance infrastructure define competitive differentiation in Chile's geographically dispersed market.
| Leading Market Players |
|---|
| Grupo EULEN Chile S.A. |
| Jones Lang LaSalle IP, Inc. |
| ISS Chile S.A. |
| Compass Group Chile Ltda. |
| Cushman & Wakefield |
| Sodexo Servicios de Gestión Chile SpA |
| CBRE Group |
| Mancorp |
| Aramark Servicios y Aseo Chile SpA |
| Others |
Value Chain & Pricing Dynamics
Santiago's concentration of certified building automation integrators compresses margins for mid-tier maintenance providers while amplifying pricing power for technology-anchored operators serving mining camp operators across the Atacama. The Ministerio de Energía's retrofit mandates force commercial landlords into premium contracting relationships, reshaping how facility service bundles are priced and procured across Chile's geographically dispersed industrial footprint.
Pricing Analysis
Legacy HVAC maintenance contracts trade at substantial discounts to building automation retrofits equipped with BACnet and Modbus protocol integration. Three-tier pricing structure across premium, standard, and economy levels separates energy performance-guaranteed managed services from commodity cleaning and security bundles. Cost compression in the standard tier is intensifying because Santiago's fragmented subcontractor base lacks certification depth for integrated workplace management systems. Mining corporations in Antofagasta exhibit the lowest price sensitivity, prioritizing uptime guarantees over per-unit service costs.
Supply Chain Analysis
Tariff exposure between Chile and China dominates equipment procurement risk for building automation hardware and IoT sensor networks. Supply concentrates in China for HVAC control systems, Germany for precision automation components, and the United States for cloud-based building management platforms. Raw material dependencies span copper wiring from domestic Codelco operations, lithium battery storage from Atacama salares, and imported semiconductor chips for sensor networks. Single-source vulnerability in certified automation technician training feeds from Chile's underdeveloped vocational pipeline. Distribution runs through specialized integrator networks anchored in Santiago, Antofagasta, and Valparaíso.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's facility management sector rewards providers who bridge the technical gap between legacy building systems and modern automation platforms, yet the certified workforce pool remains critically thin across mining regions and metropolitan centers alike.
For Market Incumbents: Entrench market position by acquiring regional maintenance networks in Antofagasta and Valparaíso to secure mining sector relationships before energy efficiency mandates consolidate demand around technology-anchored competitors. Invest in backward integration into building automation certification programs to address the Superintendencia de Electricidad y Combustibles enforcement pipeline. Capacity addition in remote-site technician training centers insulates against labor compliance risks under Ministerio del Trabajo oversight. For New Entrants and Emerging Players: Mid-market commercial buildings in Providencia and Las Condes represent the most penetrable entry point, as these landlords face imminent retrofit deadlines but lack relationships with established mining-sector providers. Specialized energy management boutiques serving Santiago's 500-plus square meter towers offer a second white-space target, given incumbent focus on bundled service contracts. A go-to-market angle emphasizing outcome-based performance guarantees with real-time energy monitoring dashboards differentiates against legacy hourly-rate competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors facility managers with proven remote-site automation deployment capabilities across dispersed mining footprints. Long-term viability rests on capturing renewable energy asset management contracts as solar and wind developers require specialized oversight for northern Chile generation sites. Acquisition target archetype: regional specialists with municipal ordinance expertise in Valparaíso or Antofagasta combined with existing Superintendencia compliance infrastructure. The signal to watch is accelerated unbundling of integrated contracts into specialized component purchases by Codelco and BHP procurement teams.| Strategic Initiative | Industry Significance |
|---|---|
| Building Automation Retrofit Partnership | Positions providers to capture Ministerio de Energía-mandated upgrade cycles in Santiago commercial towers. |
| Remote Site Technician Certification Program | Addresses Superintendencia de Electricidad y Combustibles enforcement gaps across Atacama mining camps. |
| Renewable Energy Asset Management Expansion | Captures emerging solar and wind facility oversight contracts in Antofagasta and Atacama regions. |
| Municipal Ordinance Specialization | Enables national contract standardization despite divergent environmental enforcement in Valparaíso versus Santiago. |
| Predictive Maintenance Platform Deployment | Reduces on-site staffing requirements for BHP and Codelco through IoT sensor network integration. |
Study Parameters
The analysis maps maintenance services, security operations, energy management systems, and building automation deployment, each validated through facility directors at Santiago commercial towers, procurement leads at Antofagasta mining operations, and regional service provider executives across Chile's northern extraction zones. Primary interviews with Superintendencia de Electricidad y Combustibles enforcement officers and Ministerio del Trabajo compliance specialists supplemented secondary validation through Chilean customs data on building equipment imports, SEC filings of multinational platform operators, and municipal ordinance databases for Providencia, Las Condes, and Valparaíso. Bottom-up contract value aggregation triangulates against top-down market sizing from energy efficiency retrofit permit filings.
Assumptions held fixed include continued copper price volatility within historical bands, sustained Ministerio de Energía enforcement timelines for commercial buildings exceeding 500 square meters, and stable labor code frameworks under Ministerio del Trabajo oversight. Variables tested across the projection horizon encompass mining sector outsourcing penetration rates, building automation adoption curves by Santiago landlord tier, and renewable energy facility management contract emergence. Segmentation dimensions modeled span service type, customer vertical, technology integration level, and delivery model risk transfer structure. CAGRs derive from equipment lifecycle replacement schedules and regulatory compliance deadline clustering.
Practitioners should monitor copper price movements, municipal ordinance harmonization efforts, and certified technician pipeline expansion for early signals of forecast deviation. Material shifts in Superintendencia enforcement intensity or Ministerio de Energía mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Slovenia Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
United States Facility Management Market
Facility Management
Mexico Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Cold Storage Warehouse Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Austria Facility Management Market
Facility Management
Moldova Facility Management Market
Facility Management
Nigeria Facility Management Services Market