
 Europe Soft Facility Management Market | 2026-2036
Europe Soft Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Soft Facility Management Market Foresight
European facility service providers is pivoting toward technology-integrated service delivery as clients demand measurable outcomes. Sodexo Inc leverages its continental catering and maintenance network to anchor multi-service contracts across French and Belgian hospital systems. Mitie Group PLC specializes in security-cum-cleaning bundles for UK commercial offices, while ISS Global dominates Nordic public-sector facility contracts through standardized mobile workforce platforms.
Soft facility management encompasses non-technical building services including cleaning, security, reception, and landscaping, delivered through labor-intensive operations augmented by IoT-enabled quality verification and workforce scheduling software. Its primary commercial purpose is to maintain occupant experience and regulatory compliance without altering building infrastructure. Cleaning services occupy the largest revenue pool across Europe due to mandatory frequency standards in healthcare and food retail, while cloud-based management platforms represent the fastest-expanding technology segment as clients seek real-time service verification. Security services remain mature in the UK and Germany, though margin compression is pushing vendors toward performance-based pricing models.
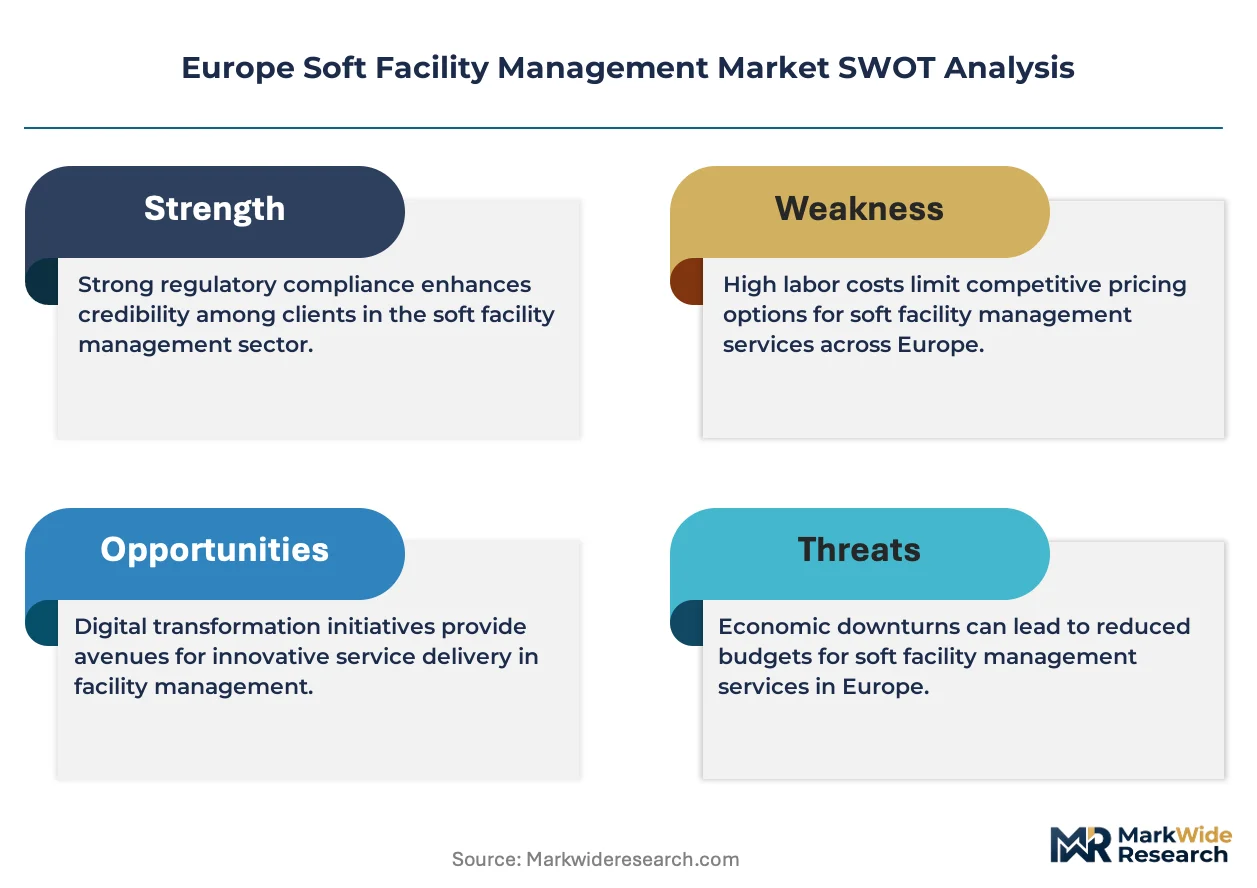
The EU Green Deal and national transpositions through France's DGEC and Germany's BAU impose escalating sustainability reporting obligations on facility operators, directly shaping procurement criteria for public-sector contracts. REACH and national biocide regulations constrain chemical cleaning product formulations, forcing vendors to reformulate or source certified alternatives. Stakeholders must monitor how the EU AI Act intersects with automated workforce surveillance tools deployed in security and reception services.
Market Dynamics
The EU Green Deal is compressing contract timelines as facility operators must retrofit reporting infrastructure before 2030 sustainability deadlines bite. Public-sector procurement teams now embed carbon accounting clauses into multi-service tenders, forcing vendors to restructure workforce deployment around real-time energy dashboards.
Growth Catalysts
- Cloud-based energy monitoring:The EU Green Deal mandates granular carbon tracking across public buildings, creating procurement pull for integrated facility platforms that merge cleaning schedules with HVAC load data.
- Healthcare outsourcing in France:Hospital systems under budget pressure are bundling reception, cleaning, and patient transport into single-vendor contracts with outcome-based KPIs.
- REACH biocide reformulation:Chemical restrictions on traditional disinfectants accelerate demand for electrochemical activation systems and enzyme-based cleaning protocols certified under ECHA frameworks.
Market Restraints
- Labor cost rigidity:Minimum wage harmonization across EU member states compresses margin flexibility for labor-intensive cleaning and reception services.
- Input volatility in cleaning chemicals:Petrochemical feedstock fluctuations destabilize pricing for surfactant-dependent formulations used in hospital-grade disinfection protocols.
- GDPR friction with workforce surveillance:IoT-enabled quality verification tools face deployment restrictions where employee tracking intersects with biometric data collection.
Strategic Opportunities
- Underpenetrated Nordic public sector:Swedish and Finnish municipalities lag in outsourced facility management, presenting white space for vendors offering bundled carbon-neutral service packages.
- EU AI Act compliance services:Automated scheduling algorithms require audit trails; vendors can monetize algorithmic transparency as a premium contract add-on.
- Convergence of IoT and mobile workforce platforms:Real-time sensor data feeding directly into cleaner dispatch systems enables dynamic route optimization previously impossible with static scheduling.
Industry Challenges
- CSRD reporting capability gaps:Facility operators lack in-house carbon accounting expertise to meet corporate sustainability reporting directive timelines.
- Legacy system integration friction:Cloud-based management platforms struggle to interface with decades-old building automation systems common in German commercial real estate.
- Biocide certification delays:Novel disinfectant formulations face 18-24 month ECHA approval windows, slowing product pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Soft Facility Management Market |
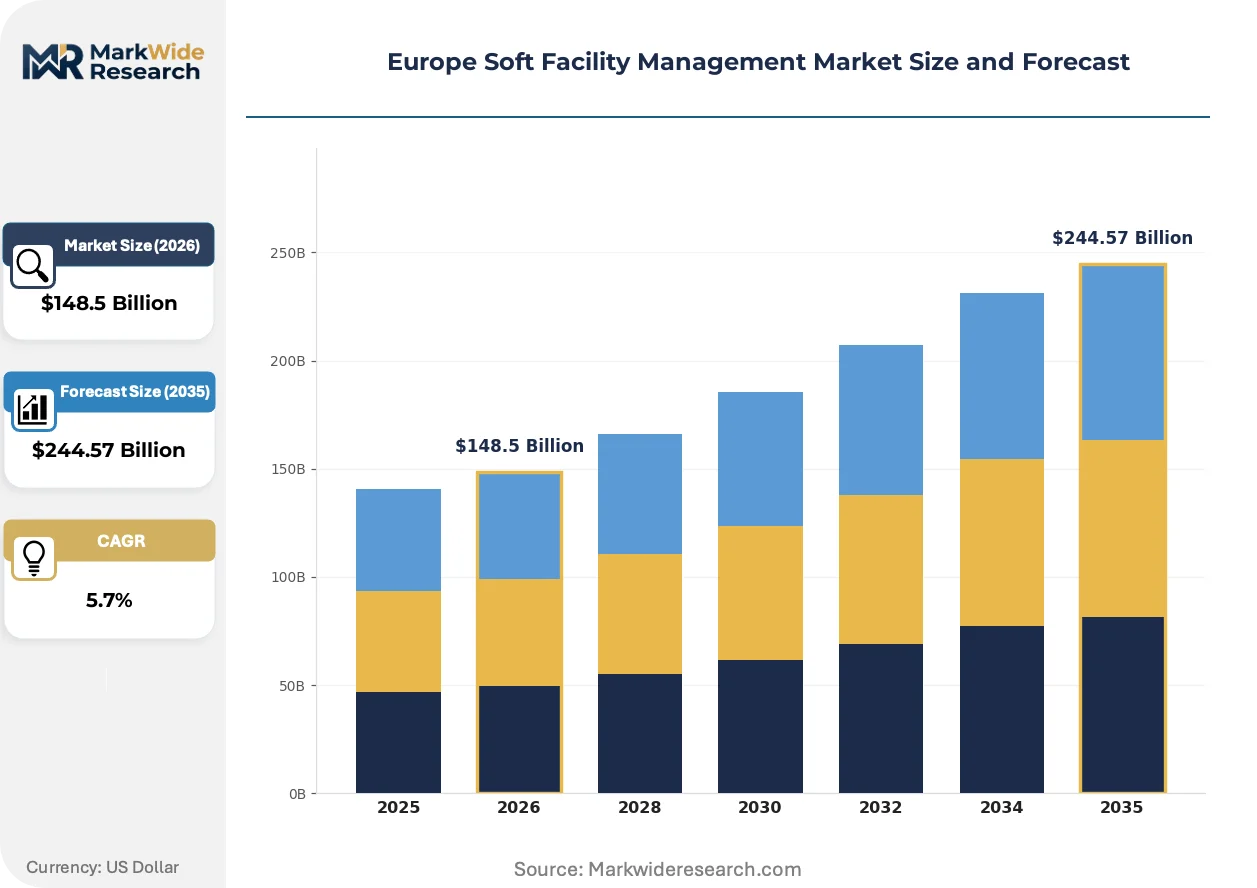
| Market Size in 2026 | $148.5 Billion |
| Market Size in 2035 | $244.57 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Reception, Landscaping End User: Commercial Offices, Educational Institutions, Healthcare Facilities, Retail Outlets Technology: IoT Solutions, Cloud-Based Management, Mobile Applications, Software Analytics Pricing Model: Fixed-Price, Pay-As-You-Go, Subscription-Based, Performance-Based |
| Companies Covered | Atalian Global Services, Sodexo Inc, CBRE Group, Andron Facilities Management, Emcor Facilities Services WLL, Mitie Group PLC, JLL Limited, Atlas FM Ltd, ISS Global, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Soft Facility Management Market Shifts & Advancements
Technology-integrated service delivery is displacing labor-only contracts as buyers demand measurable environmental and operational outcomes. Vendors now compete on data transparency rather than headcount efficiency alone.
Electrochemical water activation technology is expanding into hospital and food retail cleaning protocols. French healthcare procurement teams pilot these systems to eliminate quaternary ammonium compounds from patient-facing environments. The technology is expanding into contract structures that bundle equipment capital costs into per-square-meter service fees, compressing traditional chemical supply margins.
France's DGEC transposition of EU Green Deal obligations now requires facility operators above 500 employees to submit verified carbon footprints biannually. This regulatory layer forces vendors to install sub-metering infrastructure or risk contract disqualification. German hospital systems respond fastest, embedding energy performance clauses into five-year cleaning and maintenance tenders.
Buyers now unbundle specification-setting from service execution, retaining in-house sustainability officers who audit vendor performance against science-based targets. UK commercial landlords lead this pattern, inserting open-book energy accounting into lease-aligned facility contracts. The shift concentrates negotiation leverage with procurement teams versed in carbon accounting rather than traditional facilities managers.
Europe Soft Facility Management Market Segmentation
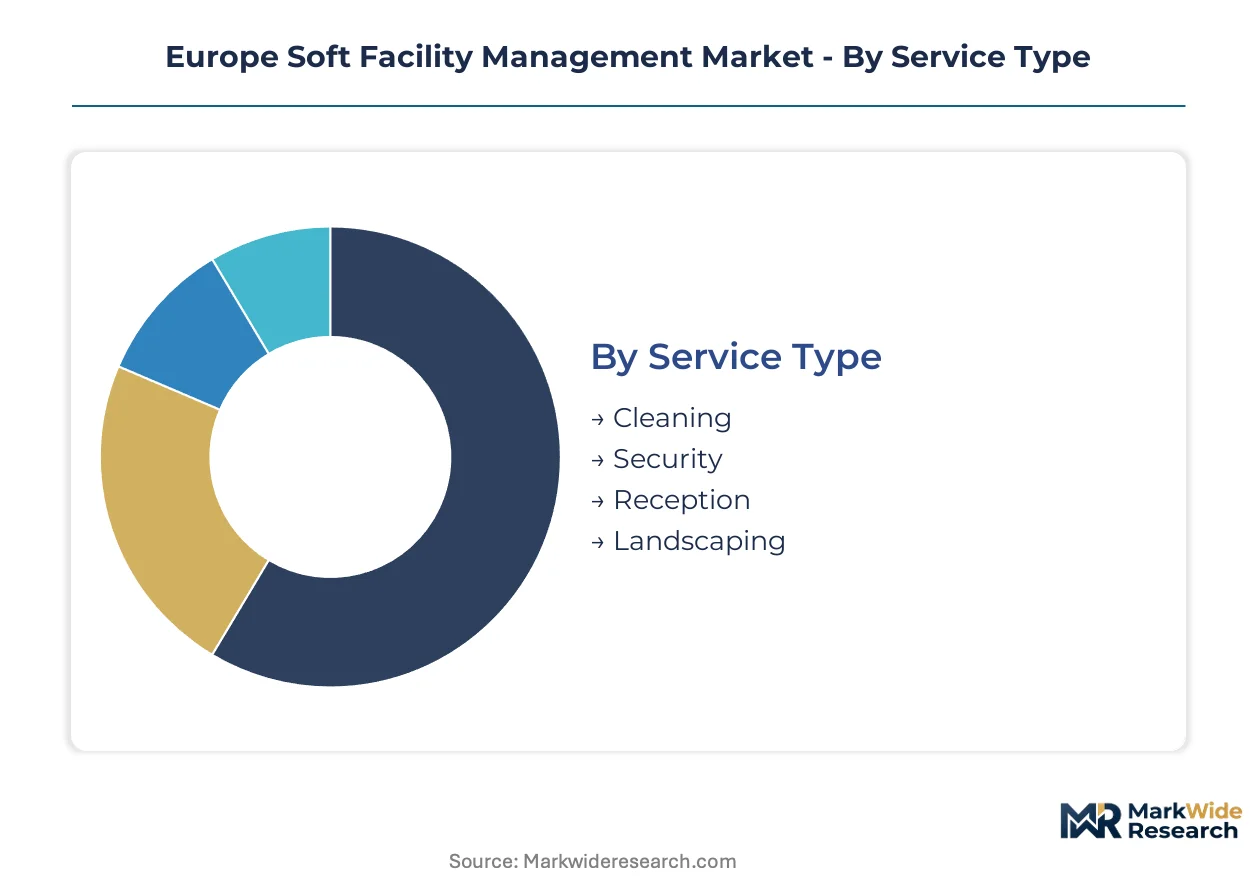
Soft facility management segmentation reveals how procurement teams balance labor intensity against technology integration. Buyers increasingly unbundle specification-setting from execution, creating distinct competitive arenas across service delivery modes.
Service Type:
Cleaning commands volume dominance while security and reception concentrate premium pricing power through specialized labor certification.
- Cleaning:Labor-intensive operations span routine janitorial work through hospital-grade disinfection protocols. Demand clusters in French healthcare systems and German food retail chains where REACH biocide regulations force continuous formulation upgrades. Mandatory frequency standards in clinical environments sustain contract renewal rates.
- Security:Personnel-based guarding integrates with access control technology and mobile patrol verification. UK commercial landlords drive performance-based pricing adoption, linking vendor payments to incident response metrics rather than headcount deployed.
- Reception:Front-desk services combine visitor management with administrative support functions. Corporate campuses across Belgium and the Netherlands bundle reception into multi-service tenders requiring bilingual staffing capabilities.
- Landscaping:Exterior grounds maintenance follows seasonal demand patterns with lower technology penetration than indoor services. Municipal contracts in Nordic countries increasingly specify electric equipment fleets to satisfy EU Green Deal procurement criteria.
Today's leader: Cleaning. Tomorrow's challenger: Security.
End User:
Healthcare and commercial offices generate contrasting contract structures—one demands compliance documentation, the other prioritizes cost-per-square-meter efficiency.
- Commercial Offices:UK landlords lead open-book energy accounting adoption, inserting carbon performance clauses into lease-aligned facility contracts. Mitie Group PLC anchors market presence through security-cum-cleaning bundles for London financial district towers.
- Healthcare Facilities:French hospital systems under DGEC pressure bundle reception, cleaning, and patient transport into single-vendor agreements with outcome-based KPIs. Electrochemical water activation pilots eliminate quaternary ammonium compounds from patient-facing environments.
- Educational Institutions:German universities and research campuses expand outsourced scope beyond traditional cleaning into integrated facility platforms. Budget constraints favor multi-year tenders with capped annual escalation clauses.
- Retail Outlets:Food retail chains in Spain and Italy enforce strict hygiene protocols through centralized procurement functions. High-frequency cleaning requirements during operating hours sustain dedicated on-site staffing models.
Healthcare commands premium pricing. Commercial offices drive standardization.
Technology:
Cloud infrastructure absorbs capital investment while mobile applications deliver immediate workforce productivity gains.
- Cloud-Based Management:Platforms merge cleaning schedules with HVAC load data to satisfy EU Green Deal carbon tracking mandates. French operators above 500 employees must install sub-metering infrastructure or face public-sector contract disqualification.
- IoT Solutions:Sensor networks enable real-time service verification and dynamic route optimization for mobile cleaning teams. German commercial real estate struggles with legacy building automation integration, slowing deployment timelines.
- Mobile Applications:Workforce scheduling software standardizes task allocation across dispersed cleaning crews. GDPR friction constrains biometric data collection for quality verification tools in security and reception deployments.
- Software Analytics:Predictive maintenance algorithms optimize consumable replenishment and equipment replacement cycles. Vendors monetize algorithmic transparency as premium contract add-ons under emerging EU AI Act compliance requirements.
Cloud platforms anchor current investment. IoT sensors promise the steepest expansion trajectory.
Pricing Model:
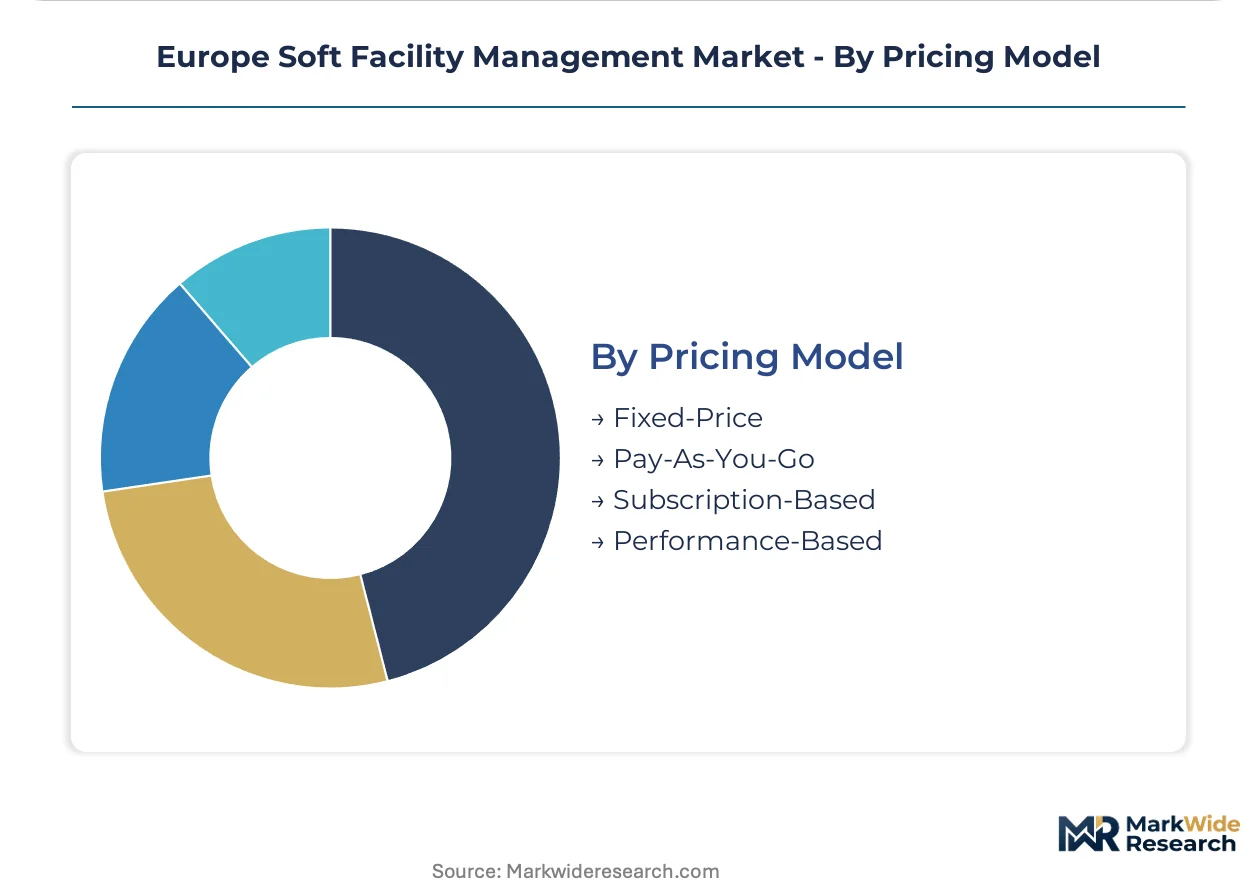
Fixed-price contracts dominate volume procurement while performance-based structures concentrate in premium segments with measurable outcome potential.
- Fixed-Price:Predetermined fees for defined service scopes protect buyers against labor cost volatility. German municipal tenders favor this structure for standardized cleaning specifications with minimal variation.
- Performance-Based:Vendor compensation ties directly to energy reduction metrics, incident response times, or occupant satisfaction scores. UK commercial office landlords pioneer this approach for integrated security and reception contracts.
- Subscription-Based:Monthly fees bundle technology platform access with baseline labor services. Nordic public-sector contracts adopt this model to spread cloud infrastructure costs across multi-year agreements.
- Pay-As-You-Go:Variable pricing responds to actual service consumption rather than contracted minimums. Ad hoc demand spikes in event-driven retail and exhibition spaces sustain limited market presence.
Fixed-price holds volume share. Performance-based structures gain fastest in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as facility operators migrate contracts toward jurisdictions with clearer carbon accounting frameworks and standardized public-sector tender processes.
Germany
Corporate campuses in Frankfurt and Munich are expanding multi-service outsourcing contracts that bundle cleaning, reception, and energy monitoring. The BAU's transposition of EU Green Deal obligations mandates real-time HVAC sub-metering in public buildings above 500 employees. Industrial clusters in North Rhine-Westphalia are piloting cloud-based workforce scheduling platforms that merge cleaning dispatch with building automation data.
France
Hospital systems under DGEC pressure are consolidating reception, cleaning, and patient transport into single-vendor agreements with outcome-based KPIs. Biannual verified carbon footprint submissions are now required for facility operators above the employee threshold. The Île-de-France region leads electrochemical water activation pilots designed to eliminate quaternary ammonium compounds from clinical environments.
United Kingdom
London commercial landlords are embedding open-book energy accounting clauses into lease-aligned facility contracts. Performance-based pricing models now tie vendor compensation to incident response metrics rather than headcount deployed. Security-cum-cleaning bundles dominate financial district towers where regulatory compliance intersects with occupant experience demands.
Sweden
Municipal procurement teams are specifying electric equipment fleets for exterior grounds maintenance to satisfy EU Green Deal criteria. Standardized mobile workforce platforms are penetrating public-sector contracts previously resistant to outsourced service models. The Stockholm-Uppsala corridor is emerging as a testbed for carbon-neutral service package bundling.
Netherlands
Corporate campuses in Amsterdam and Rotterdam are demanding bilingual reception staffing capabilities within multi-service tenders. REACH biocide regulations are accelerating reformulation of disinfectant protocols across food retail and healthcare contracts. The Randstad region concentrates vendor investment in IoT-enabled quality verification systems.
Europe Soft Facility Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue technology-integrated service delivery and carbon-accounting specialization. The vendor base organizes around three archetypes: continental multi-service networks anchoring hospital and public-sector contracts, security-specialized operators bundling guarding with cleaning protocols, and Nordic-focused platforms leveraging standardized mobile workforce systems. Dominant competitive moves include portfolio diversification into energy monitoring adjacencies and strategic partnerships with cloud infrastructure providers.
Within the multi-service network tier, Sodexo Inc and ISS Global exemplify archetypes that anchor continental contract structures across French hospital systems and Nordic public-sector facilities respectively. Mitie Group PLC occupies a position representing the security-integrated specialist model prevalent in UK commercial office deployments. These entities sit within competitive positioning that prioritizes measurable outcome verification over labor arbitrage.
| Leading Market Players |
|---|
| Atalian Global Services |
| Sodexo Inc |
| CBRE Group |
| Andron Facilities Management |
| Emcor Facilities Services WLL |
| Mitie Group PLC |
| JLL Limited |
| Atlas FM Ltd |
| ISS Global |
| Others |
Supply & Pricing Matrix
Public-sector procurement teams in France and Germany concentrate negotiating leverage through multi-year bundled tenders, locking vendors into fixed-price structures with carbon-accounting add-ons that compress margin flexibility.
Pricing Analysis
Direct-to-facility contracts bypass distributor markups entirely. Three-tier pricing structure across premium, standard, and economy levels separates carbon-certified service packages from baseline labor-only offerings. Price differentiation hinges on real-time energy dashboard integration and ECHA biocide certification tiers. Pricing pressure stems from minimum wage harmonization across EU member states, squeezing labor-intensive cleaning margins. Food retail chains exhibit highest price sensitivity, while French hospital systems prioritize compliance documentation over unit cost.
Supply Chain Analysis
Freight costs for electrochemical activation equipment from Netherlands-based manufacturers inflate landed costs for Spanish and Italian facility operators. Supply concentrates in Germany, France, and the Netherlands for cloud-based workforce platforms and IoT sensor hardware. Raw material dependencies span petrochemical surfactants, lithium-ion battery cells for electric cleaning fleets, and semiconductor components for access control systems. Single-source vulnerability sits with ECHA-certified biocide formulations facing 18-24 month approval windows. Distribution runs through direct vendor-facility relationships anchored by multi-service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility service vendors can exploit geographic arbitrage between Nordic municipalities with nascent outsourcing adoption and saturated Western European markets where carbon-accounting expertise commands premium pricing.
For Market Incumbents: Cement market position through backward integration into cloud infrastructure and sub-metering hardware, insulating margins from third-party platform licensing costs. Acquire specialized electrochemical cleaning technology providers before ECHA approval windows accelerate competitive entry. Counter emerging pure-play technology vendors by bundling energy monitoring with legacy labor contracts. For New Entrants and Emerging Players: Launch via subscription-based SaaS platforms targeting Swedish and Finnish municipal contracts previously resistant to outsourced models. Penetrate the underdeveloped Nordic public sector with carbon-neutral service packages that satisfy EU Green Deal procurement criteria. Target food retail chains in Spain and Italy through centralized procurement channels demanding REACH-compliant disinfectant protocols. For Investors and Strategic Acquirers: Continental multi-service networks are the most active acquirer in this space, consolidating regional cleaning specialists to anchor hospital system contracts. Long-term viability rests on technology-integrated service delivery capabilities rather than labor arbitrage. Watch for ECHA biocide approval acceleration as inflection signal for electrochemical activation system adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cloud Infrastructure | Reduces platform licensing costs for vendors serving French DGEC-mandated carbon reporting requirements. |
| Electrochemical Technology Licensing | Accelerates ECHA-compliant disinfectant alternatives for hospital systems eliminating quaternary ammonium compounds. |
| Nordic Public-Sector Joint Venture | Unlocks Swedish and Finnish municipal contracts through localized carbon-neutral service bundling expertise. |
| Mobile Workforce Platform Acquisition | Consolidates ISS Global's standardized dispatch systems with IoT-enabled quality verification capabilities. |
| Energy Performance Partnership | Aligns vendor compensation with BAU-mandated HVAC sub-metering targets in German commercial real estate. |
Research Methodology
Multiple input streams — facility procurement directors, cloud platform engineers, ECHA regulatory specialists, and hospital sustainability officers — were reconciled against EU Green Deal implementation databases, national tender documentation from France's DGEC and Germany's BAU, and facility operator SEC filings. Secondary validation drew from REACH biocide registration records, municipal procurement registries, and commercial real estate lease alignment datasets. Bottom-up contract value aggregation and top-down market sizing triangulated segment-level estimates.
Historical contract renewal patterns were cross-referenced against expert panel assessments of technology adoption trajectories across the projection horizon. Segmentation dimensions modeled include service type intensity, end-use compliance requirements, technology deployment architecture, and pricing model structure. CAGRs were derived from vendor revenue disclosures and public-sector tender value extrapolation. Forecast inputs incorporated EU AI Act compliance timeline assumptions and ECHA approval velocity for novel disinfectant formulations.
Several conditions sit outside the modeled scope, including geopolitical disruption to petrochemical feedstock supply and unanticipated GDPR enforcement actions against workforce surveillance tools. Forecasts reflect underlying assumptions about regulatory deadline adherence and technology integration cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Global Unified Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Iceland Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
United Arab Emirates Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Qatar Facility Management Market