
 Human Resource Management Software Market | 2026-2036
Human Resource Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Human Resource Management Software Market Intelligence
The direct sales channel for enterprise HR suites is narrowing as vendors consolidate partner ecosystems around cloud-native delivery. Workday leverages its unified architecture to anchor subscription revenue among Fortune 500 accounts. SAP SuccessFactors competes through deep ERP integration and localized payroll engines across multiple jurisdictions. BambooHR specializes in self-service onboarding tools that dominate the sub-500 employee segment with minimal implementation overhead.
Human Resource Management Software constitutes integrated platforms that automate workforce administration through modules for talent acquisition, compensation calculation, time tracking, and predictive analytics, typically delivered via multi-tenant cloud architectures with API connectivity to finance and operations systems. Its primary commercial purpose is to reduce administrative labor, ensure regulatory compliance, and improve employee retention through data-driven engagement strategies. Cloud-based deployment leads in new customer acquisition due to lower capital requirements and faster implementation cycles, while on-premises solutions retain a mature installed base in highly regulated industries where data residency mandates prevail. Workforce analytics represents the fastest-expanding solution offering as organizations seek predictive models for turnover risk and succession readiness.
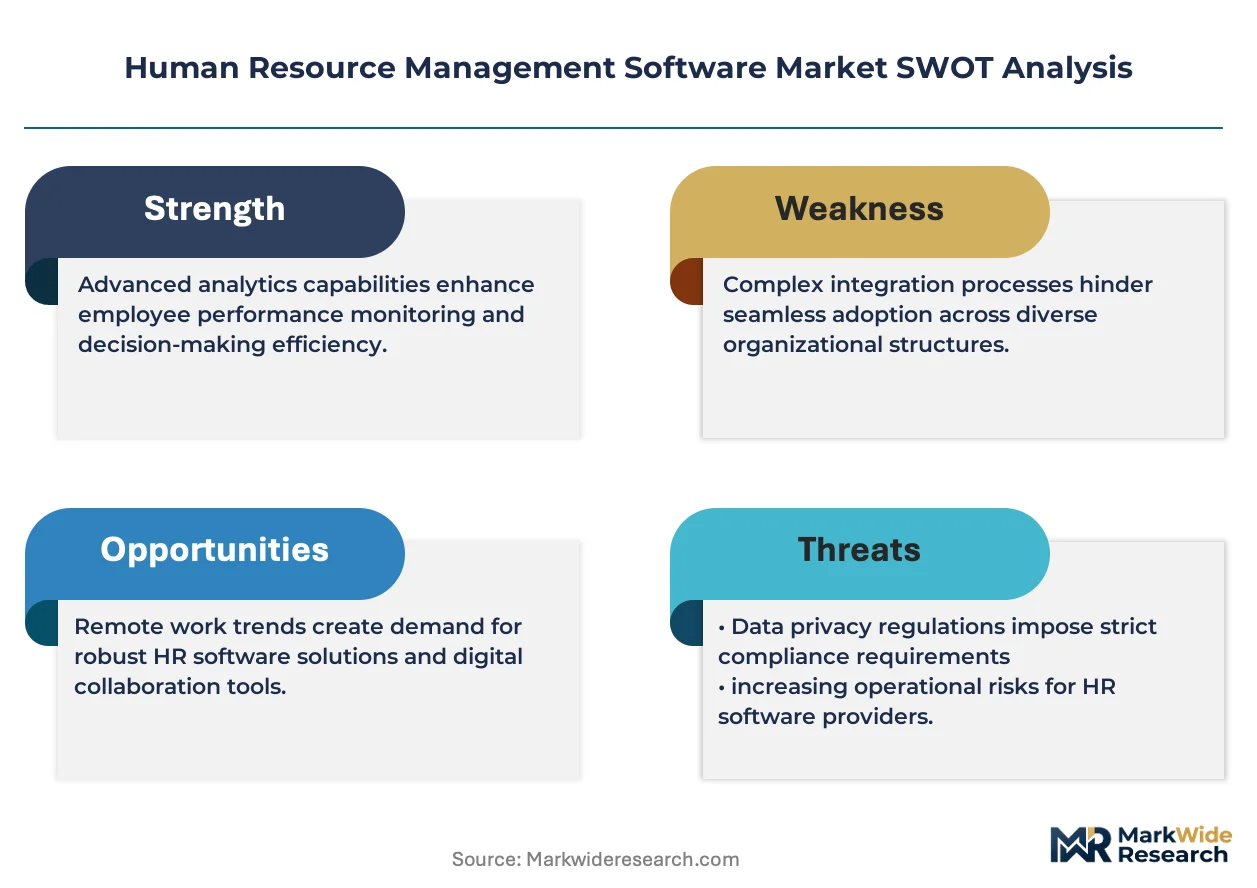
The EU AI Act and GDPR constrain how European vendors deploy automated scoring in recruitment and performance evaluation, forcing architectural investments in explainability and consent management. In the United States, the EEOC and state-level biometric privacy statutes create fragmented compliance obligations that elevate demand for embedded regulatory monitoring tools. Stakeholders must weigh the trade-off between AI-enabled workforce insights and the escalating compliance burden of algorithmic accountability mandates across multiple enforcement regimes.
Market Dynamics
The EU AI Act is forcing vendors to rearchitect performance management modules around explainability requirements while healthcare systems accelerate cloud migration to address clinical workforce shortages.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive scheme for SaaS infrastructure is accelerating mid-market payroll digitization across manufacturing and services clusters.
- Biometric privacy statutes:Fragmented state-level mandates in the United States are elevating demand for embedded compliance monitoring tools within time-tracking modules.
- Workforce analytics convergence:Predictive turnover modeling is digitizing retention strategy across professional services and healthcare delivery organizations.
Market Restraints
- Data residency mandates:On-premises solutions retain entrenched positions in German banking and French public sector where GDPR localization requirements block multi-tenant cloud migration.
- API integration costs:Legacy ERP connectivity consumes 40-60% of implementation budgets for mid-market buyers, compressing vendor margins on sub-500 employee deployments.
- Algorithmic accountability litigation:EEOC guidance on automated hiring tools has created defensive procurement freezes among risk-averse Fortune 1000 employers.
Strategic Opportunities
- Explainable AI architectures:Vendors investing in consent-management workflows and audit-trail documentation are capturing displaced European public sector contracts from non-compliant competitors.
- Embedded finance integration:Payroll-earned wage access and benefits administration APIs represent unmonetized white space for platforms serving gig-economy staffing firms.
- Clinical workforce platforms:Credential verification and shift-scheduling modules tailored to nursing shortages are opening specialized verticals within United States health systems.
Industry Challenges
- Machine learning operations talent:Shortages of MLOps engineers with HR domain expertise are delaying predictive analytics deployments at mid-tier vendors.
- Cross-border payroll engines:Jurisdiction-specific tax calculation requirements force perpetual engineering investment to maintain compliance across fragmented European regulatory landscapes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Resource Management Software Market |
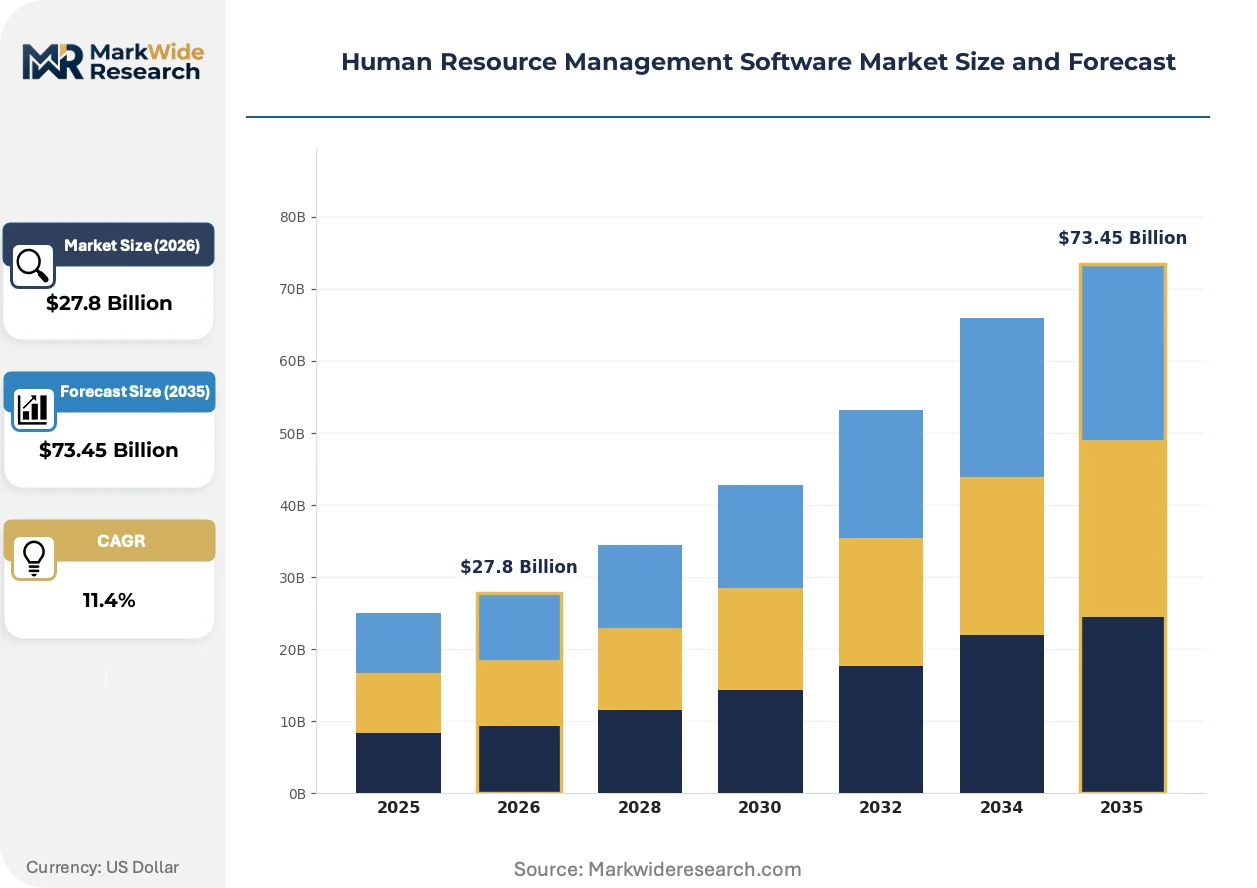
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $73.45 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted Solution Offering: Talent Acquisition, Payroll Management, Performance Management, Workforce Analytics, Time & Attendance Application: Employee Engagement, Succession Planning, Compliance Management, Compensation Management, Learning & Development End User: Small Enterprises, Mid-Sized Firms, Large Corporations, Government Agencies |
| Companies Covered | BambooHR, Oracle HCM Cloud, Workday, Qandle, Paycor, ADP, UKG Pro, SAP SuccessFactors, Rippling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Resource Management Software Market Strategic Shifts & Innovations
Generative interfaces and ambient intelligence are compressing the administrative burden of workforce management while regulatory pressure on automated decision-making intensifies architectural investments.
Large language models are digitizing self-service query resolution across benefits, policy, and compensation domains. Mid-sized employers with limited HR staff are deploying these tools to reduce ticket volume by 50-70% within six months of implementation. The technology is digitizing tier-one support functions previously requiring human intervention, reallocating specialist capacity toward strategic workforce planning.
GDPR Article 22 enforcement and the EU AI Act's risk-classification framework are mandating human-in-the-loop overrides for automated performance scoring. Vendors serving French and German enterprise accounts must now maintain separate algorithmic governance documentation and consent audit trails. This regulatory compression is favoring established platforms with compliance engineering resources over lean challengers.
Subscription fatigue among mid-market buyers is accelerating consolidation onto unified suites with native payroll engines. Point solutions for recruitment or time-tracking face elevated churn as procurement teams prioritize vendor reduction and single-contract negotiation leverage. This pattern is most visible in United Kingdom professional services firms and Benelux manufacturing clusters where finance and HR leadership report jointly to shared services directors.
Human Resource Management Software Market Segmentation
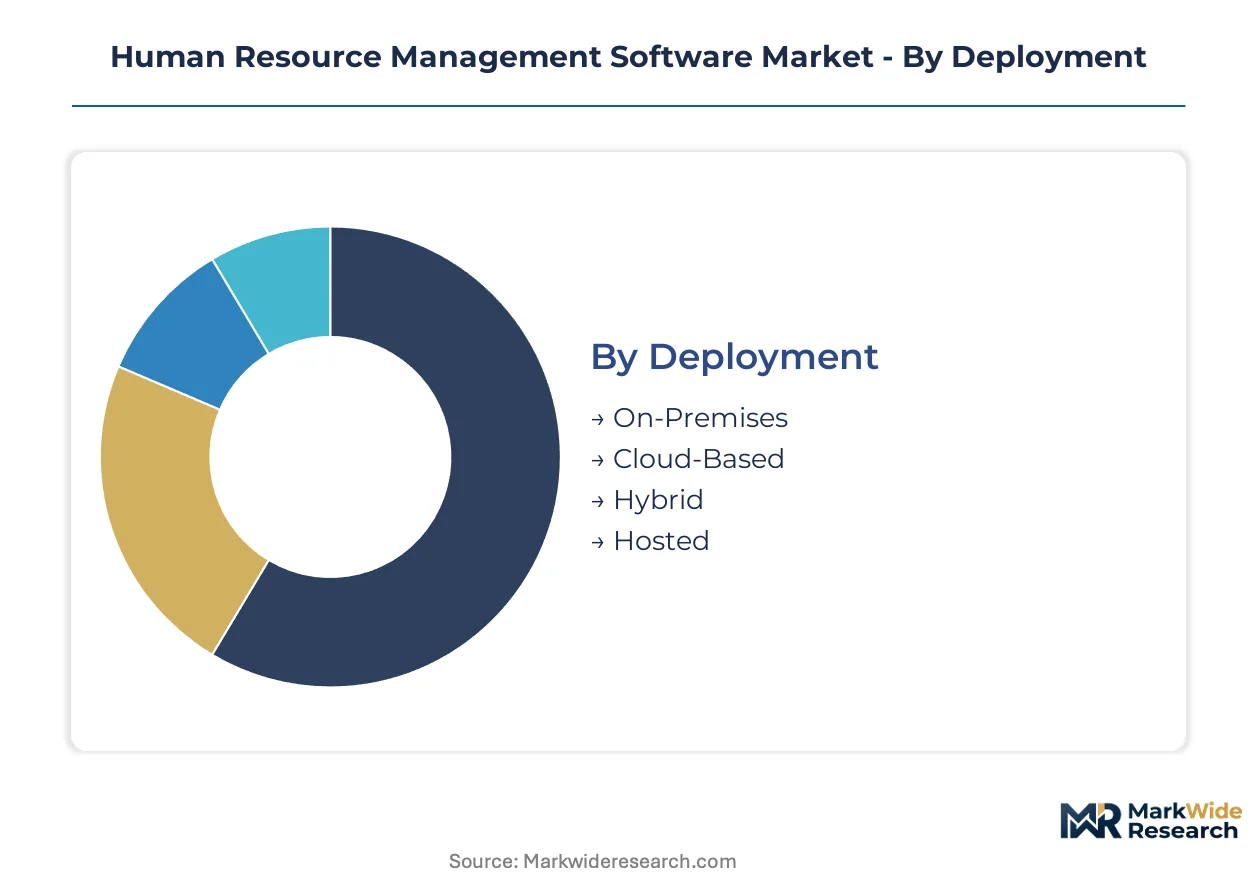
HR software segmentation reveals how deployment architecture, solution depth, and organizational scale create distinct competitive arenas with divergent margin structures and vendor specialization requirements. Each dimension carries implications for implementation complexity, recurring revenue durability, and regulatory exposure that shape procurement decisions across buyer tiers.
Deployment:
Cloud-native architectures dominate new customer acquisition while legacy infrastructure retains entrenched positions in regulated verticals.
- On-Premises:Single-tenant installations with localized data storage persist in German banking and French public sector where GDPR localization mandates block multi-tenant migration. Data residency requirements and sovereign cloud restrictions preserve this segment despite higher total cost of ownership.
- Cloud-Based:Multi-tenant SaaS delivery with API connectivity to finance and operations systems accelerates implementation cycles and reduces capital requirements. Mid-sized firms in India and professional services clusters in the United Kingdom prioritize this model under subscription economics.
- Hybrid:Split architectures separating sensitive payroll data on-premises while routing analytics workloads to cloud infrastructure. Healthcare delivery organizations in the United States deploy this pattern to satisfy HIPAA compartmentalization.
- Hosted:Dedicated single-tenant cloud instances managed by third-party infrastructure providers. Government agencies with procurement restrictions on public cloud prefer this intermediate model for compliance documentation.
The dominant share belongs to Cloud-Based deployment, while Hybrid configurations are closing the gap fastest among risk-averse regulated industries.
Solution Offering:
Module selection correlates with organizational maturity, with integrated suites displacing point solutions as procurement teams consolidate vendor relationships.
- Talent Acquisition:Applicant tracking systems and candidate relationship management tools automate sourcing pipelines. EEOC guidance on algorithmic hiring tools has triggered defensive procurement freezes among Fortune 1000 employers.
- Payroll Management:Jurisdiction-specific tax calculation engines with embedded compliance monitoring. Cross-border payroll complexity in fragmented European regulatory landscapes demands perpetual engineering investment.
- Performance Management:Goal-setting frameworks and continuous feedback mechanisms with automated scoring capabilities. EU AI Act explainability requirements are forcing architectural rewrites for European deployments.
- Workforce Analytics:Predictive models for turnover risk and succession readiness digitizing retention strategy. Healthcare systems and professional services firms deploy these tools to address clinical and knowledge worker shortages.
- Time & Attendance:Biometric verification and shift-scheduling modules with compliance documentation. State-level biometric privacy statutes in the United States elevate demand for embedded regulatory monitoring.
Workforce Analytics commands premium pricing, while Talent Acquisition faces margin compression from algorithmic accountability litigation.
Application:
Functional use-case selection reflects strategic priorities ranging from regulatory defense to talent development investment.
- Employee Engagement:Pulse surveys and sentiment analysis tools measuring organizational health. Large corporations deploy these systems to reduce voluntary turnover in competitive labor markets.
- Succession Planning:Leadership pipeline visualization and readiness assessment frameworks. Family-owned enterprises in Germany and Japan prioritize this application for intergenerational transition management.
- Compliance Management:Automated audit trails and regulatory change monitoring across multi-jurisdictional operations. GDPR Article 22 enforcement and EU AI Act risk classification mandate human-in-the-loop documentation.
- Compensation Management:Pay equity analytics and total rewards optimization with market benchmarking. Mid-sized firms use these tools to compete for talent against larger employers.
- Learning & Development:Skills gap analysis and personalized training pathway generation. Government agencies in Singapore and the United Arab Emirates deploy these systems for workforce reskilling initiatives.
Compliance Management anchors public sector procurement, though Learning & Development shows steepest expansion trajectory among digitally transforming enterprises.
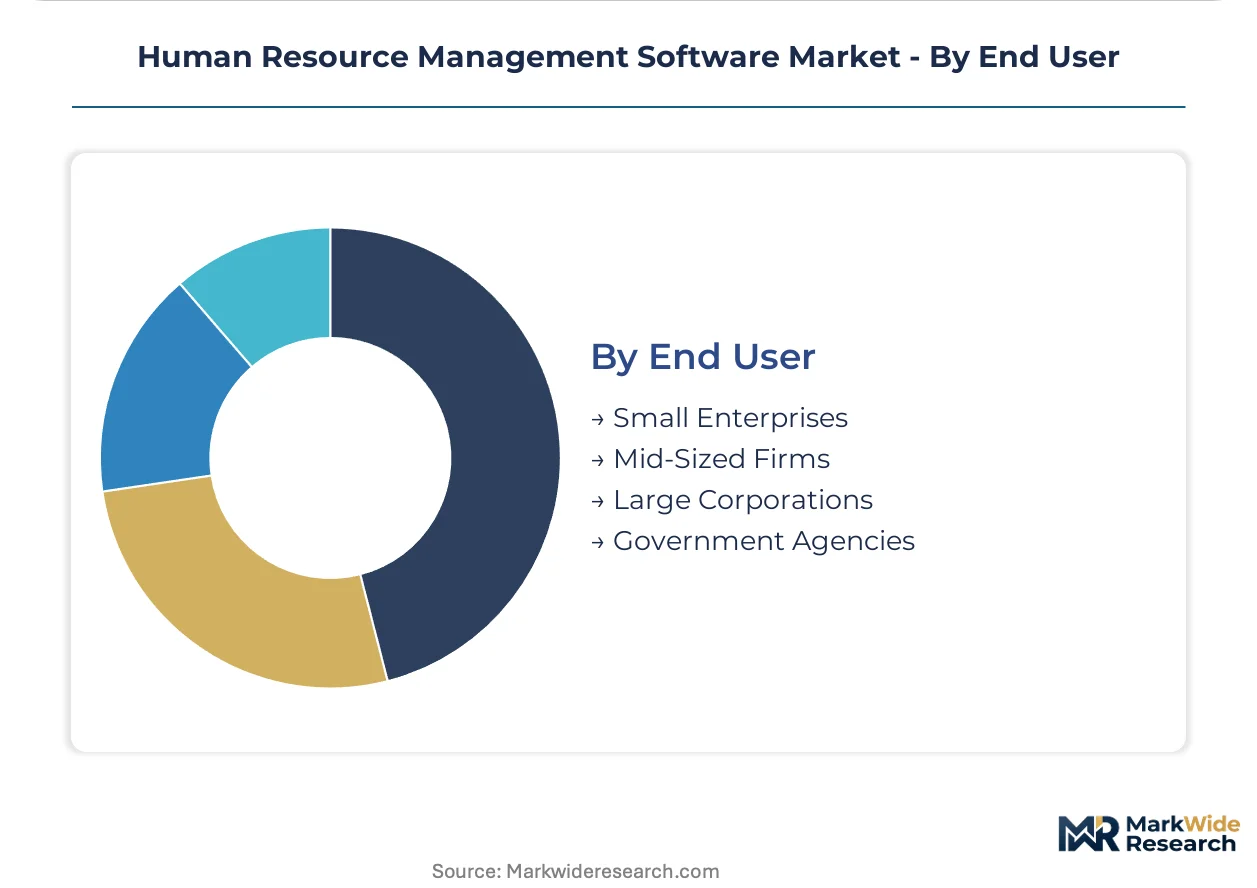
End User:
Organizational scale determines implementation complexity tolerance and integration requirements with existing finance and operations infrastructure.
- Small Enterprises:Organizations with sub-100 employees requiring minimal configuration and rapid deployment. Self-service onboarding tools with minimal implementation overhead dominate this tier.
- Mid-Sized Firms:Companies between 100-999 employees consolidating from point solutions onto unified suites. Subscription fatigue accelerates vendor reduction priorities in United Kingdom professional services and Benelux manufacturing.
- Large Corporations:Enterprises with 1000+ employees demanding deep ERP integration and localized payroll engines. Fortune 500 accounts anchor subscription revenue through unified architecture commitments.
- Government Agencies:Public sector entities with procurement restrictions and sovereign data requirements. Explainable AI architectures with consent-management workflows capture displaced contracts from non-compliant competitors.
Large Corporations generate the majority of vendor revenue, while Government Agencies represent the most rapidly expanding opportunity under regulatory displacement dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic fiber routes and cloud region interconnects anchor the United States' dominance in HR software infrastructure, while submarine cable landings in Mumbai and Chennai accelerate India's SaaS delivery capacity.
United States
Healthcare delivery organizations deploy clinical workforce platforms to address nursing shortages across Texas Medical Center and Mayo Clinic networks. HIPAA compartmentalization requirements sustain hybrid cloud architectures separating sensitive payroll data from analytics workloads. The EEOC's algorithmic hiring guidance triggers defensive procurement freezes among Fortune 1000 employers in Manhattan and Chicago financial districts.
Germany
Family-owned enterprises in Baden-Württemberg prioritize succession planning modules for intergenerational transition management. GDPR Article 22 enforcement mandates human-in-the-loop overrides for automated performance scoring. Frankfurt's banking cluster retains on-premises installations where sovereign cloud restrictions block multi-tenant migration.
India
Mid-sized manufacturing firms in Gujarat and Tamil Nadu digitize payroll workflows under PLI scheme incentives for SaaS infrastructure. The central bank's digital payment integration standards accelerate earned-wage-access feature deployment. Bangalore's technology corridor concentrates vendor engineering centers serving domestic and export markets.
United Kingdom
Professional services firms in London and Manchester consolidate from point solutions onto unified suites amid subscription fatigue. CSRD disclosure requirements elevate demand for workforce analytics documenting pay equity metrics. The Midlands manufacturing belt drives compliance management procurement for multi-jurisdictional operations.
France
Public sector entities in Île-de-France procure explainable AI architectures with consent-management workflows under EU AI Act risk classification. CNIL enforcement of automated decision-making transparency forces architectural investments in audit-trail documentation. Lyon and Toulouse healthcare clusters adopt credential verification modules tailored to clinical staffing gaps.
Human Resource Management Software Market Key Industry Players
On the supply side, the industry is consolidating around unified cloud-native architectures as point solutions face elevated churn from procurement teams prioritizing vendor reduction. Two strategic archetypes dominate: enterprise-scale platforms with deep ERP integration and localized payroll engines, and lightweight challengers specializing in rapid-deployment self-service tools for sub-500 employee segments. Competitive moves concentrate on M&A to acquire jurisdictional tax calculation capabilities and strategic partnerships embedding finance APIs for earned-wage-access features.
Within the enterprise-tier vector, Workday and SAP SuccessFactors exemplify unified architecture strategies anchoring Fortune 500 subscription revenue through multi-module commitments. BambooHR occupies a position representing the rapid-deployment archetype, targeting mid-market buyers with minimal implementation overhead. Oracle HCM Cloud sits within the cloud-native transition category, competing through database integration advantages.
| Leading Market Players |
|---|
| BambooHR |
| Oracle HCM Cloud |
| Workday |
| Qandle |
| Paycor |
| ADP |
| UKG Pro |
| SAP SuccessFactors |
| Rippling |
| Others |
Cost & Logistics Intelligence
Overcapacity in Bangalore's SaaS engineering corridor compresses vendor margins while accelerating cloud-native delivery migration. This utilization dynamic forces mid-tier platforms to absorb API integration costs and extend implementation support without pricing recovery.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates enterprise HR software procurement. Premium tiers anchor on deep ERP integration and localized payroll engines across multiple jurisdictions, while economy tiers compete through rapid-deployment self-service tools for sub-500 employee segments. Price differentiation rests on customization depth and compliance certification grade. Cost compression in the mid-market tier is intensifying because subscription fatigue drives vendor consolidation priorities. Small enterprises exhibit highest price sensitivity due to minimal implementation budgets, whereas Fortune 500 accounts prioritize architectural unification over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced GPU clusters and AI training infrastructure limit flows to certain cloud regions, constraining predictive analytics module development. Software engineering capacity concentrates in India, the United States, and Ireland. Raw material dependencies include cloud compute instances, biometric hardware components, and jurisdictional tax calculation databases. Single-source vulnerability runs through hyperscaler infrastructure concentration. Distribution runs through direct enterprise sales channels consolidating around partner ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification framework constitutes a regulatory inflection forcing architectural reinvestment across European deployments. This disruption favors platforms with compliance engineering resources over lean challengers.
For Market Incumbents: Build explainable-AI documentation moats through consent-management workflow investments and audit-trail infrastructure. Consolidate jurisdictional payroll engine capabilities via targeted capability acquisition to neutralize cross-border compliance fragmentation. Defensive positioning against emerging cloud-native challengers requires deepening ERP integration moats and embedding finance APIs for earned-wage-access features.
For New Entrants and Emerging Players: Build out clinical workforce platform specialization targeting credential verification and shift-scheduling modules for United States health systems. White-space concentration exists in mid-sized manufacturing clusters under India's PLI scheme incentives. Go-to-market execution should anchor on rapid-deployment self-service onboarding with minimal implementation overhead to capture sub-500 employee displacement from legacy point solutions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among unified-suite vendors with native payroll engines and multi-module commitments. Long-term viability over the projection horizon favors platforms with jurisdictional tax calculation capabilities and compliance engineering depth. Acquisition target archetype: mid-tier vendors with MLOps talent shortages but strong domain positioning. Signal to watch: EEOC enforcement actions triggering defensive procurement freezes among Fortune 1000 employers.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies talent acquisition, payroll, and analytics modules to reduce vendor fragmentation under subscription fatigue pressures. |
| Acquisition of Specialist Firm | Captures jurisdictional tax calculation capabilities required for European cross-border payroll compliance complexity. |
| Strategic Partnership | Embeds finance APIs enabling earned-wage-access features for gig-economy staffing firm expansion. |
| Product Launch | Deploys generative interfaces for self-service query resolution reducing HR ticket volume in mid-sized firms. |
| Geographic Expansion | Establishes sovereign cloud instances in Germany and France to satisfy GDPR localization mandates blocking multi-tenant migration. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CHROs, IT procurement officers, payroll operations directors, and compliance engineering leads. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU regulatory filings under GDPR and the EU AI Act, and GPO contract databases. Bottom-up triangulation across deployment model, organization size, vertical specialization, and regional adoption patterns was cross-checked against top-down market sizing.
Calibration against historical implementation timelines and regulatory change velocity anchored the analytical framework. Segmentation dimensions modeled include deployment architecture, solution module depth, organizational scale tier, and jurisdictional compliance complexity. CAGRs were derived from growth rate convergence analysis across the projection horizon. Industry-specific forecast inputs incorporated PLI scheme incentive disbursement patterns and EEOC enforcement trajectory indicators.
Stress conditions across cloud infrastructure cost inflation, regulatory enforcement intensity, and MLOps talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subscription economics durability and compliance cost pass-through capacity. Material shifts in EU AI Act implementation timelines or EEOC algorithmic hiring guidance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Photogrammetry Software Market
Software & Services
Performing Arts Software Market
Software & Services
Global Membership Management Software Market
Software & Services
Website Builder Tool Market
Software & Services
Enterprise Application Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
Testing As a Service (Taas) Market
Software & Services
Load Testing Software Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Mind Mapping Software Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Global Quoting Software Market
Software & Services
Backend-As-A-Service Market
Software & Services
Global AR Game Engine Software Market
Software & Services
Managed Information Services Market