
 Building Information Modeling (BIM) Extraction Software Market | 2026-2036
Building Information Modeling (BIM) Extraction Software Market Size, Share, and Industry Trends Forecast 2026-2036
Building Information Modeling (BIM) Extraction Software Market Outlook
Market Context
Cloud-native architecture is consolidating around containerized microservices that replace legacy monolithic CAD extraction engines. Autodesk leverages its Forge platform to sustain developer ecosystem density across AEC workflows. Nemetschek Group anchors its portfolio through Allplan and Graphisoft interoperability layers. Bentley Systems differentiates via digital twin integration with iTwin infrastructure.
Technical Definition and Structural Segments
Building Information Modeling (BIM) Extraction Software comprises algorithmic tools that parse IFC, Revit, or proprietary model formats to isolate geometric, semantic, and parametric data for cost estimation, scheduling, and facilities management. Cloud-based deployment leads current revenue contribution while hybrid architectures capture fastest expansion as enterprises balance latency-sensitive edge processing with centralized model repositories. Architects and engineers represent the mature end-user base, whereas owners emerge as the margin-rich segment demanding lifecycle asset analytics rather than design-phase extraction alone.
Regulatory Frame and Outlook
The UK Building Regulations Part L and the EU Energy Performance of Buildings Directive mandate machine-readable building data, directly expanding extraction software procurement scope. The US General Services Administration BIM standards and ISO 19650 certification requirements in Commonwealth markets shape product functionality roadmaps. Stakeholders must monitor whether emerging carbon disclosure rules transform extraction tools from design utilities into mandatory compliance infrastructure.
Market Dynamics
Cloud-native microservices architectures are displacing monolithic CAD extraction engines across architecture, engineering, and construction workflows, compressing deployment cycles from months to weeks while forcing legacy vendors to re-platform or lose enterprise accounts.
Growth Catalysts
- UK Building Regulations Part L:Mandates for machine-readable energy performance data require automated extraction tools that parse thermal properties from IFC models, directly expanding procurement scope for compliance software.
- Industrial facility renovation:Germany's manufacturing sector drives demand for as-built model extraction to support retrofit planning and carbon accounting across aging production plants.
- IFC 4.3 schema adoption:Enhanced semantic richness in open building data standards enables deeper parametric extraction for facilities management and lifecycle analytics.
Market Restraints
- Specialized talent scarcity:Shortage of developers fluent in both computational geometry and AEC domain knowledge inflates implementation costs for complex extraction pipelines.
- Proprietary format lock-in:Autodesk's Revit API restrictions and Nemetschek's closed ecosystems fragment data interoperability, forcing buyers into vendor-specific toolchains.
- Edge processing hardware costs:Latency-sensitive extraction workloads require GPU-accelerated local infrastructure, raising total cost of ownership for mid-sized firms.
Strategic Opportunities
- EU Energy Performance of Buildings Directive:Renovation passport requirements create mandated demand for automated extraction of building stock data across member states.
- Digital twin convergence:Integration of BIM extraction with IoT sensor streams and real-time analytics platforms opens lifecycle service revenue beyond design-phase licensing.
- Owner-operator segment:Real estate investment trusts and infrastructure funds represent underpenetrated buyers seeking asset-level data for portfolio risk management.
Industry Challenges
- ISO 19650 certification complexity:Multi-stage audit timelines for information management compliance delay software procurement decisions by six to twelve months.
- Legacy ERP integration friction:Custom middleware development for connecting extraction outputs to SAP, Oracle, and proprietary cost databases consumes implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Information Modeling (BIM) Extraction Software Market |
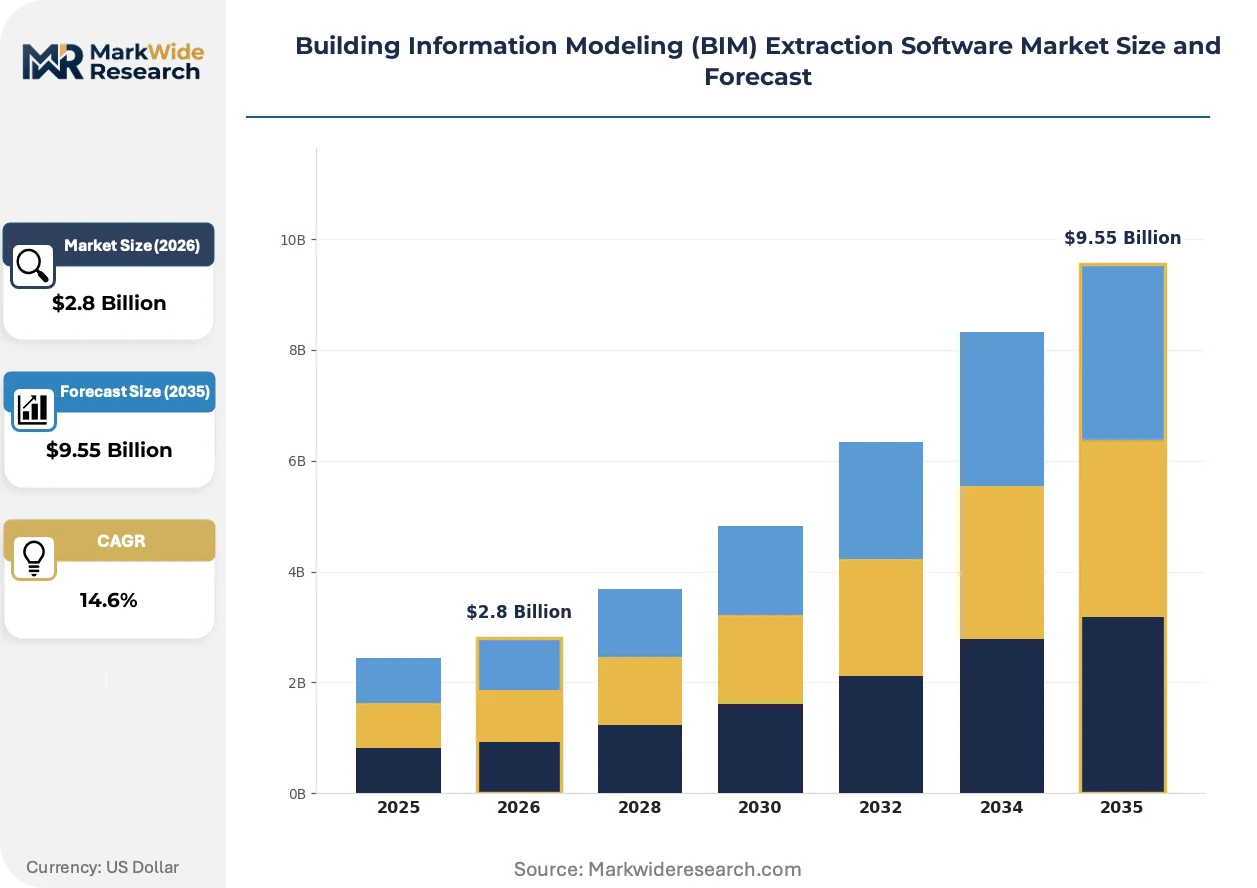
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, SaaS End User: Architects, Engineers, Contractors, Owners Deployment Model: Public Cloud, Private Cloud, Community Cloud, Edge Computing Feature: 3D Modeling, Data Analytics, Collaboration Tools, Visual Simulation |
| Companies Covered | Autodesk, Nemetschek Group, Bentley Systems, Trimble, Hexagon AB, Dassault Systèmes, Procore Technologies, AVEVA Group, RIB Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Information Modeling (BIM) Extraction Software Market Strategic Shifts
Generative AI and large language models are embedding into extraction workflows, automating semantic classification of building elements while compressing manual model review cycles that previously dominated project timelines.
Neural-network-based element recognition is overtaking rule-based geometric parsing in commercial extraction tools. MEP contractors in the United States adopt these systems to accelerate clash detection and quantity takeoff preparation. The shift is compressing pre-construction scheduling from weeks to days while elevating software vendors who own training data advantages.
EU CSRD disclosure requirements are mandating granular building-level carbon data for real estate portfolios. Asset managers must now extract embodied carbon figures from BIM models to satisfy Scope 3 reporting obligations. German and French property funds are procuring extraction tools with automated EPD mapping to avoid manual data collection penalties.
Subscription pricing for extraction modules is displacing perpetual licenses across mid-market architecture firms. Channel partners and systems integrators capture margin by bundling extraction tools with implementation services rather than reselling standalone seats. This pattern concentrates in the United Kingdom where ISO 19650 compliance consulting drives attached software sales.
Building Information Modeling (BIM) Extraction Software Market Segmentation
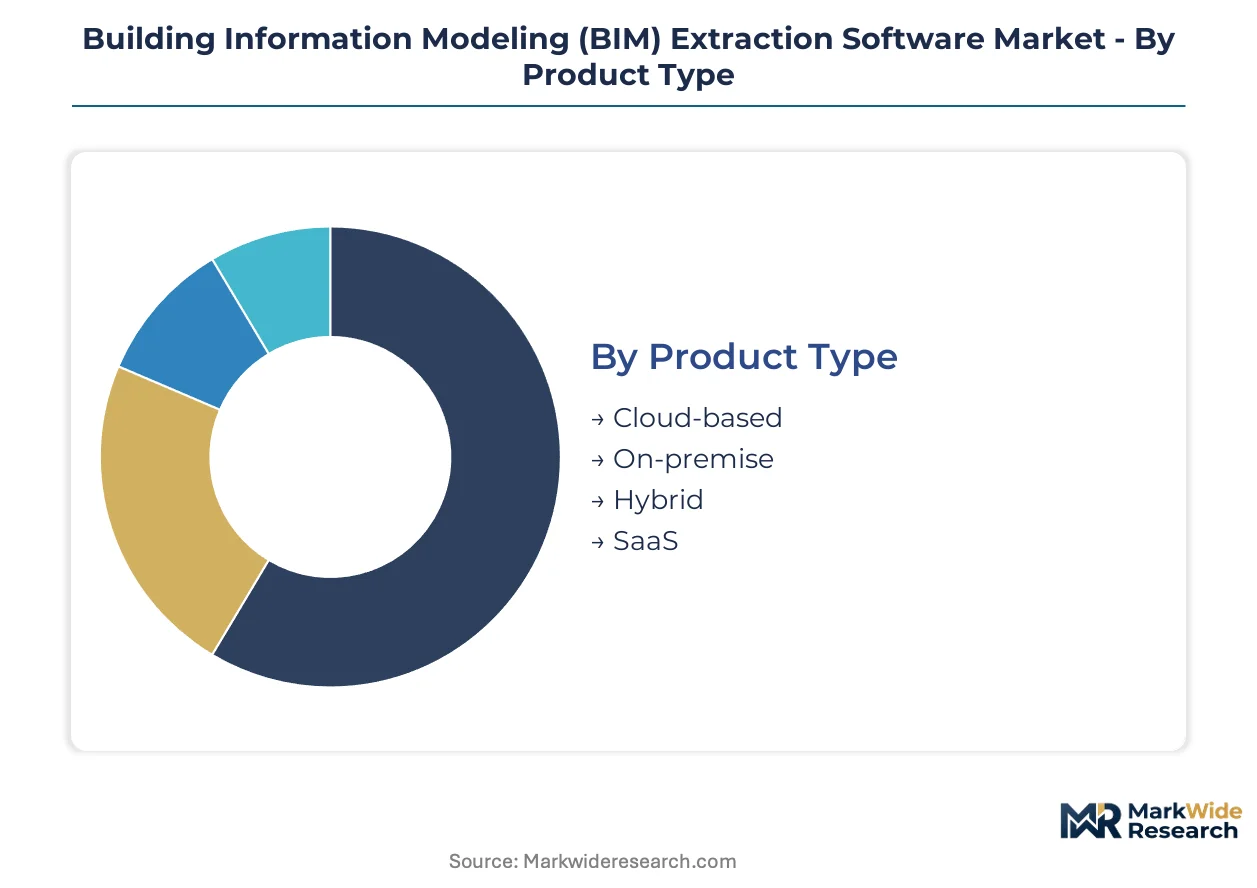
BIM extraction software segments reflect divergent technical requirements across project phases. Deployment architecture and user sophistication drive purchasing criteria more than feature breadth alone.
Product Type:
Containerized microservices architectures separate latency-tolerant processing from real-time extraction workloads.
- Cloud-based:Multi-tenant SaaS platforms host model parsing engines on hyperscaler infrastructure. US commercial construction teams favor these systems for distributed quantity takeoff coordination across project sites.
- Hybrid:Split architectures process sensitive IP locally while pushing anonymized geometry to centralized repositories. German industrial facility renovators deploy hybrid stacks to satisfy data residency requirements while accessing cloud-scale compute.
- On-premise:Air-gapped installations serve defense and critical infrastructure clients with classified project workflows.
- SaaS:Subscription modules integrate extraction capabilities into broader AEC software suites through API layers.
Cloud-based leads on scale; hybrid leads on momentum.
End User:
Procurement authority shifts downstream as building data becomes a balance-sheet asset.
- Owners:Real estate investment trusts and infrastructure funds extract lifecycle analytics for portfolio risk management. UK asset managers under CSRD disclosure rules automate embodied carbon calculations from IFC models to satisfy Scope 3 reporting.
- Engineers:Structural and MEP disciplines parse parametric data for clash detection and systems coordination. US contractors accelerate pre-construction scheduling from weeks to days through automated quantity takeoff.
- Architects:Design-phase extraction supports code compliance checking and energy performance simulation.
- Contractors:Field teams consume extracted schedules and cost data for procurement and subcontractor coordination.
Engineers dominate current seat volume; owners climb the fastest.
Deployment Model:
Latency sensitivity and data sovereignty dictate infrastructure location.
- Public Cloud:Shared hyperscaler resources serve mid-market firms with standard compliance requirements.
- Private Cloud:Dedicated tenant environments host extraction pipelines for financial services and healthcare real estate portfolios.
- Edge Computing:GPU-accelerated local nodes process large-format models without upload latency. German manufacturing facility retrofits deploy edge extraction for as-built documentation of aging production plants.
- Community Cloud:Shared infrastructure among consortium members supports joint venture projects with mutual data access protocols.
Public cloud leads on scale; edge computing leads on momentum.
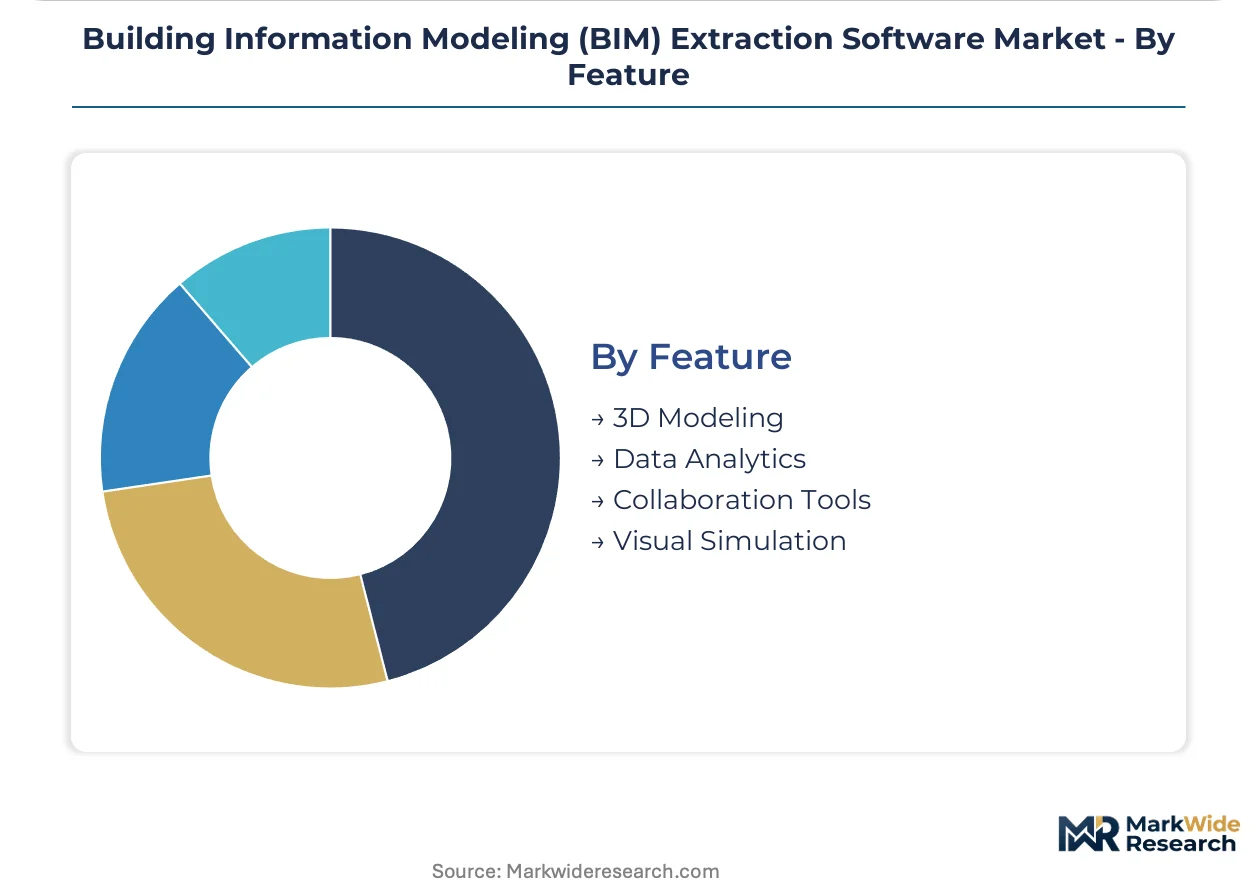
Feature:
Functional modules align with distinct workflow integration points.
- Data Analytics:Parametric aggregation engines feed business intelligence dashboards for cost forecasting and carbon accounting. French property funds automate EPD mapping to avoid manual data collection penalties under EU disclosure rules.
- 3D Modeling:Geometric parsing isolates building elements from IFC, Revit, and proprietary formats for downstream applications.
- Collaboration Tools:Multi-stakeholder annotation and version control synchronize extraction outputs across distributed teams.
- Visual Simulation:Rendered walkthroughs and virtual reality exports support client presentations and regulatory submissions.
3D modeling leads on scale; data analytics leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial manufacturing belt concentrates BIM extraction software procurement for facility renovation and carbon accounting workflows, with demand radiating from automotive production clusters into adjacent construction technology markets.
United States
Commercial construction teams in Texas and California deploy automated quantity takeoff tools to compress pre-construction scheduling. The General Services Administration BIM standards mandate machine-readable building data for federal projects. MEP contractors in the Pacific Northwest adopt neural-network-based element recognition to accelerate clash detection cycles.
Germany
Industrial facility renovators in Bavaria and North Rhine-Westphalia drive demand for as-built model extraction to support retrofit planning. The country's national building energy regulations require granular thermal property documentation from IFC models. Manufacturing plant operators in Baden-Württemberg deploy edge computing nodes for latency-sensitive extraction of aging production facility data.
United Kingdom
Asset managers in London and the Southeast automate embodied carbon calculations from BIM models to satisfy CSRD disclosure obligations. Building Regulations Part L mandates machine-readable energy performance data for compliance submissions. ISO 19650 certification consulting in the Midlands drives attached software sales through channel partners.
France
Property funds in Île-de-France procure extraction tools with automated EPD mapping to avoid manual data collection penalties under EU disclosure rules. The national implementation of the Energy Performance of Buildings Directive creates mandated demand for building stock data extraction. Real estate investment trusts in Lyon and Auvergne-Rhône-Alpes seek asset-level analytics for portfolio risk management.
China
State-backed infrastructure developers in the Yangtze River Delta and Pearl River Delta pilot digital twin integration for transportation and utility projects. The country's dual carbon goals drive procurement of extraction tools for embodied carbon quantification in commercial real estate. Municipal governments in Beijing-Tianjin-Hebei mandate BIM deliverables for public construction tenders.
Building Information Modeling (BIM) Extraction Software Market Competitive Environment
Global majors compete with regional champions across platform ecosystem density and developer community reach. The market structure consolidates around three to five platform owners with sufficient API infrastructure to sustain third-party tool integration. Two strategic archetypes dominate: design software incumbents extending extraction modules from existing CAD platforms, and construction management specialists embedding extraction into project delivery workflows. Competitive moves center on API ecosystem expansion and strategic partnerships with facilities management software vendors.
Within the design-platform tier, Autodesk and Nemetschek Group exemplify contrasting geographic and architectural approaches. Autodesk leverages its San Rafael-based developer ecosystem to sustain integration density across North American AEC workflows. Nemetschek Group anchors European market presence through its Munich-originated portfolio of interoperability layers. Bentley Systems occupies a position at the infrastructure-specialist intersection, with its Exton-based operations differentiating through digital twin integration capabilities.
| Leading Market Players |
|---|
| Autodesk |
| Nemetschek Group |
| Bentley Systems |
| Trimble |
| Hexagon AB |
| Dassault Systèmes |
| Procore Technologies |
| AVEVA Group |
| RIB Software |
| Others |
Value Chain & Pricing Dynamics
EU CSRD disclosure mandates gate both qualified supply and premium-tier pricing access for BIM extraction software vendors, as asset managers under Scope 3 reporting obligations demand automated embodied carbon calculation modules that only certified developers can deliver.
Pricing Analysis
Input-cost pass-through from GPU-accelerated edge computing hardware and specialized computational geometry talent inflates implementation pricing for hybrid deployment architectures. Pricing stratifies across ISO 19650-certified premium tiers, volume-scaled standard subscriptions, and economy SaaS modules with limited API access. Cost compression in mid-market cloud tiers is intensifying because hyperscaler infrastructure commoditizes base parsing engines. Contractors exhibit highest price sensitivity due to project-based procurement cycles, while real estate investment trusts accept premium pricing for lifecycle analytics capabilities.
Supply Chain Analysis
Computational geometry engine development rests on specialized software talent concentrated in Germany, the United States, and the United Kingdom. Core inputs include open-source IFC parsing libraries, hyperscaler cloud infrastructure, and GPU hardware from NVIDIA and AMD supply channels. Single-source vulnerability concentrates in Autodesk's Revit API ecosystem, which fragments data interoperability for extraction tool developers. Distribution runs through channel partners and systems integrators who bundle implementation services with software licenses, particularly in UK markets where compliance consulting drives attached sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
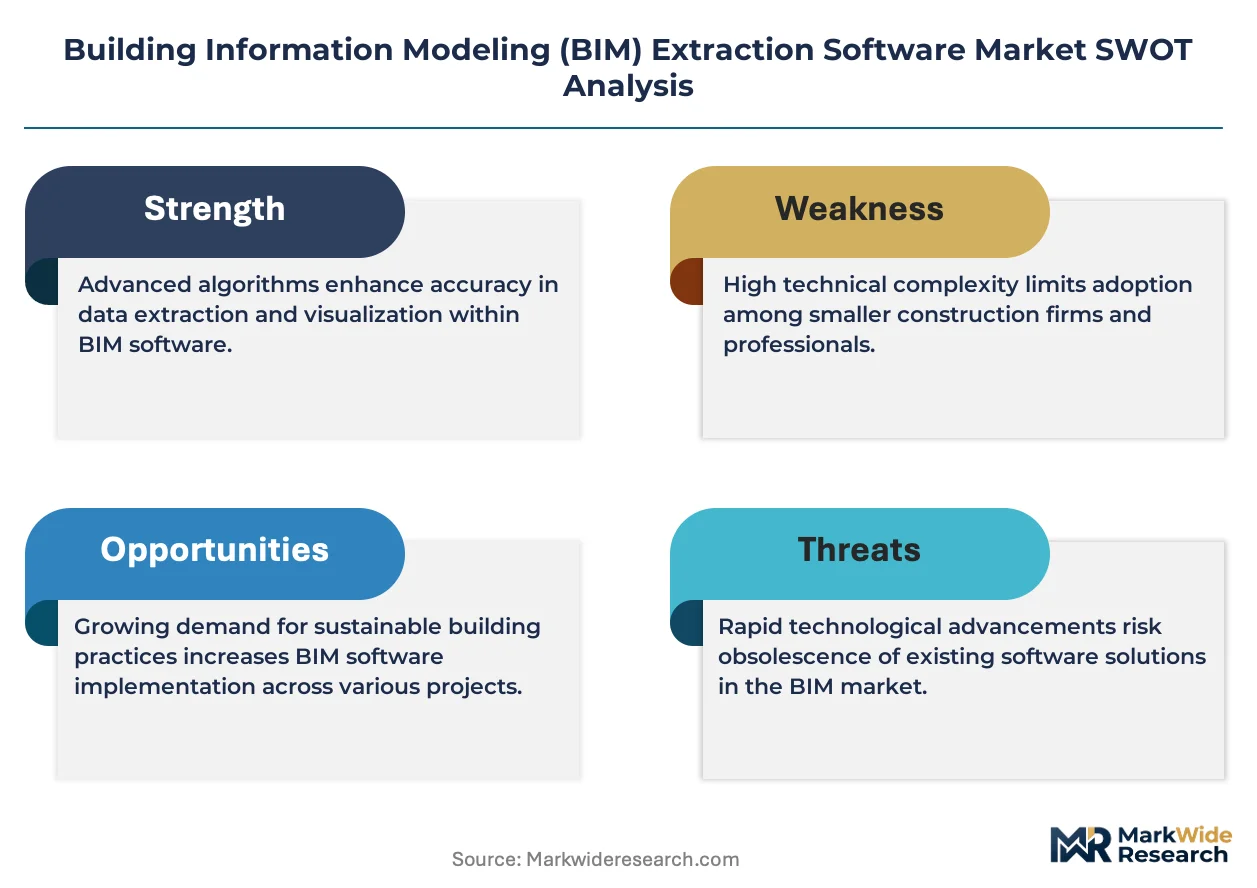
Analyst Recommendations
This market represents a late-cycle quality story as procurement authority shifts from design-phase architects toward owner-operators demanding lifecycle asset analytics with premium specification requirements.
For Market Incumbents: Extend API ecosystem density through strategic partnerships with facilities management software vendors to defend against construction management specialists embedding extraction into project delivery workflows. Invest in ISO 19650 certification consulting capabilities to capture channel margin in UK and Commonwealth markets. Prioritize backward integration into IoT sensor data streams for digital twin convergence revenue beyond design-phase licensing. For New Entrants and Emerging Players: Begin with owner-operator segments in French and German property funds where automated EPD mapping demand outpaces incumbent solution coverage. Target edge computing deployment for German industrial facility renovators with data residency requirements. Pursue white-label API licensing to construction management platforms seeking rapid extraction capability integration without internal R&D investment. For Investors and Strategic Acquirers: Roll-up economics work for regional compliance specialists because fragmented ISO 19650 certification consulting markets concentrate buyer relationships that software vendors struggle to replicate organically. Long-term viability hinges on lifecycle service revenue expansion beyond perpetual design-phase licenses. Monitor EU Energy Performance of Buildings Directive enforcement intensity as the inflection indicator for mandated building stock data extraction demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Forge and iTwin API layers sustain developer ecosystem density across North American AEC workflows. |
| Acquisition of Specialist Firm | Computational geometry boutiques with training data advantages accelerate neural-network element recognition deployment. |
| Strategic Partnership | Facilities management software alliances open lifecycle service revenue beyond design-phase extraction licensing. |
| Geographic Expansion | German industrial belt penetration captures carbon accounting demand from automotive production facility renovators. |
| Product Launch | Automated EPD mapping modules satisfy EU CSRD disclosure obligations for French and UK asset managers. |
Study Parameters
Bottom-up owner-operator demand modeling reconciled against top-down vendor supply tracking forms the analytical core, combining primary interviews with BIM managers, facilities directors, IT procurement officers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory implementation timelines.
Input-output matrix framing maps deployment architecture adoption rates against end-user procurement authority shifts across the projection horizon, segmenting by cloud-hybrid-on-premise infrastructure, organization size, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs derive from modeled seat expansion and average revenue per user trajectories, with IFC 4.3 schema adoption velocity and CSRD enforcement intensity as key forecast inputs.
Caveats apply where EU Energy Performance of Buildings Directive implementation delays or Revit API access restriction tightening could materially shift the outlook. Forecasts reflect assumptions around regulatory mandate timelines and hyperscaler infrastructure cost trajectories. A small set of named triggers—including ISO 19650 certification audit backlogs and carbon disclosure rule expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Content Moderation Software Market
Software & Services
Global Qualitative Data Analysis Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Global Virtual Desktop Market
Software & Services
Global Android Kiosk Software Market
Software & Services
Logistics Services Software Market
Software & Services
Global OEE Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Load Balancing Software Market
Software & Services
Global Ipad POS Software Market
Software & Services
Global Landscape Software Market
Software & Services
United States IT Services Market
Software & Services
Global Client Portal Software Market
Software & Services
Global Personalisation Software Market