
 Human Chorionic Gonadotropin Market | 2026-2036
Human Chorionic Gonadotropin Market Size, Share, and Industry Trends Forecast 2026-2036
Human Chorionic Gonadotropin Market Outlook
The capability gap between recombinant manufacturing scale and traditional extraction methods is collapsing as purification technology becomes commoditized. Merck & Co., Inc. leverages its biologics infrastructure to sustain supply reliability for fertility clinic networks. Organon anchors its position through specialized gynecological therapeutic portfolios. Ferring Pharmaceuticals differentiates via concentrated investment in hypogonadism management channels.
Human chorionic gonadotropin is a heterodimeric glycoprotein hormone comprising alpha and beta subunits, with the beta subunit conferring biological specificity for luteinizing hormone receptor binding; recombinant production in Chinese hamster ovary cell lines yields batch-to-batch consistency critical for therapeutic dosing in controlled ovarian stimulation. Recombinant HCG commands premium positioning due to reduced immunogenicity risk and standardized potency compared with urine-derived alternatives. Injectable delivery dominates clinical workflows, though subcutaneous formulations are gaining protocol adoption in fertility clinics seeking reduced patient burden.
FDA biologics licensing requirements and EMA's Good Manufacturing Practice enforcement for peptide hormones govern market access and batch release protocols. The WHO's prequalification standards for fertility medicines additionally shape procurement criteria for public health programs in emerging markets. Stakeholders must monitor evolving biosimilar pathway clarity and reimbursement compression dynamics in concentrated fertility clinic networks.
Market Dynamics
Recombinant manufacturing scale is collapsing the cost premium against urinary-derived HCG, forcing purification technology investments to become table stakes rather than differentiators for fertility clinic suppliers.
Growth Catalysts
- Assisted reproductive technology protocol standardization:Fertility networks in the United States, Germany, and Japan are harmonizing stimulation regimens around recombinant HCG dosing schedules, creating predictable demand pull through specialized clinic channels.
- FDA biologics licensing pathway maturation:Clarity in purity validation requirements for peptide hormones has reduced regulatory uncertainty for domestic manufacturers, compressing batch release timelines for injectable fertility medicines.
- Subcutaneous formulation adoption:Reduced patient burden protocols in outpatient fertility settings are displacing intramuscular administration, expanding addressable patient populations through self-injection training programs.
Market Restraints
- Chinese hamster ovary cell line supply concentration:Master cell bank repositories for recombinant glycoprotein production concentrate in three contract manufacturing organizations, creating single-source vulnerability for batch consistency.
- EMA Good Manufacturing Practice peptide hormone enforcement:Batch release documentation requirements for sterility assurance and endotoxin testing have extended quality control timelines by four to six weeks for European market entry.
- Urinary-derived HCG price compression:Post-menopausal urine collection networks in Eastern Europe and China sustain residual demand for lower-cost alternatives, capping premium recombinant pricing power in reimbursement-constrained markets.
Strategic Opportunities
- Indian fertility clinic network expansion:Metro hospital chains in Mumbai, Delhi, and Bangalore are building captive reproductive medicine units, creating demand for cold-chain reliable HCG supply with WHO prequalification status.
- Hypogonadism management channel development:Endocrinology practices are adopting HCG monotherapy for male testosterone preservation, opening prescriber relationships outside traditional gynecological settings.
- Biosimilar pathway exploitation:Reference product exclusivity cliffs for legacy recombinant formulations are creating abbreviated approval opportunities for manufacturers with demonstrated analytical biosimilarity.
Industry Challenges
- Glycosylation pattern analytical capability scarcity:Mass spectrometry and capillary electrophoresis expertise for batch-to-batch carbohydrate heterogeneity characterization concentrates in contract testing laboratories, creating quality control bottlenecks.
- Legacy vial-filling line reconfiguration:Multi-dose presentation requirements for fertility clinic settings demand aseptic processing equipment upgrades that strain capital allocation for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Chorionic Gonadotropin Market |
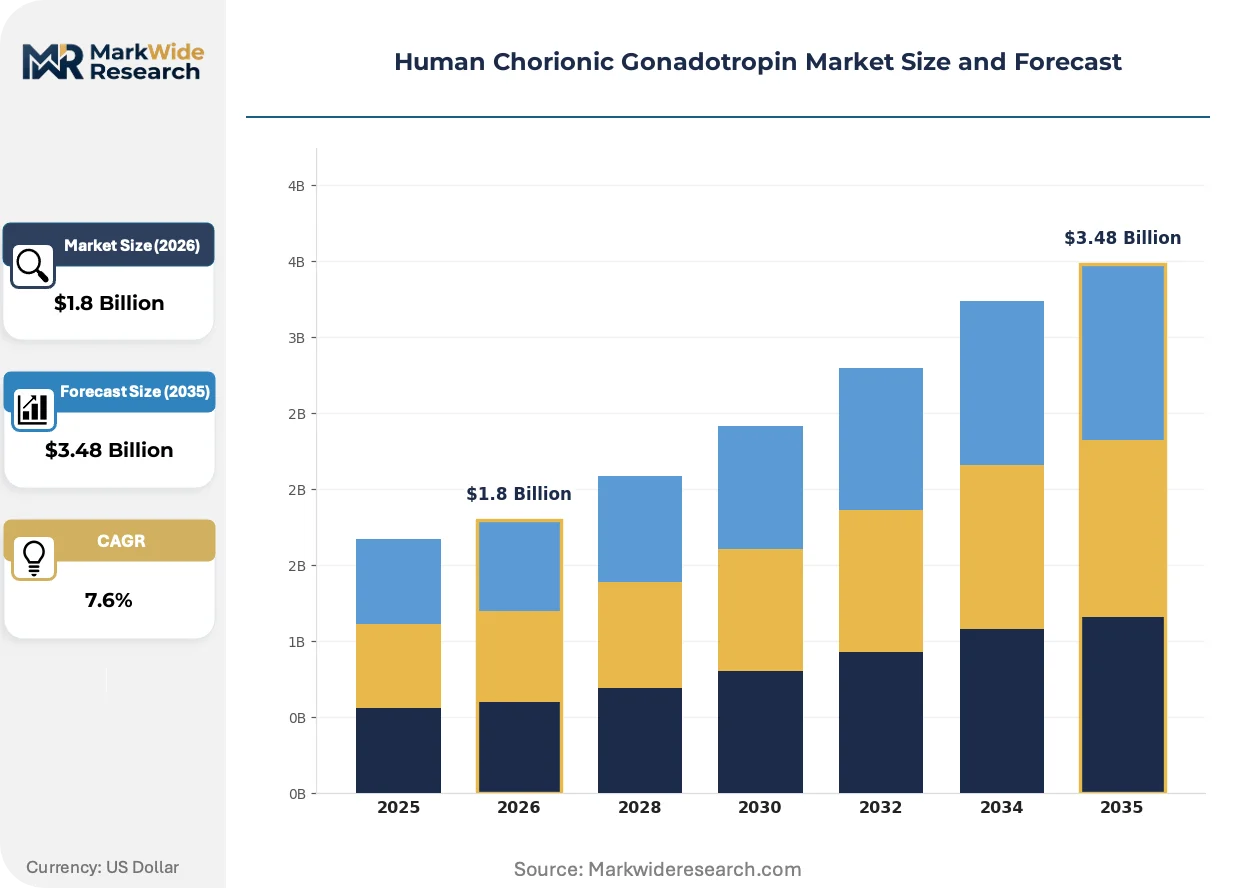
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine-Derived HCG, Recombinant HCG, Synthetic HCG, Purified HCG Application: Fertility Treatment, Cryptorchidism Therapy, Hypogonadism Management, Weight Loss Programs End User: Fertility Clinics, Oncology Centers, Diagnostic Laboratories, Specialized Medical Practices Delivery Mode: Injectable, Subcutaneous, Intramuscular, Nasal Spray |
| Companies Covered | Sun Pharmaceutical Industries Ltd, Organon, Merck & Co., Inc., Zydus Lifesciences Ltd., Sanzyme, Ferring Pharmaceuticals, Lupin Limited, Intas Pharmaceuticals Ltd., Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Chorionic Gonadotropin Market Strategic Shifts
Lyophilized formulation stability improvements and cold-chain logistics automation are compressing the operational gap between centralized manufacturing and point-of-care preparation workflows in fertility medicine delivery.
Single-use bioreactor technology for Chinese hamster ovary cell culture is bifurcating the manufacturing base between stainless-steel facility incumbents and flexible modular entrants. Contract development and manufacturing organizations in Switzerland and Singapore are adopting disposable bag systems to reduce cross-contamination risk between glycoprotein campaigns. This technology compression is enabling mid-scale entrants to achieve comparable batch yields without fixed-asset intensity, eroding the scale advantages of legacy recombinant infrastructure.
EMA's Medical Device Regulation harmonization with pharmaceutical quality systems is forcing combination product reclassification for pre-filled HCG syringes and auto-injector platforms. Manufacturers must now submit dual technical documentation for drug constituent and device constituent, extending development timelines by twelve to eighteen months. Fertility clinic networks in France and the Netherlands are responding by consolidating procurement around established pen-injector formats rather than novel delivery mechanisms.
Direct-to-clinic inventory management is replacing wholesale distribution for high-volume fertility networks. Third-party logistics providers with validated cold-chain capabilities are positioning regional distribution hubs within four-hour transport radius of major metropolitan treatment centers. This channel restructuring is most visible in the United States, where integrated delivery networks in Texas, California, and New York are negotiating consignment arrangements that shift working capital burden upstream to manufacturers.
Human Chorionic Gonadotropin Market Segmentation
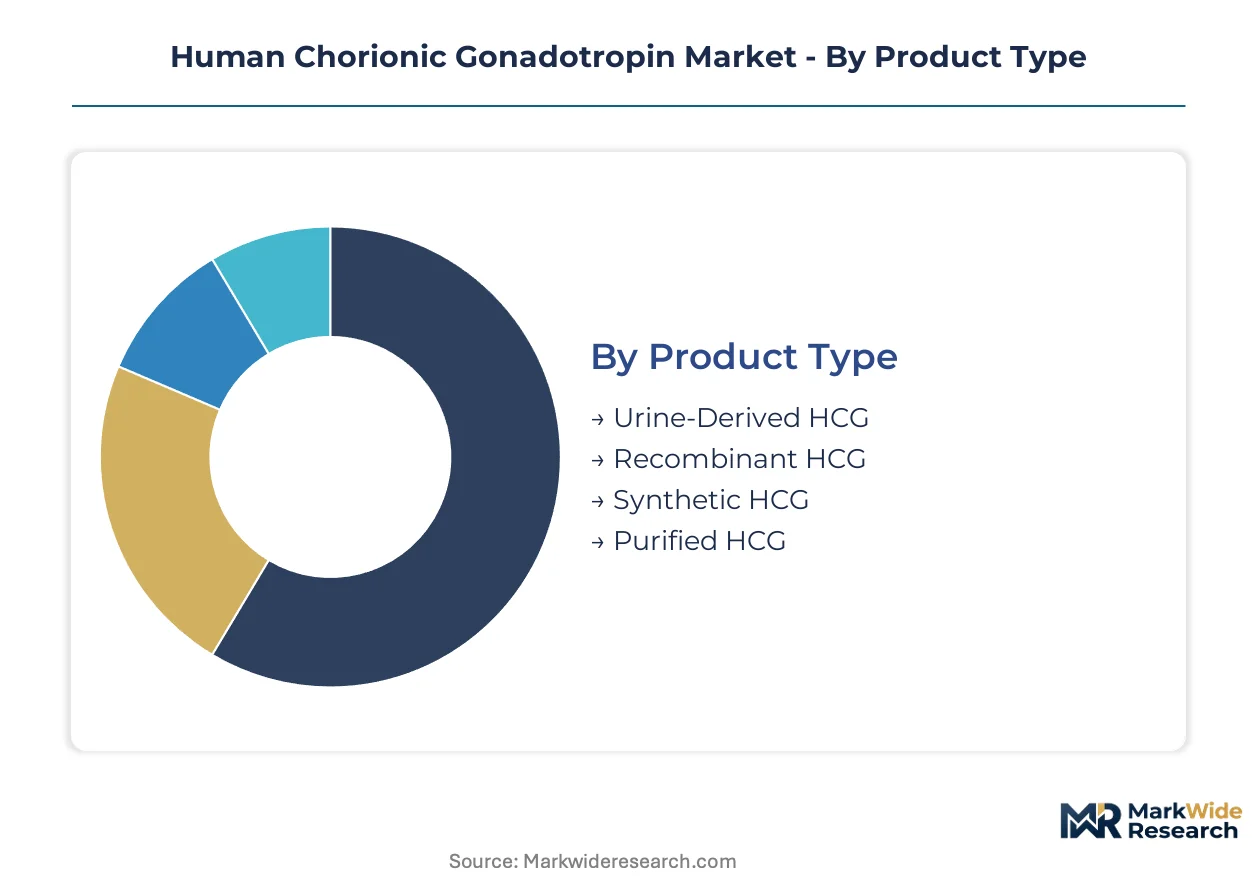
Segmentation in the HCG market tracks how purification technology, clinical application, and delivery innovation concentrate margin pools across distinct patient pathways. Understanding these divisions reveals where recombinant manufacturing investments yield sustainable pricing power versus commoditized alternatives.
Product Type:
Margin concentration follows purification sophistication, with recombinant platforms commanding premium positioning against extraction-based alternatives.
- Recombinant HCG:Manufactured in Chinese hamster ovary cell lines, this segment delivers batch-to-batch glycoprotein consistency essential for controlled ovarian stimulation dosing. Fertility clinics in the United States and Germany are standardizing procurement around recombinant formulations to minimize immunogenicity risk and simplify inventory management. Reduced endotoxin variability compresses quality control overhead for high-volume treatment centers.
- Urine-Derived HCG:Isolated from post-menopausal urine collections, this extraction-based product retains residual demand in reimbursement-constrained markets where cost sensitivity outweighs potency standardization concerns. Collection networks in Eastern Europe and China sustain supply for price-sensitive public health programs, though batch heterogeneity limits adoption in premium fertility networks.
- Synthetic HCG:Peptide synthesis approaches yield simplified molecular structures without native glycosylation patterns, restricting biological activity to research applications and limited therapeutic niches.
- Purified HCG:Enhanced chromatographic refinement of urinary extracts narrows potency variance without full recombinant conversion, occupying a mid-tier positioning for clinics transitioning procurement standards.
Recombinant HCG holds installed capacity. Urine-Derived HCG is rotating up the share rankings in emerging market public procurement.
Application:
Volume concentration tracks assisted reproductive technology penetration, while emerging therapeutic categories reshape prescriber relationships beyond traditional gynecology.
- Fertility Treatment:Controlled ovarian stimulation protocols represent the dominant clinical use case, with HCG triggering final oocyte maturation before retrieval procedures. Standardized dosing regimens across fertility clinic networks in Japan, Spain, and the United States create predictable demand pull through specialized channels. Recombinant formulation preference is hardening as clinic chains consolidate procurement around reduced immunogenicity profiles.
- Hypogonadism Management:Endocrinology practices are adopting HCG monotherapy for male testosterone preservation, particularly in younger patients seeking fertility preservation alongside hormonal replacement. This application is climbing the fastest as prescriber relationships extend into urology and men's health settings outside traditional fertility medicine.
- Cryptorchidism Therapy:Pediatric endocrinology applications for undescended testicle management retain steady but limited volume against surgical intervention preferences.
- Weight Loss Programs:Off-label metabolic applications persist in wellness clinic settings despite regulatory scrutiny and absence of cardiovascular outcome validation.
Fertility Treatment anchors volume concentration. Hypogonadism Management is gaining share fastest through prescriber base expansion.
End User:
Customer-type margin stratification reflects cold-chain reliability requirements and procurement sophistication across institutional settings.
- Fertility Clinics:Specialized reproductive medicine units concentrate demand for high-potency recombinant formulations with validated stability documentation. Direct-to-clinic inventory arrangements are displacing wholesale distribution for high-volume networks in Texas, California, and New York, shifting working capital burdens upstream to manufacturers.
- Specialized Medical Practices:Endocrinology and urology settings are building HCG prescribing capacity for hypogonadism management, creating fragmented but expanding demand outside fertility medicine's concentrated channels.
- Oncology Centers:Limited diagnostic and therapeutic applications for tumor marker detection sustain niche procurement relationships with assay manufacturers.
- Diagnostic Laboratories:Quality control reference material demand supports small-volume contracts for assay calibration and proficiency testing programs.
Fertility Clinics hold installed capacity. Specialized Medical Practices is rotating up the share rankings through prescriber relationship expansion.
Delivery Mode:
Formulation innovation is compressing the operational gap between clinical administration and patient self-management capabilities.
- Injectable:Lyophilized vial presentations dominate fertility clinic workflows, requiring reconstitution before intramuscular or subcutaneous administration. Established supply chains and familiar handling protocols sustain preference despite patient burden.
- Subcutaneous:Pre-filled syringe and pen-injector formats are displacing intramuscular protocols in outpatient settings seeking reduced administration complexity and expanded self-injection training programs.
- Intramuscular:Traditional deep-tissue injection protocols retain residual use in hospital-based fertility units with established nursing workflows.
- Nasal Spray:Non-invasive absorption approaches remain developmental, constrained by glycoprotein stability challenges and bioavailability variability.
Injectable holds installed capacity. Subcutaneous is rotating up the share rankings through patient protocol simplification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for recombinant HCG track manufacturing concentration in Switzerland and Singapore against consumption gravity in the United States and Germany. Cold-chain logistics capabilities and FDA prequalification status determine cross-border shipment viability for fertility clinic supply contracts.
United States
Specialized fertility networks in Texas, California, and New York are consolidating procurement around direct-to-clinic inventory arrangements that shift working capital burdens upstream. FDA biologics licensing requirements for peptide hormone purity validation govern batch release protocols for domestic manufacturers. The Boston-Cambridge biotech corridor anchors recombinant production capacity serving North American clinic demand.
Germany
Fertility clinic chains in Munich, Hamburg, and Berlin are harmonizing stimulation regimens around recombinant HCG dosing schedules with standardized potency documentation. EMA Good Manufacturing Practice enforcement for sterility assurance and endotoxin testing extends quality control timelines for European market entry. The Rhine-Main pharmaceutical manufacturing cluster concentrates contract fill-finish capacity for lyophilized fertility medicines.
Japan
PMDA oversight of glycoprotein hormone specifications shapes import approval pathways for recombinant formulations used in controlled ovarian stimulation protocols. METI initiatives for reproductive medicine infrastructure expansion support clinic network growth in Tokyo, Osaka, and Nagoya. The Kanto region's fertility treatment centers are adopting subcutaneous pen-injector formats to reduce patient administration burden.
India
Metro hospital chains in Mumbai, Delhi, and Bangalore are building captive reproductive medicine units creating demand for WHO-prequalified HCG supply with validated cold-chain reliability. CDSCO import registration requirements for biologic fertility medicines govern procurement criteria for domestic distributors. The Hyderabad-Visakhapatnam pharmaceutical corridor is expanding recombinant manufacturing capacity for export to Southeast Asian and African markets.
Switzerland
Contract development and manufacturing organizations in Basel and Zurich are adopting single-use bioreactor technology for Chinese hamster ovary cell culture to reduce cross-contamination risk between glycoprotein campaigns. Swissmedic oversight of peptide hormone manufacturing standards ensures batch consistency for European and Middle Eastern export contracts. The country's precision medicine logistics infrastructure supports validated cold-chain distribution to fertility clinic networks across Continental Europe.
Human Chorionic Gonadotropin Market Competitive Environment
Concentration sits with diversified pharmaceutical conglomerates possessing biologics infrastructure and specialized gynecological therapeutic portfolios. The vendor base spans three tiers: multinational incumbents with recombinant manufacturing scale, mid-cap regional formulators with purification technology investments, and emerging market suppliers competing on urinary-derived product cost. Dominant competitive moves include strategic partnerships for cell line access and geographic expansion through WHO prequalification pursuit.
Among diversified pharmaceutical conglomerates, Merck & Co., Inc. and Organon occupy positions exemplifying biologics infrastructure leverage for fertility clinic supply reliability. Ferring Pharmaceuticals represents the specialized gynecological therapeutic archetype with concentrated investment in hypogonadism management channels. Indian formulators including Sun Pharmaceutical Industries Ltd. and Zydus Lifesciences Ltd. sit within the emerging market supplier tier competing on cost-accessible recombinant and urinary-derived product portfolios.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd |
| Organon |
| Merck & Co., Inc. |
| Zydus Lifesciences Ltd. |
| Sanzyme |
| Ferring Pharmaceuticals |
| Lupin Limited |
| Intas Pharmaceuticals Ltd. |
| Fresenius Kabi AG |
| Others |
Value Chain & Pricing Dynamics
FDA biologics licensing requirements for peptide hormone purity validation simultaneously gate supply qualification for fertility clinic networks and stratify price differentiation between recombinant and urinary-derived product tiers. This regulatory framework compresses batch release timelines for domestic manufacturers while elevating quality assurance costs that transmit downstream through specialized procurement channels.
Pricing Analysis
The customization-premium spread between patient-specific dosing protocols and standard fertility clinic regimens widens as recombinant HCG commands premium positioning against extraction-based alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects glycosylation pattern consistency, cold-chain reliability documentation, and WHO prequalification status. Cost compression in urine-derived tiers intensifies because Eastern European collection networks sustain lower-cost alternatives. Public health programs in emerging markets exhibit highest price sensitivity; specialized fertility networks in the United States and Germany demonstrate lowest sensitivity due to reimbursement framework insulation.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled biologics shipment from Swiss and Singaporean manufacturing hubs to United States fertility clinic networks hinge on validated cold-chain container availability through trans-Atlantic and trans-Pacific trade lanes. Supply concentrates in Switzerland, Singapore, and the Boston-Cambridge corridor, with contract manufacturing organizations drawing from Chinese hamster ovary cell line repositories and chromatographic purification resin suppliers. Single-source vulnerability concentrates in three contract manufacturing organization master cell bank repositories. Distribution runs through direct-to-clinic inventory arrangements that displace wholesale distribution for high-volume fertility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fertility medicine procurement is approaching a platform-economics inflection as direct-to-clinic inventory management systems interoperate with electronic health record platforms and automated dosing protocol libraries across consolidated clinic networks.
For Market Incumbents: Consolidate cell line access through strategic partnerships with contract manufacturing organizations possessing redundant master cell bank repositories, insulating against single-source vulnerability in Chinese hamster ovary production. Deepen backward integration into aseptic fill-finish capacity for lyophilized multi-dose presentations, capturing margin pools currently absorbed by third-party service providers. Glycosylation pattern analytical capability scarcity in contract testing laboratories represents a critical bottleneck requiring captive investment or exclusive service agreements. For New Entrants and Emerging Players: Service-layer gaps in hypogonadism management channel development present white-space opportunities as endocrinology practices build HCG prescribing capacity outside traditional gynecological settings. Underpenetrated prescriber relationships in urology and men's health clinics offer the most penetrable entry vector. A go-to-market angle anchored in self-injection training program partnerships with outpatient fertility settings reduces patient administration burden and differentiates against intramuscular protocol incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across single-use bioreactor manufacturing platforms, enabling mid-scale entrants to achieve comparable batch yields without fixed-asset intensity. Long-term viability over the projection horizon favors acquisition targets possessing demonstrated analytical biosimilarity capabilities and WHO prequalification status for emerging market access. The signal to watch is EMA Medical Device Regulation harmonization clarity for combination product reclassification timelines affecting pre-filled syringe development.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Single-use bioreactor adoption reduces cross-contamination risk between glycoprotein campaigns at Swiss CDMOs. |
| Regulatory Approval Pathway | EMA combination product reclassification extends development timelines for pen-injector platforms by twelve to eighteen months. |
| Long-term Supply Agreement | Direct-to-clinic consignment arrangements shift working capital burden upstream to manufacturers in Texas fertility networks. |
| Backward Integration | Captive fill-finish capacity for lyophilized presentations captures margin pools from third-party service providers. |
| Geographic Expansion | WHO prequalification pursuit unlocks procurement criteria for public health programs in Indian metro hospital chains. |
Study Parameters
The analysis maps recombinant manufacturing platforms, urinary-derived extraction networks, and synthetic peptide synthesis approaches, each validated through fertility clinic procurement directors, endocrinology practice administrators, and CDMO regulatory affairs specialists. Primary interviews with biologics manufacturing executives, gynecological therapeutic portfolio managers, and cold-chain logistics operators combined with secondary validation against FDA biologics licensing filings, EMA Good Manufacturing Practice inspection records, and WHO prequalification databases. Bottom-up demand modeling across clinic network procurement volumes triangulates with top-down pharmaceutical market sizing.
Consistency checks validated volume and value outputs against external benchmarks including fertility treatment cycle reporting databases, peptide hormone import-export trade statistics, and biologics manufacturing capacity disclosures. Segmentation dimensions modeled span product type purification technology, clinical application pathway, end-user procurement sophistication, and delivery mode formulation innovation. CAGRs were derived from normalized growth trajectory analysis across the analysis window, incorporating fertility clinic network expansion rates, reimbursement framework evolution, and regulatory approval timeline compression.
Underlying assumptions cover sustained recombinant formulation preference hardening in premium fertility networks, with deviation risk concentrated in urinary-derived price compression dynamics and EMA batch release timeline extensions. Forecasts reflect these documented assumptions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Interleukin 1 Beta (IL-1β) ELISA Kit Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Drug-Induced Immune Hemolytic Anemia Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
North America Vaccines Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Chemotherapy Drugs Market