
 Insulin Aspart Market | 2026-2036
Insulin Aspart Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Aspart Market Insights
Home care patients is bifurcating demand away from traditional clinic-administered doses across the insulin aspart landscape. Novo Nordisk leverages its manufacturing scale to dominate vial and pen supply chains in regulated markets. Sanofi anchors its position through geographic diversification across European and Asian distribution networks. Eli Lilly and Company differentiates via R&D intensity in next-generation delivery device compatibility.
Insulin aspart is a rapid-acting recombinant human insulin analog engineered with a single amino acid substitution at position B28, enabling faster subcutaneous absorption and mealtime glucose control than regular human insulin. The molecule achieves peak plasma concentration within 40 to 50 minutes, supporting its primary purpose in prandial glycemic management for diabetes mellitus. Pens and prefilled syringes command the largest volume pools among product formats, while pump reservoirs capture expanding share through integration with continuous glucose monitoring ecosystems. Type 1 diabetes applications sustain the highest per-patient consumption intensity, though Type 2 diabetes represents the broader addressable base as insulin intensification protocols advance.
FDA biosimilar pathways, EMA's biosimilar guidelines under the EU pharmaceutical framework, and WHO prequalification standards collectively shape product approval timelines, interchangeability designations, and market access conditions across jurisdictions. These frameworks determine manufacturing compliance burdens, clinical trial requirements, and pricing negotiations that directly influence stakeholder investment priorities. Manufacturers and procurement bodies must monitor evolving interchangeability rulings and biosimilar substitution policies to anticipate volume shifts and contract restructuring.
Market Dynamics
Self-administration protocols are redistributing insulin aspart volumes from clinical settings to home environments, compressing traditional hospital purchasing cycles while expanding direct-to-patient supply chains and reimbursement complexity.
Growth Catalysts
- CGM-Pump Integration:Continuous glucose monitoring ecosystems are expanding pump reservoir compatibility, pulling insulin aspart into automated dosing workflows.
- FDA Biosimilar Pathways:Accelerated approval frameworks are shortening time-to-market for follow-on biologics, intensifying price competition and expanding patient access.
- Type 2 Intensification:Escalating insulin therapy protocols in Type 2 diabetes management are broadening the addressable patient base beyond Type 1 populations.
Market Restraints
- API Supply Concentration:Recombinant insulin active pharmaceutical ingredient production clusters in Denmark and China, creating geopolitical and single-source vulnerability.
- Cold Chain Costs:Temperature-controlled distribution requirements impose 15-25% logistics premiums versus standard pharmaceuticals, squeezing margin in price-sensitive markets.
- Interchangeability Friction:FDA's evolving substitution rules and state-level pharmacy laws create prescribing uncertainty that slows biosimilar uptake.
Strategic Opportunities
- Latin America Expansion:Underpenetrated markets in Brazil and Mexico present volume growth as diabetes prevalence climbs and reimbursement frameworks mature.
- Wearable Delivery Convergence:Patch pump and smart pen technologies are creating compatibility partnerships that lock in formulation supply.
- IRA Price Negotiation Exemptions:Biologic insulin's delayed inclusion in Medicare price controls preserves pricing flexibility for originator manufacturers through 2028.
Industry Challenges
- Biologics Manufacturing Expertise Gap:Fermentation scale-up and purification optimization require specialized talent pools that compete with broader biopharma expansion.
- Legacy Device Integration:Existing pen needle and vial ecosystems create switching costs that slow next-generation delivery adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Aspart Market |
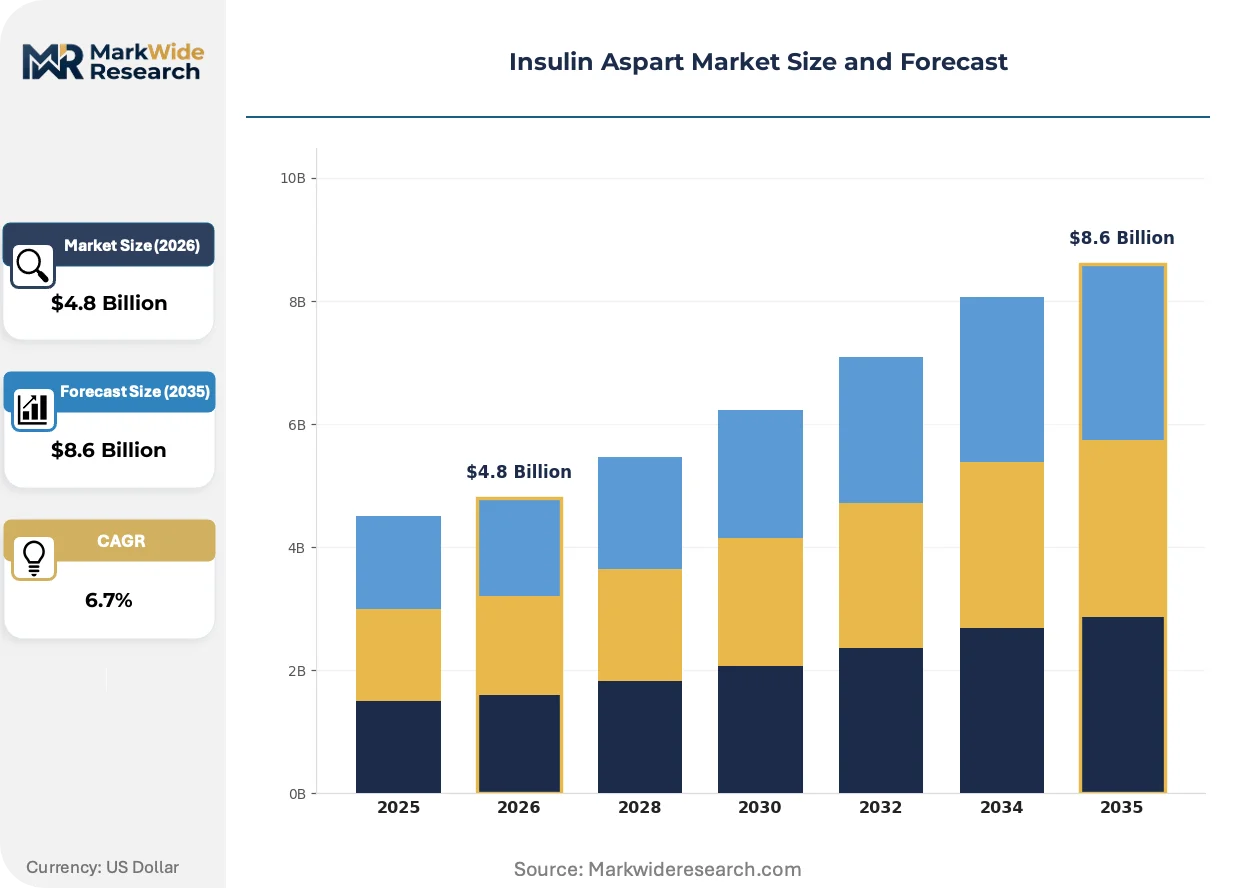
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Pens, Cartridges, Prefilled Syringes, Pump Reservoirs Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes, Insulin Pump Therapy End User: Endocrinologists, Diabetes Clinics, Pharmacies, Diagnostic Centers, Home Care Patients Delivery Mode: Subcutaneous Injection, Insulin Pumps, Continuous Glucose Monitoring, Inhalable Insulin, Needle-Free Devices |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, Biocon Biologics, Viatris, Gan & Lee Pharmaceuticals, Tonghua Dongbao Pharmaceutical, Wockhardt, Civica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Aspart Market Trends and Innovations
Device-formulation convergence is redefining competitive advantage in insulin aspart, with delivery technology compatibility now determining formulary placement as much as clinical efficacy profiles.
Smart pen systems with dose logging and Bluetooth connectivity are supplanting conventional disposable pens in premium reimbursement tiers. Endocrinology practices in Germany and the Netherlands are piloting these devices for medication adherence monitoring. The technology is compressing differentiation windows for manufacturers lacking digital health partnerships.
EMA's revised biosimilar immunogenicity guidelines are tightening clinical trial requirements for insulin analogs. Manufacturers must now demonstrate equivalent antibody formation profiles across larger patient cohorts. European markets are responding with extended development timelines and elevated R&D allocation toward immunogenicity endpoints.
Home care patients are consolidating purchase authority through specialized diabetes supply distributors. Traditional wholesale channels are losing volume to direct-ship models that bundle insulin with strips and lancets. The United States exhibits the most pronounced channel migration, where Medicare Part D restructuring accelerates mail-order preference.
Insulin Aspart Market Segmentation
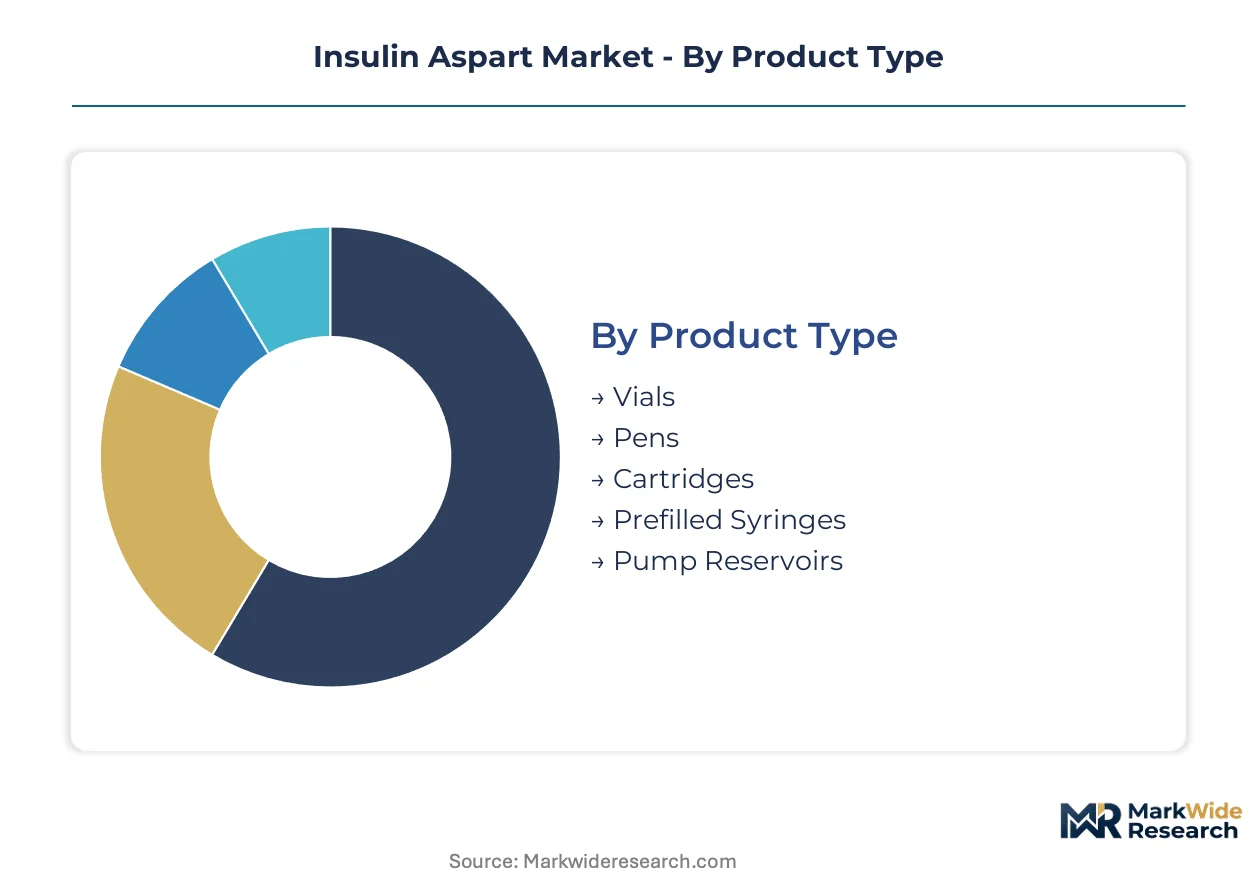
Insulin aspart segmentation reveals how delivery technology compatibility and care setting migration are fragmenting traditional purchasing patterns. Manufacturers now optimize formulation stability across device ecosystems rather than optimizing devices around a single formulation standard.
Product Type:
Substitution pressure from biosimilars and next-generation analogs weighs most heavily on legacy vial formats, while pen and pump-compatible presentations defend margin through device lock-in effects.
- Pens:Reusable and disposable pen systems dominate ambulatory prescribing through dose precision and portability. United States Medicare Part D reimbursement structures favor pen acquisition over vial-and-syringe combinations, consolidating demand around this format. Pen needle compatibility requirements create formulation-device pairing stickiness that slows therapeutic substitution.
- Pump Reservoirs:Specialized cartridges engineered for continuous subcutaneous infusion integrate with tubing sets and automated delivery algorithms. CGM-pump convergence in Germany and the Netherlands accelerates reservoir demand as closed-loop systems achieve regulatory clearance. Reservoir volume specifications vary by pump manufacturer, fragmenting supply contracts.
- Vials:Glass or polymer containers for manual syringe withdrawal retain cost-sensitive hospital procurement volumes.
- Cartridges:Pen-compatible 3 mL containers support reusable pen body systems prevalent in European markets.
- Prefilled Syringes:Single-use presentations address acute care and emergency department protocols requiring rapid insulin administration.
Pens anchor the volume base while pump reservoirs gain share at the steepest rate.
Application:
Cost tier stratification separates intensive prandial regimens from basal-bolus escalation protocols, with Type 1 diabetes commanding premium rapid- analog positioning and Type 2 diabetes facing downward price pressure from step-therapy requirements.
- Type 2 Diabetes:Progressive insulin intensification protocols expand the addressable population beyond traditional Type 1 boundaries. United States endocrinology practices increasingly initiate insulin aspart as second-line therapy after oral agent failure, though payer step-therapy rules delay access in Medicaid programs. Per-patient consumption intensity remains below Type 1 levels but aggregate volume exceeds Type 1 due to population prevalence.
- Type 1 Diabetes:Absolute insulin deficiency mandates prandial rapid-acting analog coverage for all carbohydrate intake. Pediatric and adolescent populations in Scandinavia and the United Kingdom achieve superior HbA1c outcomes with aspart-based pump therapy compared to multiple daily injection regimens. This segment sustains the highest per-patient annual consumption volumes.
- Gestational Diabetes:Pregnancy-specific glycemic targets require rapid-acting insulin for postprandial glucose excursions.
- Prediabetes:Early pharmacologic intervention protocols occasionally deploy insulin aspart for severe hyperglycemic states.
- Insulin Pump Therapy:Device-mediated delivery subset spanning Type 1 and insulin-requiring Type 2 populations.
Type 2 Diabetes generates the largest absolute volume while Insulin Pump Therapy climbs the fastest as device adoption accelerates.
End User:
Customer type migration from institutional purchasing to direct-to-patient distribution is restructuring procurement authority and rebate capture mechanisms across the value chain.
- Home Care Patients:Self-administering individuals now direct the majority of insulin aspart purchasing decisions through specialty pharmacy and mail-order channels. United States Medicare Part D restructuring and commercial insurance preferred pharmacy networks accelerate this shift. Patient copay assistance programs and manufacturer discount cards influence brand selection more than prescriber preference.
- Pharmacies:Retail and specialty dispensing locations intermediate between wholesale acquisition and patient possession. Independent pharmacies in France and Italy retain significant insulin distribution share despite chain consolidation elsewhere. Pharmacy benefit manager formulary placement determines which aspart presentations achieve preferred tier status.
- Endocrinologists:Specialist prescribers influence initial therapy selection and device pairing recommendations.
- Diabetes Clinics:Hospital-affiliated and independent specialty centers manage complex patient populations.
- Diagnostic Centers:Glucose tolerance testing and screening sites occasionally initiate acute insulin therapy.
Home Care Patients anchor the volume base while Pharmacies gain share at the steepest rate through specialty distribution consolidation.
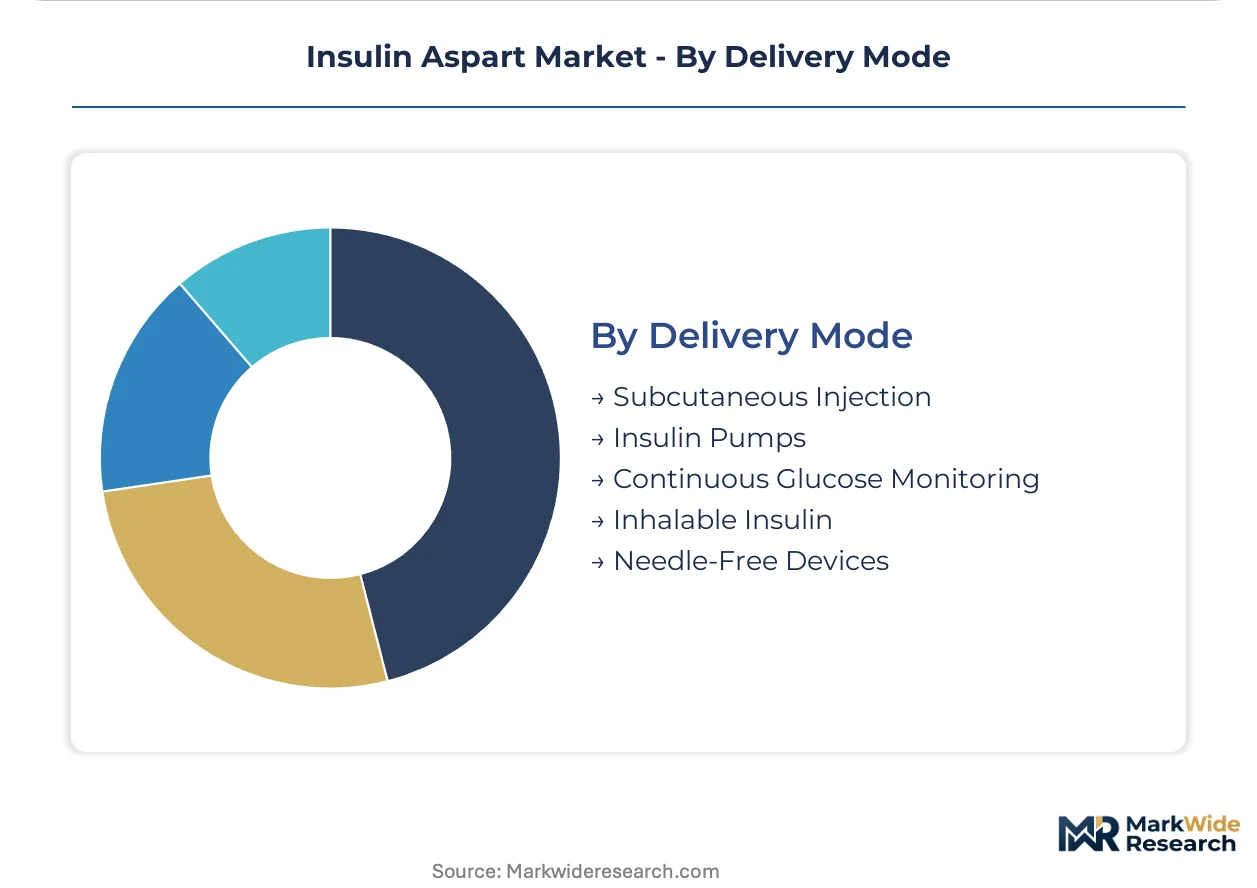
Delivery Mode:
Supply concentration in subcutaneous injection infrastructure faces displacement pressure from pump and CGM-integrated alternatives, though needle-based delivery retains cost and universality advantages.
- Subcutaneous Injection:Manual pen or syringe administration remains the universal fallback with lowest device acquisition cost. Emerging markets in Brazil and Mexico depend almost exclusively on this mode due to pump reimbursement limitations. Injection technique education requirements create adherence barriers that pump therapy addresses.
- Insulin Pumps:Electromechanical devices delivering continuous basal infusion with patient-triggered bolus capability. Tandem Diabetes Care and Medtronic pump ecosystems in the United States specify insulin aspart compatibility for automated insulin delivery algorithms. Pump therapy achieves superior time-in-range metrics in registry data from Sweden and the United States.
- Continuous Glucose Monitoring:Sensor-augmented pump systems and standalone CGM inform dosing decisions.
- Inhalable Insulin:Pulmonary delivery alternatives compete for prandial coverage in needle-averse populations.
- Needle-Free Devices:Jet injector and microneedle technologies address phobia and pain concerns.
Subcutaneous Injection anchors the volume base while Insulin Pumps gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish insulin aspart production flows primarily into United States and German distribution networks, with secondary corridors serving Japanese and Brazilian markets through regional formulation and packaging partnerships.
United States
Medicare Part D restructuring accelerates mail-order channel migration for home care patients. FDA biosimilar interchangeability rulings create prescribing uncertainty that slows substitution uptake. Endocrinology clinic density in Boston and Minneapolis supports premium rapid- analog positioning.
Germany
CGM-pump convergence in closed-loop systems drives reservoir demand from diabetes centers in Munich and Heidelberg. EMA revised immunogenicity guidelines extend biosimilar trial timelines. The country's statutory health insurance funds negotiate reference pricing that compresses originator margins.
Japan
PMDA accelerated review pathways for follow-on biologics intensify price competition in Osaka and Tokyo metropolitan markets. Aging demographics expand Type 2 insulin intensification protocols. Prefilled pen formats dominate reimbursement tiers over legacy vial presentations.
Brazil
ANVISA regulatory harmonization with WHO prequalification standards streamlines biosimilar entry for domestic manufacturers. São Paulo and Rio de Janeiro diabetes prevalence climbs fastest among Latin American peers. Subcutaneous injection remains the dominant delivery mode due to pump reimbursement limitations.
India
CDSCO biosimilar guidelines under the New Drugs and Clinical Trials Act shape domestic manufacturer approval timelines. Maharashtra and Gujarat clusters host recombinant insulin API fermentation capacity. Price-controlled essential medicines lists cap rapid-acting analog reimbursement in public procurement.
Insulin Aspart Market Competitive Landscape
Player mix skews toward vertically integrated biologics specialists with captive fermentation capacity and multi-format device portfolios. Market structure concentrates around three originator manufacturers controlling pen and pump-compatible presentation supply chains. Strategic archetypes include: full-stack insulin analog developers with device ecosystems; regional biosimilar specialists leveraging cost-optimized manufacturing; and hybrid generic-biologic players diversifying from small-molecule portfolios. Dominant competitive moves encompass geographic licensing partnerships for emerging market access and formulation-device compatibility certifications for pump ecosystem integration.
Within the originator tier, Novo Nordisk and Sanofi occupy positions defined by manufacturing scale and European distribution network density. Eli Lilly and Company exemplifies R&D-intensive positioning through next-generation delivery device partnerships. Among emerging biosimilar specialists, Biocon Biologics and Viatris represent cost-optimized manufacturing archetypes targeting price-sensitive markets with vial and pen presentations. These five entities collectively anchor competitive dynamics across regulated and emerging market access corridors.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| Biocon Biologics |
| Viatris |
| Gan & Lee Pharmaceuticals |
| Tonghua Dongbao Pharmaceutical |
| Wockhardt |
| Civica |
| Others |
Pricing and Supply Chain Analysis
Fermentation capacity utilization above 85% in Danish manufacturing clusters anchors cost structures across the insulin aspart landscape, concentrating supply-side leverage among originators with captive biologics infrastructure while compressing price floors for vial-format competitors lacking equivalent scale.
Pricing Analysis
Device-generation pricing gaps separate legacy vial-syringe combinations from smart pen ecosystems and CGM-integrated pump reservoirs. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery technology compatibility and reimbursement tier placement. Cost compression in standard-tier vials is intensifying because FDA biosimilar entry accelerates interchangeability pressure. Home care patients exhibit highest price sensitivity through copay-driven brand switching, while hospital procurement committees leverage volume aggregation for standard-tier discounts.
Supply Chain Analysis
Inventory lead times for recombinant insulin API stretch 12-16 weeks from Danish and Chinese fermentation facilities to formulation and fill-finish sites. Active pharmaceutical ingredient production draws from Denmark, China, and India, with downstream packaging concentrated in United States and German distribution hubs. Cold chain logistics rest on temperature-controlled transport and specialized warehousing infrastructure. Single-source vulnerability in Danish API fermentation creates supply risk exposure. Distribution runs through specialty pharmacy and direct-to-patient mail-order channels displacing traditional wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device-formulation convergence fragments competitive positioning across delivery technology ecosystems, creating niche entry points for specialists mastering pump compatibility certification or smart pen integration partnerships.
For Market Incumbents: Consolidate manufacturing scale advantages through backward integration into recombinant insulin API fermentation, locking in supply security against Chinese capacity expansion. Deepen pump ecosystem partnerships with Tandem Diabetes Care and Medtronic to defend reservoir market share from biosimilar vial substitution. Prioritize FDA interchangeability litigation to delay automatic substitution rules. For New Entrants and Emerging Players: FDA biosimilar fast-track pathways offer accelerated entry for vial and pen presentations targeting Medicaid step-therapy populations. Brazil and Mexico present underpenetrated volume opportunity where pump reimbursement limitations preserve injection-format dominance. Pursue ANVISA regulatory harmonization partnerships with domestic Brazilian distributors to bypass originator channel control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors device-formulation convergence specialists with captive CGM integration capabilities and regulatory approval momentum. Long-term viability hinges on Medicare price negotiation exemption timelines and biosimilar substitution elasticity. Watch FDA interchangeability rulings as inflection signal for originator pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| CGM-Pump Compatibility Certification | Device ecosystem partnerships with Tandem and Medtronic lock in reservoir demand. |
| FDA Biosimilar Interchangeability Pathway | Accelerated review timelines compress development-to-revenue cycles for follow-on entrants. |
| Specialty Pharmacy Distribution Partnership | Direct-to-patient channels bypass wholesale margin capture and accelerate rebate optimization. |
| Smart Pen Digital Health Integration | Bluetooth-enabled dose logging creates adherence data assets for payer contracting leverage. |
| Latin America Regulatory Harmonization | ANVISA-WHO alignment streamlines biosimilar entry in Brazilian and Mexican diabetes markets. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration throughout the study period. Primary interviews with diabetes supply chain stakeholders combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient-volume modeling and top-down manufacturer revenue triangulation anchored value estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions spanned product type, application, end user, delivery mode, and regional regulatory cluster. CAGRs derived from patient population growth, therapy intensification rates, and device adoption curves. Forecast inputs incorporated insulin pump penetration trajectories and biosimilar substitution elasticity assumptions.
Decision-makers should treat outputs as directional under stable FDA interchangeability rulings and intact Medicare price negotiation exemptions; material deviation in either would warrant model refresh. Forecasts reflect base-case assumptions around cold chain infrastructure investment and API supply security. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Recombinant Erythropoietin Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market