
 Melting Point Apparatus Market | 2026-2036
Melting Point Apparatus Market Size, Share, and Industry Trends Forecast 2026-2036
Melting Point Apparatus Market Outlook
Leasing and instrument-as-a-service models are reshaping capital deployment in analytical instrumentation, allowing mid-sized laboratories to access automated systems without upfront purchase. METTLER TOLEDO leverages its global service infrastructure to anchor recurring revenue streams alongside hardware sales. BUCHI specializes in compact, integrated thermal analysis platforms that dominate European pharmaceutical quality labs. Thermo Fisher Scientific extends its channel control through bundled compliance software and validation support packages.
A melting point apparatus measures the temperature at which a solid substance transitions to liquid phase, typically employing capillary tubes heated in a controlled oil bath or metal block with precision thermometry to ±0.1°C accuracy. The instrument serves as a fundamental identity and purity verification tool in pharmaceutical compendial testing, organic synthesis validation, and polymer characterization workflows. Automatic systems lead the product type landscape due to throughput requirements in high-volume quality control environments, while digital platforms with integrated data integrity features represent the fastest-expanding segment driven by ALCOA+ compliance mandates. Optical measurement technology occupies mature, stable demand in academic settings, whereas thermal analysis methods concentrate margin pools in pharmaceutical contract manufacturing organizations.
The United States Pharmacopeia (USP) and European Pharmacopoeia (EP) enforce instrument qualification protocols that shape product design and validation documentation requirements for manufacturers seeking market access. FDA 21 CFR Part 11 and EMA data integrity guidelines force end users toward digital systems with audit trail capabilities, directly filtering demand away from manual apparatus. China's NMPA alignment with ICH Q7 guidelines for active pharmaceutical ingredient manufacturing is accelerating replacement cycles among domestic producers. Stakeholders must monitor evolving pharmacopeial harmonization efforts and qualification burden shifts to determine whether to compete on compliance integration or modular affordability.
Market Dynamics
Pharmacopeial data integrity mandates are compressing replacement cycles for manual melting point apparatus across quality control laboratories, forcing capital allocation toward automated platforms with embedded audit trail architectures.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signature requirements compel pharmaceutical manufacturers to retire analog thermometry systems in favor of digital melting point platforms with automated data capture.
- Polymer characterization laboratories:High-throughput screening demands in materials science departments accelerate procurement of multi-sample automatic systems capable of parallel thermal analysis.
- Contract manufacturing organizations:Volume-based testing contracts in India and China drive consolidation toward centralized automated platforms replacing distributed manual workstations.
Market Restraints
- Precious metal thermocouple costs:Platinum-rhodium sensor price volatility elevates bill-of-materials exposure for high-accuracy apparatus manufacturers sourcing from South African refiners.
- Validation documentation burden:EMA qualification protocol requirements extend sales-to-revenue recognition timelines by 4-8 months for EU-bound instrument shipments.
- Differential scanning calorimetry substitution:Thermal analysis laboratories in polymer and pharmaceutical sectors increasingly specify DSC for purity verification, compressing addressable demand for standalone melting point systems.
Strategic Opportunities
- Leasing and instrument-as-a-service models:Mid-sized Brazilian and Mexican quality control laboratories seek subscription-based access to automated systems without capital expenditure approval cycles.
- AI-assisted melting point prediction:Integration of machine learning algorithms with optical detection systems enables real-time polymorph identification during heating protocols.
- China NMPA GMP alignment:Domestic active pharmaceutical ingredient producers face 2025 compliance deadlines requiring instrument qualification documentation that favors validated digital platforms.
Industry Challenges
- Thermal metrology expertise scarcity:Quality control departments struggle to recruit technicians proficient in ASTM E794 and pharmacopeial method harmonization for multi-standard environments.
- Legacy LIMS integration complexity:Digital melting point systems require custom middleware development to interface with established laboratory information management systems in mature pharmaceutical facilities.
- Calibration certificate turnaround:ISO 17025-accredited service providers face backlog pressures extending preventive maintenance intervals beyond manufacturer-recommended schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melting Point Apparatus Market |
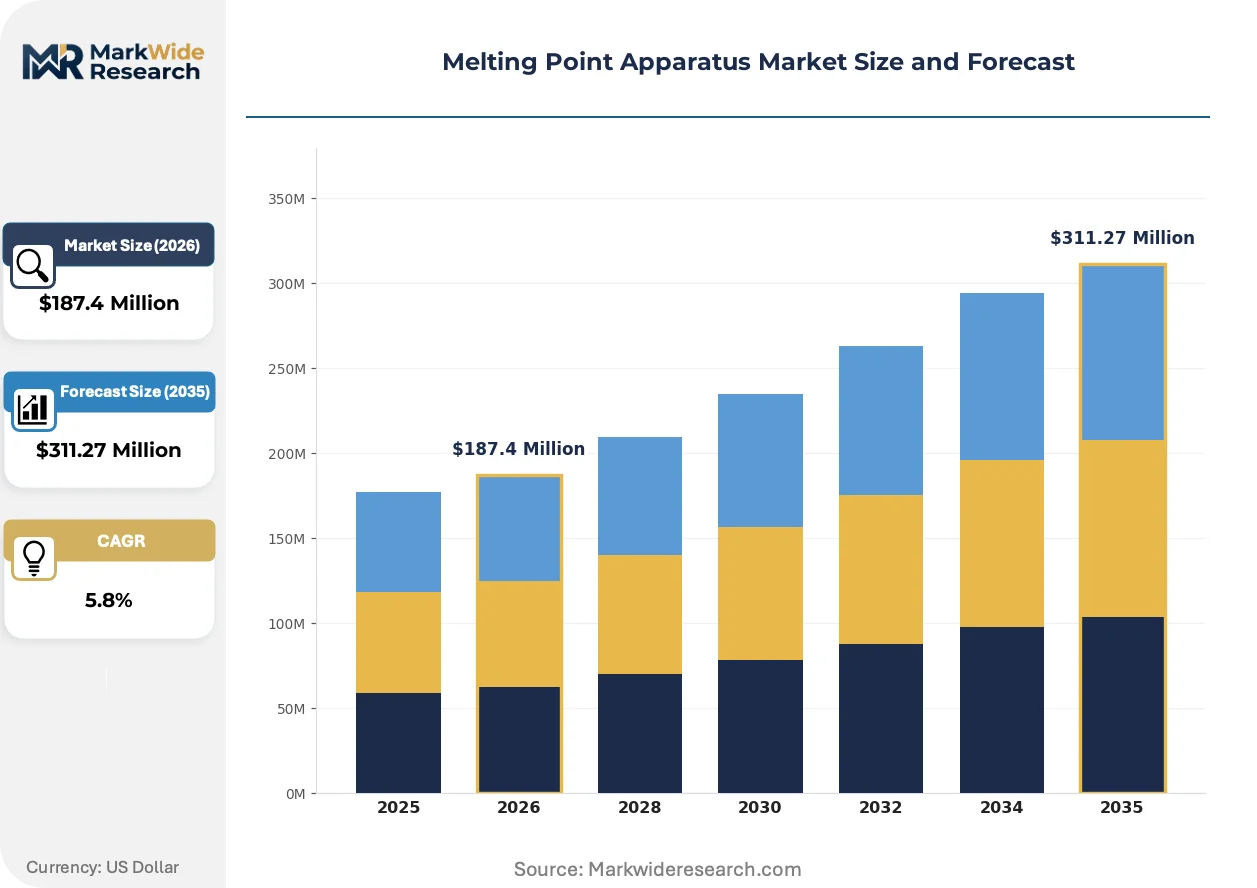
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillary Method, Automatic, Manual, Digital Technology: Thermal Analysis, Optical Measurement, Infrared Detection, Resistance Measurement End User: Chemical Laboratories, Academic Institutions, Pharmaceutical Companies, Quality Control Application: Research, Quality Assurance, Educational Purposes, Material Evaluation |
| Companies Covered | METTLER TOLEDO, BUCHI, Stanford Research Systems, Kruss, Thermo Fisher Scientific, Shanghai Benang Instruments, Jinan Hanon Instrument, JiaHang Instruments, Shanghai Instrument Physical Optics Instrument, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melting Point Apparatus Market Strategic Shifts
Video-based optical detection systems are displacing traditional visual observation methods while cloud-connected thermal analysis platforms enable remote method validation. Regulatory data integrity architectures now dictate hardware design priorities ahead of raw measurement precision.
Video-microscopy melting point systems equipped with automated meniscus detection algorithms are rendering obsolete manual visual observation protocols that depend on operator judgment. Pharmaceutical quality control departments in Germany and Switzerland have accelerated adoption since 2023. The technology compresses inter-operator variability from ±0.3°C to ±0.05°C while eliminating transcription errors.
EMA data integrity guidelines and FDA 21 CFR Part 11 enforcement are mandating audit trail functionality as a non-negotiable specification for new instrument procurement. Manufacturers must embed tamper-evident electronic records and user access controls at the firmware level. Small and mid-sized contract testing laboratories in Eastern Europe face disproportionate compliance costs relative to their revenue base.
Service unbundling from hardware sales is restructuring vendor-customer relationships in analytical instrumentation. Pharmaceutical buyers increasingly specify validation support and qualification documentation as separately contracted deliverables rather than bundled inclusions. This pattern concentrates margin capture with manufacturers possessing dedicated field service organizations in the United States and Western Europe.
Melting Point Apparatus Market Segmentation
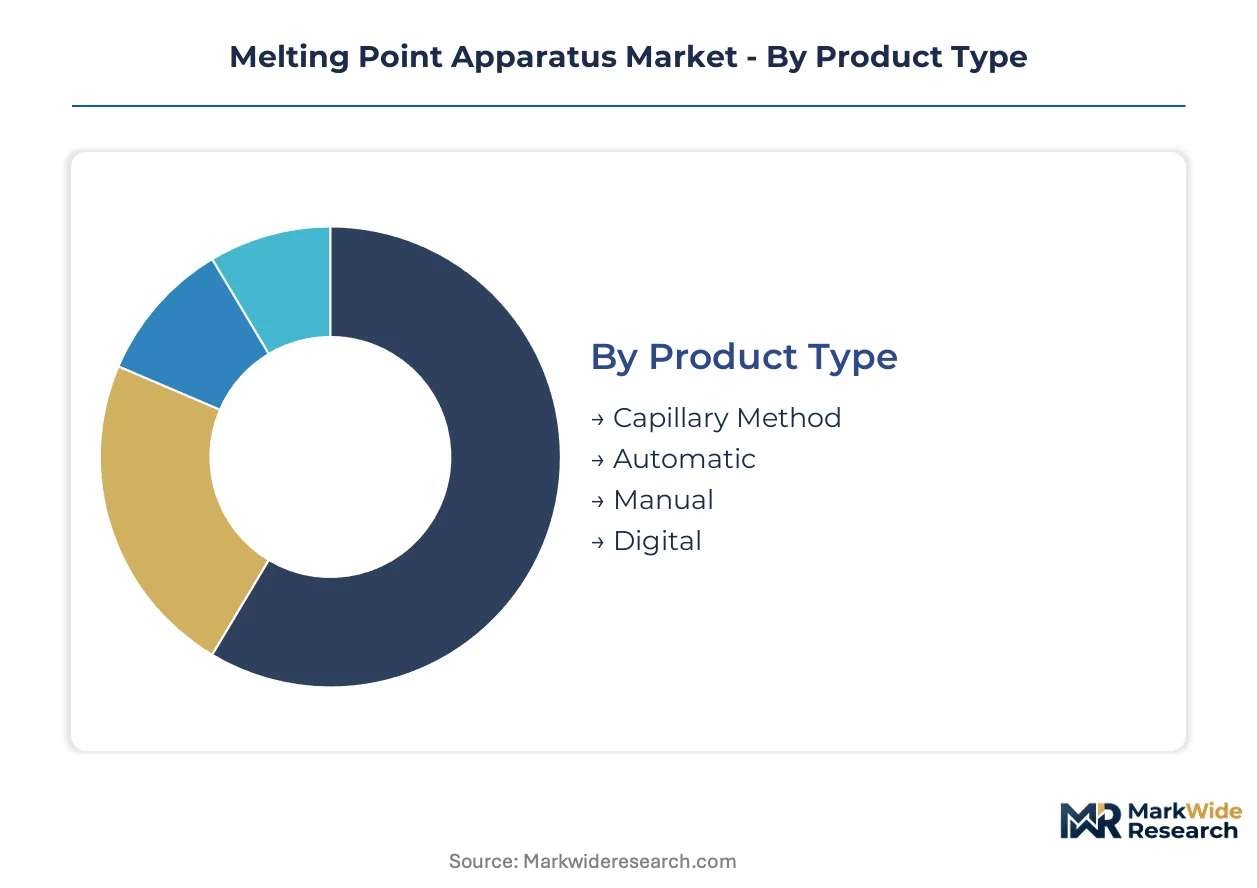
Segmentation in the melting point apparatus market reveals distinct service intensity profiles across product tiers. After-sales validation support and qualification documentation generate recurring revenue streams that often exceed hardware margins over the instrument lifecycle.
Product Type:
After-sales service intensity varies sharply across product tiers, with automated platforms demanding multi-year calibration contracts while manual systems require minimal vendor involvement.
- Automatic:Multi-sample platforms with programmable heating ramps and integrated cooling systems dominate pharmaceutical quality control workflows. High-throughput contract manufacturing organizations in India and China specify these systems to meet volume-based testing contracts while minimizing operator intervention.
- Digital:Microprocessor-controlled units with embedded audit trail functionality and USB data export capabilities are displacing analog thermometry in FDA-regulated environments. EMA data integrity guidelines and 21 CFR Part 11 enforcement compel pharmaceutical manufacturers toward these platforms despite 40-60% price premiums over manual alternatives.
- Capillary Method:Traditional tube-based heating block systems with visual or automated meniscus detection serve routine identity testing in compendial laboratories.
- Manual:Basic oil bath or metal block apparatus with operator-dependent observation persists in academic teaching laboratories and resource-constrained settings.
Automatic systems hold the largest share; momentum sits with Digital platforms.
Technology:
Technology selection determines capital expenditure thresholds and determines whether laboratories can satisfy pharmacopeial method harmonization requirements across multiple jurisdictions.
- Thermal Analysis:Differential scanning calorimetry-adjacent methods measuring heat flow during phase transitions deliver precision to ±0.01°C for polymorph characterization. Polymer laboratories and pharmaceutical development groups specify these systems despite higher capital outlay.
- Optical Measurement:Video-microscopy systems with automated image processing algorithms eliminate operator variability in meniscus detection. German and Swiss pharmaceutical quality departments have accelerated procurement since 2023 to compress inter-operator deviation.
- Infrared Detection:Non-contact temperature sensing through IR thermometry enables specialized applications where sample contamination risks preclude direct probe contact.
- Resistance Measurement:Platinum resistance thermometer-based systems provide traceable metrology for ISO 17025-accredited calibration laboratories.
Thermal Analysis commands premium pricing; Optical Measurement is climbing the fastest.
End User:
End-user procurement authority shapes whether sales cycles emphasize technical specifications or total cost of ownership calculations.
- Pharmaceutical Companies:Corporate quality departments with dedicated metrology groups specify validated platforms with IQ/OQ/PQ documentation packages. FDA and EMA inspection readiness requirements mandate digital audit trail capabilities for all new instrument acquisitions.
- Quality Control:Independent contract testing laboratories face disproportionate compliance documentation burdens relative to revenue base, driving preference for vendors with embedded validation support.
- Chemical Laboratories:Industrial R&D and specialty chemical producers balance measurement precision against throughput requirements for synthesis validation workflows.
- Academic Institutions:Teaching laboratories prioritize capital cost minimization and durability over advanced data integrity features, sustaining demand for manual and entry-level digital systems.
Pharmaceutical Companies hold the largest share; Quality Control faces the steepest compliance cost pressures.
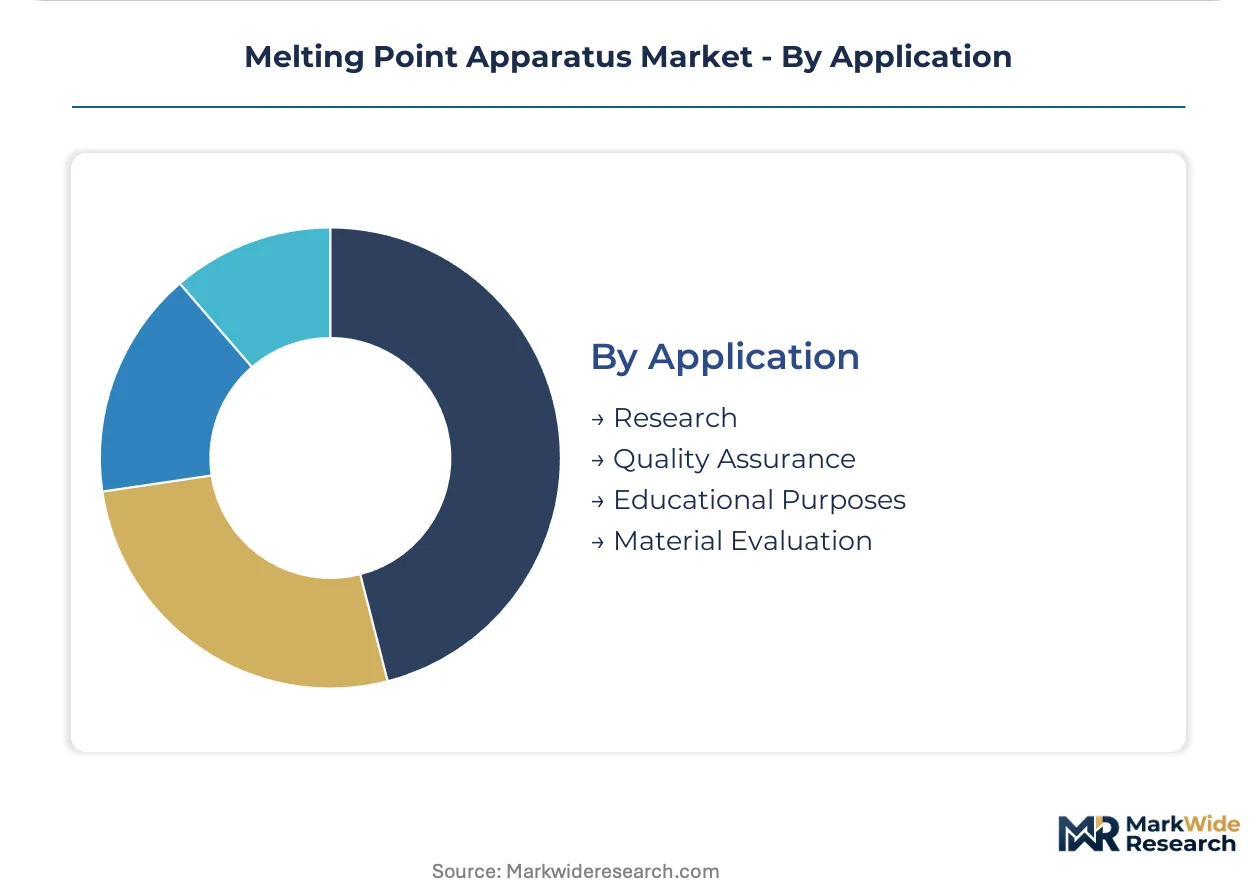
Application:
Application context determines whether laboratories prioritize measurement throughput, pedagogical clarity, or regulatory defensibility.
- Quality Assurance:Compendial identity and purity verification against pharmacopeial standards requires documented method validation and instrument qualification. NMPA alignment with ICH Q7 guidelines for active pharmaceutical ingredient manufacturing accelerates replacement cycles among domestic Chinese producers.
- Research:Polymorph screening and novel compound characterization demands flexibility in heating protocols and detection methods.
- Material Evaluation:Polymer melting range determination for incoming raw material certification supports manufacturing process control.
- Educational Purposes:Undergraduate chemistry instruction emphasizes fundamental phase transition concepts over measurement precision or regulatory compliance.
Quality Assurance holds the largest share; Research applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical quality control laboratories in Germany, the United States, and China concentrate procurement authority for automated melting point systems, while academic and industrial R&D facilities in Switzerland and India sustain secondary demand tiers.
United States
FDA-regulated pharmaceutical manufacturers drive replacement cycles for manual apparatus with digital platforms featuring embedded audit trails. 21 CFR Part 11 enforcement compels electronic records and signature capabilities in all new instrument acquisitions. Boston-Cambridge biotech clusters and New Jersey pharmaceutical corridors anchor demand for validated systems with IQ/OQ/PQ documentation packages.
Germany
European Pharmacopoeia compliance requirements shape instrument specifications across industrial quality control departments. EMA data integrity guidelines mandate tamper-evident electronic records and user access controls at firmware level. Rhine-Main and Rhine-Ruhr industrial regions concentrate procurement from vendors with dedicated German field service organizations.
China
Domestic active pharmaceutical ingredient producers face NMPA GMP alignment deadlines requiring instrument qualification documentation. ICH Q7 guideline implementation accelerates replacement cycles among domestic manufacturers. Yangtze River Delta pharmaceutical manufacturing bases and Pearl River Delta contract research organizations drive volume demand for multi-sample automatic platforms.
Switzerland
Swissmedic oversight of pharmaceutical manufacturing elevates specifications for thermal analysis precision in polymorph characterization workflows. Basel-based multinational headquarters and Zurich analytical instrument clusters sustain premium-tier demand for optical measurement systems with automated meniscus detection algorithms.
India
Contract manufacturing organizations in Hyderabad and Ahmedabad consolidate testing capacity toward centralized automated platforms. CDSCO alignment with international pharmacopeial standards filters procurement toward validated digital systems. Mumbai-Pune pharmaceutical corridors sustain demand for mid-tier equipment balancing compliance documentation against capital constraints.
Melting Point Apparatus Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: diversified analytical instrumentation conglomerates with global service infrastructure, compact thermal analysis specialists with regional manufacturing depth, and precision measurement component suppliers with modular platform strategies. Dominant competitive moves include service unbundling from hardware sales and geographic expansion through validation support partnerships.
Within the diversified instrumentation tier, METTLER TOLEDO and Thermo Fisher Scientific anchor positions through bundled compliance software and global qualification documentation networks. BUCHI occupies a specialist position among European thermal analysis platform providers. Among precision measurement component suppliers, Stanford Research Systems and Kruss exemplify technology-focused positioning. Chinese fabricators including Shanghai Benang Instruments, Jinan Hanon Instrument, and JiaHang Instruments represent regional manufacturing depth serving domestic and emerging market price tiers.
| Leading Market Players |
|---|
| METTLER TOLEDO |
| BUCHI |
| Stanford Research Systems |
| Kruss |
| Thermo Fisher Scientific |
| Shanghai Benang Instruments |
| Jinan Hanon Instrument |
| JiaHang Instruments |
| Shanghai Instrument Physical Optics Instrument |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors transmit platinum-rhodium thermocouple cost volatility from South African refiners directly into apparatus bill-of-materials, concentrating pricing power with vendors who anchor long-term supply contracts while forcing mid-tier buyers toward extended payment structures.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange precious metal pricing dominate high-accuracy apparatus procurement, with platinum-rhodium sensor costs passed through via quarterly adjustment clauses. Price differentiation rests on IQ/OQ/PQ documentation bundling and ISO 17025 calibration certification tiers. Pricing pressure intensifies in manual apparatus segments as EMA qualification requirements compress demand toward validated digital platforms. Academic and teaching laboratories exhibit highest price sensitivity, while pharmaceutical quality departments prioritize compliance documentation over capital outlay minimization.
Supply Chain Analysis
Supplier-financing facilities extending payment terms to 90-120 days have become standard for mid-sized quality control laboratories in Brazil and Mexico seeking automated platform access. Manufacturing concentrates in Germany, Switzerland, and China, with platinum-rhodium thermocouples, precision optical sensors, and microprocessor control modules as critical component dependencies. Single-source vulnerability in South African platinum group metal refining exposes apparatus manufacturers to commodity price spikes. Distribution runs through authorized dealer networks with embedded field service capabilities in pharmaceutical manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The melting point apparatus market sits in early-cycle expansion as pharmacopeial data integrity mandates force replacement waves across quality control laboratories. NMPA GMP alignment deadlines in China and CDSCO standardization in India accelerate penetration among domestic API producers.
For Market Incumbents: Harden firmware-level audit trail architectures against differential scanning calorimetry substitution threats in polymer characterization workflows. Deepen backward integration into platinum-rhodium sensor supply through long-term offtake agreements with South African refiners. Expand validation support headcount in Rhine-Main and Yangtze River Delta pharmaceutical corridors to capture service-unbundling margin pools.
For New Entrants and Emerging Players: Mexican and Brazilian quality control laboratories represent underpenetrated white-space where subscription-based instrument-as-a-service models bypass capital expenditure approval barriers. Target mid-tier contract manufacturing organizations in Ahmedabad and Hyderabad seeking compliance documentation without premium-tier pricing. Lead with AI-assisted polymorph identification features to differentiate against established optical detection platforms.
For Investors and Strategic Acquirers: Compact thermal analysis specialists with embedded European pharmaceutical quality lab relationships command scarcity premia in consolidation scenarios. Field service infrastructure density serves as the primary signal for platform acquisition attractiveness. Long-term viability hinges on qualification documentation recurring revenue streams exceeding hardware depreciation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Validation Documentation Unbundling | Separates IQ/OQ/PQ packages from hardware sales to capture recurring service revenue from FDA-regulated pharmaceutical manufacturers. |
| AI-Assisted Polymorph Detection | Integrates machine learning with optical systems to compress inter-operator variability in Swissmedic-regulated polymorph characterization workflows. |
| Instrument-as-a-Service Expansion | Enables Brazilian and Mexican laboratories to access automated platforms without capital expenditure approval cycles. |
| Platinum-Rhodium Supply Hedging | Mitigates South African refinery concentration risk through long-term offtake contracts indexed to LME pricing. |
| Cloud-Connected Audit Trail Architecture | Embeds tamper-evident electronic records at firmware level to satisfy FDA 21 CFR Part 11 and EMA data integrity mandates. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with quality control directors, pharmaceutical regulatory affairs leads, analytical instrument procurement managers, and thermal analysis laboratory heads; and secondary validation against FDA 483 inspection observations, EMA qualification guidance documents, USP and EP pharmacopeial method updates, and customs trade data for platinum-rhodium thermocouple imports. Bottom-up instrument shipment tracking triangulated against top-down pharmaceutical quality control capital expenditure surveys.
Forecast inputs incorporated product type segmentation across automatic, digital, capillary, and manual apparatus; technology tiers spanning thermal analysis, optical measurement, infrared detection, and resistance measurement; and end-user categories including pharmaceutical companies, contract quality control laboratories, chemical R&D facilities, and academic institutions. CAGRs were derived from replacement cycle compression analysis tied to pharmacopeial harmonization timelines and instrument qualification burden shifts.
Practitioners should monitor NMPA enforcement consistency, platinum-rhodium price volatility, and DSC substitution rates in polymer laboratories for early signals requiring forecast revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Viscometer Market
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Europe Process Analytics Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Micro Carbon Residue Tester Market
Testing Equipment
Rheometer Market
Testing Equipment
Elemental Analysis Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
United States Material Testing Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Global Oxidative Stress Assay Market