
 Americas Testing, Inspection and Certification (TIC) Market | 2026-2036
Americas Testing, Inspection and Certification (TIC) Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Testing, Inspection and Certification (TIC) Market Insights
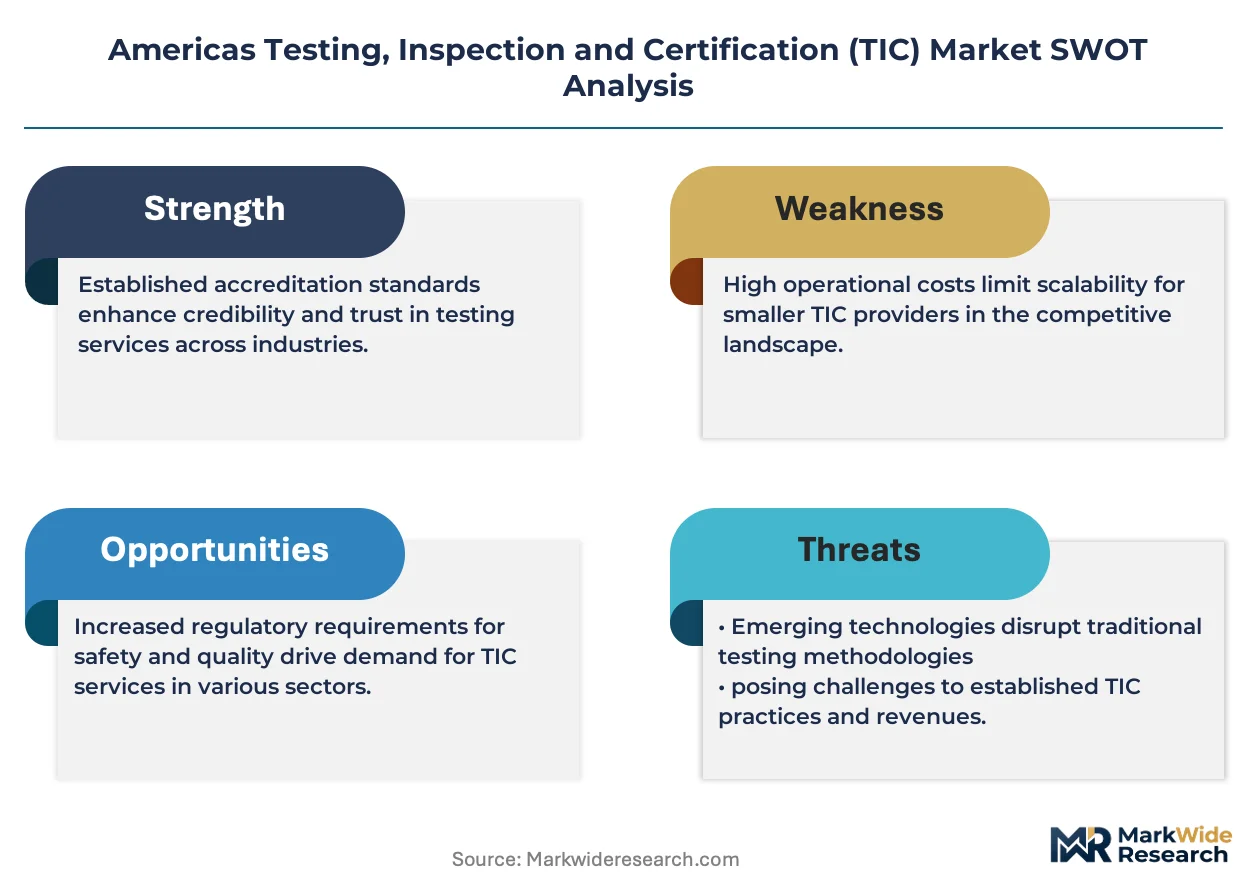
Recurring audit and compliance subscription revenue is reconfiguring how TIC providers capture lifetime customer value across industrial accounts. SGS SA leverages its agricultural and minerals testing heritage to dominate Latin American commodity export corridors. Bureau Veritas anchors its Americas position through marine and offshore inspection networks tied to Gulf Coast energy infrastructure. Intertek Group Plc differentiates via consumer goods assurance programs that control retailer shelf-access decisions across North American big-box channels.
Testing, Inspection and Certification encompasses the independent verification of product conformity, system integrity, and process safety against codified technical standards through sampling, measurement, witness examination, and formal attestation. Laboratories employ spectrometry, tensile testing, and environmental simulation to generate traceable evidence of compliance for regulatory submission and commercial risk transfer. The service type dimension shows testing commanding the largest revenue pool due to capital-intensive equipment requirements, while certification extracts premium margins from recurring surveillance audits and mark licensing. Among end users, automotive and healthcare segments are expanding fastest as battery electric vehicle platforms and FDA quality system regulations multiply validation touchpoints across supplier tiers.
The US FDA, EPA, and OSHA frameworks mandate third-party validation for medical device premarket submissions, environmental emissions verification, and workplace hazard assessments, creating structural demand for accredited TIC services. Brazil's ANVISA and Mexico's national standards body enforce pharmaceutical and food import protocols that require local laboratory partnerships for market entry. Stakeholders must monitor how AI-driven predictive inspection tools alter labor models and accreditation criteria across federal and state regulatory jurisdictions.
Market Dynamics
The US Inflation Reduction Act's domestic content mandates are rerouting certification workflows toward North American laboratories, forcing TIC providers to rebuild geographic service footprints around federal incentive eligibility rather than cost optimization alone.
Growth Catalysts
- Battery Electric Vehicle Supply Chains:EV battery safety validation protocols are multiplying testing touchpoints across automotive supplier tiers. NHTSA and EPA emissions frameworks mandate expanded third-party verification for cell chemistry stability and thermal runaway containment.
- FDA Quality System Regulations:Medical device premarket submission requirements are structurally expanding TIC demand as Class II and III device categories face intensified post-market surveillance obligations.
- Mexico Nearshoring Momentum:Manufacturing relocation from Asia is generating new laboratory capacity needs for electronics and automotive component certification serving US market access.
Market Restraints
- Accreditation Cost Concentration:ISO 17025 laboratory accreditation requires sustained capital deployment in metrology equipment and auditor training, creating barriers for mid-scale entrants.
- Skilled Technician Scarcity:Spectrometry and environmental simulation expertise concentrates in established metropolitan laboratory clusters, limiting expansion into secondary markets.
- Regulatory Fragmentation:Divergent state-level environmental testing protocols across US jurisdictions force redundant sampling workflows and compliance documentation.
Strategic Opportunities
- Brazil Agricultural Export Corridors:ANVISA and international phytosanitary protocols are driving demand for local pesticide residue and GMO verification laboratories serving European and Asian buyers.
- AI-Assisted Inspection Tools:Machine learning predictive maintenance algorithms are converging with drone-based infrastructure assessment to compress field inspection cycle times for energy and utility clients.
- Subscription Audit Models:Recurring surveillance certification contracts are replacing transactional project revenue, enabling lifetime value capture across industrial manufacturing accounts.
Industry Challenges
- Legacy System Integration:Laboratory information management systems from prior decades resist seamless data exchange with modern cloud-based client portals, delaying real-time compliance reporting.
- Certification Timeline Compression:FDA 510(k) review queue backlogs and parallel international submission requirements are stretching TIC provider project management capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Testing, Inspection and Certification (TIC) Market |
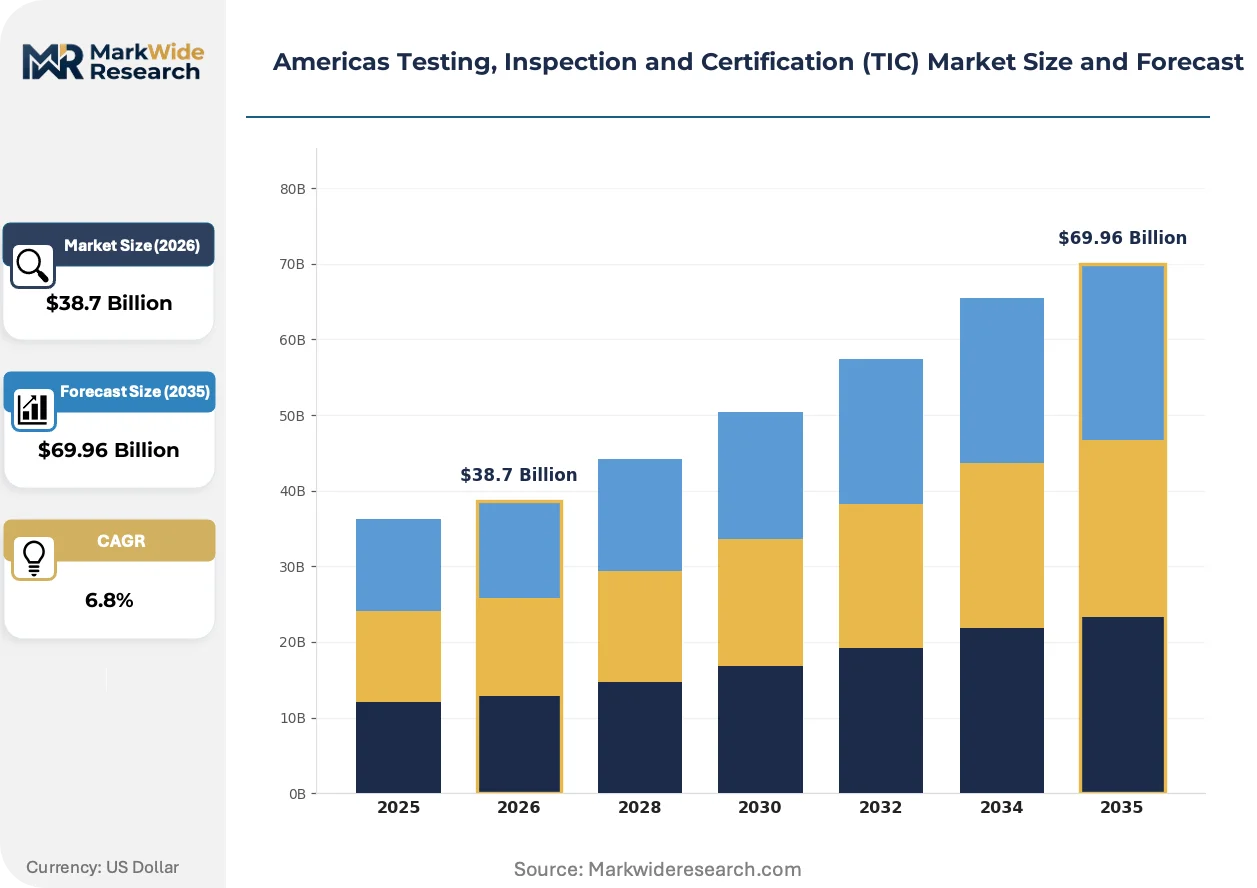
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Testing, Inspection, Certification, Consulting End User: Manufacturing, Healthcare, Automotive, Construction Technology: IoT, AI, Big Data, Automation Industry Vertical: Food & Beverage, Electronics, Chemicals, Textiles |
| Companies Covered | SGS SA, Intertek Group Plc, Bureau Veritas, UL LLC, TÜV SÜD, TÜV Rheinland, Eurofins Scientific, Element Materials Technology, Applus Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Testing, Inspection and Certification (TIC) Market Trends and Innovations
Digital instrumentation and automated sampling protocols are compressing laboratory turnaround times while regulatory data integrity requirements are tightening traceability standards across the Americas TIC value chain.
Spectrometry-based material analysis is migrating from destructive sampling methods toward non-contact laser-induced breakdown spectroscopy. Automotive OEMs and aerospace suppliers are adopting these platforms for in-line quality verification. This migration from benchtop to production-floor deployment is collapsing the time between manufacturing and certification release.
EPA's expanded greenhouse gas reporting mandates under the Inflation Reduction Act are compelling industrial emitters to install continuous emissions monitoring systems with third-party verification. Oil and gas facilities along the US Gulf Coast face the most immediate compliance deadlines. TIC providers are responding by building dedicated atmospheric testing mobile units rather than relying on stationary laboratory networks.
Retailer-driven supplier certification requirements are consolidating procurement decisions around fewer accredited TIC partners with multi-category capabilities. North American big-box channels increasingly mandate single-source assurance programs covering safety, sustainability, and social compliance. This concentration pattern is most visible in consumer goods and electronics sourcing from Mexican and Central American manufacturing zones.
Americas Testing, Inspection and Certification (TIC) Market Segmentation
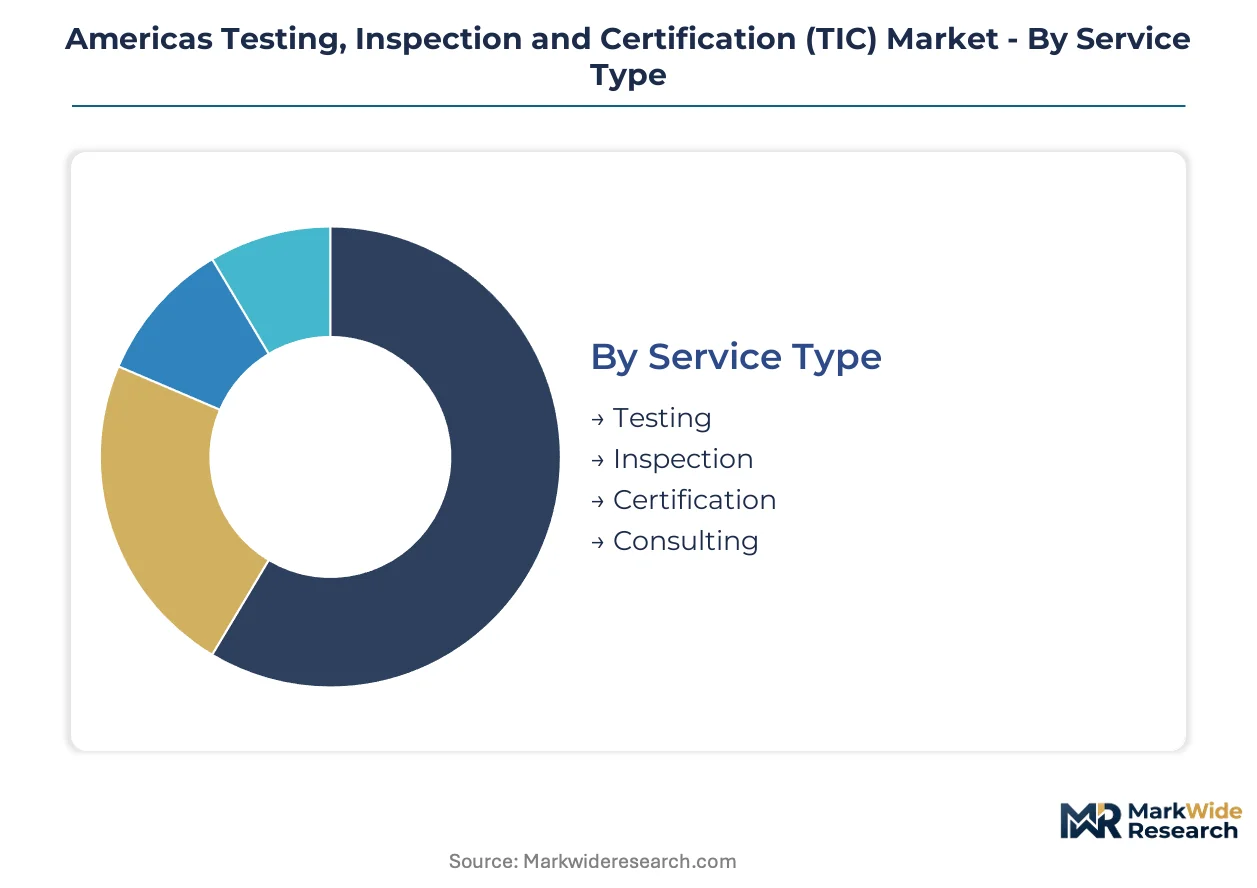
TIC providers configure service portfolios around distinct value capture mechanisms, from capital-intensive laboratory testing to recurring audit subscriptions. Understanding segment boundaries clarifies where accreditation requirements, technology investments, and regulatory mandates concentrate competitive advantage.
Service Type:
Cost tier structures separate segments by capital intensity and margin profile, with equipment-heavy services demanding upfront laboratory investment while knowledge-based offerings scale through talent density.
- Testing:Spectrometry, tensile analysis, and environmental simulation require accredited laboratory infrastructure with metrology-calibrated instrumentation. Demand concentrates in automotive battery validation corridors across Michigan and Ohio, where NHTSA thermal runaway protocols multiply cell chemistry verification touchpoints.
- Inspection:Physical witness examination and non-destructive evaluation deploy field personnel to manufacturing sites, energy infrastructure, and construction projects. Gulf Coast offshore platforms and Mexican nearshoring facilities drive volume as OSHA process safety and Mexican labor standards enforcement intensify.
- Certification:Formal attestation and mark licensing generate recurring surveillance revenue through multi-year compliance contracts.
- Consulting:Advisory services on regulatory strategy and quality system implementation capture premium hourly rates.
Testing commands the established base. The steepest expansion runs through certification subscription models.
End User:
Application concentration varies by regulatory exposure and supply chain complexity, with sectors facing multi-jurisdictional compliance obligations driving premium service demand.
- Manufacturing:Industrial production quality assurance spans supplier qualification, in-process verification, and finished goods release across discrete and process industries. Electronics and automotive component production in Mexican border states generates sustained demand for ISO 9001 and IATF 16949 audit services.
- Healthcare:FDA Quality System Regulation compliance and medical device premarket submission requirements structure demand for 21 CFR Part 820 auditing and 510(k) testing support.
- Automotive:Battery electric vehicle platforms require expanded cell chemistry stability validation and thermal propagation containment verification.
- Construction:Structural integrity assessment and materials certification support building code compliance and infrastructure project financing.
Manufacturing anchors volume throughput. Healthcare delivers the fastest margin expansion.
Technology:
Volume scalability separates technology-enabled service delivery from labor-constrained traditional methods, with data infrastructure investments determining competitive differentiation.
- IoT:Sensor networks enable continuous emissions monitoring and predictive equipment surveillance, compressing inspection cycle times for utility and energy clients.
- AI:Machine learning algorithms automate defect detection in visual inspection workflows and predict failure modes in materials testing protocols.
- Big Data:Regulatory submission databases and historical compliance archives inform risk-based sampling strategies.
- Automation:Robotic sampling and digital instrumentation reduce laboratory turnaround times while tightening traceability standards.
IoT platforms capture the installed base. AI applications are climbing the fastest.
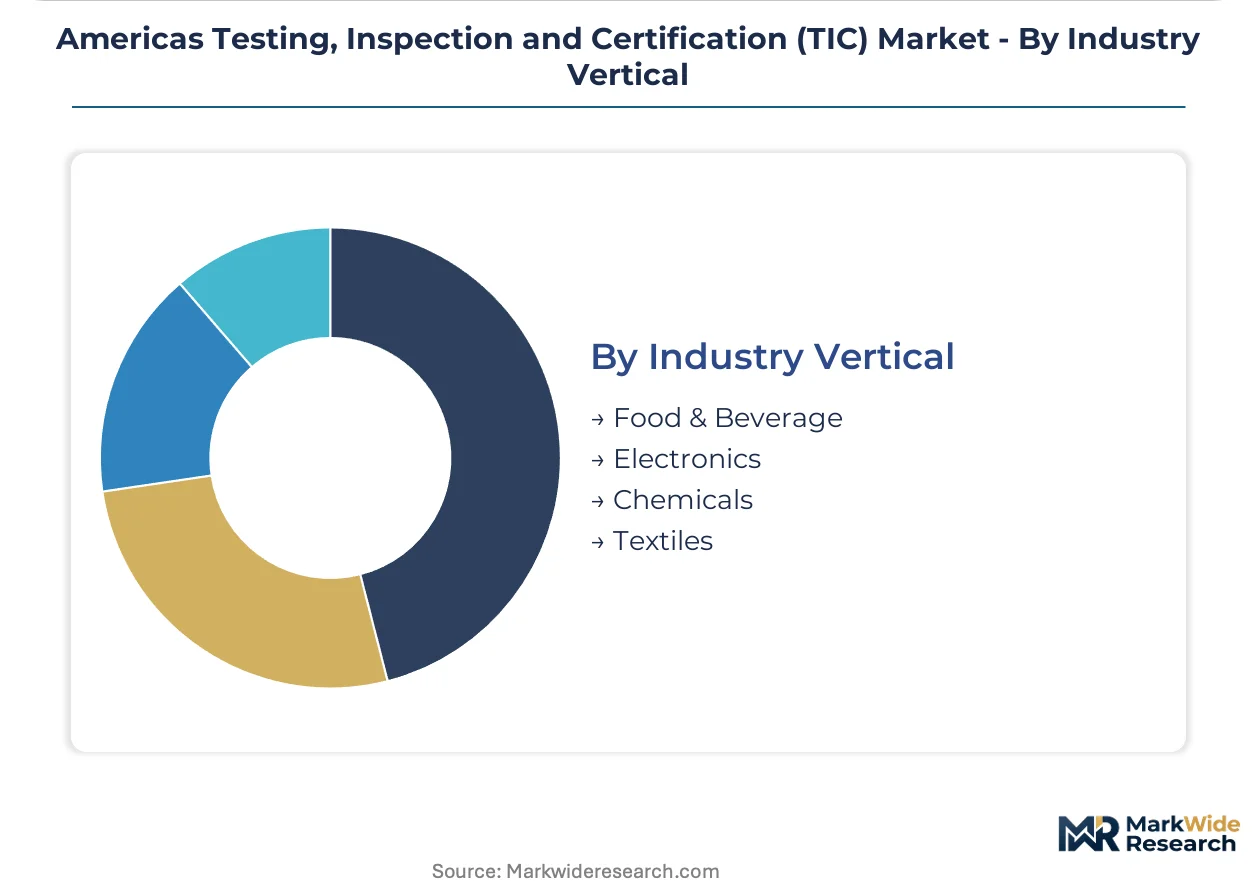
Industry Vertical:
Customer type diversity shapes service bundling requirements, with multi-category accreditation determining procurement consolidation patterns among large buyers.
- Food & Beverage:Pesticide residue analysis, microbiological testing, and GMO verification support export access to European and Asian markets. Brazil's agricultural export corridors concentrate demand for ANVISA-compliant local laboratory partnerships.
- Electronics:RoHS substance restrictions, FCC electromagnetic compatibility, and safety mark certification govern North American market access for Asian and Latin American manufacturing.
- Chemicals:EPA toxic substance control and workplace hazard assessment requirements mandate third-party validation.
- Textiles:Restricted substance testing and social compliance auditing respond to retailer-driven supplier certification mandates.
Food and beverage holds the established revenue base. Electronics verticals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and Mexico exhibit the highest price elasticity for commodity testing services, while US automotive and healthcare sectors absorb premium pricing for accelerated certification timelines. This demand-elasticity contrast shapes where TIC providers deploy capital-intensive laboratory infrastructure versus lean field inspection networks.
United States
Electric vehicle battery validation and FDA medical device submissions dominate service demand. The Inflation Reduction Act's domestic content requirements redirect certification workflows toward North American laboratories. Michigan and Ohio host the densest automotive testing clusters, where NHTSA thermal runaway protocols multiply cell chemistry verification touchpoints.
Brazil
Agricultural export corridors drive pesticide residue and GMO verification demand for European and Asian buyers. ANVISA pharmaceutical import protocols require local laboratory partnerships for market entry. São Paulo anchors the largest concentration of food safety testing capacity serving the Mercosur trade bloc.
Mexico
Nearshoring momentum from Asian manufacturing relocation generates electronics and automotive component certification needs. Mexican labor standards enforcement intensifies inspection demand at border-state assembly facilities. Nuevo León and Baja California concentrate new laboratory investments serving US market access requirements.
Canada
Energy infrastructure inspection and environmental emissions verification structure demand in Alberta and British Columbia. Health Canada medical device regulations parallel FDA frameworks, creating cross-border certification efficiencies. Ontario hosts the primary healthcare testing corridor serving North American pharmaceutical submissions.
Americas Testing, Inspection and Certification (TIC) Market Competitive Landscape
Capability concentration sits with heritage specialists possessing multi-decade accreditation portfolios; scale advantage sits with diversified conglomerates spanning testing, inspection, and certification under unified brands. The Americas TIC market exhibits tiered consolidation, with three global groups commanding disproportionate share in premium certification segments while mid-scale laboratories compete on turnaround speed and sector specialization. Strategic archetypes include agricultural-commodity specialists, marine-offshore inspection anchors, and consumer-goods assurance integrators. Dominant competitive moves encompass geographic footprint rebuilding around IRA eligibility zones and subscription-based audit model deployment to capture lifetime customer value.
Within the diversified conglomerate tier, SGS SA, Bureau Veritas, and Intertek Group Plc occupy positions exemplifying distinct geographic and sector anchoring strategies. SGS SA represents the agricultural and minerals testing heritage archetype with Latin American commodity corridor dominance. Bureau Veritas exemplifies marine and offshore inspection network concentration tied to Gulf Coast energy infrastructure. Intertek Group Plc sits within the consumer goods assurance archetype, controlling retailer shelf-access decisions across North American big-box channels.
| Leading Market Players |
|---|
| SGS SA |
| Intertek Group Plc |
| Bureau Veritas |
| UL LLC |
| TÜV SÜD |
| TÜV Rheinland |
| Eurofins Scientific |
| Element Materials Technology |
| Applus Services |
| Others |
Pricing and Supply Chain Analysis
Panama Canal transit corridors shape cost dynamics for laboratory equipment imports into Brazil and Mexico, concentrating supply-side leverage among accredited providers near coastal logistics hubs while downstream price differentiation separates premium certification tiers from commodity testing services.
Pricing Analysis
Recurring surveillance audit contracts anchor lifetime value capture, with three-tier pricing structure across premium, standard, and economy levels separating FDA-tier medical device validation from routine agricultural commodity screening. Certification grade and volume scale drive price differentiation, while cost compression in standard-tier food safety testing intensifies due to mid-scale laboratory overcrowding. Healthcare buyers absorb premium pricing for accelerated FDA submission support; agricultural exporters exhibit highest price sensitivity for pesticide residue verification.
Supply Chain Analysis
Contract manufacturing concentration rests with German and Japanese analytical instrumentation suppliers for spectrometry and environmental simulation equipment. Laboratory networks draw from US metrology calibration sources, South Korean sensor component providers, and Swiss precision instrumentation. Single-source vulnerability concentrates in advanced mass spectrometry platforms, with distribution running through authorized distributor channels rather than direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage as AI-assisted inspection tools and cloud-based compliance portals reconfigure interoperability standards between TIC providers and industrial client systems.
For Market Incumbents: Insulate certification mark authority by deepening captive supply of AI-driven predictive inspection algorithms and expanding accredited laboratory footprints in IRA-eligible domestic content zones. Defend against mid-scale specialists by locking multi-year surveillance contracts with automotive OEMs and healthcare device manufacturers before subscription audit models commoditize.
For New Entrants and Emerging Players: Secondary Brazilian agricultural corridors beyond São Paulo present the most penetrable geography for pesticide residue and GMO verification laboratories serving European phytosanitary protocols. Target ANVISA partnership pathways and undercut established providers on turnaround speed for commodity export certification. Lead with digital client portals offering real-time compliance tracking as the primary go-to-market wedge.
For Investors and Strategic Acquirers: The Inflation Reduction Act's domestic content mandates reshape the acquisition landscape toward North American laboratory assets with federal incentive eligibility. Long-term viability centers on recurring revenue intensity rather than transactional project volume. Monitor FDA 510(k) submission queue lengths as the inflection signal for healthcare TIC demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Portfolio Expansion | Broadening ISO 17025 scopes into EV battery thermal runaway testing captures NHTSA-mandated demand corridors across Michigan and Ohio. |
| AI-Assisted Inspection Platform Launch | Machine learning defect detection compresses field inspection cycle times for Gulf Coast offshore infrastructure clients. |
| Subscription Audit Model Deployment | Multi-year surveillance contracts replace transactional revenue and lock lifetime value across industrial manufacturing accounts. |
| Mexico Nearshoring Laboratory Buildout | Border-state capacity additions serve electronics and automotive component certification for US market access requirements. |
| Brazil Agricultural Corridor Partnership | ANVISA-aligned local laboratories capture pesticide residue and GMO verification demand from European and Asian buyers. |
Research Methodology
Initial hypotheses were tested against primary input from laboratory operations directors, regulatory affairs managers at medical device manufacturers, automotive supplier quality engineers, and agricultural export compliance officers and refined through secondary validation against FDA 510(k) submission databases, ANVISA import protocol filings, EPA emissions monitoring disclosures, and customs trade records for analytical instrumentation. Bottom-up service provider revenue estimates and top-down end-user demand sizing were triangulated to reconcile segment-level figures.
Demand-supply balance dynamics across the projection horizon structured the analytical framework, with segmentation dimensions spanning service type, end-user industry, technology deployment, and regional regulatory cluster. CAGRs were derived from regression analysis of historical accreditation expansion rates and forward-projected regulatory mandate intensities, incorporating EV battery safety protocol multiplication and IRA domestic content eligibility requirements as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by diversified conglomerates or disruptive pricing by AI-native entrants would shift outcomes beyond modeled ranges. Quarterly review of FDA submission queue lengths, ANVISA partnership announcements, and IRA laboratory eligibility designations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Piping Hydro Testing Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Paper Tester Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Viscometer Market
Testing Equipment
Europe Process Analytics Market
Testing Equipment
Global Asbestos Testing Market
Testing Equipment
Gold Purity Tester Market