
 Material Tester Market | 2026-2036
Material Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Material Tester Market Outlook
Multi-source procurement among aerospace and automotive OEMs is repositioning how testing equipment vendors secure long-term contracts. Illinois Tool Works Inc. leverages its diversified industrial portfolio to cross-sell calibration services alongside hardware. Zwick Roell anchors its competitive stance through deep specialization in materials testing for European automotive certification. MTS Systems Corporation dominates high-force simulation segments where aerospace customers require custom servo-hydraulic configurations.
A material tester is an instrument that applies controlled mechanical forces—tension, compression, torsion, or impact—to specimens in order to quantify properties such as yield strength, elongation at break, and fracture toughness, with load capacities ranging from newtons to meganewtons depending on the application. These systems serve as critical gatekeeping tools across manufacturing supply chains, ensuring that raw materials and finished components conform to specified performance envelopes before release to downstream assembly. Tensile testers command the largest installed base due to their ubiquity in metals and polymer certification workflows, while fatigue testers capture disproportionate margin pools from aerospace engine programs with extended validation cycles. Digital technology segments are displacing mechanical counterparts as manufacturers integrate force transducers with cloud-connected data acquisition platforms for real-time statistical process control.
FAA airworthiness directives and NHTSA crashworthiness standards in the United States, alongside ECE vehicle type-approval frameworks in Europe, mandate repeatable test documentation that drives capital expenditure on calibrated equipment. ISO 6892 and ASTM E8 further tighten the specification landscape, compelling laboratories to upgrade load-frame accuracy and software traceability. Stakeholders must weigh the capital efficiency of retrofitted digital controllers against full-platform replacement as regulatory audit frequencies intensify across certificate-dependent industries.
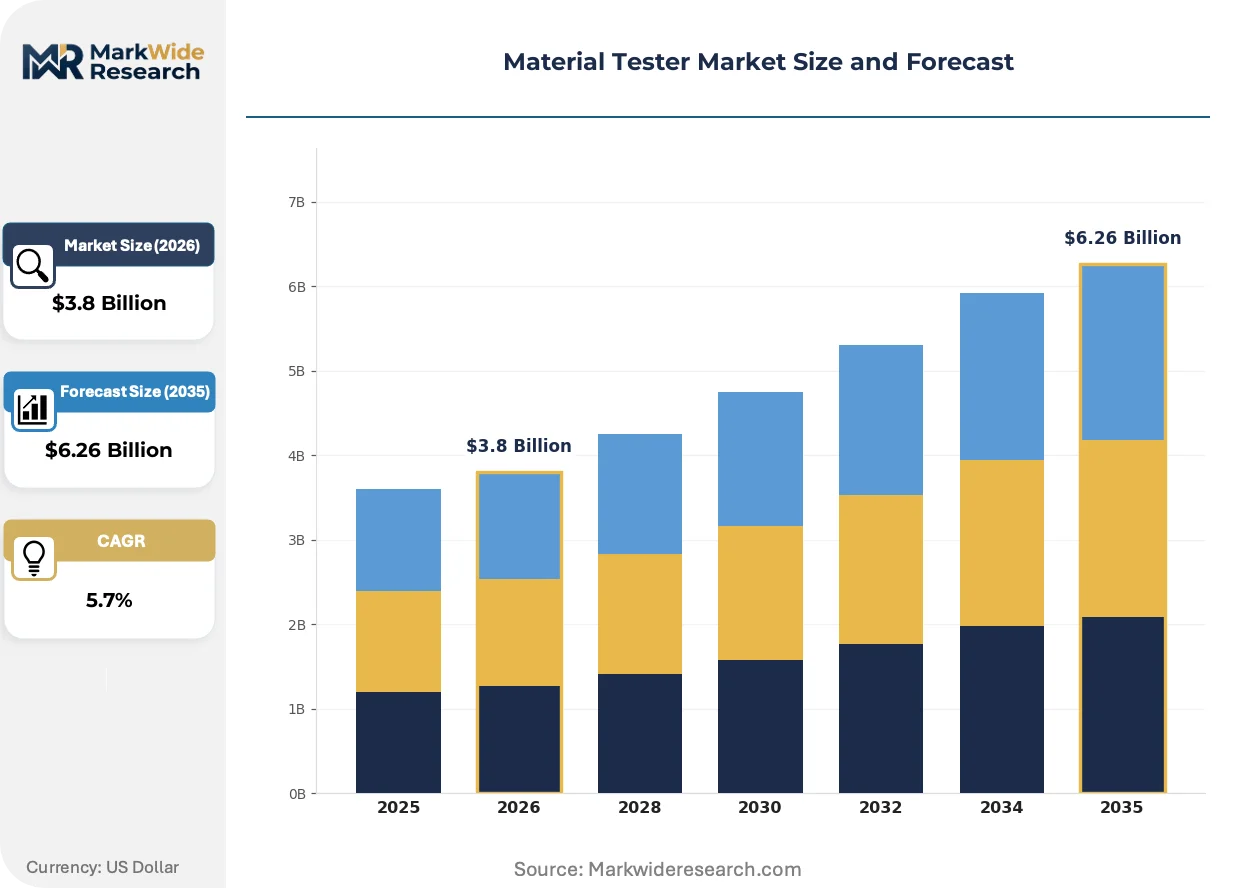
Market Dynamics
Automotive lightweighting mandates are compressing validation timelines, forcing OEMs to accelerate test cycles for aluminum alloys and carbon-fiber composites while maintaining NHTSA and ECE traceability standards.
Growth Catalysts
- ISO 6892-1 Compliance Deadlines:European automotive suppliers face mandatory upgrades to digital load-frame systems to maintain CE marking for structural component exports.
- Battery Enclosure Certification:Electric vehicle manufacturers require puncture and crush testing for lithium-ion module housings, expanding demand for high-capacity universal testing machines.
- Germany:Dense clusters of Tier-1 suppliers in Stuttgart and Munich operate round-the-clock quality labs, sustaining replacement demand for servo-hydraulic fatigue systems.
Market Restraints
- Specialized Load Cell Supply:Strain-gauge transducer manufacturing concentrates among Japanese and German component suppliers, creating lead-time vulnerability for system integrators.
- ASTM E8 Calibration Burden:Annual recertification requirements for tensile testing laboratories impose recurring operational costs that deter mid-tier manufacturers from in-house testing adoption.
- Optical Extensometry Substitution:Non-contact strain measurement systems using digital image correlation threaten traditional clip-on extensometer attach rates in polymer testing workflows.
Strategic Opportunities
- Additive Manufacturing Qualification:Powder-bed fusion part certification requires novel porosity-mechanical property correlation protocols, opening service revenue for testing laboratories.
- India:BIS implementation of harmonized automotive steel standards creates first-mover advantage for equipment vendors establishing calibration partnerships with domestic metal producers.
- Cloud-Connected SPC Integration:Convergence of force transducer data with manufacturing execution systems enables real-time pass-fail decisions at forging and stamping lines.
Industry Challenges
- Servo-Hydraulic Technician Scarcity:Maintenance of high-force fatigue systems requires specialized fluid power expertise that vocational programs have deprioritized in favor of mechatronics training.
- Legacy Controller Retrofit Complexity:Digital acquisition upgrades for 1990s-era test frames demand custom signal conditioning that extends commissioning timelines beyond planned production windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Material Tester Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tensile Tester, Hardness Tester, Impact Tester, Fatigue Tester Technology: Digital, Mechanical, Hydraulic, Pneumatic End User: Manufacturers, Research Institutions, Quality Control Labs, Educational Institutes Application: Construction, Aerospace, Automotive, Consumer Goods |
| Companies Covered | Illinois Tool Works Inc., Zwick Roell, Shimadzu Corporation, AMETEK Inc., Instron, MTS Systems Corporation, Tinius Olsen, Hegewald & Peschke, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Material Tester Market Strategic Shifts
Digital thread integration is dissolving boundaries between materials characterization and production quality control, embedding testing data directly into supplier audit trails and airworthiness documentation.
Electromechanical test frames with linear motor actuation are expanding into aerospace fastener qualification programs, where Boeing and Airbus suppliers adopt these systems for their energy efficiency and reduced maintenance intervals compared to hydraulic alternatives. The technology compresses total cost of ownership calculations for high-cycle fatigue applications.
REACH substance restrictions on hydraulic fluids are compelling European equipment operators to retrofit biodegradable synthetic alternatives or migrate to fully electric actuation architectures. MTS Systems and Zwick Roell have accelerated oil-free product roadmaps for customers serving German automotive OEMs with strict environmental audit protocols.
Multi-year service contracts with embedded uptime guarantees are displacing transactional calibration arrangements among North American aerospace Tier-1 suppliers. Boeing's 787 and 777X programs demand continuous test-cell availability, pushing vendors toward predictive maintenance models using transducer health monitoring algorithms.
Material Tester Market Segmentation
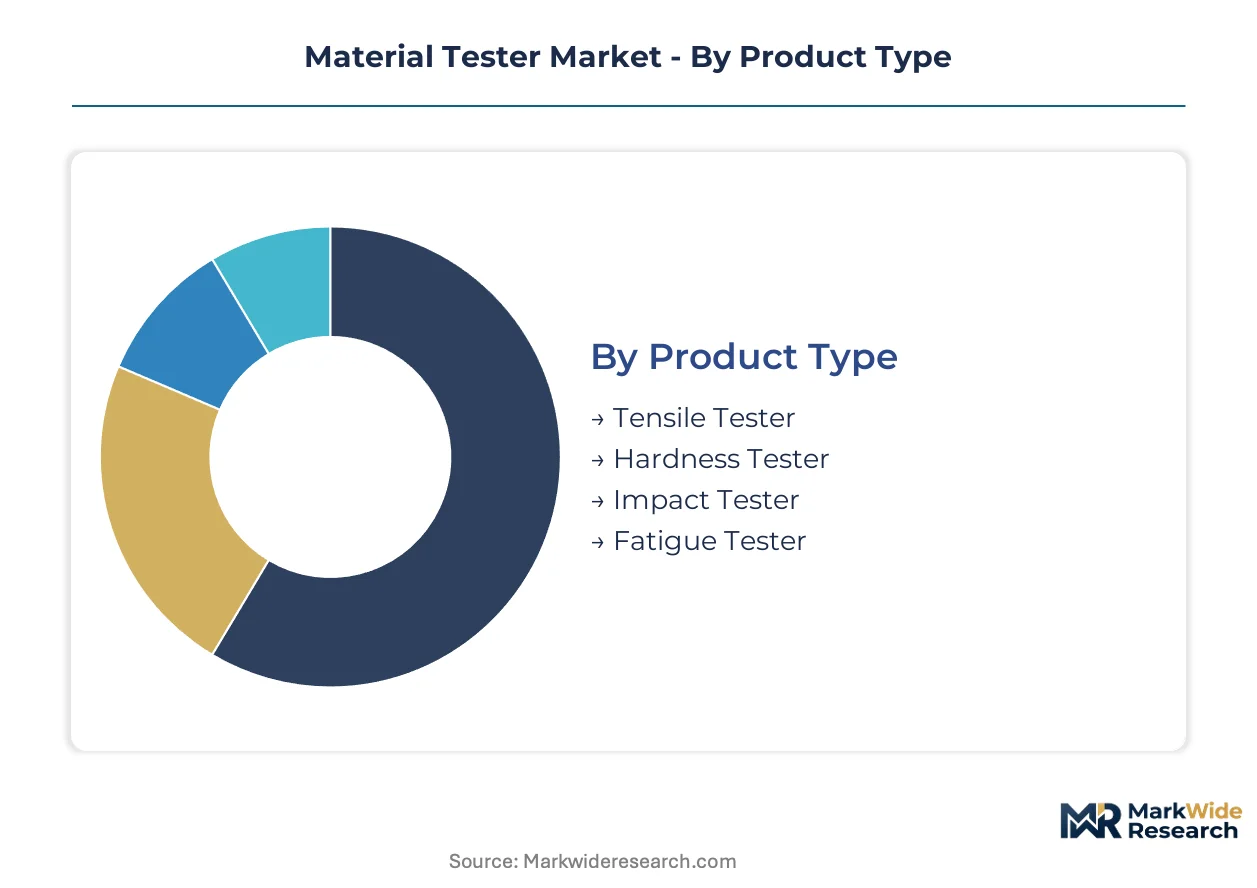
Material tester procurement patterns diverge sharply across product architectures and operational environments. Capital deployment decisions hinge on force-range requirements, certification protocols, and integration complexity with existing quality management systems.
Product Type:
Tensile and fatigue systems demand the heaviest upfront capital outlay due to precision load-frame engineering and extended calibration infrastructure.
- Tensile Tester:Electromechanical or hydraulic frames apply uniaxial tension to quantify yield strength, ultimate tensile strength, and elongation per ASTM E8 and ISO 6892 protocols. German automotive OEMs in Stuttgart and Munich maintain the densest installed base for structural steel and aluminum alloy certification workflows.
- Fatigue Tester:Servo-hydraulic or electrodynamic systems subject specimens to cyclic loading for crack propagation and endurance limit characterization. Aerospace engine programs in the United States drive replacement demand as FAA airworthiness directives mandate extended validation cycles for turbine disk alloys.
- Hardness Tester:Rockwell, Brinell, and Vickers configurations provide rapid indentation-based assessments for heat-treated components and surface coatings.
- Impact Tester:Pendulum or drop-tower designs measure Charpy and Izod toughness for low-temperature performance qualification in pipeline steels and automotive crash structures.
Most installed capacity flows through Tensile Tester systems. Expansion is steepest in Fatigue Tester configurations.
Technology:
Digital architectures command premium pricing but compress total cost of ownership through reduced maintenance and cloud-connected data pipelines.
- Digital:Closed-loop control systems integrate force transducers with real-time data acquisition platforms enabling statistical process control integration. European automotive suppliers face mandatory upgrades to maintain CE marking compliance under harmonized ISO standards.
- Hydraulic:Servo-valve controlled fluid power delivers high-force capability for aerospace structural testing and metal forging qualification. REACH substance restrictions on hydraulic fluids are accelerating migration timelines in Germany.
- Mechanical:Screw-driven and lever-based designs persist in educational settings and low-throughput quality labs with limited capital budgets.
- Pneumatic:Compressed air actuation serves light-force polymer and textile testing where rapid cycle rates outweigh precision requirements.
Digital platforms now dominate new order intake. Hydraulic retains dominance in force ranges exceeding one meganewton.
End User:
Quality control laboratories generate the most predictable replacement cycles due to mandated audit frequencies and certificate-dependent operational licenses.
- Quality Control Labs:Tier-1 supplier facilities operate round-the-clock testing cells for incoming material verification and finished component release. Boeing 787 and 777X programs demand continuous availability with embedded uptime guarantees.
- Manufacturers:In-house testing departments at automotive OEMs and primary metals producers integrate material characterization directly into production workflows. Battery enclosure certification for electric vehicles is expanding high-capacity universal testing machine procurement.
- Research Institutions:Universities and national laboratories pursue novel materials development with emphasis on additive manufacturing qualification protocols.
- Educational Institutes:Vocational and undergraduate programs prioritize mechanical and basic digital systems for instructional purposes.
Quality Control Labs anchor replacement demand. Research Institutions are gaining share fastest for advanced electromechanical configurations.
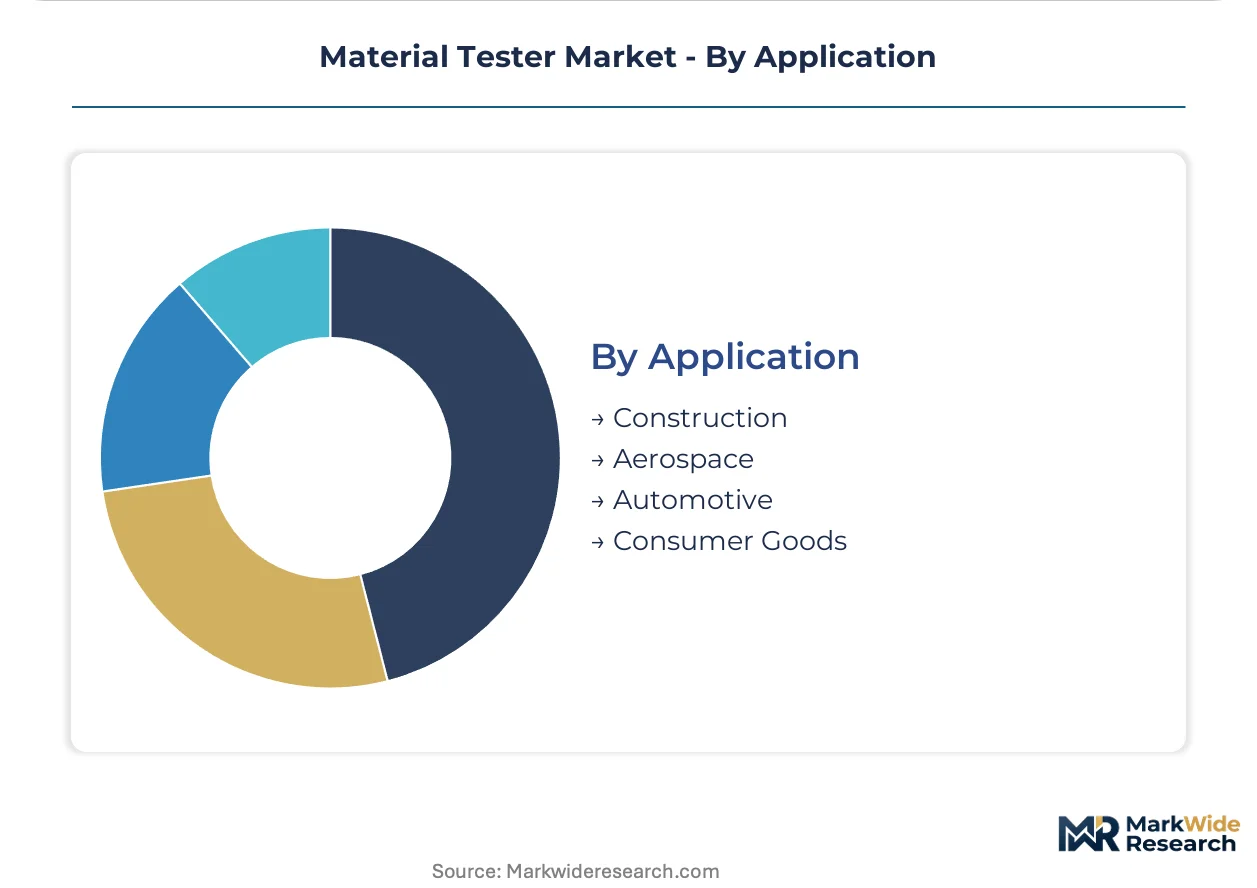
Application:
Aerospace and automotive applications concentrate the highest-value testing contracts due to regulatory documentation burdens and extended validation timelines.
- Aerospace:Fastener qualification, turbine disk testing, and composite laminate characterization require NADCAP-traceable calibration chains. Electromechanical frames with linear motor actuation are displacing hydraulic alternatives for energy efficiency.
- Automotive:Lightweighting mandates for aluminum alloys and carbon-fiber composites compress validation timelines while maintaining NHTSA and ECE traceability standards.
- Construction:Rebar, structural steel, and concrete admixture testing follows regional building code specifications with periodic third-party verification.
- Consumer Goods:Packaging integrity, textile durability, and appliance component testing operates at lower force ranges with simplified documentation requirements.
Automotive applications command the largest equipment count. Aerospace applications generate the highest margin per installed system.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping equipment procurement as manufacturers relocate testing capacity to jurisdictions with streamlined certification pathways. Cost-of-compliance gaps between NHTSA-driven North American protocols and CE-marking European frameworks are accelerating facility investments in lower-audit-frequency environments.
United States
FAA airworthiness directives and NHTSA crashworthiness standards mandate exhaustive documentation for aerospace and automotive suppliers. Boeing's 787 and 777X programs in Washington State and South Carolina drive continuous test-cell availability requirements. Wichita, Kansas anchors fastener qualification demand from precision component manufacturers serving commercial aviation.
Germany
KBA type-approval frameworks and REACH substance restrictions on hydraulic fluids compel equipment upgrades among automotive OEMs. Stuttgart and Munich host dense Tier-1 supplier networks operating round-the-clock quality laboratories. Baden-Württemberg's automotive cluster sustains replacement cycles for servo-hydraulic fatigue systems.
China
GB standards harmonization and MIIT automotive certification requirements expand domestic laboratory capacity. MIIT's dual carbon goals accelerate migration from hydraulic to electric actuation architectures. Yangtze River Delta manufacturing bases in Shanghai and Jiangsu province concentrate battery enclosure testing for electric vehicle producers.
Japan
METI industrial standards and JIS certification protocols maintain stringent load-frame accuracy requirements for precision metal suppliers. Nagoya's aerospace subcontractor network qualifies turbine disk alloys under extended validation cycles. Chubu region testing facilities serve Toyota and Honda supply chains with NADCAP-traceable calibration chains.
India
BIS implementation of harmonized automotive steel standards creates equipment procurement windows for domestic metal producers. CDSCO medical device regulations extend testing requirements to implant-grade materials. Maharashtra and Gujarat manufacturing corridors attract first-mover calibration partnerships from international equipment vendors.
Material Tester Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electromechanical specialization and cloud-connected data platforms. The vendor base stratifies across diversified industrial conglomerates, European certification specialists, and precision instrumentation houses. Three archetypes dominate: diversified portfolio holders cross-selling calibration services, regional specialists anchoring geographic certification ecosystems, and high-force simulation customizers. Competitive moves concentrate on M&A for digital controller capabilities and strategic partnerships for additive manufacturing qualification protocols.
Among diversified industrial holdings, Illinois Tool Works Inc. exemplifies the portfolio-breadth archetype, leveraging cross-divisional service networks. Zwick Roell occupies a position within the European specialist tier, anchoring certification-centric relationships with German automotive OEMs. MTS Systems Corporation represents the high-force customization archetype, serving aerospace customers with bespoke servo-hydraulic configurations.
| Leading Market Players |
|---|
| Illinois Tool Works Inc. |
| Zwick Roell |
| Shimadzu Corporation |
| AMETEK Inc. |
| Instron |
| MTS Systems Corporation |
| Tinius Olsen |
| Hegewald & Peschke |
| Bruker Corporation |
| Others |
Value Chain & Pricing Dynamics
Battery enclosure certification mandates from NHTSA and ECE regulators are compressing procurement timelines for high-capacity universal testing machines, forcing equipment vendors to absorb strain-gauge transducer cost volatility or risk losing aerospace and automotive contracts.
Pricing Analysis
Input-cost pass-through from Japanese and German strain-gauge transducer suppliers governs system-level pricing, with servo-hydraulic fatigue configurations bearing the steepest markups due to specialized load cell dependencies. Three-tier pricing structure across premium, standard, and economy levels separates NADCAP-traceable aerospace systems from CE-marked automotive workhorses and educational mechanical units. Cost compression in mid-tier electromechanical frames is intensifying because REACH-compliant hydraulic fluid retrofits add recurring service bundling requirements. Research institutions exhibit highest price sensitivity due to grant-funded capital cycles, while quality control labs at Boeing and Airbus suppliers demonstrate lowest sensitivity given uptime guarantee mandates.
Supply Chain Analysis
Freight cost escalation for precision-ground ball screws and linear motor actuators from Japan and Germany is elevating landed costs for electromechanical frame assemblers in North America and China. Component manufacturing concentrates in Japan, Germany, and the United States for force transducers, servo valves, and digital controllers. Raw material dependencies span high-grade aluminum alloys for load frames, rare-earth magnets for linear motors, and synthetic hydraulic fluids compliant with REACH restrictions. Single-source vulnerability pervades strain-gauge transducer supply, where NMB and HBM anchor global capacity. Distribution runs through direct OEM sales teams for aerospace programs and regional distributor networks for automotive Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchet effects, with FAA airworthiness directives and ECE vehicle type-approval frameworks mandating equipment refresh cycles that outpace typical industrial machinery depreciation schedules.
For Market Incumbents: Deepen calibration service bundling to capture recurring revenue from NHTSA and ECE audit frequency acceleration, while anchoring servo-hydraulic maintenance contracts with predictive algorithms that offset technician scarcity. Vertical integration into strain-gauge transducer assembly mitigates Japanese and German supply concentration risks. Certification investment in additive manufacturing qualification protocols defends margin position against emerging electromechanical specialists. For New Entrants and Emerging Players: Cloud-connected data platform partnerships offer the lowest-friction entry vector, enabling real-time SPC integration without competing on load-frame engineering heritage. Target India's BIS harmonization window for automotive steel standards, where first-mover calibration partnerships with Maharashtra and Gujarat metal producers remain unclaimed. Direct-to-laboratory digital sales channels bypass incumbent distributor lock-in at research institutions pursuing powder-bed fusion certification protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with electromechanical specialists possessing linear motor actuation IP and oil-free product roadmaps, as REACH substance restrictions accelerate hydraulic displacement across European automotive clusters. Five-to-ten-year viability favors vendors with embedded aerospace uptime guarantees rather than transactional calibration dependence. Monitor FAA airworthiness directive issuance velocity as inflection indicator for fatigue system replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Bundling | NHTSA audit frequency acceleration locks laboratories into multi-year uptime guarantee contracts with predictive maintenance algorithms. |
| Electromechanical Platform Migration | REACH-compliant oil-free architectures capture German automotive OEM procurement shifting from servo-hydraulic systems. |
| Additive Manufacturing Qualification | Powder-bed fusion certification protocols open service revenue streams from aerospace and medical implant material testing. |
| Cloud-Connected SPC Integration | Force transducer data convergence with manufacturing execution systems enables real-time pass-fail decisions at forging lines. |
| Regional Calibration Partnership | BIS harmonization in India creates first-mover advantage for equipment vendors establishing domestic metal producer relationships. |
Study Parameters
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market combining structured interviews with quality control laboratory directors, aerospace Tier-1 procurement managers, automotive OEM platform engineers, aftermarket service heads, and national standards body technical officers. Secondary validation draws from FAA airworthiness directive filings, NHTSA crashworthiness standard updates, ECE vehicle type-approval frameworks, ISO and ASTM specification revisions, and customs data for testing equipment trade flows. Bottom-up equipment shipment analysis triangulates against top-down capital expenditure surveys from automotive and aerospace manufacturing clusters.
Rate-of-change decomposition separates volume effects from mix shifts and pricing dynamics across the projection horizon. Segmentation dimensions modeled include product architecture, actuation technology, end-user category, application industry, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis correlated with mandated audit frequencies and certificate-dependent operational license renewals. Industry-specific forecast inputs incorporate NHTSA and ECE regulatory pipeline visibility, REACH substance restriction implementation timelines, and electric vehicle battery enclosure certification expansion curves.
The model assumes a particular technology adoption path; alternative pathways for electromechanical linear motor displacement of servo-hydraulic systems would alter the outlook for maintenance revenue composition and technician skill requirements. Forecasts reflect assumptions about regulatory audit frequency intensification and harmonized standard implementation schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Hydrometer Market
Testing Equipment
Laboratory Filtration Equipment and Supplies Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
Bitumen and Asphalt Testing Services Market
Testing Equipment
Global Lab Supplies Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Membrane Osmometer Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
China Material Testing Market
Testing Equipment
Corrosion Testing Services Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Water Testing Equipment Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Global Film Thickness Measurement Market