
 Europe Line Pipe Market | 2026-2036
Europe Line Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Line Pipe Market Foresight
REACH compliance is restructuring the cost-of-entry calculus for European line pipe suppliers, forcing reformulation of coating chemistries and third-party certification budgets. Tenaris SA leverages its seamless pipe expertise to dominate high-pressure hydrogen transmission tenders. ArcelorMittal S.A. sustains vertical integration from raw steel through finished pipe, insulating margin pools from scrap volatility. Salzgitter Mannesmann anchors its position in German industrial clusters with proximity to chemical and refining demand.
Europe line pipe denotes hollow tubular products manufactured to API 5L, EN 10208, or ISO 3183 specifications, typically ranging from 2 to 56 inches in nominal diameter and produced through seamless extrusion or longitudinal/ helical submerged arc welding for pressurized fluid conveyance. Seamless grades command premium positioning in sour service and ultra-high-pressure environments where weld integrity cannot be risked, while LSAW and SSAW variants occupy volume-driven trunkline installations where diameter and wall thickness scale efficiently. Steel retains overwhelming material share across oil and gas and emerging hydrogen backbone applications, though composite reinforcement is gaining traction in corrosion-critical water supply networks where lifecycle cost trumps first cost.
EMA's material safety frameworks, the EU Green Deal's Fit for 55 package, and CE marking under the Construction Products Regulation collectively dictate allowable compositions, carbon intensity thresholds, and traceability protocols for line pipe deployed across member states. ECHA's candidate list expansions for SVHCs directly constrain anti-corrosion coating formulations, pushing suppliers toward epoxy alternatives with longer qualification cycles. Buyers must monitor hydrogen purity standards under development at CEN and the interaction between national hydrogen strategies and cross-border pipeline certification reciprocity.
Market Dynamics
Hydrogen backbone deployment is compressing qualification timelines for high-pressure line pipe grades, forcing mills to accelerate EN 10208-2 certification cycles while managing alloy chemistry shifts for embrittlement resistance.
Growth Catalysts
- EU Green Deal Fit for 55:Binding carbon reduction targets mandate hydrogen pipeline retrofits across member states, generating tender volumes for large-diameter transmission infrastructure.
- Steel decarbonization:Green hydrogen-based direct reduction processes are lowering Scope 3 emissions in pipe feedstock, aligning supplier portfolios with ECHA carbon intensity disclosure requirements.
- German industrial corridor concentration:Chemical and refining clusters in North Rhine-Westphalia are anchoring demand for sour-service seamless grades in hydrogen blending applications.
Market Restraints
- Scrap volatility:Electric arc furnace feedstock costs swing with Turkish export demand, compressing margin pools for LSAW producers without captive scrap supply.
- Coating chemistry constraints:ECHA SVHC list expansions are disqualifying legacy zinc-rich formulations, forcing reformulation investments with 18-month qualification cycles.
- Seamless capacity concentration:Premium hydrogen-grade pipe supply concentrates in Italian and Romanian rolling mills, creating bottleneck risk for urgent transmission projects.
Strategic Opportunities
- Polish hydrogen valleys:National hydrogen strategy funding is unlocking trunkline projects linking Pomeranian offshore wind to Silesian industrial demand.
- Composite reinforcement convergence:Glass-fiber hybrid designs are penetrating water supply networks where lifecycle cost advantages override first-cost premiums.
- CE marking streamlining:Construction Products Regulation mutual recognition pathways are reducing re-certification burdens for cross-border pipeline tenders.
Industry Challenges
- Welding procedure qualification:Hydrogen service demands new WPS parameters for low-temperature toughness, stretching technician certification pipelines.
- Legacy system integration:Retrofitting existing natural gas networks for hydrogen blending requires material compatibility assessments against decades-old pipe specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Line Pipe Market |
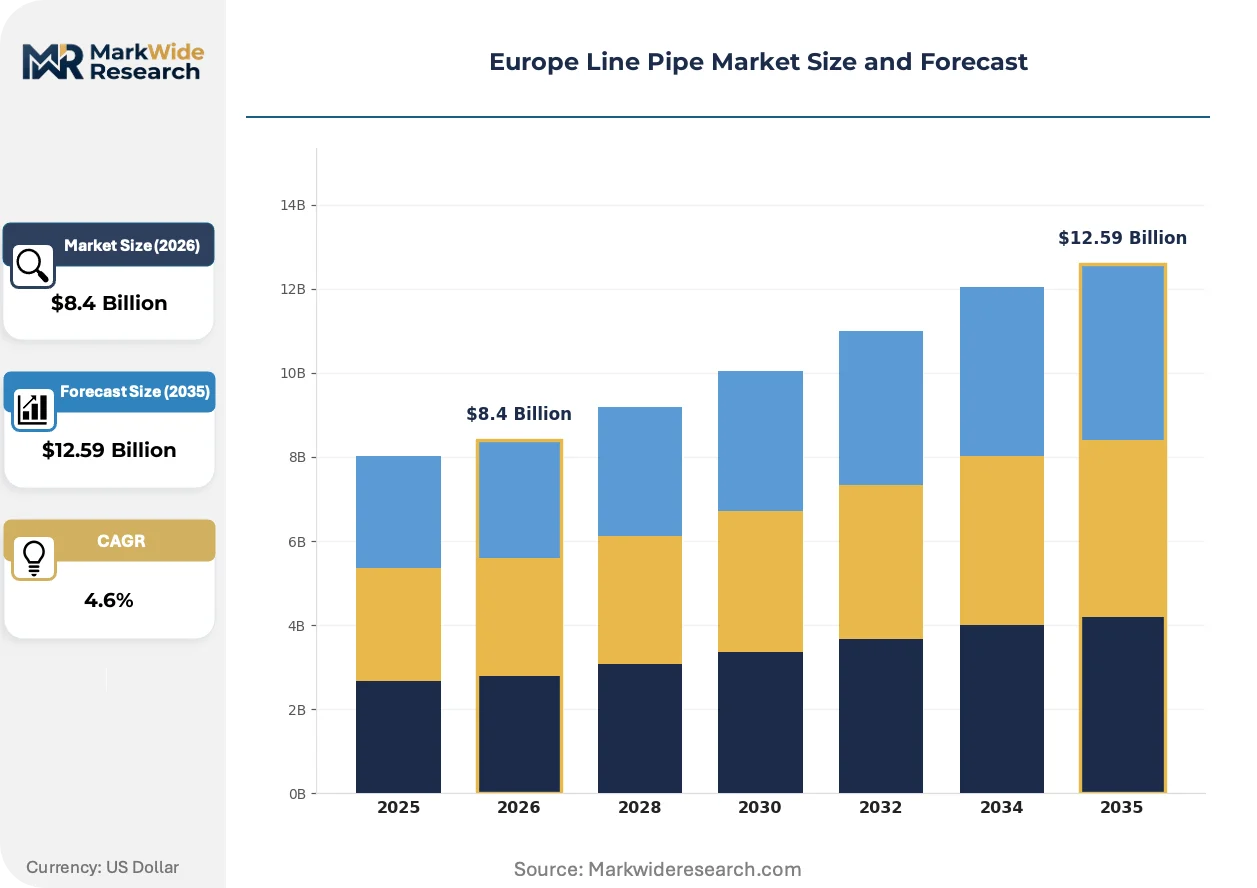
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Welded, LSAW, SSAW Material: Steel, Plastic, Composite, Copper Application: Oil & Gas, Water Supply, Sewage, Industrial End User: Utilities, Construction, Manufacturing, Transportation |
| Companies Covered | Vallourec S.A., Tenaris SA, ArcelorMittal S.A., EVRAZ plc, Corinth Pipeworks S.A., Europipe GmbH, Salzgitter Mannesmann, Borusan Mannesmann, TMK, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Line Pipe Market Shifts & Advancements
Digital traceability and advanced metallurgy are converging to reshape how line pipe specifications are validated and deployed across European transmission networks.
High-strength low-alloy grades with enhanced hydrogen compatibility are integrating into tender specifications for cross-border hydrogen backbone projects. Transmission system operators in the Netherlands and Denmark are mandating these chemistries for new-build lines. This metallurgical shift is integrating hydrogen embrittlement testing into standard mill qualification protocols, extending lead times but reducing field failure risk.
REACH candidate list expansions are accelerating coating substitution toward epoxy-phenolic systems with reduced chromate content. Mill coaters face reformulation investments exceeding seven figures per facility. German and French transmission operators are most affected, specifying third-party verification of new coating adhesion performance under cryogenic hydrogen exposure.
Buyer consortiums are consolidating procurement for transnational hydrogen corridors, displacing fragmented national tendering. Aggregated volume commitments from Dutch-German hydrogen partnerships are compressing supplier negotiation leverage. This concentration is most visible in North Sea offshore pipeline clusters, where joint sourcing frameworks now govern material specification harmonization.
Europe Line Pipe Market Segmentation
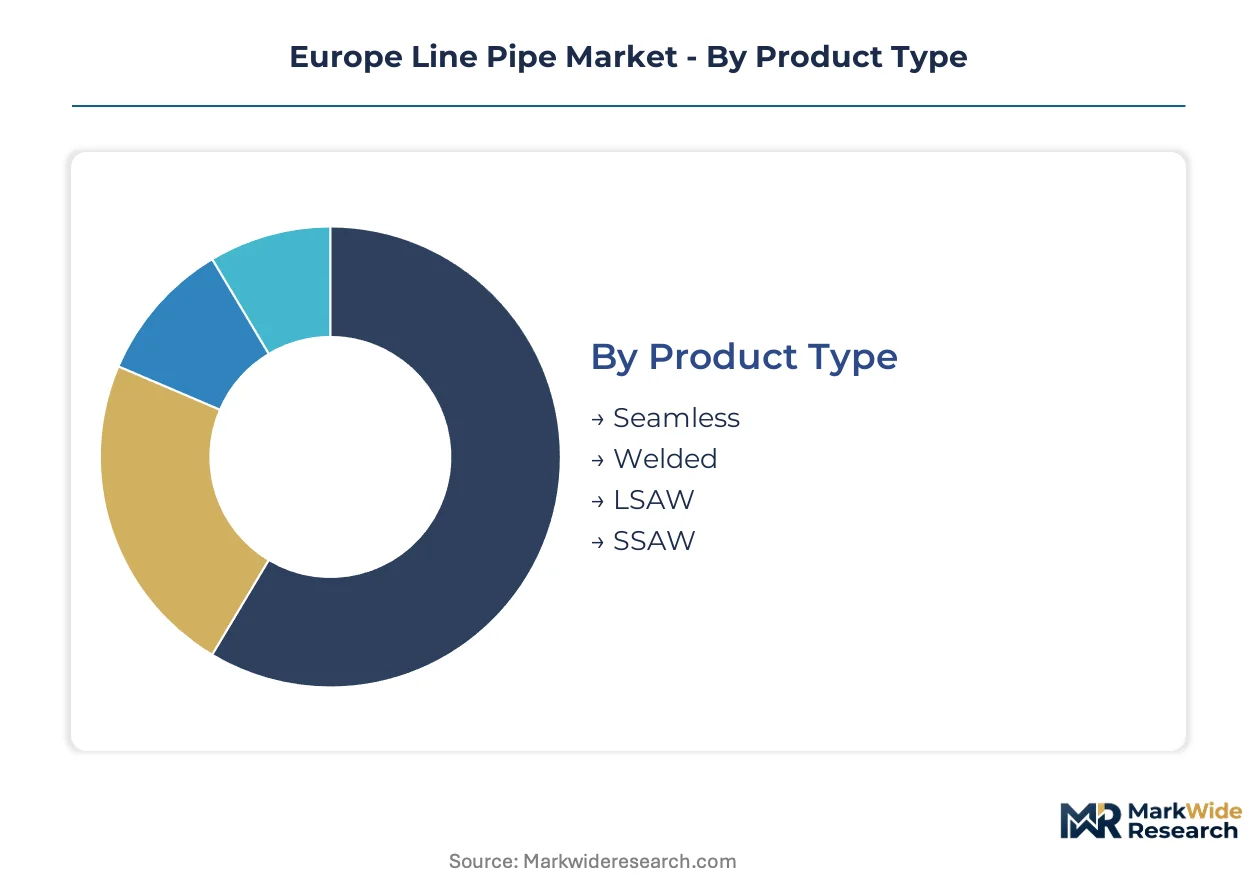
Segmentation in Europe's line pipe market reveals how hydrogen infrastructure mandates and REACH compliance are fragmenting procurement specifications across product categories. Buyers now specify material grades and welding protocols independently rather than accepting standardized portfolios.
Product Type:
Seamless and welded variants occupy fundamentally different integration depths—seamless pipes deploy as standalone pressure-bearing systems, while welded configurations integrate into larger trunkline assemblies.
- Seamless:Extruded tubular products manufactured without longitudinal welds, meeting API 5L X80+ specifications for sour service. Demand concentrates in North Rhine-Westphalia's hydrogen blending corridors where embrittlement resistance commands specification priority.
- Welded:Longitudinal or spiral seam construction enabling diameter scalability beyond seamless mill limits. Dutch and Danish transmission operators specify these for offshore hydrogen backbone segments where installation cost efficiency outweighs seamless performance premiums.
- LSAW:Longitudinal submerged arc welded pipes with single-seam geometry for large-diameter transmission. German industrial clusters anchor procurement volumes for chemical feedstock lines.
- SSAW:Helical seam construction from coiled plate, dominating water supply networks in Poland and Romania where pressure ratings remain moderate.
Seamless leads volumes today; LSAW is gaining share fastest.
Material:
Material selection stratifies across cost tiers, with premium metallurgy commanding three-to-fourfold price multiples over standard grades.
- Steel:Carbon and alloy grades retaining 90%+ share across hydrogen and hydrocarbon applications. High-strength low-alloy variants with enhanced hydrogen compatibility are penetrating Dutch-German corridor tenders.
- Plastic:Thermoplastic solutions for corrosion-critical water distribution. French utilities specify polyethylene for tertiary distribution networks where lifecycle cost trumps mechanical strength.
- Composite:Glass-fiber reinforced epoxy systems penetrating sewage and chemical processing lines. Italian water authorities pilot these for coastal installations.
- Copper:Limited to small-diameter instrumentation and utility service lines. German building codes restrict deployment to sub-2-inch diameters.
Steel dominates absolute volumes; composite materials are expanding most quickly in corrosion-sensitive applications.
Application:
Application segmentation tracks customer maturity—oil and gas incumbents specify conservatively while water utilities adopt novel materials aggressively.
- Oil & Gas:Conventional hydrocarbon transmission and hydrogen blending retrofits. Norwegian North Sea operators anchor demand for sour-service seamless grades.
- Water Supply:Potable and non-potable distribution networks. Spanish utilities are consolidating procurement for desalination feed lines.
- Sewage:Wastewater conveyance with corrosion-resistant specifications. Italian regional water boards specify cement-mortar lined steel.
- Industrial:Process piping for chemical, refining, and power generation. German chemical parks in Ludwigshafen and Leverkusen concentrate demand for high-pressure grades.
Oil and gas retains the largest installed base; water supply demonstrates the steepest expansion trajectory.
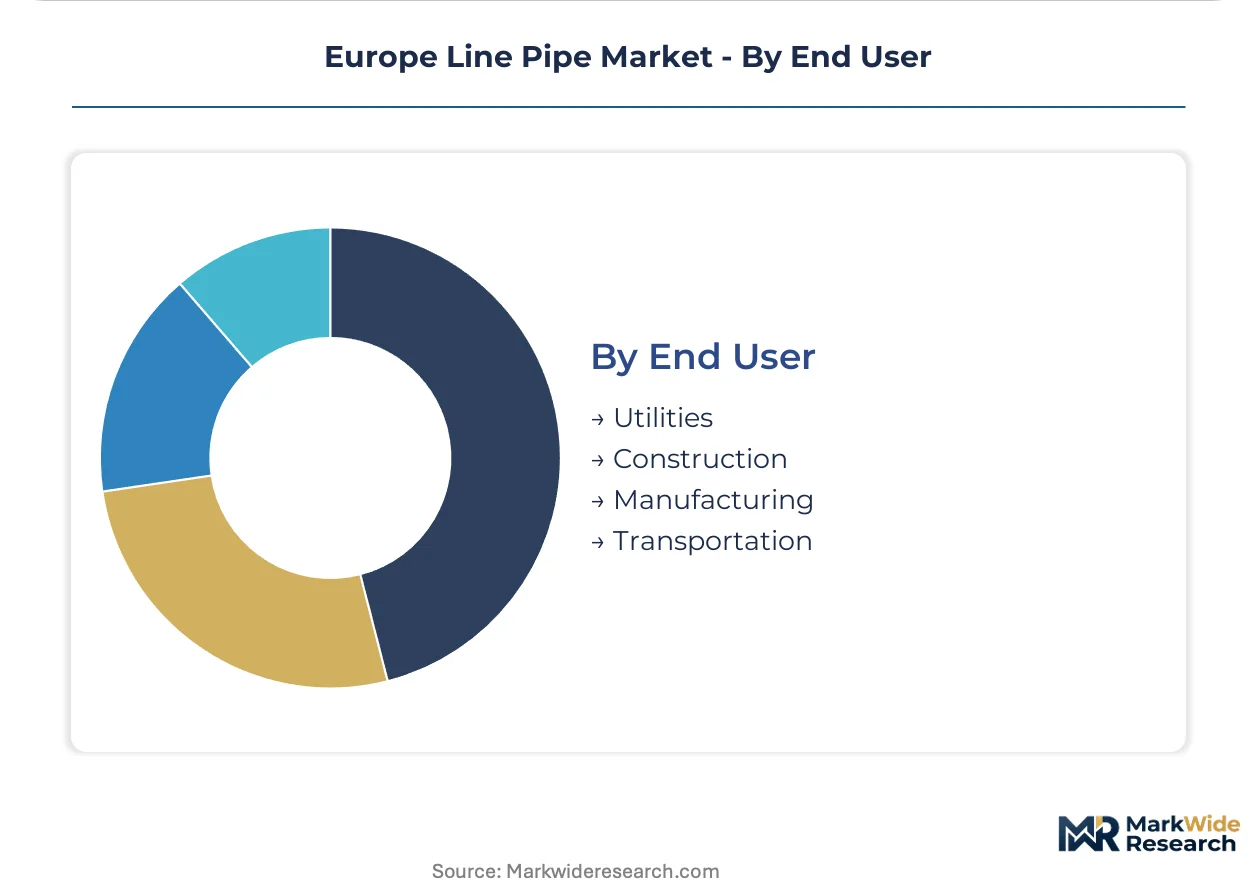
End User:
End-user concentration follows infrastructure ownership patterns—regulated utilities consolidate procurement while fragmented construction contractors accept spot market terms.
- Utilities:Regulated transmission and distribution operators with multi-year framework agreements. Dutch Gasunie and German FNB anchor hydrogen backbone tender volumes.
- Construction:EPC contractors executing project-specific procurement. Polish infrastructure builders face compressed timelines for hydrogen valley connections.
- Manufacturing:Industrial facilities with captive pipeline requirements. Chemical producers in Belgium's Port of Antwerp specify seamless for high-purity hydrogen.
- Transportation:Pipeline operators and logistics infrastructure owners. Danish Energinet governs specifications for cross-border hydrogen links.
Utilities lead procurement volumes; manufacturing end users are climbing the fastest as industrial hydrogen adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding technicians and metallurgical engineers concentrate in Germany's Ruhr industrial belt, anchoring Europe's deepest talent pool for high-pressure hydrogen pipeline fabrication and certification.
Germany
North Rhine-Westphalia's chemical parks in Leverkusen and Ludwigshafen drive demand for sour-service seamless grades in hydrogen blending applications. The EU Green Deal's Fit for 55 package mandates pipeline retrofits across German transmission networks. Bavaria's industrial corridor concentrates investment in large-diameter LSAW trunklines connecting offshore wind to inland demand centers.
Netherlands
Gasunie and Energinet anchor procurement volumes for cross-border hydrogen backbone corridors linking Dutch offshore platforms to German industrial clusters. REACH compliance deadlines are accelerating coating reformulation investments at Rotterdam-area coating facilities. The Port of Rotterdam serves as the primary import hub for hydrogen-grade pipe stockpiling.
Italy
Specialized rolling mills in northern Italy concentrate premium hydrogen-grade seamless capacity, creating supply bottlenecks for urgent transmission timelines. ECHA's SVHC list expansions are disqualifying legacy coating chemistries at Milan-area applicators. Emilia-Romagna's steel fabrication belt is pivoting mill output toward EN 10208-2 certified grades.
Poland
National hydrogen strategy funding is unlocking trunkline projects connecting Pomeranian offshore wind to Silesian industrial demand valleys. CE marking under the Construction Products Regulation governs cross-border certification reciprocity for Polish-German pipeline links. The Upper Silesian industrial zone anchors domestic demand for medium-pressure welded distribution networks.
Denmark
Energinet governs specifications for North Sea offshore hydrogen links, mandating high-strength low-alloy grades with enhanced hydrogen compatibility. The EU Green Deal's decarbonization mandates are reshaping tender specifications for Baltic Sea interconnector projects. Copenhagen's engineering consultancies are concentrating expertise in subsea pipeline installation protocols.
Europe Line Pipe Market Competitive Landscape
The competitive structure tilts toward vertically integrated steel conglomerates with captive raw material supply. Italian and Romanian rolling mills concentrate premium seamless capacity, while German and Turkish fabricators dominate large-diameter welded segments. Two strategic archetypes predominate: integrated steel-to-pipe producers with margin insulation from scrap volatility, and specialized seamless mills with metallurgical expertise in sour-service grades. Capacity expansion and coating chemistry reformulation represent the dominant competitive moves as hydrogen qualification timelines compress.
Among the integrated steel conglomerates, ArcelorMittal S.A. and Salzgitter Mannesmann exemplify the archetype of producers with backward control over raw steel supply, insulating margin pools from feedstock swings. Tenaris SA occupies a position representing specialized seamless expertise, anchoring high-pressure hydrogen transmission tenders where weld integrity cannot be compromised. These three entities collectively illustrate how European line pipe supply stratifies between scale-driven integration and metallurgical specialization.
| Leading Market Players |
|---|
| Vallourec S.A. |
| Tenaris SA |
| ArcelorMittal S.A. |
| EVRAZ plc |
| Corinth Pipeworks S.A. |
| Europipe GmbH |
| Salzgitter Mannesmann |
| Borusan Mannesmann |
| TMK |
| Others |
Supply & Pricing Matrix
Hot-rolled coil steel indices in Northwest Europe cascade through line pipe supply chains into three distinct pricing tiers: seamless grades for hydrogen service command premiums against LSAW trunkline volumes, while SSAW water utility contracts absorb the most cost compression. Scrap volatility and coating chemistry reformulation costs are redistributing margin pools across these tiers, with integrated mills capturing value that merchant producers forfeit.
Pricing Analysis
Bundled coating-and-certification packages separate premium hydrogen-grade seamless from unbundled commodity welded pipe where buyers source anti-corrosion services independently. Price differentiation rests on EN 10208-2 certification status and captive scrap supply, with ArcelorMittal and Salzgitter Mannesmann insulating margins while merchant LSAW producers face erosion. Pricing pressure stems from Turkish scrap export demand swings, compressing spot-market LSAW quotations. Water utilities in Poland and Romania exhibit highest price sensitivity, prioritizing first-cost over lifecycle metrics; Dutch Gasunie and German FNB demonstrate lowest sensitivity, embedding performance guarantees into multi-year frameworks.
Supply Chain Analysis
Direct-to-utility channels handle hydrogen backbone procurement, while distributor-mediated flows serve fragmented water and sewage contractors. Supply concentrates in Germany, Italy, and Romania for seamless rolling capacity, with German and Turkish fabricators dominating large-diameter welded segments. Raw material dependencies center on electric arc furnace scrap, hot-rolled coil feedstock, and epoxy-phenolic coating resins. Single-source vulnerability concentrates in Italian premium seamless mills, where hydrogen-grade qualification bottlenecks threaten urgent transmission timelines. Distribution runs through Rotterdam stockpiling hubs for cross-border corridor projects, with national distributors handling spot utility maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe line pipe market functions as a stable compounder, with EU Green Deal hydrogen infrastructure mandates generating tender visibility across multi-year transmission buildouts. Decarbonization compliance requirements are locking in supplier relationships and extending contract durations.
For Market Incumbents: Extend seamless capacity in hydrogen-certified grades to capture Dutch-German corridor volumes before qualification timelines compress further. Backward integration into green hydrogen-based direct reduction feedstock insulates margin pools from scrap volatility that threatens merchant LSAW competitors. Prioritize coating chemistry reformulation investments to preempt REACH SVHC disqualifications that would freeze German and French transmission operator approvals.
For New Entrants and Emerging Players: Digital procurement platforms for water utility spot contracting offer low-friction entry beneath integrated mill radar. Polish hydrogen valley trunklines present the most penetrable geography, with national strategy funding unlocking project finance but domestic seamless capacity absent. Position on rapid SSAW turnaround times for Silesian industrial distribution networks, where construction contractors prioritize delivery speed over brand heritage.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized seamless mills possessing EN 10208-2 hydrogen certification and proximity to North Sea offshore clusters. Long-term viability favors producers with captive steel supply and coating application capabilities integrated under single ownership. Monitor CEN hydrogen purity standard finalization as the critical inflection signal that will trigger accelerated tender releases across member states.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Green Steel Feedstock | Captive hydrogen-based direct reduction supply insulates margins from Turkish scrap export volatility. |
| EN 10208-2 Certification Acceleration | Compressed qualification timelines for hydrogen-grade seamless capture Dutch-German corridor tenders. |
| Coating Chemistry Reformulation | Epoxy-phenolic system investments preempt ECHA SVHC disqualification of legacy zinc-rich formulations. |
| Polish Hydrogen Valley Market Entry | National strategy funding unlocks trunkline projects linking Pomeranian offshore wind to Silesian demand. |
| Digital Procurement Platform Development | Direct channels to water utility spot buyers bypass integrated mill dominance in fragmented maintenance segments. |
Research Methodology
Direct dialogue with transmission system operator procurement directors, EPC contractor project managers, steel mill technical sales leads, and coating applicator quality managers grounded the qualitative foundation. Secondary validation drew from EU Green Deal implementation documents, ECHA SVHC candidate list updates, CEN hydrogen standard draft specifications, and national hydrogen strategy filings across Germany, Netherlands, Poland, and Denmark. Bottom-up tender volume aggregation and top-down steel consumption correlation established cross-verified demand estimates.
Segment-level value outputs combined product type splits with application-specific pricing tiers across the projection horizon. The analytical framework modeled seamless versus welded demand shares, hydrogen-grade certification penetration curves, and regional corridor buildout phasing. CAGRs derived from utility capital expenditure commitments and industrial hydrogen adoption timelines, with sensitivity testing around scrap price volatility and coating reformulation cost pass-through assumptions.
The model assumes a particular technology adoption path; alternative pathways for composite-reinforced line pipe in water networks would alter the outlook for steel demand trajectories. Forecasts reflect documented assumptions regarding EU Green Deal enforcement consistency and hydrogen purity standard harmonization across member states. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
Pipe Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Steel Roll-On Tube Market