
 Bicycle Safety Gear Market | 2026-2036
Bicycle Safety Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Safety Gear Market Analysis
The premium bicycle safety gear tier is consolidating around integrated MIPS systems and custom-fit retention mechanisms while commodity helmets compete on price-point penetration in mass retail. POC leverages Scandinavian design heritage and medical research partnerships to sustain margin premiums in competitive racing channels. Giro anchors North American specialty retail through deep category specialization in road and mountain bike helmets. Bell Helmets dominates price-accessible distribution through sporting goods retailers and big-box placement.
Bicycle safety gear encompasses protective equipment engineered to reduce traumatic injury risk during cycling activities, with helmets typically constructed from expanded polystyrene liners bonded to polycarbonate or ABS shells designed to absorb impact energy through controlled deformation. The primary commercial purpose spans consumer protection liability reduction, regulatory compliance for road use, and performance optimization across competitive and recreational disciplines. Helmets command the largest revenue share due to mandatory use laws in most developed jurisdictions while reflective wear represents the fastest-expanding category as urban commuting adoption rises and low-light visibility regulations tighten. Distribution through specialty stores captures the highest margin pool by bundling fitting services and premium brand curation whereas online retail is displacing sporting goods retailers for replacement purchases and accessory add-ons.
EN 1078 governs helmet construction and testing across European Union member states while the US Consumer Product Safety Commission enforces 16 CFR Part 1203 for bicycle helmet impact protection and retention system performance. These frameworks mandate minimum safety thresholds that filter substandard imports and create compliance cost barriers for new market entrants. Stakeholders must monitor evolving e-bike speed classifications in Germany and the Netherlands where helmet requirements may extend beyond traditional cycling parameters.
Market Dynamics
MIPS rotational impact technology and EN 1078 certification upgrades are compressing product development cycles while fragmenting competitive tiers between premium integrated systems and price-driven commodity helmets.
Growth Catalysts
- Urban Commuting Infrastructure:European cities including Amsterdam, Copenhagen, and Berlin are expanding protected cycling lanes and procurement programs for municipal fleet safety equipment.
- EN 1078 Certification Upgrades:Revised European testing protocols for rotational impact protection are accelerating replacement demand among safety-conscious consumers.
- E-Bike Speed Reclassification:German and Dutch regulators are reviewing helmet mandates for pedal-assist vehicles operating above 25 km/h thresholds.
Market Restraints
- Polycarbonate Shell Cost Volatility:Petrochemical feedstock fluctuations compress margins for ABS and polycarbonate-dependent manufacturers.
- Asian Supply Concentration:Expanded polystyrene liner production concentrates in Chinese and Taiwanese molding facilities, creating single-source vulnerability.
- Retention System Technical Limitations:Custom-fit mechanisms require precise anthropometric data that smaller brands lack resources to develop independently.
Strategic Opportunities
- Reflective Wear Category Expansion:Low-light visibility regulations in Denmark and Sweden are opening adjacent product development beyond traditional helmet markets.
- Specialty Retail Channel Integration:Fitting-service bundling with premium brand curation captures margin pools that online displacement cannot replicate.
- Medical Research Partnerships:Collaboration with trauma centers and biomechanics institutes differentiates concussion-reduction claims in competitive racing segments.
Industry Challenges
- Biomechanical Engineering Talent Scarcity:Specialized expertise in rotational impact modeling commands premium compensation that mid-tier manufacturers struggle to absorb.
- Multi-Jurisdiction Certification Timelines:Parallel EN 1078 and 16 CFR Part 1203 testing protocols extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Safety Gear Market |
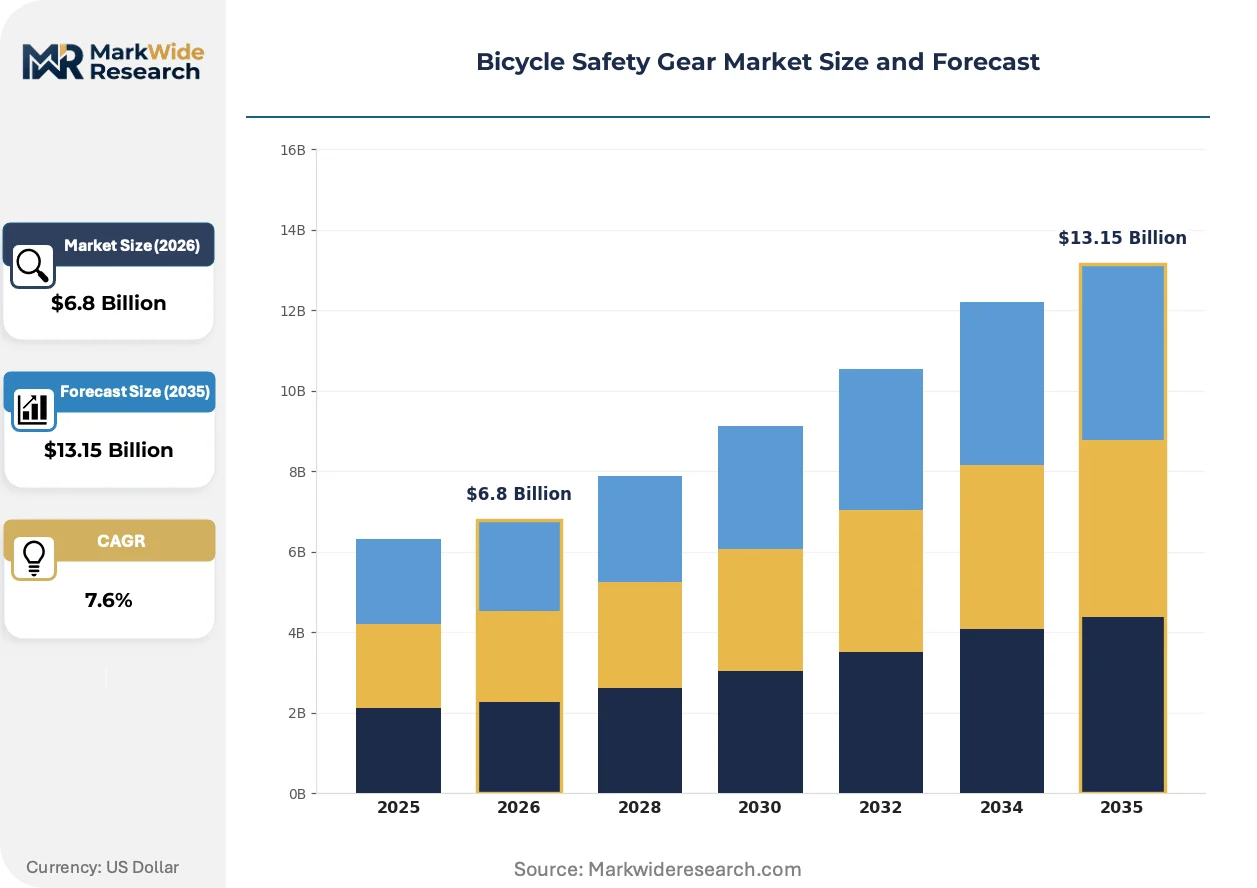
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Lights, Reflective Wear, Gloves Application: Commuting, Recreational Cycling, Competitive Racing, Mountain Biking Customer Type: Individuals, Schools, Cycling Clubs, Municipalities Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Retailers, Direct Sales |
| Companies Covered | Specialized, Bontrager, POC, Oakley, Smith Optics, Giro, Trek Bicycle, 100%, Bell Helmets, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Safety Gear Market Emerging Trajectories
Active safety systems are migrating from passive impact absorption toward predictive injury reduction, with sensor integration and material science advancing in parallel rather than sequential development cycles.
MIPS multi-directional impact protection is converging with custom-fit 3D scanning retention systems to create helmet architectures that adapt to individual cranial geometry rather than standardized sizing. Competitive cyclists and triathletes in Germany and the Netherlands are adopting these integrated platforms at rates exceeding recreational segments. This convergence is compressing the addressable market for generic fit systems while elevating R&D investment thresholds for category participation.
EU regulatory frameworks are tightening low-light visibility requirements through amendments to the Personal Protective Equipment Regulation, mandating minimum reflective surface areas for urban commuting gear. Manufacturers serving Dutch and Belgian municipal procurement programs must now certify garments to enhanced photometric standards. The reflective wear segment is responding with bonded retroreflective films that maintain breathability performance.
Replacement purchasing behavior is shifting toward direct-to-consumer channels for accessory add-ons while complex fitting requirements sustain specialty store relevance for initial helmet acquisitions. Urban commuters in Copenhagen and Stockholm demonstrate higher online repurchase rates for replacement visors and padding kits than road cycling enthusiasts. This bifurcation is forcing brands to maintain parallel distribution architectures with incompatible margin structures and inventory planning horizons.
Bicycle Safety Gear Market Segmentation
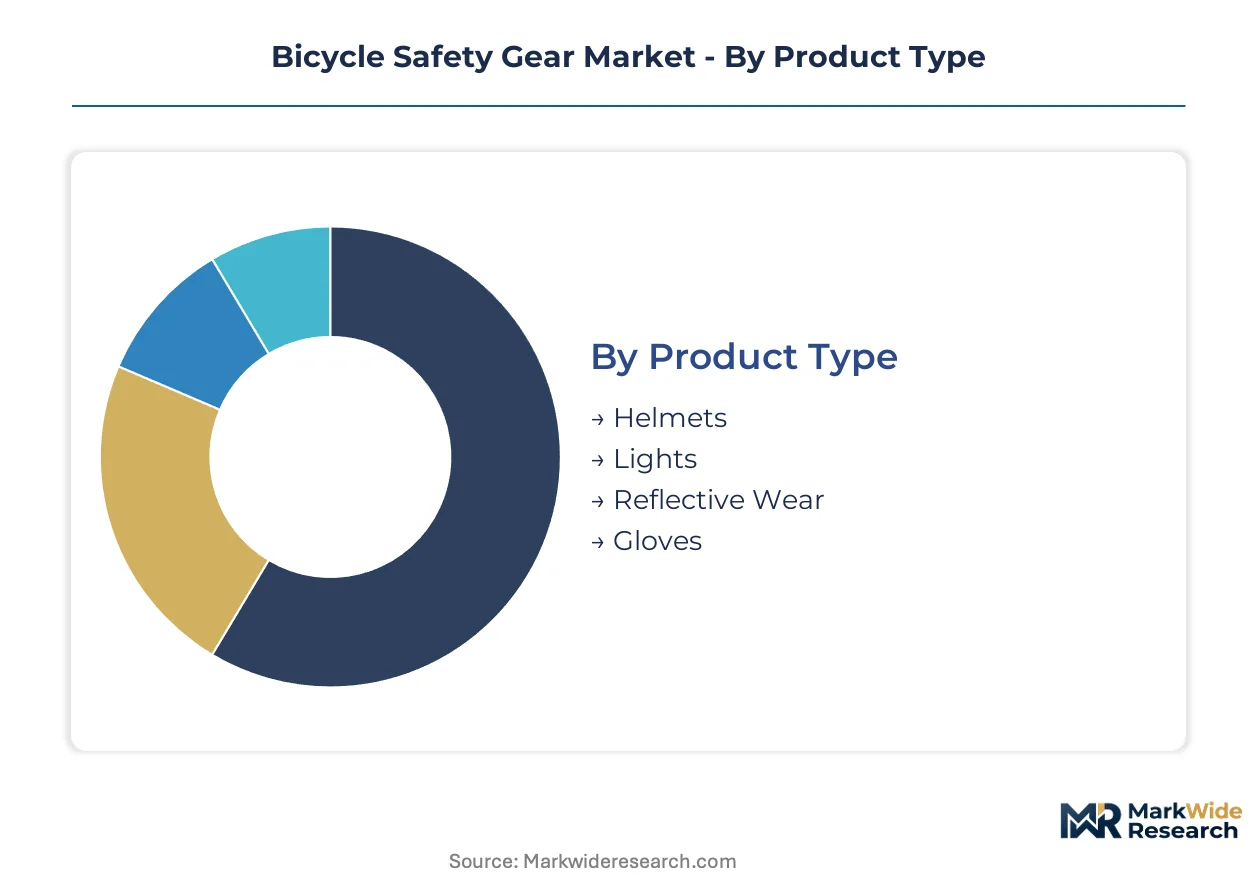
Segmentation in bicycle safety gear reveals distinct procurement patterns across product categories and buyer types. Helmets dominate revenue due to regulatory mandates, while reflective wear captures municipal fleet contracts. Distribution channel selection varies sharply between first-time purchasers seeking fitting services and replacement buyers prioritizing convenience.
Product Type:
Cost tier separates premium integrated systems from price-driven commodity alternatives in this category.
- Helmets:Expanded polystyrene liners bonded to polycarbonate shells absorb impact through controlled deformation. Germany, the Netherlands, and Denmark concentrate demand as helmet mandates expand with e-bike speed reclassifications. MIPS rotational impact systems command margin premiums in competitive racing channels.
- Reflective Wear:Bonded retroreflective films maintain breathability while meeting enhanced photometric standards under EU Personal Protective Equipment Regulation amendments. Municipal procurement programs in Copenhagen and Stockholm drive volume as low-light visibility requirements tighten for urban commuters.
- Lights:LED and laser diode systems address nighttime visibility gaps in cycling infrastructure.
- Gloves:Padded palm constructions reduce vibration fatigue and abrasion risk in mountain biking segments.
Helmets lead volumes today; reflective wear is gaining share fastest.
Application:
Volume concentration varies by discipline-specific equipment refresh cycles and safety regulation exposure.
- Commuting:Urban cyclists in Amsterdam, Berlin, and Copenhagen purchase helmet-reflective wear bundles through municipal subsidy programs. EN 1078 certification upgrades accelerate replacement demand among safety-conscious daily riders.
- Competitive Racing:Triathletes and road cyclists in Germany and the Netherlands adopt custom-fit 3D scanning retention systems at rates exceeding recreational segments. Medical research partnerships differentiate concussion-reduction claims in this margin-rich channel.
- Recreational Cycling:Weekend riders prioritize price accessibility over technical specification.
- Mountain Biking:Technical terrain demands full-face coverage and enhanced retention system performance.
Commuting anchors current volume; competitive racing delivers the steepest margin expansion trajectory.
Customer Type:
Procurement authority separates individual discretionary purchases from institutional tender processes.
- Individuals:Direct-to-consumer channels capture replacement purchases and accessory add-ons, while specialty stores retain initial helmet acquisition share due to fitting complexity. Online repurchase rates for replacement visors and padding kits run highest among urban commuters.
- Municipalities:Dutch and Belgian city governments mandate minimum reflective surface areas for fleet safety equipment, creating certified supplier lists that exclude non-compliant manufacturers. Procurement timelines extend twelve to eighteen months.
- Schools:Bulk helmet programs target youth cycling education initiatives.
- Cycling Clubs:Group purchasing concentrates volume for premium brand negotiations.
Individuals generate the highest transaction frequency; municipalities deliver the most predictable contract pipelines.
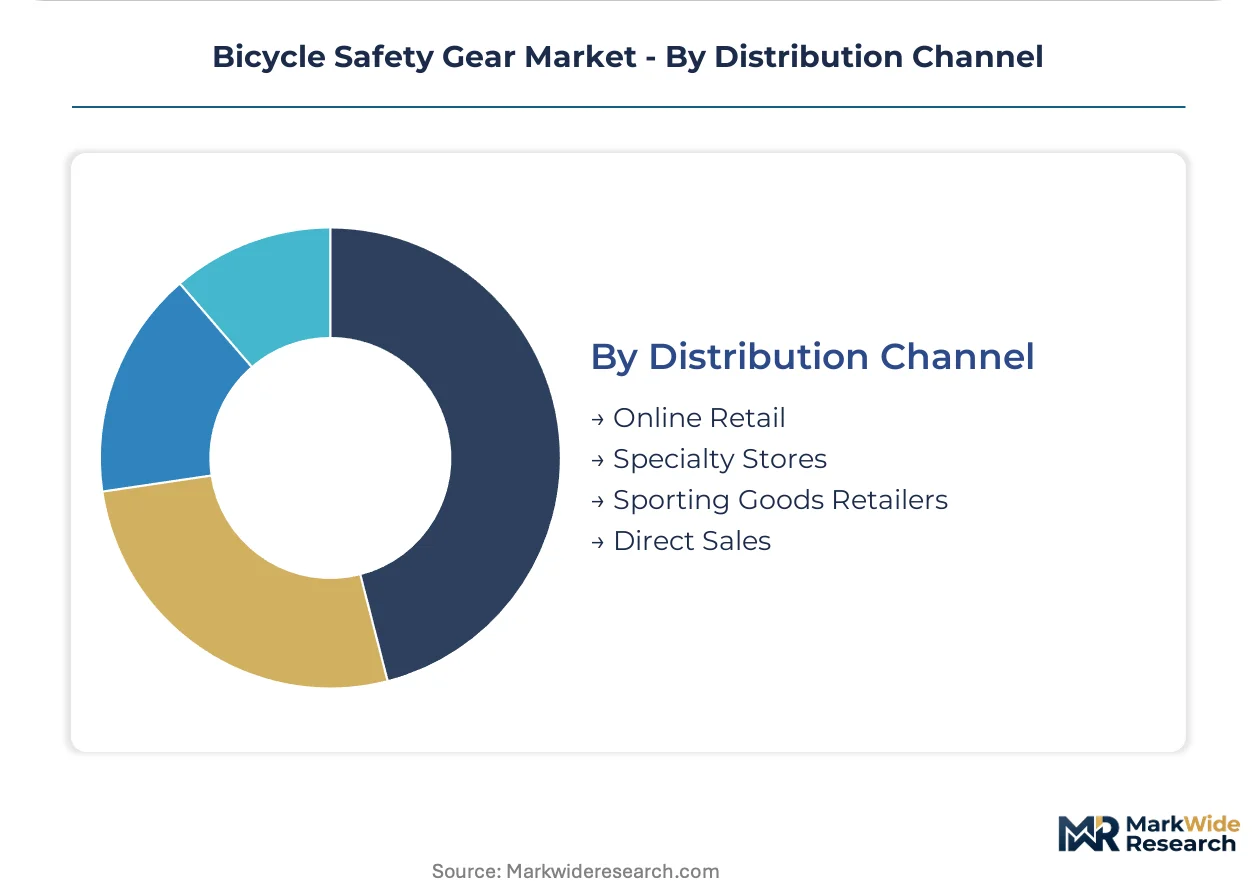
Distribution Channel:
Margin structure and inventory planning horizons force parallel architectures incompatible under single operational models.
- Specialty Stores:Fitting-service bundling with premium brand curation captures margin pools that online displacement cannot replicate. Road and mountain bike enthusiasts in North American and European markets demonstrate persistent channel loyalty for complex retention system adjustments.
- Online Retail:Direct-to-consumer platforms displace sporting goods retailers for replacement purchases and accessory add-ons. Urban commuters in Scandinavian markets demonstrate higher digital repurchase rates for standardized sizing categories.
- Sporting Goods Retailers:Big-box placement prioritizes price-accessible SKUs over technical specification depth.
- Direct Sales:Manufacturer-owned channels serve institutional and team contract accounts.
Specialty stores retain premium positioning; online retail is expanding most quickly in replacement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the Netherlands diverge in regulatory ambition despite shared cycling infrastructure density, with Dutch municipal procurement programs outpacing German federal standard-setting in reflective wear mandates.
Germany
E-bike speed reclassification debates and EN 1078 certification upgrades drive helmet replacement cycles among safety-conscious commuters. The country's national transport regulator reviews mandatory helmet thresholds for pedal-assist vehicles exceeding 25 km/h. Berlin anchors municipal fleet procurement, with city authorities bundling reflective wear into cycling infrastructure subsidies.
Netherlands
Amsterdam and Rotterdam expand protected lane networks while mandating minimum reflective surface areas for urban commuting gear. Dutch municipal procurement programs create certified supplier lists that exclude non-compliant manufacturers. The Randstad metropolitan cluster concentrates demand for integrated helmet-retention systems among competitive racing segments.
Denmark
Copenhagen's cycling infrastructure investment sustains premium safety gear penetration rates among daily commuters. Enhanced photometric standards under EU Personal Protective Equipment Regulation amendments tighten certification requirements for reflective garments. The Øresund region links Danish procurement patterns with Swedish municipal fleet standardization.
United States
North American specialty retail channels retain loyalty among road and mountain bike enthusiasts seeking complex fitting services. The US Consumer Product Safety Commission enforces 16 CFR Part 1203 for impact protection and retention system performance. California and Colorado metropolitan clusters concentrate demand for custom-fit 3D scanning retention platforms.
Sweden
Stockholm demonstrates higher online repurchase rates for replacement visors and padding kits than comparable European markets. Low-light visibility regulations accelerate reflective wear category expansion beyond traditional helmet markets. Scandinavian design heritage clusters in Gothenburg sustain margin premiums through medical research partnerships.
Bicycle Safety Gear Market Vendor Landscape
Top-tier vendors anchor premium integrated systems, while commodity manufacturers compete on price-point penetration through sporting goods and big-box retail channels. The market structures around three tiers: MIPS-integrated premium specialists, mid-market EN 1078-certified brands, and price-driven mass-market suppliers. Dominant competitive moves include medical research partnerships for concussion-reduction differentiation and specialty retail fitting-service bundling to defend margin pools against online displacement.
Within the Scandinavian design heritage tier, POC exemplifies premium positioning through medical research partnerships. Giro and Bell Helmets occupy distinct channel positions, with the former anchoring specialty retail specialization and the latter representing price-accessible distribution scale. These three vendors illustrate how geographic origin and channel strategy stratify competitive positioning without overlapping addressable segments.
| Leading Market Players |
|---|
| Specialized |
| Bontrager |
| POC |
| Oakley |
| Smith Optics |
| Giro |
| Trek Bicycle |
| 100% |
| Bell Helmets |
| Others |
Supply Flow & Price Mechanics
Biomechanical engineering talent scarcity in Sweden and Germany widens pricing spreads between MIPS-integrated premium helmets and commodity alternatives, as labor-cost differentials in rotational impact modeling expertise translate directly into tiered product positioning.
Pricing Analysis
Bundled fitting-service premiums separate specialty retail from unbundled online replacement purchases in this market. Three-tier pricing structure across premium MIPS-integrated, standard EN 1078-certified, and economy non-certified levels reflects certification grade and after-sales service intensity. Pricing pressure stems from polycarbonate shell cost volatility feeding commodity-tier margin compression. Municipal procurement programs demonstrate lowest price sensitivity; mass-market recreational cyclists exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with expanded polystyrene liner production concentrated in Chinese and Taiwanese molding facilities. Raw material dependencies center on petrochemical feedstocks for polycarbonate and ABS shells, plus MIPS rotational impact system licensing. Supply chain risk manifests as tariff exposure on Asian-sourced components entering European and North American assembly plants. Distribution runs through specialty stores for initial helmet acquisitions, direct-to-consumer platforms for replacement accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with EN 1078 certification upgrades and e-bike speed reclassifications in Germany and the Netherlands generating replacement demand cycles that outpace organic growth.
For Market Incumbents: Anticipate margin compression from Asian commodity manufacturers by deepening MIPS licensing partnerships and securing exclusive specialty retail fitting-service contracts. Certification investment in enhanced photometric standards for reflective wear represents a defensible lever against price-driven entrants.
For New Entrants and Emerging Players: Municipal procurement specialists offer the most accessible channel partnership for bypassing established brand loyalty, with Dutch and Belgian city governments maintaining open certified supplier lists for reflective wear contracts. Target white-space in custom-fit 3D scanning retention systems for competitive racing segments where medical research partnerships differentiate premium positioning.
For Investors and Strategic Acquirers: Cycling apparel conglomerates are the most active acquirer in this space, seeking helmet technology integration for full-gear ecosystem bundling. Acquisition candidates with captive MIPS licensing and Scandinavian design heritage command sustainable premium multiples. Watch e-bike speed reclassification rulings in Germany as the inflection signal for helmet mandate expansion beyond traditional cycling parameters.
| Strategic Initiative | Industry Significance |
|---|---|
| MIPS Licensing Partnership | Secures rotational impact technology access for premium tier participation against unlicensed competitors. |
| Medical Research Collaboration | Differentiates concussion-reduction claims in competitive racing channels through trauma center validation. |
| Municipal Procurement Certification | Unlocks Dutch and Belgian city fleet contracts under enhanced photometric PPE standards. |
| Specialty Retail Integration | Captures fitting-service margin pools that online displacement cannot replicate in initial acquisitions. |
| 3D Scanning Retention Development | Addresses custom-fit demand from German and Dutch triathletes exceeding recreational adoption rates. |
Methodological Framework
Bottom-up commuter and competitive cyclist demand modeling reconciled against top-down helmet and reflective wear production tracking forms the analytical core of this study. Primary interviews with product development directors at MIPS-integrated specialists, EN 1078 certification auditors, municipal procurement officers in Amsterdam and Copenhagen, and specialty retail category managers combined with secondary validation from EU PPE regulation amendments, US CPSC enforcement records, customs trade data for polycarbonate shell imports, and SEC filings from publicly traded cycling gear manufacturers.
Historical trendline analysis of replacement purchase cycles and municipal fleet refresh patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type tier, application discipline, customer procurement authority, and distribution channel architecture. CAGRs derived from fitted growth curves incorporating e-bike speed reclassification policy scenarios and EN 1078 upgrade adoption rates.
Revisions become necessary when regulatory timelines for helmet mandate expansion or petrochemical feedstock disruption materialize outside modeled parameters. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market