
 Hearing Protection Products Market | 2026-2036
Hearing Protection Products Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Protection Products Market Insights
ANSI S3.19-1974 certification-tier upgrades across industrial portfolios is unwinding legacy procurement patterns in hearing protection. 3M leverages captive acoustic testing laboratories to sustain premium positioning in oil and gas contracts. Honeywell International Inc. anchors North American distribution through safety supply house partnerships. Moldex-Metric Inc. differentiates via disposable foam earplug manufacturing scale across European automotive plants.
Hearing protection products are personal protective equipment designed to attenuate acoustic energy transmission through passive absorption materials or active noise cancellation circuitry, typically rated by Noise Reduction Ratio values between 15 and 33 decibels for occupational compliance. Their primary commercial purpose is preventing noise-induced hearing loss in environments exceeding 85 decibels time-weighted average. Earmuffs command the largest revenue share in manufacturing applications where reusable protocols reduce long-term procurement costs. Earplugs represent the fastest-expanding category in construction due to compatibility with hard hats and respiratory equipment. Noise-cancelling headphones capture emerging margin pools among musicians and audio professionals seeking flat-frequency attenuation.
OSHA enforces 29 CFR 1910.95 hearing conservation programs mandating baseline audiometric testing and engineering controls above 85 decibels, directly expanding employer expenditure on compliant devices. The EU PPE Regulation 2016/425 requires CE-marked hearing protection with documented attenuation performance, creating market access barriers for uncertified imports. ISO 4869-1 standardization of real-ear attenuation testing shapes product development roadmaps for multinational suppliers. Stakeholders must monitor how emerging ototoxicant exposure guidelines integrate hearing protection into broader chemical safety protocols.
Market Dynamics
OSHA's 2023 enforcement surge on 29 CFR 1910.95 compliance is forcing construction and manufacturing employers to replace legacy hearing conservation programs with certified PPE procurement systems. This regulatory pressure is compressing sales cycles and elevating ANSI S3.19-1974 certification from optional specification to mandatory bid threshold.
Growth Catalysts
- EU PPE Regulation 2016/425:CE-marking mandates for attenuation documentation are filtering out uncertified imports across German and French industrial supply chains.
- Active noise cancellation circuitry:Musicians and audio engineers in recording studios are adopting flat-frequency attenuation headphones for precise monitoring environments.
- Oil and gas sector concentration:Extraction operations in the Permian Basin and North Sea are procuring premium earmuffs with integrated two-way radio compatibility.
Market Restraints
- Acoustic foam supply concentration:Polyurethane foam production clusters in China create input cost volatility for disposable earplug manufacturers.
- Real-ear attenuation testing limitations:ISO 4869-1 laboratory requirements block rapid product iteration for smaller suppliers lacking captive acoustic facilities.
- Substitution by engineering controls:Enclosure and dampening investments in automotive plants reduce per-worker PPE unit requirements.
Strategic Opportunities
- India's manufacturing expansion:PLI scheme beneficiaries in electronics assembly are establishing first-time hearing conservation programs without legacy vendor relationships.
- Ototoxicant exposure guidelines:Emerging OSHA integration of chemical and noise hazards creates bundled safety procurement opportunities.
- Direct-to-employer digital platforms:Safety supply aggregators are bypassing traditional distribution houses to capture mid-market construction contracts.
Industry Challenges
- Audiometric technician certification gaps:Baseline testing requirements under OSHA 29 CFR 1910.95 outpace qualified service provider availability in rural construction markets.
- Multi-standard compliance timelines:Simultaneous ANSI S3.19-1974, CE marking, and ISO 4869-1 certification extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Protection Products Market |
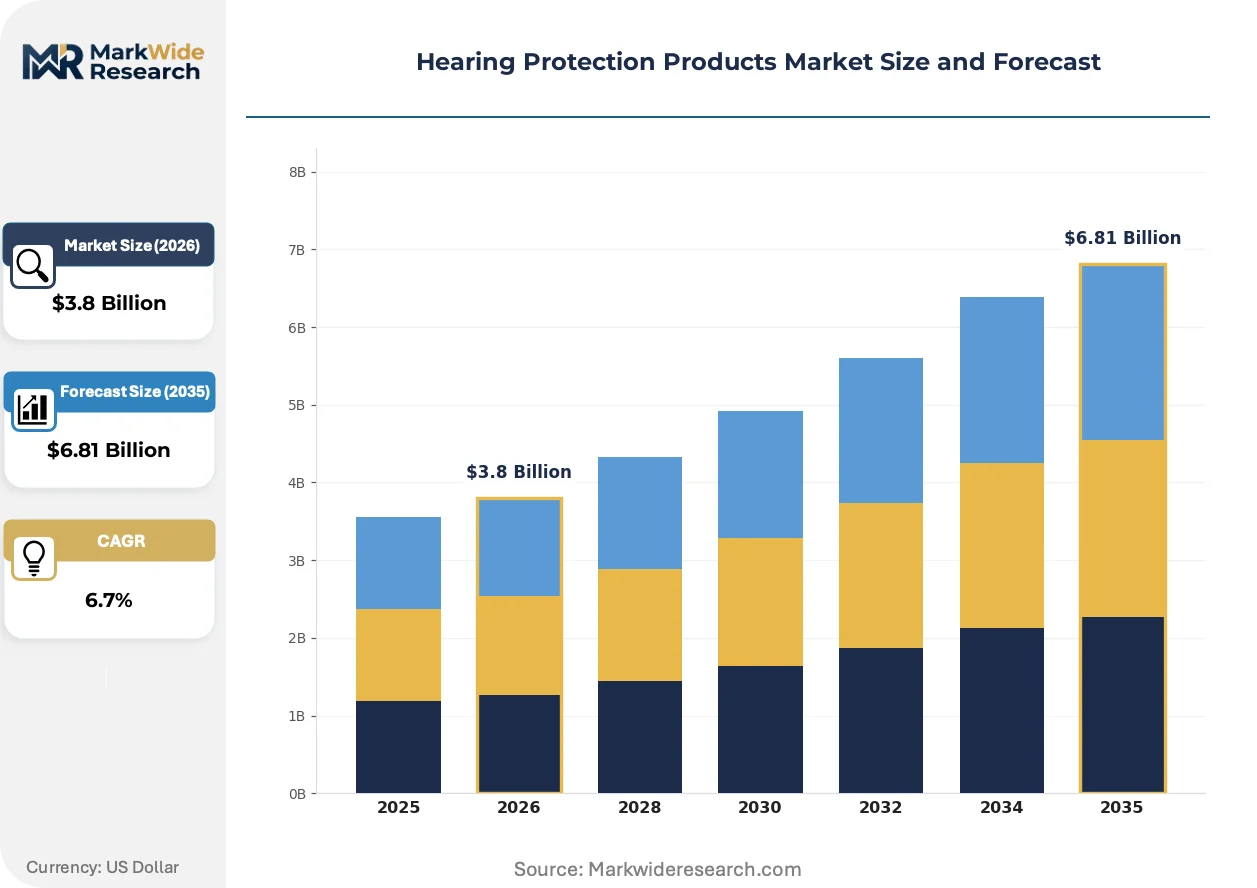
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Earmuffs, Earplugs, Semi-Inserts, Noise-Cancelling Headphones Application: Construction, Manufacturing, Entertainment, Sports End User: Workers, Musicians, Athletes, Consumers Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | 3M, Honeywell International Inc., Moldex-Metric Inc., MSA Safety Incorporated, Radians Inc., UVEX Safety Group, Etymotic Research Inc., Alpine Hearing Protection, Dynamic Ear Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Protection Products Market Trends and Innovations
Digital acoustic processing is penetrating hearing protection architectures, converting passive attenuation devices into sensor-equipped workplace safety nodes. This convergence of audio engineering and industrial IoT is redefining product value propositions beyond decibel reduction.
Bluetooth-enabled earmuffs with environmental monitoring microphones are displacing conventional passive earmuffs in high-communication manufacturing environments. Automotive assembly plants in Stuttgart and Detroit are deploying these units to preserve situational awareness without removing protection. The technology is displacing two-device protocols where workers previously alternated between protection and radio headsets.
REACH restrictions on isocyanates in polyurethane foams are compelling European earplug manufacturers to reformulate absorption materials. The ECHA regulatory pressure is accelerating bio-based polymer adoption in disposable product lines. German automotive suppliers are qualifying cellulose-derived alternatives ahead of 2025 substance restriction deadlines.
Employer purchasing is consolidating through integrated safety management platforms that bundle hearing protection with respiratory and fall protection SKUs. Construction contractors in Texas and Alberta are migrating from item-level procurement to annual spend agreements with single-source distributors. This shift is visible most acutely in mid-market building trades where procurement staff lack bandwidth for multi-vendor management.
Hearing Protection Products Market Segmentation
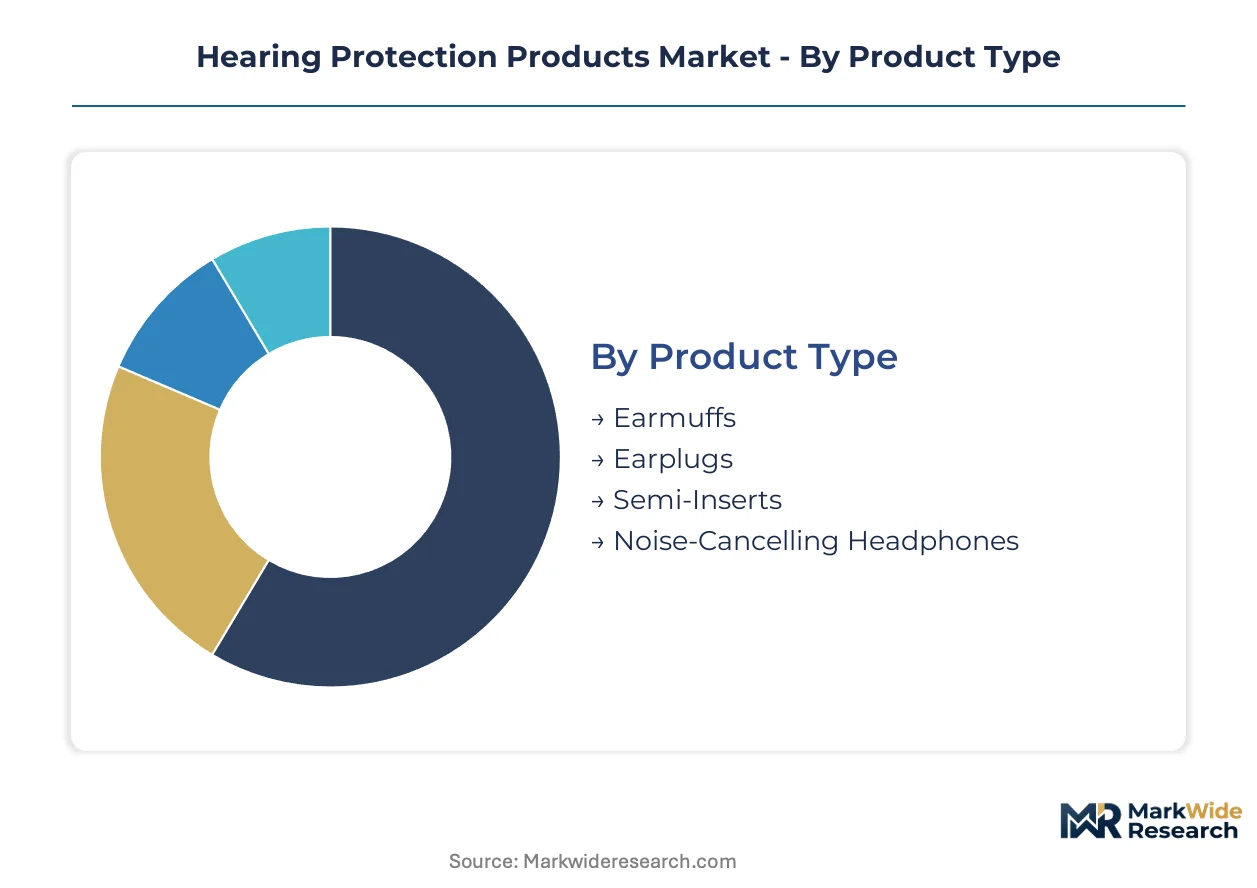
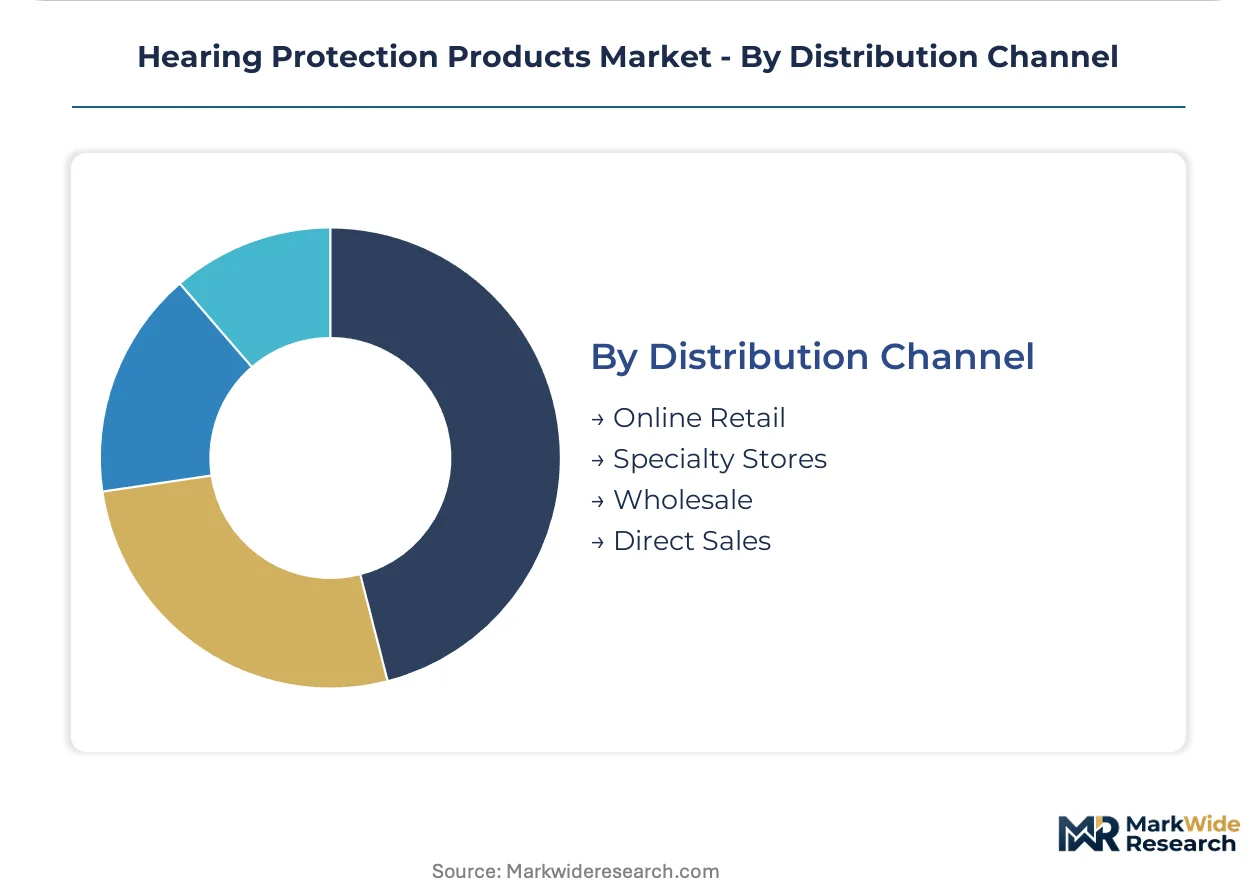
Hearing protection procurement channels diverge sharply between industrial bulk contracts and individual consumer purchases. Channel economics dictate margin structures, certification requirements, and inventory turnover velocities across each segment cluster.
Product Type:
Industrial supply houses stock earmuffs and earplugs in volume tiers, while noise-cancelling headphones flow through pro-audio retailers and direct-to-consumer platforms.
- Earmuffs:Rigid cup-and-band assemblies with foam or liquid-filled cushions achieving NRR ratings up to 33 decibels. Manufacturing plants in Stuttgart and Detroit specify reusable earmuffs for eight-hour shift compliance under OSHA 29 CFR 1910.95. Integrated two-way radio compatibility commands premium positioning in oil and gas extraction contracts.
- Earplugs:Cylindrical or tapered foam inserts manufactured through polyurethane expansion or slow-recovery polymer processes. Construction contractors in Texas and Alberta procure disposable foam earplugs in pallet quantities through safety supply aggregators. Compatibility with hard hats and respiratory equipment drives specification over earmuffs in confined workspaces.
- Semi-Inserts:Band-style devices with pod tips resting at ear canal entrance. Metal fabrication shops favor these for intermittent protection needs.
- Noise-Cancelling Headphones:Active circuitry with environmental microphones and digital signal processing for flat-frequency attenuation. Recording studios in Nashville and London specify these for musician monitoring.
Earmuffs dominate installed base. Earplugs are where expansion concentrates.
Application:
Cost tier stratification separates premium certified PPE from consumer-grade recreational products across end-use environments.
- Construction:Heavy-civil and building trades generate the highest unit volumes for disposable protection. OSHA enforcement surges in 2023 compressed procurement cycles, elevating ANSI S3.19-1974 certification to mandatory bid threshold status. Contractors bundle hearing protection with fall protection and respiratory SKUs under annual spend agreements.
- Manufacturing:Automotive assembly and metal fabrication operations specify reusable earmuffs with communication integration. German plants under EU PPE Regulation 2016/425 require CE-marked attenuation documentation.
- Entertainment:Live music venues and recording studios demand flat-response attenuation preserving audio fidelity. Musicians in Nashville and London drive specification.
- Sports:Shooting ranges and motorsports applications specify high-NRR disposable or reusable options. Consumer retail channels dominate.
Manufacturing commands revenue concentration. Construction is climbing the fastest.
End User:
Volume scale separates industrial procurement from individual purchasing patterns and decision-making authority.
- Workers:Employers mandate and fund protection under hearing conservation programs. Rural construction markets face audiometric technician certification gaps.
- Musicians:Self-directed procurement through pro-audio retailers with flat-frequency requirements.
- Athletes:Shooting and motorsports participants purchasing through specialty retailers.
- Consumers:Online retail and big-box channels for recreational noise exposure.
Workers represent the volume anchor. Musicians are gaining share fastest.
Distribution Channel:
Supply concentration shapes pricing power and certification enforcement across channel tiers.
- Online Retail:Direct-to-consumer platforms and safety supply aggregators bypass traditional distribution houses. Mid-market construction contractors migrate here for procurement efficiency.
- Specialty Stores:Pro-audio retailers serve musicians and recording engineers with flat-attenuation specifications.
- Wholesale:Industrial supply houses anchor North American distribution through safety supply house partnerships.
- Direct Sales:Premium earmuff manufacturers with captive acoustic laboratories serve oil and gas majors directly.
Wholesale holds installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of certified hearing protection concentrate from German and US manufacturing bases toward industrializing Asian markets. Import dependence for acoustic foam inputs creates cost volatility for European disposable earplug producers. Regulatory divergence between OSHA and EU PPE frameworks shapes cross-border product adaptation requirements.
United States
Construction sector procurement surged following OSHA's 2023 enforcement surge on 29 CFR 1910.95 compliance. The Department of Labor mandates baseline audiometric testing and engineering controls above 85 decibels, expanding employer expenditure on ANSI S3.19-1974 certified devices. Texas and Alberta contractors bundle hearing protection with fall protection under annual spend agreements.
Germany
Industrial contracts concentrate under stricter EU PPE Regulation 2016/425 enforcement, filtering uncertified imports from supply chains. ECHA REACH restrictions on isocyanates in polyurethane foams accelerate bio-based polymer adoption. Stuttgart automotive plants deploy Bluetooth-enabled earmuffs with environmental monitoring microphones to preserve situational awareness.
China
Polyurethane foam production clusters create input cost volatility for disposable earplug manufacturers serving export markets. MIIT standards and GB certification requirements shape domestic product specifications. Yangtze River Delta manufacturing hubs supply acoustic materials to European and North American converters.
India
PLI scheme beneficiaries in electronics assembly establish first-time hearing conservation programs without legacy vendor relationships. BIS certification requirements for industrial safety equipment create compliance entry barriers. Gujarat and Maharashtra industrial corridors drive specification for CE-marked attenuation documentation in automotive supply chains.
United Kingdom
Post-Brexit regulatory alignment pressures create dual certification burdens for suppliers serving EU and domestic markets. The Health and Safety Executive enforces Control of Noise at Work Regulations 2005 with exposure action values at 80 and 85 decibels. Midlands manufacturing clusters specify reusable earmuffs for metal fabrication operations.
Hearing Protection Products Market Competitive Landscape
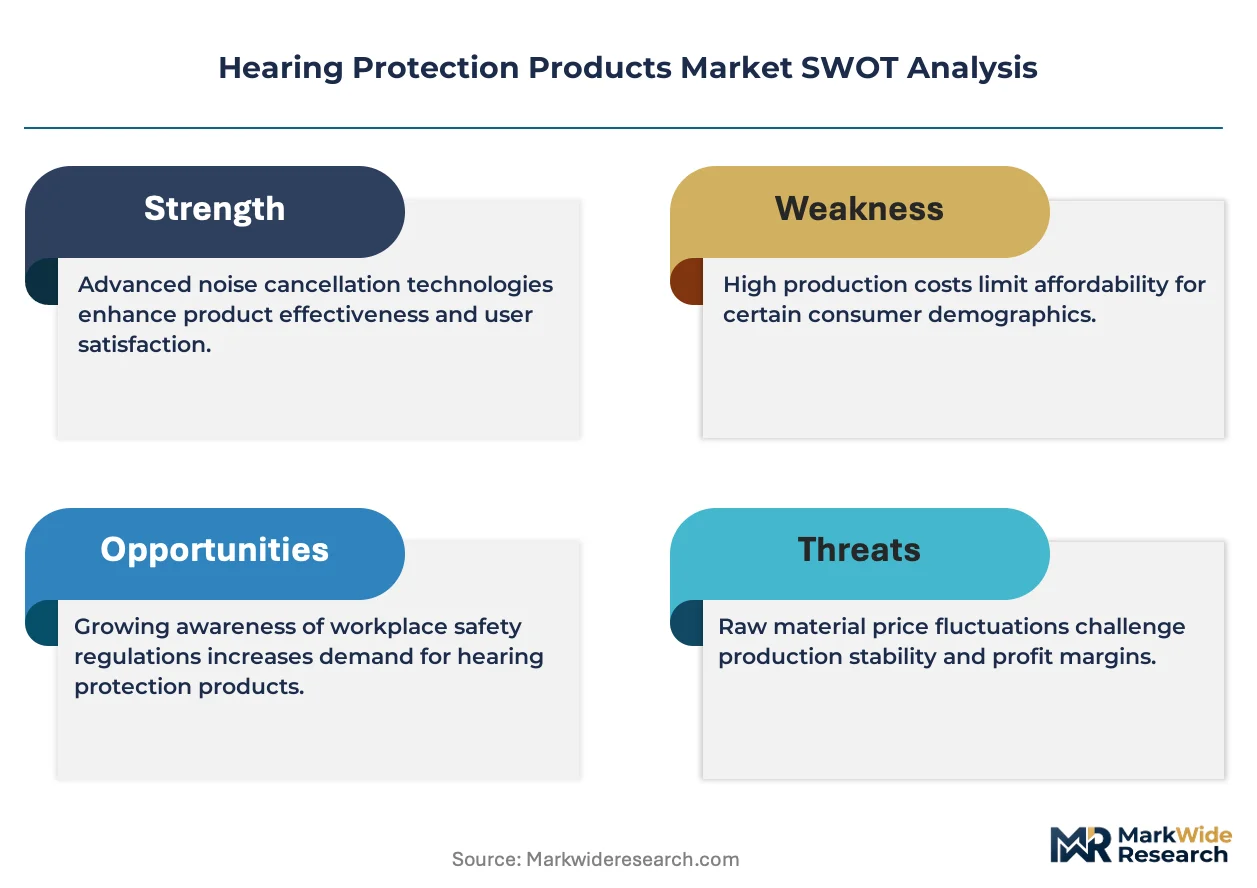
Listed leaders compete with private specialists across certification-tier positioning in hearing protection. The vendor base separates into scale-driven diversified industrials, acoustic-testing laboratories with captive facilities, and regional foam-conversion specialists. Three archetypes dominate: premium-tier integrated manufacturers, mid-market distribution-anchored suppliers, and disposable-product volume players. Competitive moves concentrate on M&A for acoustic laboratory assets and backward integration into foam formulation.
Within the premium-tier integrated segment, 3M and Honeywell International Inc. exemplify diversified industrials with captive testing infrastructure. MSA Safety Incorporated occupies a position among safety-systems consolidators with distribution depth in North American industrial supply houses. These three represent contrasting scale strategies: laboratory-led premium positioning, supply-house partnership anchoring, and integrated safety portfolio bundling.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Moldex-Metric Inc. |
| MSA Safety Incorporated |
| Radians Inc. |
| UVEX Safety Group |
| Etymotic Research Inc. |
| Alpine Hearing Protection |
| Dynamic Ear Company |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety day lead times for ANSI-certified earmuffs from captive acoustic laboratories concentrate pricing power with integrated manufacturers holding in-house testing facilities, while construction buyers face compressed procurement cycles under tightened OSHA enforcement windows.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across premium, standard, and economy tiers. Price differentiation rests on certification grade—ANSI S3.19-1974 versus baseline CE marking—and volume scale commitments from automotive assembly plants. Cost compression in disposable foam earplugs is intensifying because polyurethane foam feedstock volatility from Yangtze River Delta clusters transmits directly to converter margins. Mid-market construction contractors exhibit highest price sensitivity, while oil and gas majors purchasing integrated communication earmuffs show lowest elasticity.
Supply Chain Analysis
Port congestion on transpacific lanes elevates inbound logistics costs for European converters sourcing acoustic foam from China. Supply concentrates in China for polyurethane foam substrates, Germany for precision-molded cup assemblies, and the United States for active noise cancellation circuitry. Raw material dependencies include isocyanate-based foams facing ECHA REACH restrictions, liquid-filled cushion polymers, and rare-earth magnets for speaker drivers. Single-source vulnerability runs through Yangtze River Delta foam production clusters. Distribution runs through industrial supply houses anchoring North American bulk procurement, with safety supply aggregators capturing mid-market migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering controls and enclosure investments threaten to displace per-worker PPE unit requirements, forcing incumbents to defend substitution-driven volume erosion through embedded technology differentiation.
For Market Incumbents: Fortify captive acoustic testing infrastructure against ISO 4869-1 certification bottlenecks that block rapid product iteration for smaller competitors. Deepen backward integration into foam formulation to mitigate isocyanate supply restrictions under ECHA REACH deadlines. Anchor channel control through integrated safety management platforms bundling hearing protection with respiratory and fall protection SKUs. For New Entrants and Emerging Players: Audiometric technician certification gaps in rural construction markets offer service-layer white space where incumbents under-serve baseline testing requirements under OSHA 29 CFR 1910.95. India's PLI scheme electronics assembly corridors present penetrable geography without legacy vendor entrenchment. Pursue direct-to-employer digital platform go-to-market angles bypassing traditional distribution houses. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrials seeking to divest non-core PPE portfolios amid safety-systems consolidation. Long-term viability hinges on acoustic laboratory asset scarcity and certification-tier positioning rather than commodity foam conversion scale. Monitor ototoxicant exposure guideline integration as inflection signal for bundled chemical-noise safety procurement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Acoustic Laboratory Acquisition | ISO 4869-1 testing infrastructure accelerates ANSI certification cycles for oil and gas contracts. |
| Bio-Based Polymer Formulation Partnership | Cellulose-derived alternatives ahead of ECHA 2025 isocyanate restrictions secure European automotive supply. |
| Integrated Safety Platform Integration | Bundled hearing-respiratory-fall protection SKUs captures mid-market construction procurement consolidation. |
| Bluetooth Communication Module Development | Two-way radio compatibility commands premium positioning in Permian Basin extraction operations. |
| Direct-to-Employer Digital Channel Launch | Safety supply aggregators bypass wholesale distribution to capture Texas and Alberta annual spend agreements. |
Research Methodology
Operator-level perspectives from safety procurement managers at construction contractors, audiometric technicians, industrial supply house category buyers, and EHS directors at automotive plants anchored the qualitative base. These interviews combined with secondary validation from OSHA enforcement databases, EU PPE Regulation 2016/425 certification registries, ECHA substance restriction filings, and customs trade flows for acoustic foam inputs. Bottom-up unit economics from disposable earplug pallet pricing and top-down industrial safety spend estimates were triangulated to constrain value outputs.
Sensitivity analysis across the projection horizon tested volume and price assumptions against regulatory enforcement intensity and raw material cost scenarios. Segmentation dimensions modeled include product architecture—passive foam, passive earmuff, active cancellation—application environment, certification tier, and procurement channel structure. CAGRs were derived from fitted growth curves anchored to baseline industrial safety expenditure and enforcement-driven replacement cycle compression. Industry-specific inputs included OSHA inspection frequency trends and EU PPE framework implementation timelines.
Forecasts assume regulatory continuity in OSHA 29 CFR 1910.95 and EU PPE Regulation 2016/425 regimes; material policy shifts would require re-modeling. Specific risk factors include REACH substance restriction acceleration, engineering control substitution thresholds, and audiometric service provider capacity constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market