
 Global Locker Market | 2026-2036
Global Locker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Locker Market Outlook
Leasing and asset-light deployment models are reshaping how locker operators scale without heavy balance-sheet exposure. ASSA ABLOY leverages its access-control heritage to dominate electronic locker installations across Nordic commercial properties. Cleveron sustains technology leadership in automated parcel handoff systems for grocery and pharmacy chains. Penco Products anchors its position through manufacturing scale in metal athletic lockers for U.S. educational institutions.
A locker is an enclosed storage compartment, typically fabricated from cold-rolled steel, high-density polyethylene, or engineered wood composites, with standardized dimensions ranging from 12 to 18 inches in width and 60 to 72 inches in height, designed to secure personal or commercial goods through mechanical, electronic, or biometric locking mechanisms. Electronic lockers command expanding margin pools as enterprises replace legacy key systems with networked access platforms that integrate building management software. Free-standing lockers retain volume dominance in gym and school applications where installation flexibility outweighs space optimization. Metal construction still occupies the largest material share, though composite formulations are gaining traction in corrosive environments such as coastal airports and pool facilities.
The U.S. Department of Transportation and FAA influence locker specifications in airport terminals through fire-safety and accessibility mandates, while the EU AI Act and GDPR shape data-handling protocols for biometric-enabled electronic units. China's SAMR enforces GB standards for smart locker electromagnetic compatibility and consumer data protection in public deployments. Stakeholders must monitor how fragmented national cybersecurity certifications fragment product platform standardization and force regional configuration strategies.
Market Dynamics
Parcel locker networks are consolidating around IoT-enabled access platforms as last-mile logistics operators seek density without real estate ownership, compressing deployment timelines and forcing hardware-software bundling in procurement contracts.
Growth Catalysts
- EU AI Act biometric mandates:Public transit authorities across Germany and France must upgrade to fingerprint or facial-recognition lockers by 2026, creating replacement demand for legacy keypad units.
- E-commerce fulfillment corridors:China's SAMR-enforced smart locker standards for electromagnetic compatibility are accelerating platform standardization in high-volume urban clusters.
- Metal-to-composite substitution:Coastal airports in Japan and Australia are specifying HDPE formulations to resist salt corrosion, expanding material supplier pools beyond traditional steel fabricators.
Market Restraints
- Cold-rolled steel price volatility:Input cost swings from Turkish and Indian mills are squeezing margin structures for metal locker OEMs serving educational and athletic segments.
- Biometric module supply concentration:Fingerprint sensor fabrication concentrates in South Korean and Taiwanese foundries, exposing locker assemblers to single-source risk.
- GDPR data-localization friction:EU member states impose divergent server-location requirements for biometric data, fragmenting software architectures and delaying multi-country rollouts.
Strategic Opportunities
- India metro expansion:Delhi, Mumbai, and Bengaluru transit authorities are tendering for 50,000+ smart locker units without incumbent vendor relationships, creating first-mover windows.
- Pharmacy cold-chain integration:Temperature-controlled lockers with IoT monitoring are penetrating Japan's aging-care pharmacy networks, merging parcel handoff with clinical compliance.
- CE marking cybersecurity addendum:New EU harmonized standards for connected device resilience are creating certification-based differentiation for early-compliant hardware platforms.
Industry Challenges
- Embedded systems firmware talent:Shortage of engineers fluent in both biometric authentication protocols and building management system APIs is extending integration timelines by 4-6 months.
- Multi-jurisdiction certification stacking:Locker platforms must sequentially clear FAA fire-safety rules, SAMR electromagnetic standards, and GDPR data protocols before unified product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Locker Market |
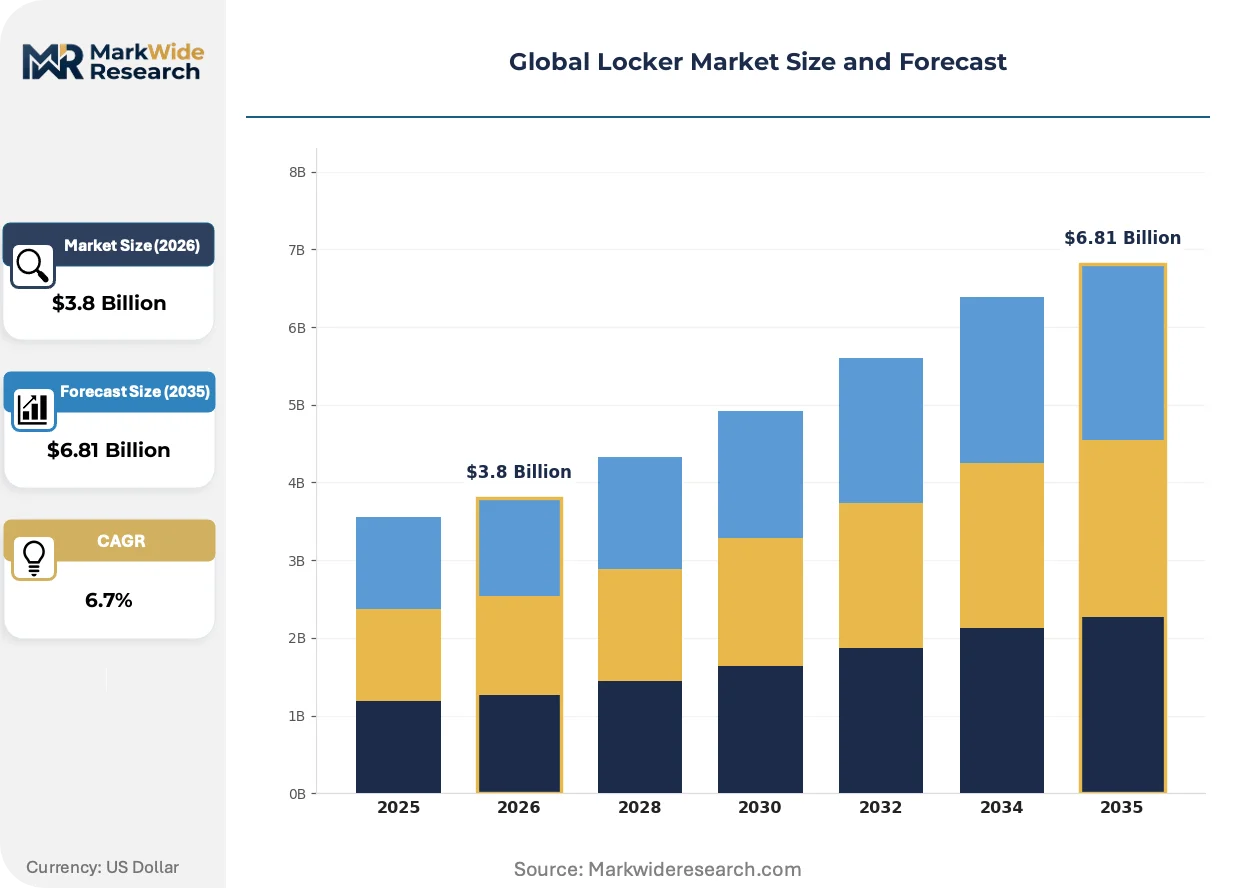
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted Lockers, Free-Standing Lockers, Electronic Lockers, Combination Lockers End User: Schools, Gyms, Offices, Airports Material: Metal, Plastic, Wood, Composite Size: Small, Medium, Large, Extra Large |
| Companies Covered | Salsbury Industries, Ricoh, ASSA ABLOY, American Locker, Cleveron, Pitney Bowes, Penco Products, Hollman, Quadient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Locker Market Strategic Shifts
Hardware-software decoupling is accelerating as locker operators demand API-first platforms that slot into existing enterprise IT stacks rather than standalone siloed systems.
Biometric access control is migrating from standalone fingerprint modules to multi-modal systems combining facial recognition, palm-vein scanning, and mobile credential verification. Nordic commercial property managers are piloting these platforms in mixed-use developments. This convergence is compressing the addressable market for single-mode hardware suppliers and forcing consolidation among sensor vendors.
The EU AI Act's risk-classification framework for biometric systems is compelling locker manufacturers to implement algorithmic audit trails and human-in-the-loop override protocols. Industrial consequence includes mandatory third-party conformity assessments for high-risk deployments. Airport and healthcare segments in Germany, France, and the Netherlands are front-loading compliance investments to secure early-mover certification advantages.
Asset-light leasing structures are displacing capital purchase models in corporate and educational procurement. Facility management providers in the United States and United Kingdom are bundling locker access into workspace-as-a-service contracts rather than owning depreciating hardware. This shift concentrates purchasing authority with national facilities integrators and compresses manufacturer margins through volume aggregation.
Global Locker Market Segmentation
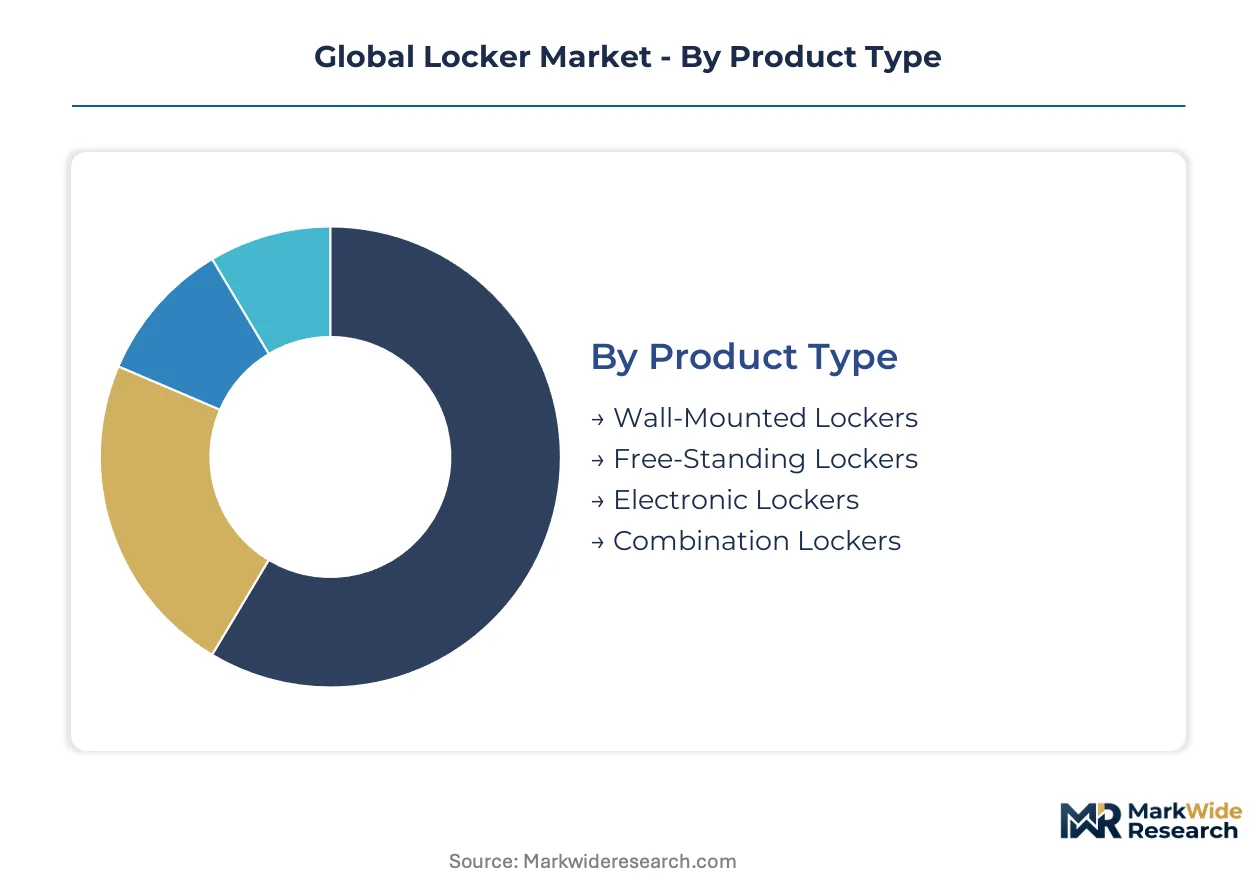
Segmentation in the locker market reveals how procurement priorities diverge across installation constraints, user security requirements, and environmental exposure. Material selection and product architecture directly determine replacement cycles and margin structures for manufacturers serving distinct verticals.
Product Type:
Installation architecture separates segments by capital intensity, retrofit feasibility, and software integration depth.
- Free-Standing Lockers:Self-supporting steel or composite units require no wall anchoring, enabling rapid deployment in leased commercial spaces. Gyms and schools in the United States favor these for lease flexibility and damage-limitation during relocation.
- Electronic Lockers:Networked access platforms integrate biometric readers, mobile credential systems, and building management APIs. Transit authorities in Germany and France are mandating these under EU AI Act biometric upgrade timelines, compressing replacement demand for legacy keypad systems.
- Wall-Mounted Lockers:Space-efficient units anchor to structural walls, common in high-density Japanese office towers where floor space commands premium valuations.
- Combination Lockers:Mechanical dial or electronic keypad hybrids serve cost-sensitive educational procurement in India and Southeast Asia where networked infrastructure remains limited.
Free-standing configurations hold installed capacity. Electronic lockers are rotating up the share rankings.
End User:
User environment dictates corrosion resistance, access frequency, and regulatory compliance burdens.
- Schools:High-volume, low-supervision deployments prioritize dent-resistant metal construction and simple mechanical locks. U.S. K-12 districts drive volume through standardized procurement consortia.
- Airports:FAA fire-safety mandates and TSA accessibility requirements govern specifications. Biometric-enabled units in German and Dutch terminals face EU AI Act algorithmic audit requirements.
- Gyms:Humidity exposure and frequent daily use favor HDPE or coated metal formulations with antimicrobial surface treatments.
- Offices:Flexible workspace operators in London and New York are bundling locker access into service contracts rather than capital purchases.
Schools dominate shipment volumes. Airport specifications are climbing the fastest on unit-value metrics.
Material:
Material selection tracks environmental exposure severity, weight constraints, and aesthetic requirements across deployment contexts.
- Metal:Cold-rolled steel construction delivers maximum impact resistance and fire ratings. Turkish and Indian mill supply volatility is squeezing margin structures for educational and athletic segment OEMs.
- Composite:Engineered formulations combining fiberglass, resin, and mineral fillers resist salt corrosion in coastal Japanese and Australian airport installations.
- Plastic:High-density polyethylene serves pool facilities and marine terminals where chlorine and salt accelerate metal degradation.
- Wood:Engineered wood composites address aesthetic specifications in Nordic commercial properties and hospitality-focused mixed-use developments.
Metal maintains production scale. Composite formulations are gaining specification share in corrosive environments.
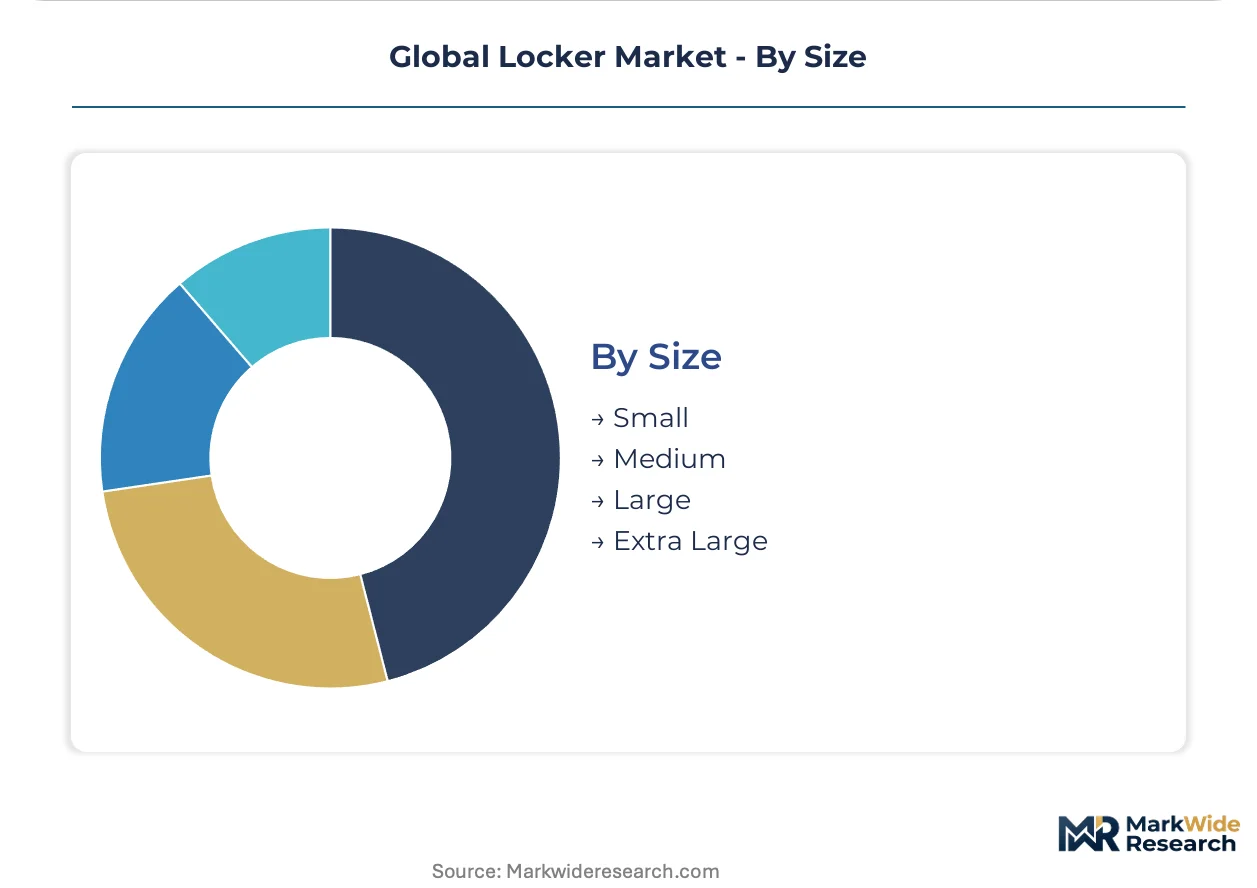
Size:
Dimensional categories align with storage duration, item bulk, and user dwell time in specific deployment settings.
- Medium:Standard 12-18 inch width compartments accommodate daily-use personal items and laptop storage. Office and gym deployments in Germany and Japan specify these as baseline configurations.
- Large:Expanded depth and height accommodate athletic equipment, carry-on luggage, and multi-day storage needs. Airport terminals in France and the Netherlands are front-loading large-format biometric units for compliance advantage.
- Small:Compact dimensions serve mobile phone and wallet storage in high-turnover transit environments.
- Extra Large:Oversized compartments handle bulky sports gear and extended-stay luggage in ski resorts and cruise terminals.
Medium sizes anchor specification frequency. Large formats are expanding most quickly in transit and aviation verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transit authorities and e-commerce fulfillment operators drive procurement concentration across Germany, China, Japan, the United States, and India. Each geography imposes distinct regulatory frameworks on biometric data handling, electromagnetic compatibility, and fire-safety specifications.
United States
Gym chains and flexible workspace operators deploy free-standing metal units for lease flexibility. The FAA mandates fire-safety and accessibility specifications for airport terminal installations. Dallas-Fort Worth and Atlanta airports are retrofitting legacy locker banks with networked access platforms.
Germany
Public transit authorities in Berlin and Munich face EU AI Act deadlines for biometric locker upgrades by 2026. The country's national data protection authority enforces GDPR server-localization requirements for facial-recognition data. Frankfurt Airport is front-loading compliance investments to secure early-mover certification advantages.
China
E-commerce fulfillment corridors in Shanghai and Shenzhen generate dense smart locker network deployment. SAMR enforces GB standards for electromagnetic compatibility and consumer data protection in public installations. Yangtze River Delta logistics clusters are accelerating platform standardization across urban nodes.
Japan
Coastal airports in Osaka and Tokyo specify HDPE composite formulations to resist salt corrosion. METI guidelines shape IoT platform integration standards for automated parcel handoff systems. Aging-care pharmacy networks in Kansai are piloting temperature-controlled lockers with clinical compliance monitoring.
India
Metro expansion in Delhi, Mumbai, and Bengaluru is tendering 50,000+ smart locker units without incumbent vendor relationships. BIS certification requirements govern electromagnetic emissions for connected devices. Transit corridors in Maharashtra and Karnataka represent first-mover windows for hardware-software bundled procurement.
Global Locker Market Competitive Environment
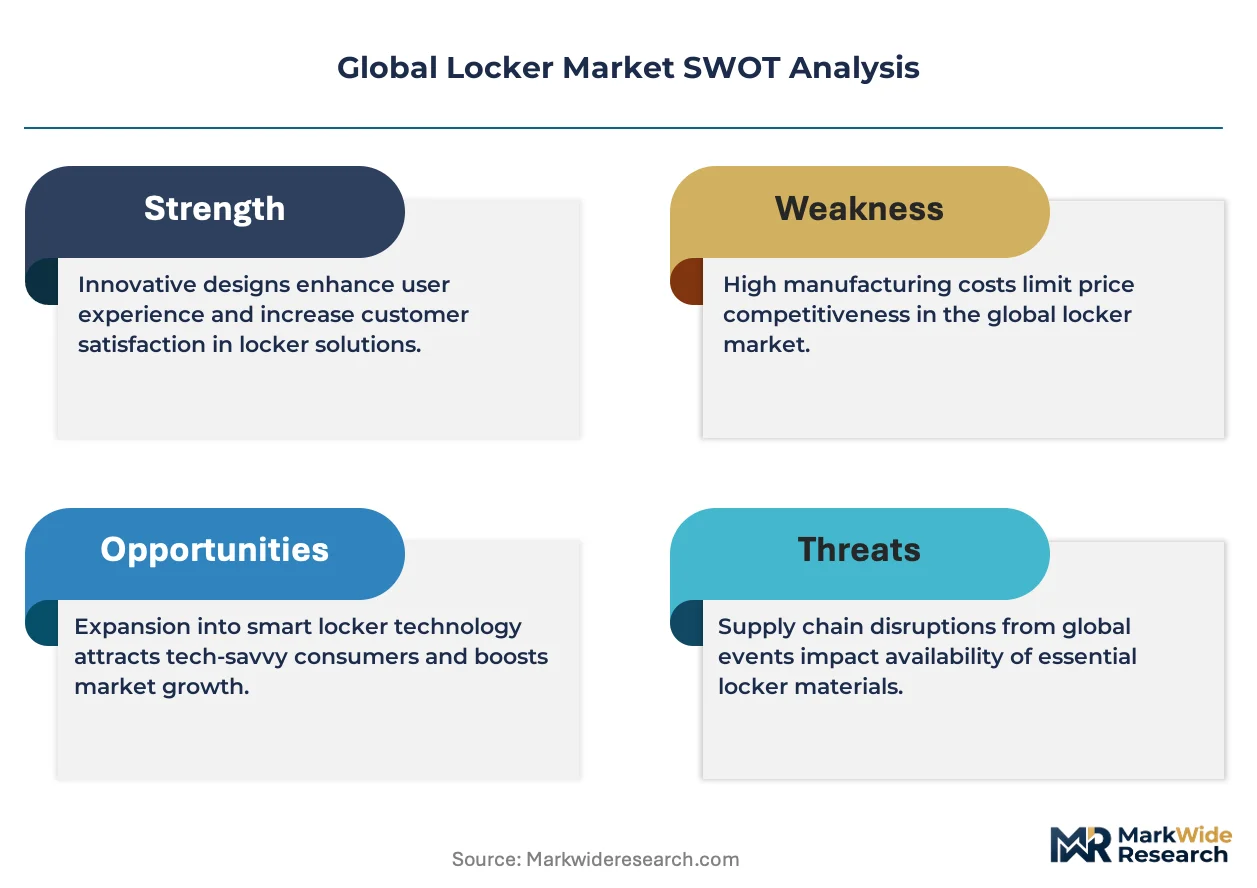
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Electronic locker platforms concentrate around access-control heritage firms and automated parcel handoff specialists, while metal fabrication volume sits with manufacturing-scale suppliers serving educational and athletic segments. Two strategic archetypes dominate: technology-integrators bundling hardware-software solutions, and scale-manufacturers optimizing cold-rolled steel throughput. Competitive moves center on asset-light leasing structures and multi-jurisdiction certification stacking to compress deployment timelines.
Among heritage access-control groups, ASSA ABLOY anchors the electronic installation tier across Nordic commercial properties. Cleveron occupies a position within the automated parcel handoff specialist archetype, serving grocery and pharmacy chain logistics. Penco Products exemplifies the manufacturing-scale metal fabricator archetype, supplying standardized athletic locker banks to educational procurement consortia.
| Leading Market Players |
|---|
| Salsbury Industries |
| Ricoh |
| ASSA ABLOY |
| American Locker |
| Cleveron |
| Pitney Bowes |
| Penco Products |
| Hollman |
| Quadient |
| Others |
Value Chain & Pricing Dynamics
Turkish and Indian cold-rolled steel mill concentration feeds directly into margin compression for metal locker OEMs serving educational procurement, while biometric module foundry dominance in South Korea and Taiwan concentrates value capture in electronic access platforms. Hardware-software bundling in transit authority contracts is rotating margin pools toward firmware-integrated suppliers.
Pricing Analysis
Certification level creates the primary spread across locker procurement tiers, with CE-marked cybersecurity addendums and EU AI Act compliance commanding premium positioning against baseline mechanical units. Three-tier pricing structure across premium, standard, and economy levels reflects biometric sophistication, networked integration depth, and after-sales service bundling. Cost compression in metal fabrication segments is intensifying because Turkish mill supply volatility and educational budget constraints squeeze standardized athletic locker margins. Schools and cost-sensitive municipal transit authorities in India exhibit highest price sensitivity, while German airport operators and Nordic commercial property managers demonstrate lowest sensitivity due to regulatory compliance mandates and workspace-as-a-service contract structures.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk calculus for electronic locker platforms, compounding existing single-source vulnerability in South Korean and Taiwanese fingerprint sensor fabrication. Cold-rolled steel supply concentrates in Turkey, India, and China, while HDPE composite formulations source from petrochemical corridors in Japan and the United States. Biometric module assembly rests on concentrated foundry capacity in East Asia, with firmware development talent scarcity in Europe and North America extending integration timelines. Distribution runs through national facilities integrators in the United States and United Kingdom, direct procurement by transit authorities in Germany and France, and hardware-software bundled tenders in China's Yangtze River Delta logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The locker market is recovering from pandemic-era deployment delays as transit infrastructure investment cycles and e-commerce fulfillment corridor buildouts synchronize. Replacement demand from EU AI Act biometric mandates provides near-term volume anchoring.
For Market Incumbents: Pre-empt margin erosion in metal fabrication segments by securing long-term offtake agreements with Turkish and Indian steel mills, while accelerating firmware talent acquisition in biometric authentication protocols to compress integration timelines threatened by embedded systems engineer shortages. Certification investment in CE marking cybersecurity addendums and GDPR-compliant data architectures defends positioning against emerging hardware-software specialists. For New Entrants and Emerging Players: Build out asset-light leasing capabilities targeting flexible workspace operators in London and New York, where procurement authority is concentrating with national facilities integrators rather than capital purchase committees. India's metro expansion corridors in Maharashtra and Karnataka represent the most penetrable geography, with 50,000+ unit tenders lacking incumbent vendor relationships and hardware-software bundled procurement creating first-mover windows for API-first platform specialists. For Investors and Strategic Acquirers: Capital is best deployed toward automated parcel handoff specialists with pharmacy cold-chain integration capabilities and temperature-controlled IoT monitoring, as Japan's aging-care networks merge clinical compliance with logistics infrastructure. The five-to-ten year viability window favors technology-integrators over scale-manufacturers as procurement shifts from capital purchase to service contracts. Watch for biometric module supply diversification announcements from South Korean and Taiwanese foundries as the inflection signal for reduced single-source risk and compressed hardware margins.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Cybersecurity Addendum | Early compliance with EU harmonized standards creates certification-based differentiation for connected locker platforms. |
| Biometric Module Supply Diversification | Reducing single-source dependence on South Korean and Taiwanese foundries mitigates procurement risk for locker assemblers. |
| Asset-Light Leasing Structure | Workspace-as-a-service bundling in the United States and United Kingdom concentrates purchasing authority with facilities integrators. |
| Pharmacy Cold-Chain Integration | Temperature-controlled lockers with IoT monitoring penetrate Japan's aging-care networks, merging parcel handoff with clinical compliance. |
| Firmware Talent Acquisition | Embedded systems engineers fluent in biometric protocols and building management APIs compress integration timelines by four to six months. |
Study Parameters
Desk research of customs and trade data, SEC filings, and regulatory submission databases preceded structured interviews with transit authority procurement officers, facilities management executives, locker OEM product managers, and biometric sensor vendor technical leads. Secondary validation drew from FAA fire-safety mandates, EU AI Act implementation guidance, SAMR GB standards documentation, and BIS certification requirements. Bottom-up unit deployment estimates across Germany, China, Japan, the United States, and India were triangulated against top-down market value projections.
Assumptions regarding EU AI Act biometric upgrade timelines, cold-rolled steel price volatility bands, and biometric module supply availability were held fixed across the projection horizon, while e-commerce penetration rates and transit infrastructure investment cycles were varied in sensitivity scenarios. Segmentation modeling incorporated product type, end user vertical, material formulation, and dimensional category, with CAGRs derived from regression analysis of historical deployment patterns and forward-looking procurement pipeline data. Hardware-software bundling penetration and asset-light leasing adoption curves served as industry-specific forecast inputs.
Stress conditions across Turkish steel export restrictions, GDPR server-localization enforcement variance, and biometric sensor foundry capacity utilization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and infrastructure investment cycles, with revision triggers including fragmented national cybersecurity certifications and multi-jurisdiction compliance stacking delays. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Plastics in Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Portable Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
US Negative Pressure Escape Masks Market