
 Head Protection Equipment Market | 2026-2036
Head Protection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Head Protection Equipment Market Outlook
ANSI Z89.1 certification is rotating the competitive set toward manufacturers with sustained testing infrastructure and documented compliance histories. MSA Safety Incorporated anchors North American industrial channels through deep vertical integration in suspension system manufacturing. Honeywell International Inc. differentiates via integrated communication modules embedded within helmet architectures. 3M Company leverages material science expertise to sustain premium positioning across mining and energy extraction applications.
Head protection equipment encompasses engineered assemblies designed to attenuate impact energy, typically constructed from polycarbonate, high-density polyethylene, or fiberglass shells with suspension systems that distribute force across cranial surfaces; these devices serve as mandatory personal protective equipment across hazardous work environments where falling objects, electrical hazards, or lateral impacts threaten worker safety. Helmets and hard hats together constitute the dominant product type category, with hard hats maintaining mature volume positions in general construction while helmets capture expanding demand in specialized verticals requiring integrated face shields or communication features. Polycarbonate material formulations represent the fastest-growing segment as manufacturers balance weight reduction against impact resistance thresholds specified by evolving standards.
OSHA workplace safety mandates in the United States, CE marking requirements under Europe's PPE Regulation, and India's BIS certification protocols collectively shape product design specifications, testing protocols, and market access conditions for manufacturers seeking cross-border distribution. ANSI Z89.1, EN 397, and IS 2925 standards establish performance baselines that determine which suppliers qualify for procurement contracts with regulated industries. Stakeholders must monitor regulatory harmonization efforts between North American and European testing protocols, as divergence in impact energy criteria could fragment certification requirements and complicate global product platform strategies.
Market Dynamics
OSHA's intensified enforcement of job-site head injury prevention is compressing procurement cycles and forcing construction contractors toward ANSI Z89.1-certified helmets with documented testing histories, reshaping supplier qualification requirements across North American industrial channels.
Growth Catalysts
- OSHA enforcement escalation:Tighter penalties for head injury violations drive construction firms toward certified equipment with traceable compliance documentation.
- Polycarbonate material advances:ECHA chemical safety reviews in Germany accelerate demand for advanced shell formulations balancing weight reduction against impact thresholds.
- Mining sector safety mandates:Underground extraction operations in resource-intensive economies specify integrated communication and face shield capabilities.
Market Restraints
- Petrochemical input volatility:Polycarbonate and high-density polyethylene resin prices fluctuate with crude oil markets, compressing margin predictability for shell manufacturers.
- Testing infrastructure concentration:ANSI Z89.1 certification capacity clusters in domestic U.S. laboratories, creating bottlenecks for foreign suppliers seeking market access.
- Substitution by soft-shell alternatives:Bump caps gain traction in low-risk warehouse and logistics environments where falling object hazards are minimal.
Strategic Opportunities
- India's BIS certification expansion:Infrastructure build-out under national safety protocols creates first-mover advantage for suppliers establishing local testing partnerships.
- Smart helmet convergence:Integration of IoT sensors with augmented reality displays opens premium positioning in precision manufacturing and energy maintenance.
- Direct-to-contractor distribution:Digital procurement platforms bypass traditional industrial supply houses, capturing margin and usage data.
Industry Challenges
- Suspension system engineering talent scarcity:Specialized biomechanical design expertise for force distribution mechanisms commands premium compensation and extends R&D timelines.
- Multi-standard certification complexity:Divergent impact energy criteria between ANSI Z89.1 and EN 397 complicate global product platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Head Protection Equipment Market |
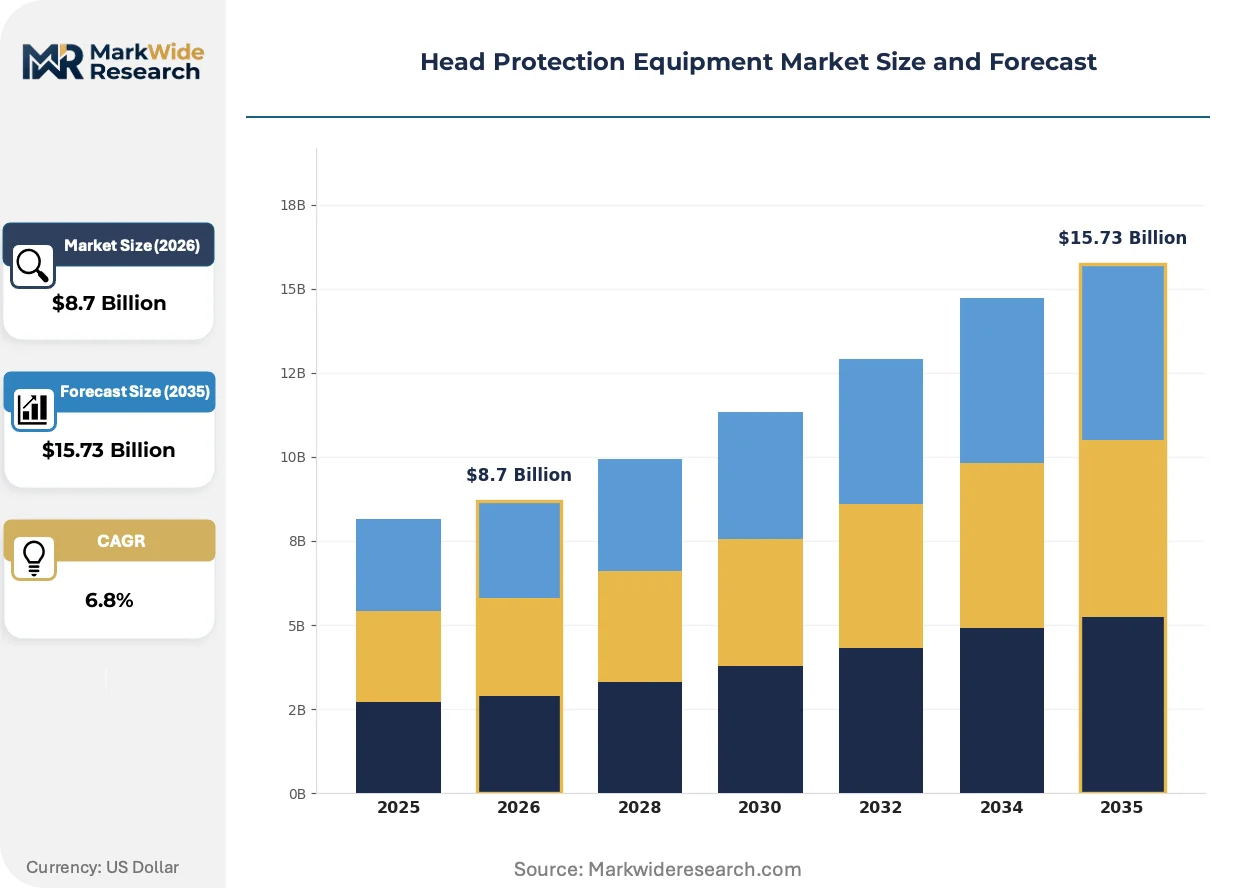
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Hard Hats, Bump Caps, Face Shields Material: Polycarbonate, Fiberglass, High-Density Polyethylene, Expanded Polystyrene Industry Vertical: Construction, Manufacturing, Oil & Gas, Mining Feature: Ventilation, Integrated Communication, Adjustable Fit, Impact Resistance |
| Companies Covered | 3M Company, Honeywell International Inc., MSA Safety Incorporated, DuPont de Nemours Inc., Bullard, JSP Ltd., Delta Plus Group, Uvex Group, Ansell Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Head Protection Equipment Market Strategic Shifts
Sensor integration and material science advances are compressing the traditional hard hat into a connected safety platform, while regulatory divergence between North American and European testing protocols fragments certification strategies.
Embedded communication modules are miniaturizing within helmet architectures without compromising impact protection ratings. Oil and gas field operators adopt these systems fastest, replacing separate two-way radio units. The technology is miniaturizing equipment stacks workers must carry, reducing neck strain claims and consolidating procurement categories.
REACH chemical safety reviews in Europe are restricting legacy plasticizer formulations in suspension system components. Manufacturers reformulate polymer blends to maintain elasticity under temperature extremes. German industrial buyers now specify full material disclosure documentation, pressuring suppliers to requalify supply chains.
Certification-driven purchasing is consolidating buyer decision criteria around documented compliance histories rather than unit price. General contractors pre-qualify suppliers based on testing infrastructure ownership, displacing low-cost imports without ANSI Z89.1 laboratory relationships. This pattern concentrates procurement authority with national distributors maintaining direct certification ties.
Head Protection Equipment Market Segmentation
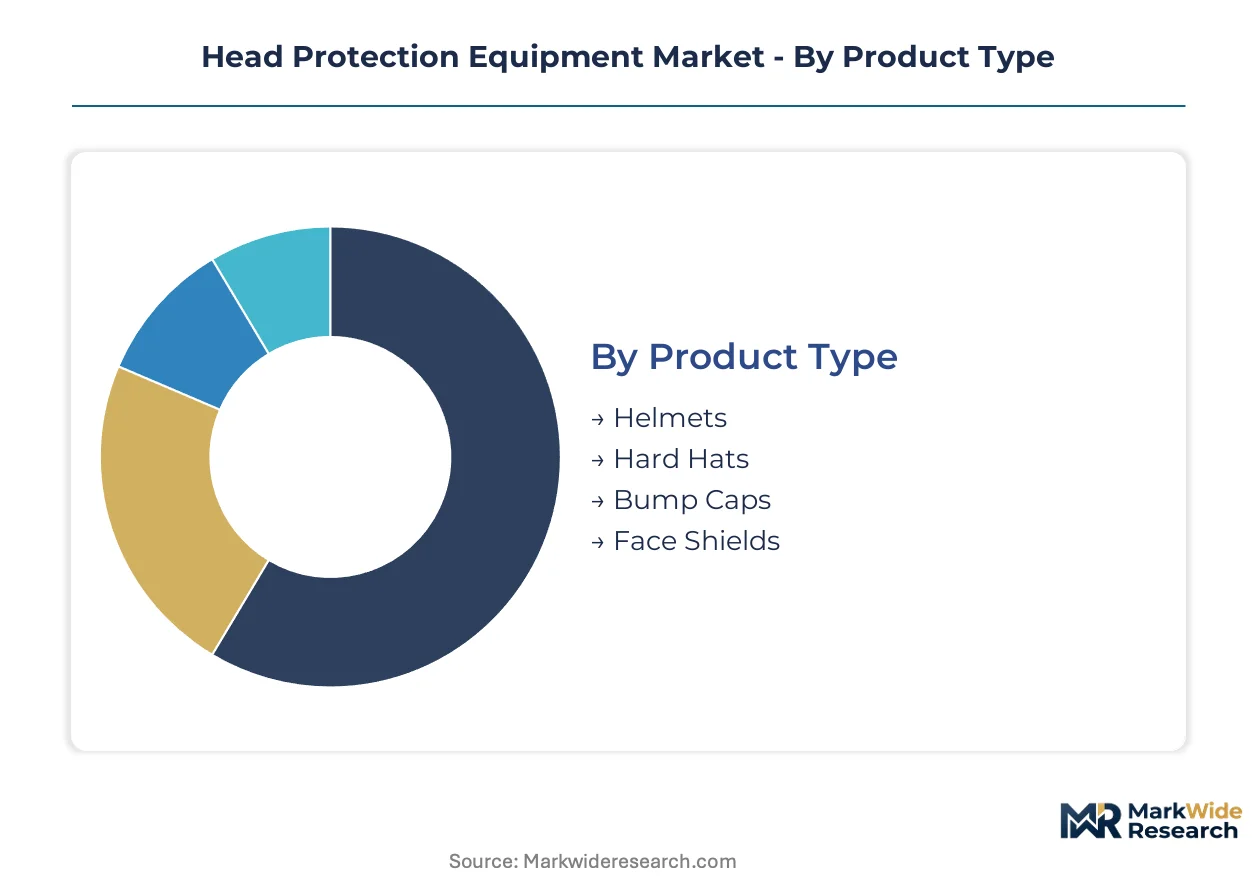
Head protection equipment procurement diverges sharply across hazard intensity levels and regulatory environments. Segmentation reveals where ANSI Z89.1 certification concentrates versus where CE marking dominates, shaping manufacturer platform strategies and distribution investments.
Product Type:
Hard hats anchor domestic U.S. construction procurement through established ANSI Z89.1 laboratory relationships, while helmets drive export-led expansion into mining and energy extraction verticals requiring integrated communication architectures.
- Hard Hats:These shell-and-suspension assemblies utilize high-density polyethylene or polycarbonate formulations with ratchet or pin-lock adjustment systems. U.S. general contractors specify these for above-ground construction sites where falling object hazards predominate, with procurement authority consolidating around national distributors maintaining direct ANSI Z89.1 certification ties.
- Helmets:Engineered with integrated face shields, hearing protection attachments, and communication module mounting points, these devices serve underground mining and oil field maintenance crews. Australian and Canadian resource extraction operations specify these for confined-space communication requirements, driving premium positioning.
- Bump Caps:Lightweight polyethylene shells with foam padding protect against lateral impacts in warehouse and logistics environments where falling object hazards are minimal.
- Face Shields:Polycarbonate visor attachments mount to helmet brims for chemical splash and arc flash protection in manufacturing and electrical utility applications.
Hard hats command the established base. The steepest expansion runs through helmets.
Material:
Cost tier differentiation separates premium polycarbonate formulations from commodity high-density polyethylene, with fiberglass occupying mid-tier positioning for electrical hazard applications.
- Polycarbonate:These amorphous thermoplastic shells deliver superior impact resistance at reduced weight versus polyethylene alternatives. German industrial buyers under ECHA chemical safety reviews now demand full material disclosure documentation, accelerating reformulation investments.
- High-Density Polyethylene:Injection-molded HDPE shells dominate volume procurement in price-sensitive construction segments. Petrochemical input volatility compresses margin predictability for manufacturers without backward integration into resin supply.
- Fiberglass:Reinforced thermoset shells provide dielectric protection for electrical utility applications where arc flash ratings determine specification.
- Expanded Polystyrene:Lightweight liner material integrates with outer shells for multi-impact energy absorption in recreational and light industrial applications.
High-density polyethylene captures the volume base. Polycarbonate climbs the fastest on safety specification upgrades.
Industry Vertical:
Application intensity determines feature bundling, with oil and gas and mining verticals absorbing premium integrated communication configurations while construction procurement emphasizes baseline impact certification.
- Construction:Above-ground building and infrastructure projects drive the highest unit volumes, with OSHA enforcement escalation compressing procurement cycles toward documented ANSI Z89.1 compliance histories.
- Mining:Underground extraction operations specify integrated communication and face shield capabilities as mandatory safety protocol. South African and Chilean mining regulators now mandate continuous worker connectivity in deep-shaft environments.
- Oil & Gas:Field maintenance crews in the Permian Basin and North Sea platforms adopt embedded radio modules fastest, replacing separate two-way units to reduce neck strain claims.
- Manufacturing:Assembly line and precision machining environments prioritize ventilation features and adjustable fit systems for extended-wear comfort.
Construction holds the volume anchor. Mining generates the steepest value-per-unit expansion.
Feature:
Customer type stratification separates specification-driven buyers prioritizing impact resistance certification from technology-adopting operators seeking integrated communication and adjustable fit innovations.
- Impact Resistance:ANSI Z89.1 Type I and Type II classification systems determine procurement eligibility for falling object and lateral impact hazards. General contractors pre-qualify suppliers based on testing infrastructure ownership.
- Integrated Communication:Miniaturized radio modules embed within helmet architectures without compromising protection ratings. Oil field operators consolidate procurement categories by eliminating separate two-way radio purchases.
- Ventilation:Passive and active airflow channels reduce heat stress in high-temperature manufacturing and desert construction environments.
- Adjustable Fit:Ratchet suspension systems and customizable padding accommodate diverse cranial geometries, reducing fit-test failures and replacement rates.
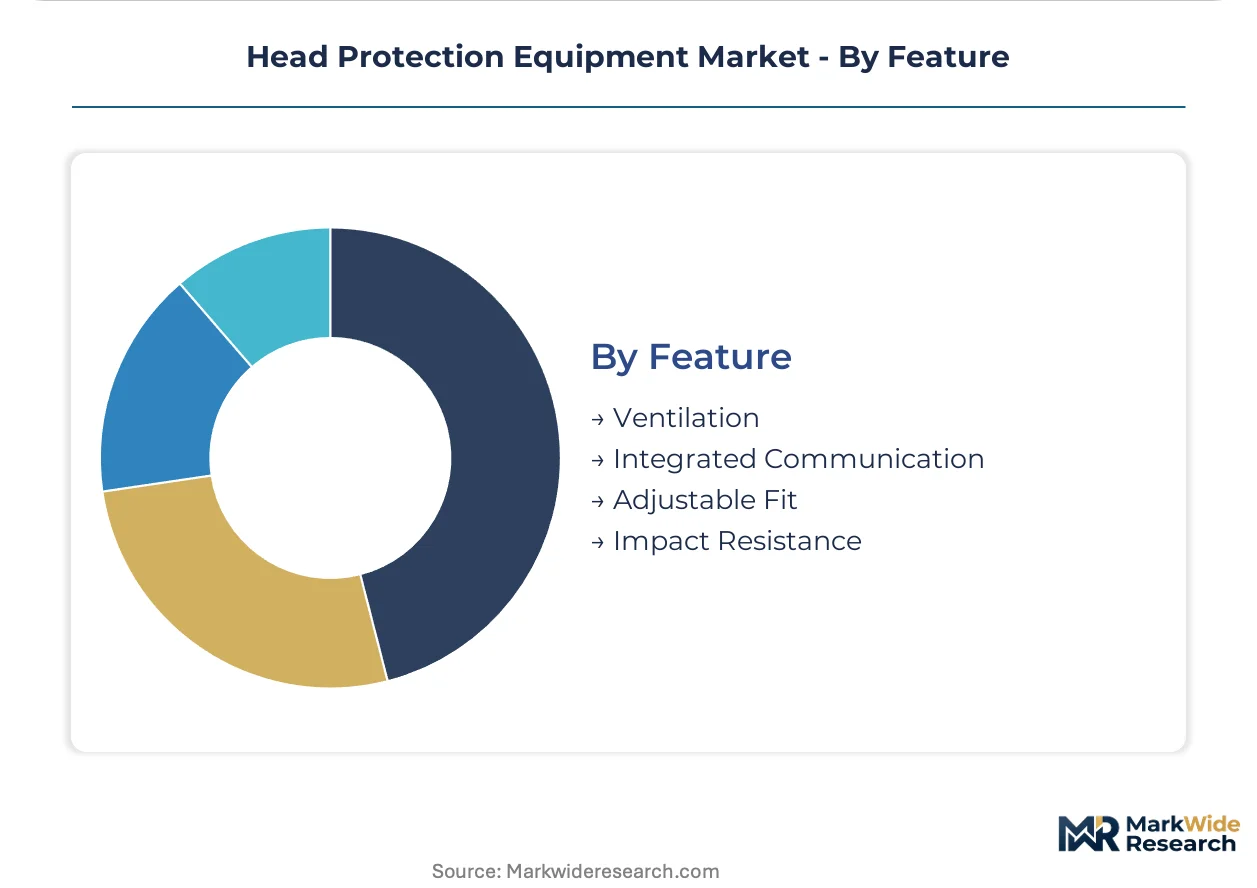
Impact resistance anchors specification compliance. Integrated communication gains share fastest on connectivity convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA enforcement escalation in the United States compresses procurement cycles toward ANSI Z89.1-certified equipment, while ECHA chemical safety reviews in Germany accelerate polycarbonate formulation upgrades. India's BIS certification expansion under national infrastructure protocols creates first-mover opportunities for suppliers establishing local testing partnerships.
United States
Construction crews expand ANSI Z89.1 helmet procurement as OSHA tightens job-site head injury prevention enforcement. General contractors now pre-qualify suppliers based on testing infrastructure ownership, displacing uncertified imports. The Permian Basin oil field maintenance sector drives embedded communication module adoption fastest.
Germany
Industrial buyers under ECHA REACH reviews demand full material disclosure documentation for polycarbonate shell formulations. Manufacturers reformulate polymer blends to maintain elasticity under temperature extremes. The Ruhr industrial cluster concentrates procurement authority with distributors maintaining direct CE marking laboratory relationships.
India
Infrastructure build-out under BIS certification protocols creates procurement scale for hard hat suppliers establishing local testing partnerships. Mining operations in Jharkhand and Odisha specify integrated face shield capabilities for underground extraction safety mandates. Delhi-NCR construction markets compress replacement cycles on safety specification upgrades.
China
GB standards for personal protective equipment align with international impact resistance benchmarks, opening export manufacturing capacity. Mining sector consolidation in Shanxi Province drives demand for helmets with continuous worker connectivity features. Yangtze River Delta fabrication clusters supply polycarbonate shell components to global brand owners.
Australia
Underground mining regulators mandate continuous worker connectivity in deep-shaft environments across Western Australian extraction operations. TGA-equivalent state-level safety protocols specify integrated communication architectures for confined-space entry. Perth-based resource contractors consolidate procurement categories by eliminating separate two-way radio purchases.
Head Protection Equipment Market Competitive Environment
Player mix skews toward diversified industrial safety conglomerates with material science capabilities and specialized helmet fabricators with regional certification expertise. The vendor base stratifies across three tiers: integrated safety technology providers, regional specialists with testing infrastructure ownership, and commodity shell manufacturers serving price-sensitive construction segments. Dominant competitive moves include M&A to capture ANSI Z89.1 laboratory relationships and geographic expansion to secure BIS certification capacity in India.
Among North American-anchored industrial safety providers, MSA Safety Incorporated, Honeywell International Inc., and 3M Company exemplify the integrated technology tier. These entities represent archetypes of vertical control over suspension system engineering, embedded communication module development, and material science expertise respectively. Each occupies a distinct positioning vector: MSA Safety Incorporated anchors domestic certification infrastructure, Honeywell International Inc. sits within the connectivity convergence layer, and 3M Company exemplifies premium material formulation capabilities for mining and energy extraction applications.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| MSA Safety Incorporated |
| DuPont de Nemours Inc. |
| Bullard |
| JSP Ltd. |
| Delta Plus Group |
| Uvex Group |
| Ansell Ltd. |
| Others |
Value Chain & Pricing Dynamics
ANSI Z89.1 certification infrastructure simultaneously gates supplier qualification and stratifies price tiers, concentrating procurement authority with domestic laboratories that can document compliance histories while compressing margin predictability for uncertified imports. Construction contractors now pre-qualify vendors based on testing infrastructure ownership, creating a direct feedback loop where supply concentration shapes pricing power and certification investment requirements feed into landed cost structures.
Pricing Analysis
Cost-plus contracts with polycarbonate resin indexation dominate procurement between shell manufacturers and construction distributors, embedding petrochemical volatility directly into unit economics. Three-tier pricing structure across premium, standard, and economy levels separates ANSI Z89.1 Type II helmets with integrated communication modules from baseline Type I hard hats and uncertified imports. Pricing pressure stems from ECHA-driven reformulation costs in European supply chains. General contractors show highest price sensitivity in volume construction segments, while oil field operators absorb premium positioning for connectivity-integrated architectures.
Supply Chain Analysis
Just-in-time inventory strategies prevail among U.S. construction distributors holding ANSI Z89.1-certified stock, while mining operators in Australia and Canada maintain strategic stockpiles of helmets with embedded communication modules for remote site deployment. Manufacturing concentrates in China for polycarbonate shell components, the United States for suspension system assembly, and Germany for advanced material formulation under REACH compliance. Raw material dependencies center on bisphenol A feedstocks for polycarbonate, high-density polyethylene resin, and specialty elastomers for suspension systems. Single-source vulnerability runs through domestic U.S. testing laboratory capacity for ANSI Z89.1 certification. Distribution runs through national industrial supply houses maintaining direct laboratory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biomechanical engineering talent for suspension system design commands premium compensation and extends R&D timelines, creating a persistent capability gap that shapes competitive positioning across certification tiers and determines which suppliers can sustain multi-standard product platforms.
For Market Incumbents: Shield certification infrastructure ownership through exclusive laboratory partnership extensions and captive testing capacity investments. MSA Safety Incorporated's vertical integration into suspension manufacturing exemplifies the defensive posture required against emerging smart-helmet entrants with IoT sensor capabilities. Prioritize ANSI Z89.1 Type II certification maintenance as the primary lever against low-cost imports lacking documented compliance histories. For New Entrants and Emerging Players: Anchor in India's BIS certification expansion under national infrastructure protocols, where local testing partnerships create first-mover advantage before incumbent laboratory relationships solidify. Target Jharkhand and Odisha mining operations with integrated face shield capabilities as the most penetrable vertical requiring continuous worker connectivity. Pursue direct-to-contractor digital procurement platforms as the primary go-to-market angle to bypass established industrial supply house gatekeepers. For Investors and Strategic Acquirers: OSHA's intensified enforcement of job-site head injury prevention reshapes the acquisition landscape toward suppliers with documented ANSI Z89.1 laboratory relationships and sustained testing infrastructure ownership. Long-term viability centers on material science capabilities enabling polycarbonate formulation upgrades under evolving chemical safety reviews. Target acquisition candidates with captive suspension system engineering talent and established CE marking capacity for European market access. Watch ECHA REACH review outcomes on plasticizer formulations as the signal indicating when supply chain requalification investments will accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| ANSI Z89.1 Laboratory Partnership Expansion | Secures procurement eligibility with OSHA-enforced construction contractors and national distributors. |
| Polycarbonate Formulation Reformulation | Maintains European market access under ECHA REACH chemical safety disclosure requirements. |
| Embedded Communication Module Integration | Captures premium positioning in Permian Basin oil field and Australian mining maintenance operations. |
| BIS Certification Infrastructure Establishment | Creates first-mover advantage in Delhi-NCR construction and Jharkhand mining procurement cycles. |
| Direct-to-Contractor Digital Platform Launch | Bypasses industrial supply house intermediaries to capture margin and usage data ownership. |
Study Parameters
Initial hypotheses were tested against primary input from safety equipment procurement managers, suspension system biomechanical engineers, construction site safety officers, and industrial distribution channel heads, then refined through secondary validation against OSHA enforcement records, ANSI Z89.1 certification databases, ECHA REACH substance evaluations, and customs trade data for polycarbonate and high-density polyethylene resin flows. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against end-use industry expenditure patterns anchored the analytical framework.
Variance decomposition across material cost trajectories, certification capacity constraints, and regulatory enforcement intensity shaped the projection methodology. Segmentation dimensions modeled include product type, shell material formulation, industry vertical, integrated feature bundling, and regional regulatory cluster. CAGRs were derived from logistic adoption curves fitted to enforcement-driven replacement cycle compression. Industry-specific forecast inputs incorporated petrochemical resin price correlation coefficients and laboratory certification queue length data.
Decision-makers should treat outputs as directional under assumptions of sustained OSHA enforcement escalation and ECHA chemical safety review continuity; material deviation in either regulatory trajectory would warrant model refresh. Revision becomes warranted when polycarbonate resin price volatility crosses thresholds that compress manufacturer margin below reformulation investment requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market