
 Electrical Safety Analyzers Market | 2026-2036
Electrical Safety Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Safety Analyzers Market Analysis
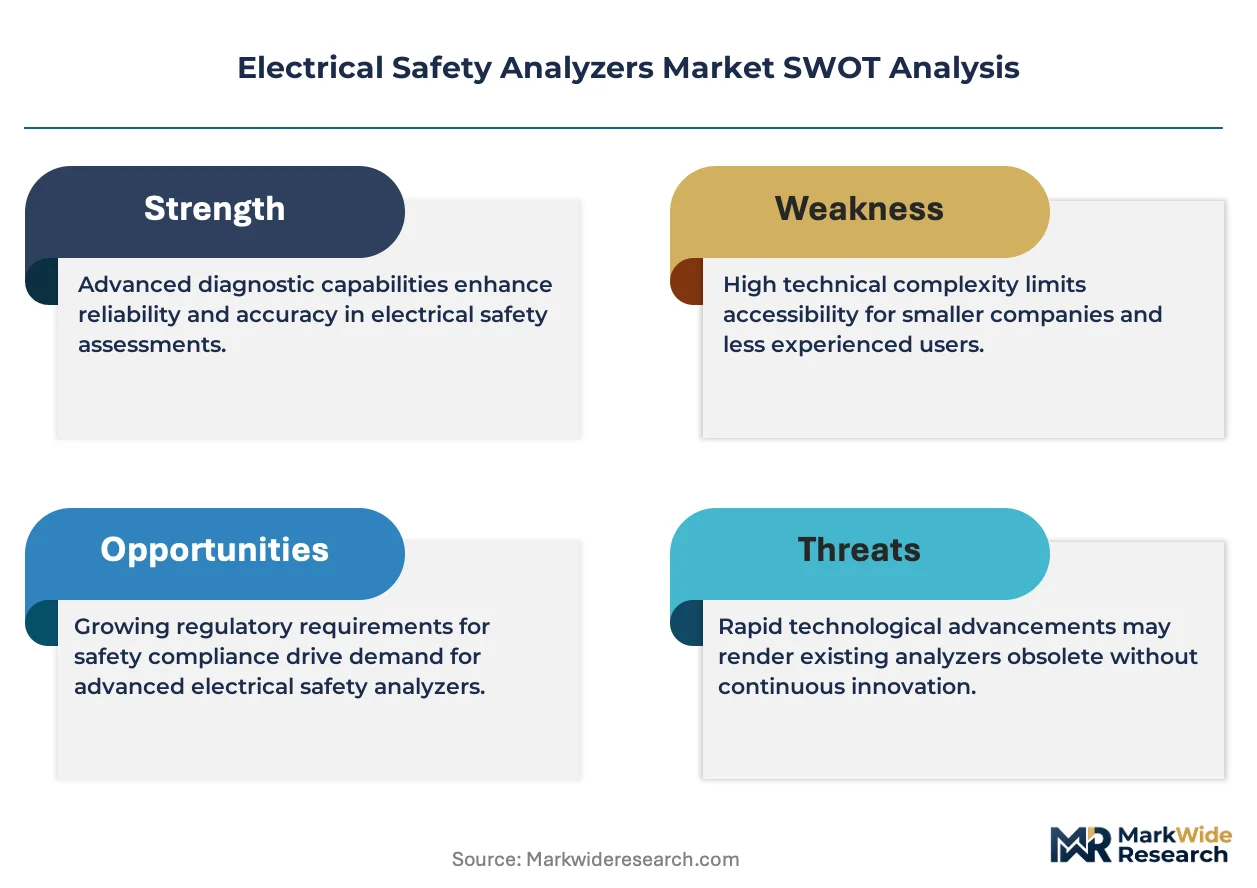
Healthcare procurement teams are reorganizing their capital equipment priorities around preventive electrical safety testing, displacing traditional reactive maintenance budgets in manufacturing plants. Fluke Biomedical leverages its hospital-installed base to sustain recurring calibration revenue. Chroma ATE anchors Asian supply through automated test system integration. Megger Group Limited competes in high-voltage utility segments with specialized insulation resistance modules.
Electrical safety analyzers are precision instruments that verify protective earth continuity, insulation resistance, leakage current, and dielectric withstand capability in accordance with IEC 61010 and IEC 60601 standards. These devices perform automated sequences of hipot, ground bond, and line leakage measurements to certify that electrical equipment poses no shock hazard to operators or patients. Portable analyzers dominate field service applications where technicians require battery-operated units with data logging, while fixed analyzers occupy production-line environments demanding higher throughput and integration with manufacturing execution systems. Multi-function analyzers capture margin concentration by consolidating previously separate hipot, ground bond, and leakage instruments into single platforms that reduce capital outlay and calibration burden.
FDA enforcement of 21 CFR 820 quality system regulations compels medical device manufacturers to document electrical safety verification, while IEC 60601-1 third edition mandates periodic testing of diagnostic and therapeutic equipment in clinical settings. OSHA electrical safety standards in industrial workplaces create baseline demand for ground fault and arc flash prevention testing. Stakeholders must monitor evolving harmonization between regional standards bodies and IEC templates to anticipate certification cost shifts and market access barriers.
Market Dynamics
Medical device manufacturers face intensifying pressure to consolidate hipot, ground bond, and leakage testing into single-platform analyzers as IEC 60601-1 third edition mandates proliferate across hospital procurement specifications.
Growth Catalysts
- IEC 60601-1 Third Edition:Mandatory periodic testing of diagnostic equipment in clinical settings drives replacement cycles for legacy single-function instruments.
- Preventive Maintenance Protocols:Healthcare facilities in Germany and the United States redirect capital budgets from reactive repair toward automated electrical safety verification systems.
- Multi-Function Platform Consolidation:Manufacturing plants adopt integrated analyzers to reduce calibration burden and footprint on production lines.
Market Restraints
- Precision Sensor Supply Concentration:High-accuracy current transformers and isolation amplifiers concentrate among Japanese and German component specialists, creating input bottlenecks.
- Calibration Infrastructure Costs:Accredited laboratories require NIST-traceable standards and controlled environments, elevating recurring operational expenditure for end-users.
- Substitution by Modular Test Racks:Industrial automation integrators assemble custom PXI-based measurement systems that bypass dedicated analyzer procurement.
Strategic Opportunities
- India Medical Device Manufacturing:CDSCO's phased implementation of quality management system rules creates first-mover advantage for analyzer vendors establishing calibration networks.
- Battery-Powered Field Units:Service technicians in distributed healthcare systems demand portable analyzers with wireless data logging for remote clinic verification.
- CE-MDR Convergence:The European Medical Device Regulation's heightened electrical safety documentation requirements expand addressable market for automated test documentation software.
Industry Challenges
- Embedded Firmware Validation:Analyzer manufacturers must maintain IEC 61010-2-034 compliance across software revision cycles, extending certification timelines.
- Legacy Equipment Integration:Hospital biomed departments struggle to interface modern analyzers with decades-old diagnostic equipment lacking standardized test points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Safety Analyzers Market |
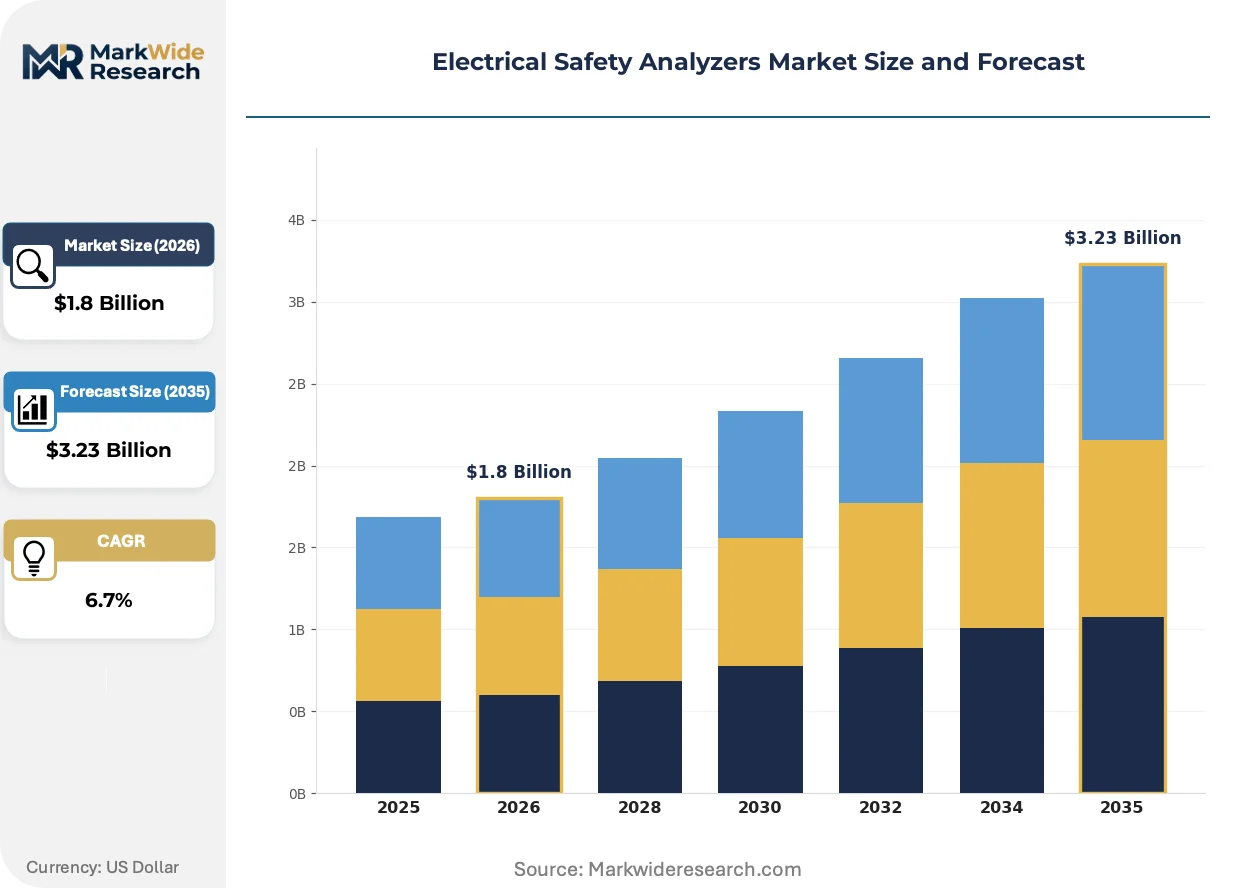
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Fixed Analyzers, Multi-Function Analyzers, Specific Analyzers End User: Manufacturing, Healthcare, Education, Utilities Technology: Digital Technology, Analog Technology, Hybrid Technology, Wireless Technology Application: Electrical Testing, Equipment Maintenance, Compliance Testing, Research & Development |
| Companies Covered | Fluke Biomedical, Chroma ATE, Vitrek, HIOKI, Datrend Systems, Sefelec Eaton, Seaward Group, Megger Group Limited, Ikonix USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Safety Analyzers Market Emerging Trajectories
Electrical safety testing is undergoing platform consolidation as manufacturers embed artificial intelligence-driven fault prediction and cloud-based calibration tracking into next-generation analyzers.
Multi-function analyzers are fragmenting the historical separation between hipot, ground bond, and leakage current instruments. Medical device contract manufacturers in Ireland and Costa Rica now specify single-platform units to compress validation timelines. This convergence is fragmenting vendor portfolios that previously specialized in discrete measurement categories.
The European Union's Medical Device Regulation (MDR) intensifies electrical safety documentation requirements for active implantable and diagnostic equipment. Manufacturers must now maintain traceable test records across device lifecycles. Class IIb and III device producers in Germany and the Netherlands are responding by specifying analyzers with integrated barcode scanning and automated report generation.
Hospital procurement departments now unbundle analyzer acquisition from multi-year service contracts, shifting toward per-test calibration pricing. Original equipment manufacturers face margin compression as third-party metrology laboratories capture recurring revenue streams. This unbundling is most visible in the United States, where Group Purchasing Organizations negotiate separate instrumentation and service line items.
Electrical Safety Analyzers Market Segmentation
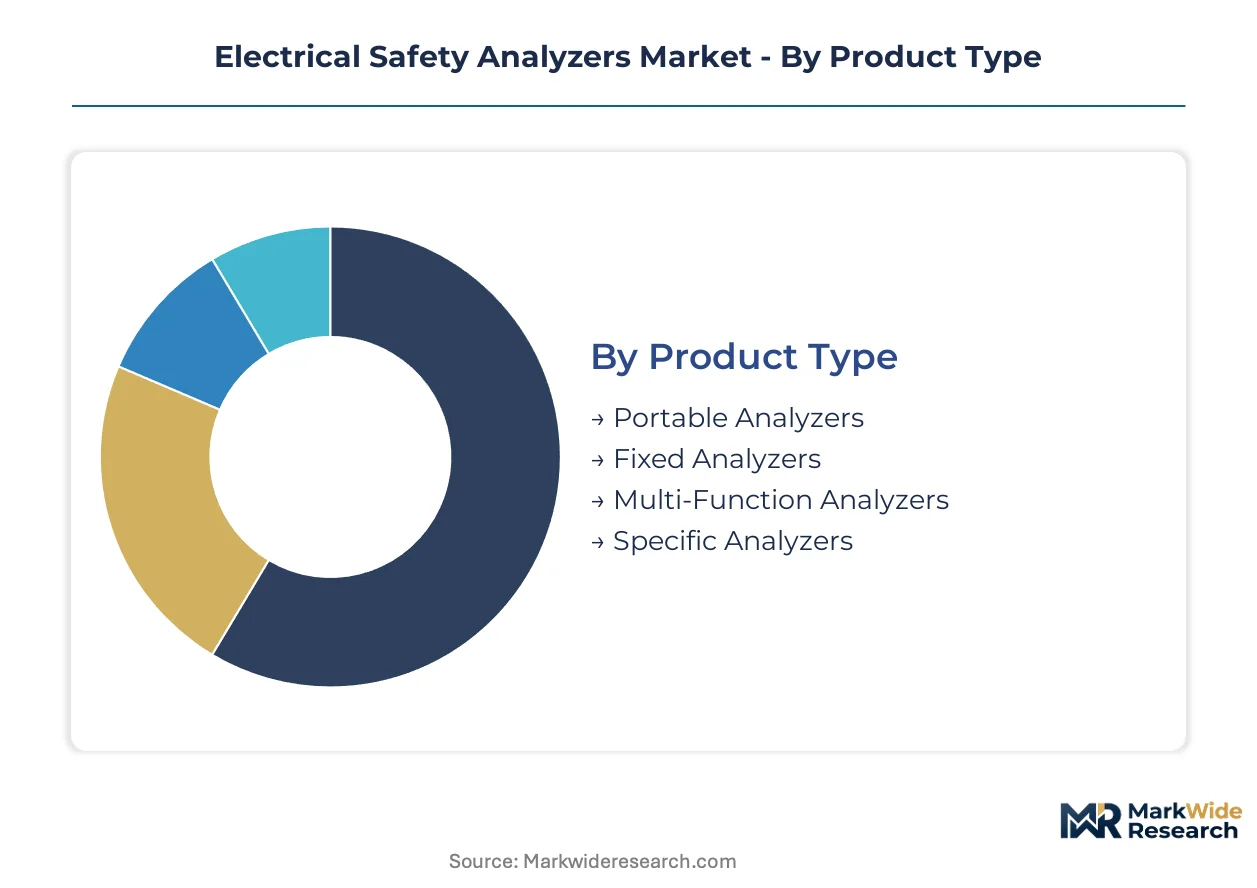
Channel strategy for electrical safety analyzers diverges sharply by product mobility and customer technical sophistication. Hospital procurement teams favor bundled service contracts for portable units, while manufacturing buyers prioritize throughput-optimized fixed installations with MES integration.
Product Type:
Portable analyzers flow through distributor networks with calibration service attachments, whereas fixed and multi-function platforms sell direct to manufacturing accounts with integration engineering support.
- Portable Analyzers:Battery-operated instruments with data logging capabilities enable field technicians to perform IEC 60601 verification at distributed clinics. Demand concentrates in German hospital networks expanding preventive maintenance protocols, though calibration infrastructure gaps in emerging markets constrain penetration.
- Multi-Function Analyzers:Integrated platforms consolidate hipot, ground bond, and leakage testing to reduce capital outlay and calibration burden. Medical device contract manufacturers in Ireland specify these units to compress validation timelines ahead of EU MDR documentation deadlines.
- Fixed Analyzers:Production-line installations demand higher throughput and MES integration for automated electrical safety verification.
- Specific Analyzers:Specialized units target niche applications with dedicated measurement ranges.
By volume, portable analyzers lead due to field service fleet replacement cycles. By growth pace, multi-function platforms are expanding most quickly as manufacturing plants consolidate test equipment footprints.
End User:
Cost tier differentiation separates premium analyzer specifications for regulated medical manufacturing from standard-grade units serving educational and utility maintenance applications.
- Healthcare:Hospitals and clinical laboratories mandate IEC 60601-1 third edition compliance for diagnostic and therapeutic equipment. German healthcare facilities redirect capital budgets toward automated verification systems, displacing reactive maintenance spending.
- Manufacturing:Medical device producers face FDA 21 CFR 820 quality system documentation requirements for electrical safety verification. Production-line throughput demands drive specification of fixed analyzers with barcode scanning and automated report generation.
- Utilities:High-voltage infrastructure maintenance requires specialized insulation resistance testing capabilities.
- Education:Technical training programs utilize entry-grade analyzers for instructional laboratory environments.
Manufacturing captures the largest revenue share. Healthcare is gaining share fastest as hospital procurement reorganizes around preventive testing protocols.
Technology:
Volume concentration favors digital architectures, while margin accrues to hybrid and wireless configurations addressing Industry 4.0 integration requirements.
- Digital Technology:Microprocessor-controlled measurement engines deliver precision current sensing and automated test sequencing. Manufacturing plants in the United States specify digital platforms for NIST-traceable calibration chains and cloud-based asset management.
- Wireless Technology:Bluetooth and Wi-Fi enabled units transmit test data directly to CMMS platforms, eliminating manual documentation. Field service technicians in distributed healthcare systems demand these capabilities for remote clinic verification workflows.
- Hybrid Technology:Combines analog signal conditioning with digital processing for specialized measurement accuracy.
- Analog Technology:Legacy architectures persist in cost-sensitive educational and basic maintenance applications.
Digital platforms dominate installed base. Wireless configurations show the steepest expansion trajectory as connectivity becomes standard in hospital procurement specifications.
Application:
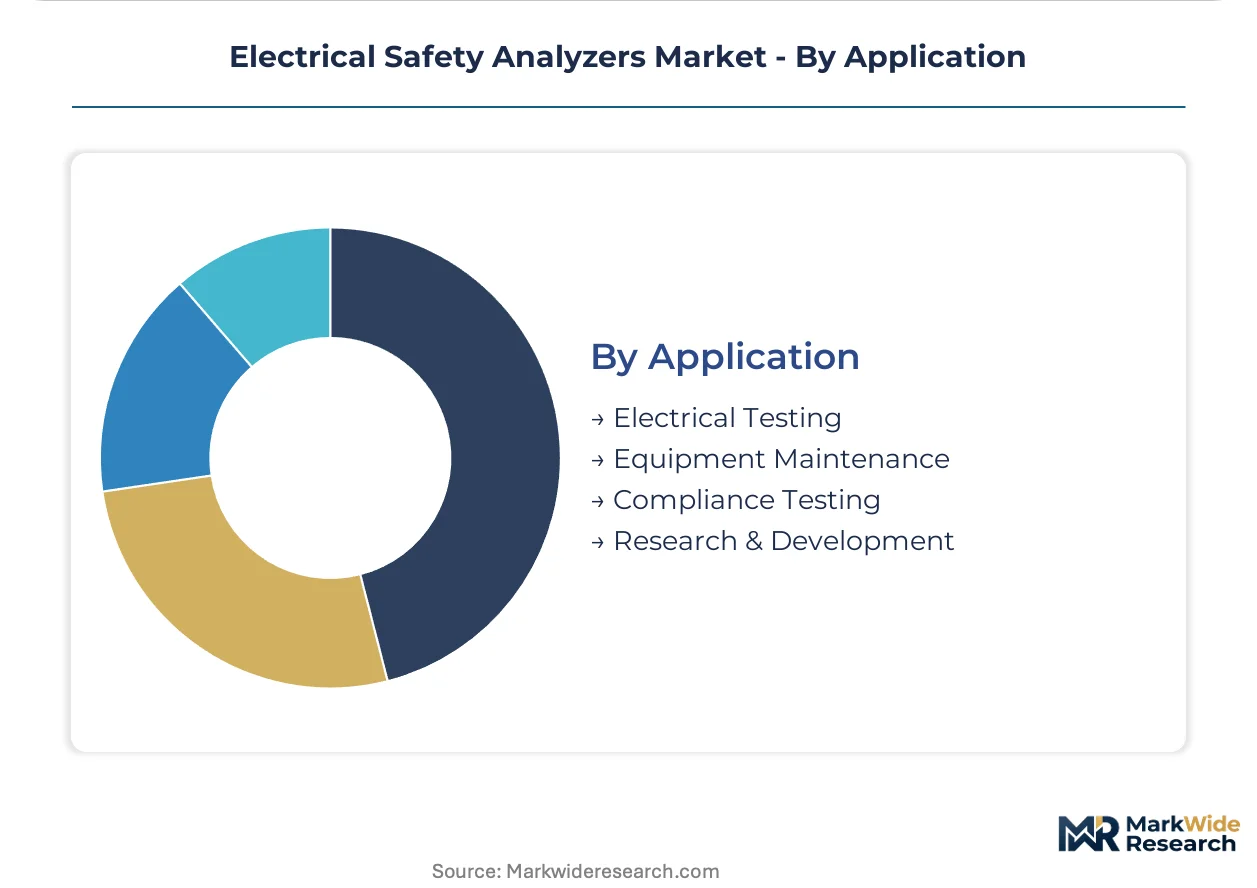
Customer type stratification separates regulated compliance testing with documentation mandates from internal maintenance and R&D applications with flexible specifications.
- Compliance Testing:Formal certification against IEC 60601, IEC 61010, and OSHA electrical safety standards requires traceable test records and accredited calibration. EU MDR intensifies documentation requirements for active implantable device producers in Germany and the Netherlands.
- Equipment Maintenance:Preventive electrical safety verification in healthcare facilities replaces reactive repair budgets. German hospital biomed departments specify analyzers with integrated barcode scanning to streamline asset tracking.
- Electrical Testing:General-purpose verification of protective earth continuity and insulation resistance.
- Research & Development:Prototype validation and design verification in medical device development cycles.
Compliance testing commands premium pricing. Equipment maintenance is climbing the fastest as healthcare facilities shift from reactive to preventive protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component supply for precision current transformers and isolation amplifiers concentrates among Japanese and German specialists, creating input bottlenecks that shape regional manufacturing strategies. Hospital procurement specifications diverge sharply between mature markets with established calibration infrastructure and emerging economies where third-party metrology networks remain underdeveloped.
United States
FDA enforcement of 21 CFR 820 quality system regulations compels medical device manufacturers to document electrical safety verification, sustaining demand for NIST-traceable calibration chains. Group Purchasing Organizations now negotiate separate instrumentation and service line items, unbundling analyzer acquisition from multi-year contracts. The Minneapolis medical device corridor and Boston biotech cluster anchor manufacturing demand for fixed analyzers with MES integration.
Germany
BfArM compliance requirements and the EU Medical Device Regulation's intensified electrical safety documentation mandate drive specification of analyzers with integrated barcode scanning. The Freiburg and Tuttlingen medical device manufacturing clusters specify single-platform units to compress validation timelines. Hospital networks redirect capital budgets from reactive repair toward automated verification systems.
China
NMPA implementation of quality management system rules for medical device registration creates calibration network expansion opportunities. The Yangtze River Delta and Pearl River Delta electronics manufacturing bases demand multi-function analyzers to reduce production-line equipment footprints. Domestic hospital procurement is shifting toward preventive maintenance protocols in tier-one cities.
India
CDSCO's phased implementation of quality management system rules creates first-mover advantage for vendors establishing calibration networks. The Maharashtra and Karnataka medical device manufacturing corridors face documentation requirements that mirror EU MDR templates. Hospital procurement in Delhi-NCR and Chennai is reorganizing around preventive electrical safety testing budgets.
Japan
PMDA medical device quality system inspections require traceable electrical safety verification records across device lifecycles. The Kanto and Kansai precision electronics manufacturing regions supply high-accuracy current transformers to global analyzer manufacturers. METI industrial safety standards create baseline demand for ground fault prevention testing in automotive and electronics plants.
Electrical Safety Analyzers Market Vendor Landscape
Concentration sits with diversified test and measurement conglomerates that leverage hospital-installed bases to sustain recurring calibration revenue. The vendor base spans three tiers: integrated conglomerates with multi-industry portfolios, specialized biomedical safety firms, and regional automation integrators assembling custom test racks. Strategic moves center on unbundling service contracts from hardware sales and embedding cloud-based asset management capabilities.
Among diversified measurement specialists, Fluke Biomedical and Chroma ATE occupy positions that exemplify contrasting geographic anchoring strategies. Fluke Biomedical represents the hospital-installed base archetype with recurring calibration revenue models, while Chroma ATE exemplifies Asian supply chain integration through automated test system capabilities. Megger Group Limited sits within the high-voltage utility specialist tier, competing in insulation resistance segments that require dedicated measurement ranges beyond standard biomedical applications.
| Leading Market Players |
|---|
| Fluke Biomedical |
| Chroma ATE |
| Vitrek |
| HIOKI |
| Datrend Systems |
| Sefelec Eaton |
| Seaward Group |
| Megger Group Limited |
| Ikonix USA |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at precision sensor foundries in Japan and Germany directly determines input cost floors for analyzer manufacturers, compressing margin structures at the mid-tier while premium vendors absorb scale advantages through captive calibration networks. This concentration simultaneously elevates price floors for NIST-traceable units and creates tiered procurement power between hospital GPOs and fragmented manufacturing buyers.
Pricing Analysis
Volume-discount tiering separates enterprise hospital networks securing bundled per-test calibration pricing from mid-size manufacturers purchasing discrete instruments. Certification grade — IEC 61010-2-034 compliance versus basic IEC 61010 — drives the primary price wedge, with after-sales service attachment rates widening spreads further. Pricing pressure stems from third-party metrology laboratories unbundling service contracts and capturing recurring revenue streams. Manufacturing buyers exhibit highest price sensitivity due to capital equipment budget constraints, while German hospital procurement committees prioritize traceability over unit cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery for German and Dutch medical device manufacturers dependent on Asian-sourced precision current transformers. Component supply concentrates in Japan, Germany, and Taiwan for high-accuracy isolation amplifiers and current sensing elements. The analyzer supply chain draws from specialized semiconductor foundries and precision resistor manufacturers, with single-source vulnerability around IEC-certified firmware validation laboratories. Distribution runs through authorized distributor networks with calibration service attachments for portable units, while fixed platforms sell direct with integration engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical safety analyzers market functions as a service-attach play where recurring calibration revenue expands faster than hardware replacement cycles, rewarding vendors that embed cloud-based asset management and per-test pricing models.
For Market Incumbents: Secure hospital-installed base loyalty by embedding wireless data logging and CMMS integration that raises switching costs for clinical engineering departments. Defend against PXI-based modular test rack substitution by certifying multi-function platforms for EU MDR documentation workflows. Prioritize backward integration into precision sensor supply through partnerships with Japanese component specialists to buffer input cost volatility. For New Entrants and Emerging Players: Anchor in India's CDSCO quality management system rollout before calibration infrastructure matures, targeting Maharashtra and Karnataka medical device manufacturing corridors with localized service networks. Penetrate the battery-powered portable segment for distributed healthcare systems in tier-two Chinese cities where preventive maintenance protocols are emerging. Lead with wireless-enabled field units and per-test calibration pricing to bypass entrenched GPO relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with hospital-installed bases exceeding ten thousand units and captive metrology laboratory networks. Long-term viability hinges on software companion development and automated test documentation capabilities that expand addressable market beyond hardware replacement cycles. Target acquisition candidates with FDA 510(k) clearance breadth and CE-MDR technical file portfolios. Monitor IEC 60601-1 fourth edition draft circulation as inflection signal for replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | Establishes recurring revenue moats in CDSCO-regulated Indian manufacturing corridors. |
| Wireless Data Logging Integration | Enables CMMS connectivity that hospital biomed departments now specify in procurement tenders. |
| EU MDR Documentation Software | Captures compliance automation demand from German Class IIb and III device producers. |
| Battery-Powered Field Unit Development | Addresses distributed clinic verification workflows in China's tier-two healthcare systems. |
| Precision Sensor Supply Partnership | Buffers margin compression from Japanese and German component specialist concentration. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with biomedical engineering directors, hospital procurement managers, GPO contracts specialists, and medical device quality assurance leads; and secondary validation against FDA 510(k) databases, IEC standard revision drafts, hospital capital equipment procurement records, and NIST calibration laboratory accreditation files. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented demand drivers including IEC 60601-1 third edition replacement cycles, EU MDR documentation intensity, and preventive maintenance budget reallocation in German and United States healthcare facilities. CAGRs derived from equipment replacement timelines, calibration service attachment rate projections, and manufacturing automation adoption curves. Industry-specific inputs incorporated PXI-based modular system substitution rates and cloud-based asset management penetration.
Material uncertainties — regulatory harmonization delays, precision sensor supply disruptions, and hospital capital budget freezes — sit outside the modeled envelope. Forecasts reflect assumptions about IEC standard revision timing and CDSCO enforcement pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market