
 Holographic Tear Tape Market | 2026-2036
Holographic Tear Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Holographic Tear Tape Market Foresight
Software-defined authentication features embedded in tear tape substrates is consolidating value toward subscription-based brand-protection platforms. Essentra leverages its European manufacturing footprint to sustain high-volume supply contracts with pharmaceutical packagers. Suzhou Image Laser anchors Asia-Pacific demand through specialized holographic mastering capabilities for export cigarette and cosmetics brands. Wavelock Advanced Technology competes on optical complexity, differentiating its product line with multi-channel security architectures that resist counterfeiting replication.
Holographic tear tape comprises a narrow polymer or paper carrier laminated with diffractive optical elements, pressure-sensitive adhesives, and release liners, engineered to provide visible tamper evidence and brand authentication upon package opening. The substrate typically measures 1-5mm in width and incorporates micro-embossed patterns at resolutions exceeding 2,000 lines per millimeter to generate kinematic optical effects. Standard tear tape still occupies the largest volume share across food and beverage cartons, though holographic variants command premium positioning in pharmaceutical and luxury goods packaging where counterfeiting risks escalate. Polypropylene dominates material selection for moisture resistance and tensile strength, while BOPP gains traction in sustainable packaging transitions requiring thinner gauge films with equivalent barrier performance.
FDA pharmaceutical packaging regulations mandate tamper-evident features for over-the-counter drug containers, directly stimulating holographic tear tape specification in US supply chains. EMA's falsified medicines directive and REACH chemical restrictions jointly shape European material compliance, forcing substrate reformulation away from certain plasticizers and adhesives. China's SAMR enforces national packaging standards for food contact materials, creating dual certification burdens for converters serving multinational brand owners. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to regionalize production or absorb cross-border compliance costs as regulatory fragmentation intensifies.
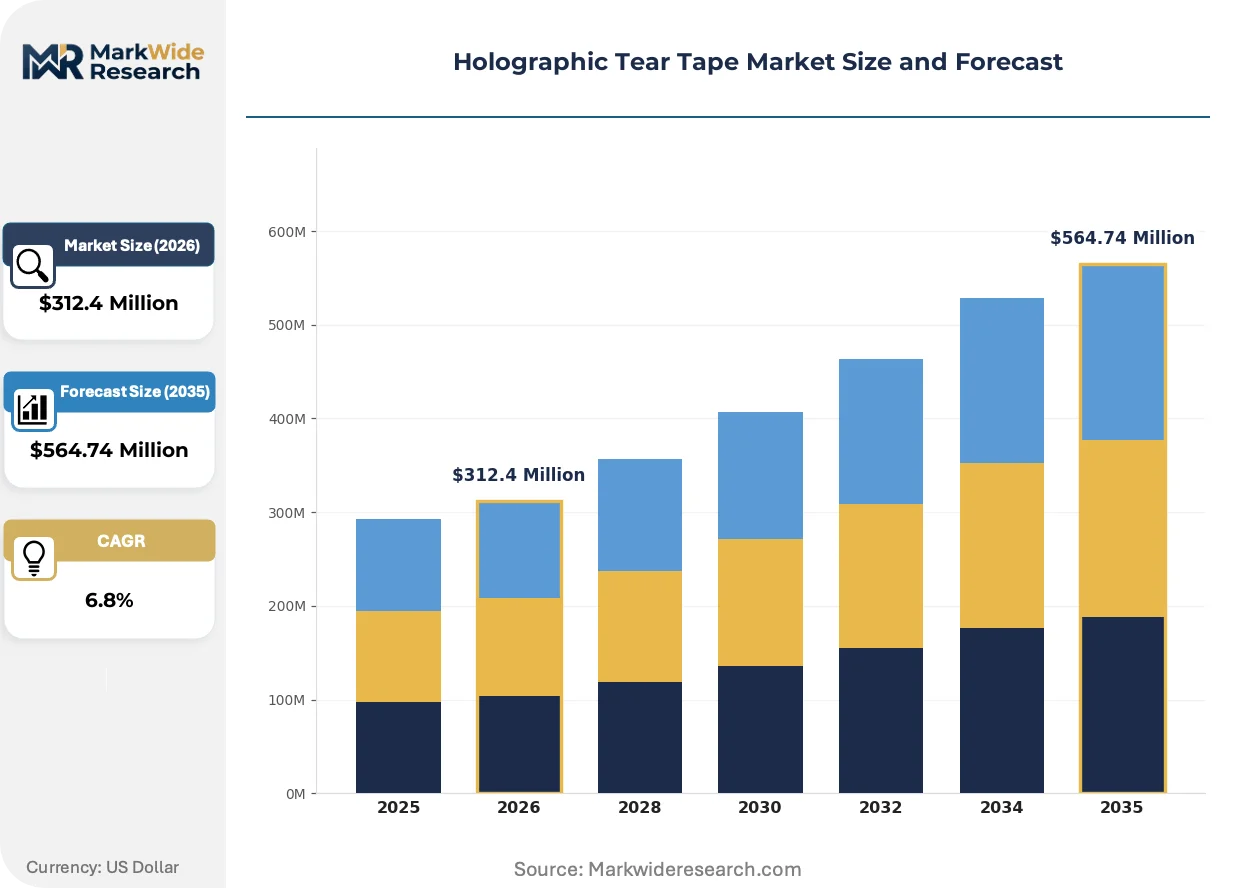
Market Dynamics
Pharmaceutical serialization mandates and REACH chemical restrictions are restructuring substrate formulations and adhesive specifications across holographic tear tape supply chains, forcing converters to regionalize production or absorb cross-border compliance costs.
Growth Catalysts
- FDA Tamper-Evident Mandates:Over-the-counter drug packaging regulations in the United States require visible opening indicators, directly stimulating holographic tear tape specification in pharmaceutical supply chains.
- Polypropylene Substrate Advances:Thinner gauge BOPP films with equivalent moisture barrier performance enable sustainable packaging transitions without sacrificing tensile strength or optical clarity.
- Export-Oriented Cosmetics Manufacturing:Chinese consumer goods producers serving international luxury brands demand authentication features that satisfy multiple destination market standards simultaneously.
Market Restraints
- Adhesive Raw Material Volatility:Pressure-sensitive acrylic formulations face feedstock cost fluctuations tied to petroleum derivatives, compressing converter margins during price spike periods.
- Mastering Equipment Concentration:High-resolution holographic embossing machinery production concentrates among German and Japanese precision engineering suppliers, creating equipment procurement bottlenecks.
- Digital Watermark Substitution:Smartphone-verifiable invisible markers threaten visible holographic solutions in cost-sensitive food and beverage carton segments.
Strategic Opportunities
- Indian Pharmaceutical Export Expansion:CDSCO serialization requirements and rising contract manufacturing volumes create untapped demand for tamper-evident packaging among domestic converters.
- Software-Defined Authentication Convergence:Integration of NFC-readable holographic substrates with cloud-based brand protection platforms enables recurring revenue models beyond physical tape sales.
- EU Extended Producer Responsibility Frameworks:Packaging waste directives incentivize mono-material tear tape designs that simplify recycling streams and command preferential supplier status.
Industry Challenges
- Micro-Embossing Technician Scarcity:Diffractive optical element production requires specialized skills in interferometry and nickel shim electroforming that outpace vocational training program outputs.
- Dual Certification Timeline Compression:Simultaneous FDA pharmaceutical compliance and SAMR food contact material approvals for multinational brand owners extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holographic Tear Tape Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tear Tape, Holographic Tear Tape, Custom Printed Tape, High-Performance Tape Material: Polypropylene, Paper, PVC, BOPP End User: Retail, E-Commerce, Packaging, Manufacturing Application: Product Packaging, Security Sealing, Brand Promotion, Tamper Evidence |
| Companies Covered | Essentra, Tann Germany, Suzhou Image Laser, Octpak, Wavelock Advanced Technology, Taibao Group, Shanghai Okay-Packaging, Bagla Group, Matrix Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holographic Tear Tape Market Shifts & Advancements
Authentication technologies are converging with digital verification infrastructure, while material science advances enable thinner substrates with equivalent security performance. Regulatory fragmentation across pharmaceutical packaging mandates is accelerating regional specialization among converters.
Laser-based holographic mastering is automating the production of multi-channel optical elements that previously required manual alignment and extended setup periods. Pharmaceutical packagers in North America and Europe are adopting these systems to reduce tooling changeover downtime. The technology is automating quality consistency in high-resolution embossing while compressing batch-to-batch variation in kinematic visual effects.
REACH chemical restrictions are prohibiting specific phthalate plasticizers and solvent-based adhesives in European tear tape formulations, forcing substrate reformulation toward water-based alternatives. Industrial consequence includes extended curing times and modified release liner specifications. Pharmaceutical and luxury cosmetics packaging segments are responding by qualifying alternative adhesive suppliers and redesigning laminate structures to maintain peel strength under new compositional constraints.
Brand owners are consolidating supplier relationships around converters offering integrated authentication platforms rather than commodity tear tape products. This consolidation is displacing spot-buy relationships in favor of multi-year framework agreements with technical service components. The pattern is most visible among multinational consumer goods companies operating in China and Southeast Asia, where single-source accountability reduces compliance auditing burdens across dispersed production facilities.
Holographic Tear Tape Market Segmentation
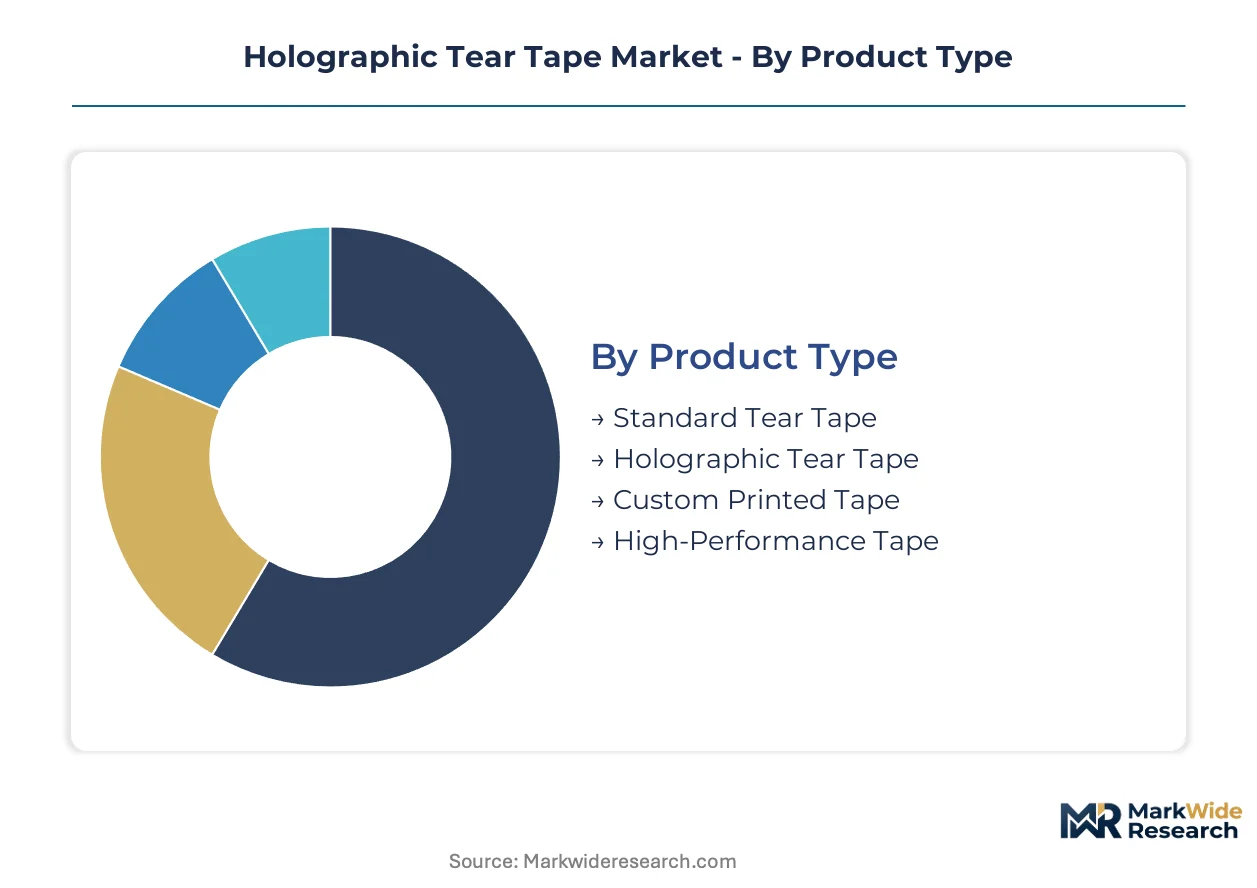
Holographic tear tape segmentation reveals how converters align technical specifications with distinct buyer risk profiles and compliance burdens. Material selection and optical complexity separate pharmaceutical tenders from commodity food carton supply, while application requirements dictate adhesive chemistry and substrate thickness.
Product Type:
Buyers differentiate primarily by authentication intensity and optical sophistication required for their brand protection strategy.
- Holographic Tear Tape:Diffractive optical elements embossed at 2,000+ lines per millimeter generate kinematic visual effects that resist counterfeiting replication. Pharmaceutical packagers in the United States specify these substrates to satisfy FDA tamper-evident mandates for over-the-counter drug containers.
- Standard Tear Tape:Unembossed polymer carriers provide mechanical opening assistance without authentication features. Volume concentrates in food and beverage cartons where cost sensitivity dominates and counterfeiting risks remain minimal.
- Custom Printed Tape:Flexographic or gravure-printed graphics integrate brand logos and variable data alongside base substrate functionality. E-commerce fulfillment centers specify these variants for unboxing experience differentiation.
- High-Performance Tape:Reinforced carriers with specialized adhesives withstand extreme temperature ranges and moisture exposure. Cold-chain pharmaceutical logistics and frozen food packaging drive qualification cycles for these specifications.
Volume sits with Standard Tear Tape; growth tilts toward Holographic Tear Tape.
Material:
Substrate chemistry determines moisture barrier performance, tensile strength, and compatibility with evolving chemical compliance frameworks.
- Polypropylene:Dominates material selection for moisture resistance and tensile strength in pharmaceutical and luxury goods applications. REACH chemical restrictions in Europe are forcing substrate reformulation away from certain plasticizers while maintaining equivalent barrier performance.
- BOPP:Thinner gauge films enable sustainable packaging transitions without sacrificing optical clarity or mechanical integrity. Brand owners in China serving export-oriented cosmetics manufacturers specify BOPP to satisfy multiple destination market standards simultaneously.
- Paper:Renewable substrates appeal to extended producer responsibility frameworks and mono-material recycling streams. EU packaging waste directives incentivize these designs among converters seeking preferential supplier status.
- PVC:Legacy substrate with declining specification due to regulatory pressure on chlorine-based polymers and plasticizer migration concerns. Niche retention in industrial sealing applications with established tooling investments.
Polypropylene captures current volume leadership; BOPP exhibits the steepest expansion trajectory as sustainability mandates intensify.
End User:
Procurement scale and technical specification authority separate enterprise packaging engineers from logistics operators.
- Packaging:Contract converters and integrated packaging manufacturers specify tear tape during carton design and line integration. These buyers consolidate supplier relationships around technical service capabilities and multi-year framework agreements.
- Manufacturing:Brand-owning producers of pharmaceuticals, cosmetics, and consumer goods directly procure authentication substrates. CDSCO serialization requirements in India are stimulating tamper-evident specification among domestic pharmaceutical exporters.
- Retail:Private label and house-brand operators specify tear tape through packaging service agreements rather than direct substrate procurement. Price sensitivity constrains holographic adoption to premium product lines.
- E-Commerce:Fulfillment-centric buyers prioritize opening experience and return-fraud prevention over optical authentication. Digital watermark substitution threatens visible holographic solutions in this cost-sensitive segment.
Manufacturing directs specification authority; Packaging intermediaries control procurement volume.
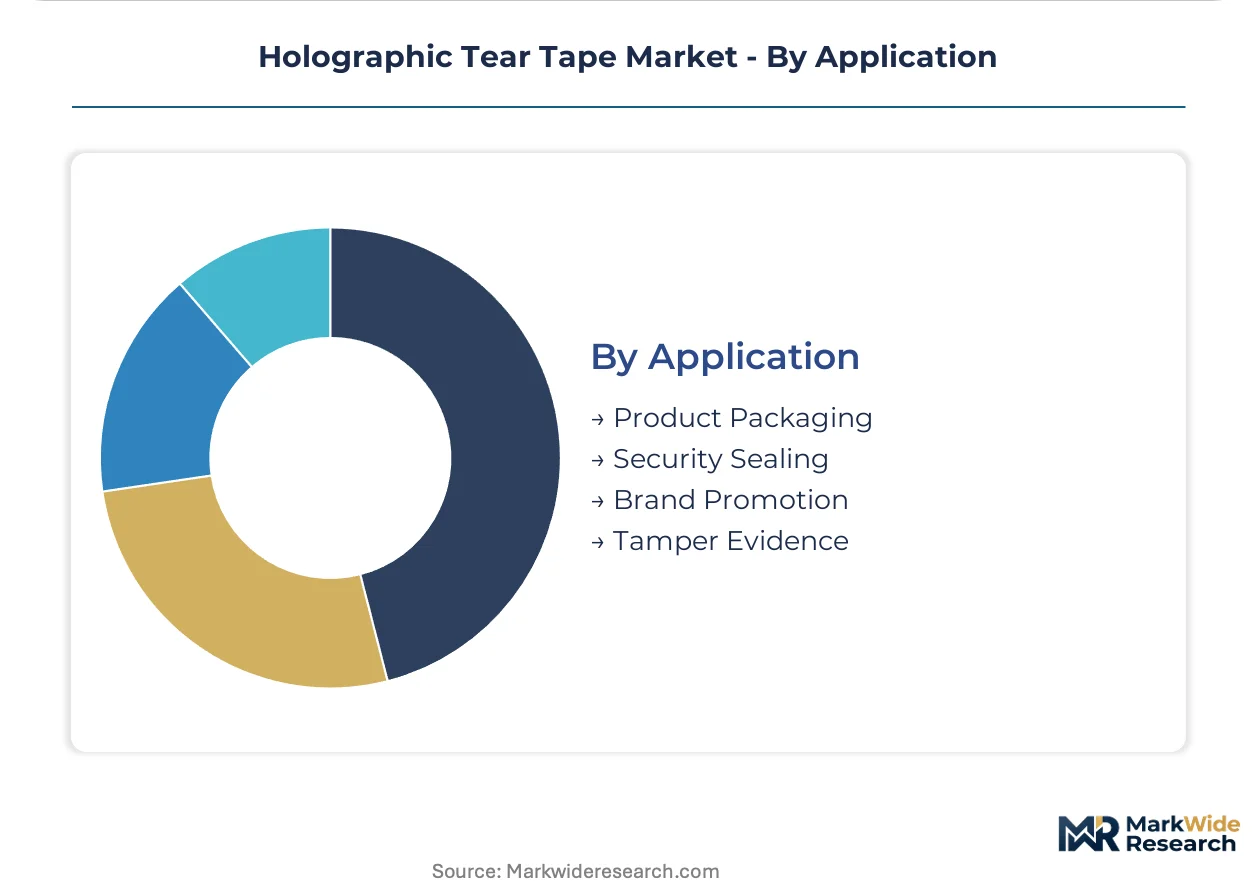
Application:
Functional requirements for visibility, permanence, and verification method determine substrate architecture and adhesive selection.
- Tamper Evidence:Irreversible visual destruction upon opening provides the primary technical requirement. FDA pharmaceutical packaging regulations directly stimulate holographic tear tape specification in US supply chains for over-the-counter drug containers.
- Security Sealing:Authentication features must resist replication while enabling rapid visual verification at point of sale. Multi-channel optical architectures from specialized converters address this requirement in luxury cosmetics and tobacco.
- Product Packaging:Mechanical opening assistance combines with brand presentation in food, beverage, and personal care cartons. Standard tear tape variants dominate this volume-driven segment.
- Brand Promotion:Holographic visual effects enhance shelf presence and unboxing experience for premium consumer goods. Chinese export-oriented manufacturers serving international luxury brands drive specification complexity.
Tamper Evidence commands premium positioning; Product Packaging generates baseline volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian precision manufacturing clusters, while consumption splits between pharmaceutical packaging hubs in North America and luxury goods export corridors in Western Europe.
United States
FDA tamper-evident mandates for over-the-counter pharmaceuticals drive specification of holographic tear tape in packaging supply chains. The agency's packaging regulations directly stimulate substrate procurement from domestic converters. New Jersey and Pennsylvania host dense concentrations of pharmaceutical contract manufacturers integrating authentication features into carton lines.
Germany
EMA's falsified medicines directive and REACH chemical restrictions jointly shape European material compliance standards. ECHA's prohibitions on specific phthalate plasticizers force substrate reformulation toward water-based adhesive alternatives. The Rhine-Ruhr industrial corridor anchors high-resolution holographic embossing equipment manufacturing and precision optics supply chains.
China
SAMR enforces national packaging standards for food contact materials, creating dual certification burdens for converters serving multinational brand owners. Suzhou Image Laser anchors Asia-Pacific demand through specialized holographic mastering capabilities. The Yangtze River Delta concentration of export-oriented cosmetics manufacturers drives specification complexity for authentication substrates.
India
CDSCO serialization requirements stimulate tamper-evident packaging specification among domestic pharmaceutical exporters. The regulator's track-and-trace mandates for exported medicines create untapped demand for holographic tear tape among domestic converters. Maharashtra and Gujarat pharmaceutical manufacturing clusters are qualifying authentication substrate suppliers for contract manufacturing volumes.
United Kingdom
Post-Brexit regulatory divergence from EU REACH frameworks creates parallel compliance pathways for packaging material suppliers. The Medicines and Healthcare products Regulatory Agency maintains pharmaceutical packaging standards that preserve tamper-evident requirements. Southeast England packaging design houses specify holographic tear tape for luxury cosmetics brands serving Middle Eastern export markets.
Holographic Tear Tape Market Competitive Landscape
Top-tier vendors anchor high-volume pharmaceutical supply contracts, while mid-scale specialists occupy regional converter niches and technology-focused players differentiate on optical complexity. The vendor base stratifies across three functional tiers: integrated packaging conglomerates with multi-material portfolios, holographic mastering specialists with captive embossing capacity, and regional adhesive laminators serving spot-buy relationships. Consolidation pressure intensifies as brand owners reduce supplier counts. Strategic moves center on geographic expansion into Indian pharmaceutical corridors and backward integration into holographic mastering equipment.
Among Asia-Pacific-based specialists, Suzhou Image Laser exemplifies the mastering-integrated archetype, while Wavelock Advanced Technology occupies a position emphasizing multi-channel optical architectures. Essentra represents the European manufacturing footprint archetype sustaining high-volume supply relationships. These three entities anchor the competitive structure visible in procurement patterns across pharmaceutical and luxury goods packaging segments.
| Leading Market Players |
|---|
| Essentra |
| Tann Germany |
| Suzhou Image Laser |
| Octpak |
| Wavelock Advanced Technology |
| Taibao Group |
| Shanghai Okay-Packaging |
| Bagla Group |
| Matrix Technologies |
| Others |
Supply & Pricing Matrix
Pharmaceutical contract manufacturers in the United States and Europe anchor demand for holographic tear tape, concentrating procurement volume among a narrow tier of FDA-compliant converters. This buyer concentration sustains contract-based long-term offtake pricing with volume-scale and certification-level differentiation, while spot-buy relationships in food and beverage cartons face sharper cost compression.
Pricing Analysis
Margin tightening in standard tear tape reflects feedstock volatility in petroleum-derived acrylic adhesives and thinner-gauge BOPP film transitions. Pricing stratifies across pharmaceutical-grade holographic substrates, food-carton standard variants, and custom-printed e-commerce specifications, with pharmaceutical packagers showing least price sensitivity due to regulatory compliance mandates. Cost-down pressure on commodity converters accelerates as digital watermark substitution threats emerge in cost-sensitive segments.
Supply Chain Analysis
Cross-border freight costs from German and Japanese precision engineering suppliers to Asia-Pacific embossing facilities compress converter margins during logistics disruptions. Supply concentrates in China for holographic mastering and substrate lamination, Germany for high-resolution embossing equipment, and India for emerging pharmaceutical converter capacity. Raw material dependencies include polypropylene resin, nickel shims for electroforming, and pressure-sensitive acrylic formulations. Single-source vulnerability in mastering equipment procurement creates supply chain risk. Distribution runs through integrated packaging conglomerates with multi-year framework agreements rather than spot-buy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-resolution holographic embossing equipment scarcity props pricing power for mastering-integrated converters, constraining supply expansion and sustaining margin premiums for qualified suppliers.
For Market Incumbents: Extend holographic mastering capabilities through backward integration into nickel shim electroforming and interferometry technician training programs. Digital watermark substitution threats in food and beverage cartons demand defensive certification investment in FDA and EMA pharmaceutical compliance tiers. Capacity addition in Maharashtra and Gujarat pharmaceutical corridors secures long-term offtake relationships with CDSCO-mandated exporters. For New Entrants and Emerging Players: Smartphone-verifiable NFC-readable holographic substrates offer a technology-first wedge into software-defined authentication platforms with recurring revenue potential. Indian pharmaceutical contract manufacturing presents the most penetrable geography, with CDSCO serialization requirements stimulating tamper-evident specification among domestic converters lacking mastering capabilities. A go-to-market angle through cloud-based brand protection platform partnerships bypasses capital-intensive embossing equipment barriers. For Investors and Strategic Acquirers: The window for entry favors mastering-integrated mid-scale specialists with captive holographic embossing capacity and established pharmaceutical compliance certifications. Long-term viability hinges on converter consolidation around integrated authentication platforms rather than commodity tear tape supply. The signal to watch is EMA and FDA regulatory harmonization pressure forcing dual-certification timeline compression that favors scaled suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mastering Equipment | Captive holographic embossing capacity reduces German and Japanese equipment procurement bottlenecks for converters. |
| Software-Defined Authentication Platform Launch | NFC-readable substrate integration enables recurring revenue models beyond physical tape sales for brand owners. |
| Indian Pharmaceutical Corridor Expansion | CDSCO serialization mandates create untapped demand for tamper-evident packaging among domestic contract manufacturers. |
| Mono-Material Tear Tape Design Certification | EU Extended Producer Responsibility frameworks incentivize recyclable substrates with preferential supplier status. |
| Water-Based Adhesive Formulation Transition | REACH chemical restrictions force substrate reformulation toward compliant alternatives for European pharmaceutical packagers. |
Research Methodology
Multi-period observation of holographic mastering equipment utilization rates, pharmaceutical packaging tender awards, and REACH compliance certification timelines anchored the trend analysis, supplemented by interviews with packaging engineers at contract manufacturers, procurement leads at multinational consumer goods companies, holographic embossing technicians, and regulatory affairs specialists at FDA and EMA compliance consultancies. Secondary validation drew from FDA packaging guidance documents, EMA falsified medicines directive filings, SAMR food contact material standards, CDSCO serialization circulars, and customs trade data on polypropylene substrate imports. Bottom-up tear tape volume estimates and top-down pharmaceutical packaging spend analysis were triangulated against converter capacity disclosures.
Segment-weighting approaches modeled product type splits across holographic, standard, custom-printed, and high-performance tape variants, material transitions between polypropylene and BOPP substrates, end-user procurement patterns distinguishing packaging intermediaries from manufacturing brand owners, and application requirements spanning tamper evidence through brand promotion. CAGRs were derived from regression analysis of historical tender award values and projected pharmaceutical serialization mandate implementation timelines across the analysis window. Industry-specific forecast inputs included laser-based holographic mastering automation adoption curves and dual-certification timeline compression effects on product development cycles.
Several conditions sit outside the modeled scope, including unannounced regulatory harmonization between FDA and EMA frameworks, breakthrough advances in digital watermark smartphone verification accuracy, and geopolitical disruptions to German and Japanese precision equipment export channels. Forecasts reflect assumptions about sustained pharmaceutical serialization mandate enforcement and REACH chemical restriction expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Security Tape Market
Tapes
PVC Tapes Market
Tapes
Paper Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Breathable Tape Market
Tapes
Twist Tube Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Global Surface Protection Tapes Market
Tapes
Wing Walk Tapes Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Tape Backing Materials Market
Tapes
Tape Stretching Line Market
Tapes
Building and Construction Tapes Market
Tapes
Packaging Tape Printing Market
Tapes
Edge Band Tapes Market
Tapes
Raffia Tape Stretching Line Market