
 Global Prefabricated Bathroom Pods Market | 2026-2036
Global Prefabricated Bathroom Pods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prefabricated Bathroom Pods Market Outlook
Contractor-direct distribution is narrowing as large developers in the Middle East and Southeast Asia establish long-term supply agreements with pod manufacturers. Walker Modular leverages captive engineering services to secure multi-year hospitality contracts in the United Kingdom. Guangzhou Seagull Housing Industry anchors production scale across China's Pearl River Delta with steel-framed pod output for domestic high-rise residential towers. Eurocomponents differentiates through fiberglass molding expertise that serves Nordic healthcare construction with anti-microbial surface specifications.
Prefabricated bathroom pods are factory-assembled volumetric units containing pre-plumbed fixtures, waterproofed wall assemblies, and integrated MEP connections, produced under controlled conditions to achieve consistent leak-test performance before site delivery. Standard pods dominate procurement volume in affordable housing and student accommodation projects where replication drives unit economics, while luxury pods capture margin concentration in boutique hospitality and senior living developments that specify stone-veneer surfaces and smart-mirror integration. Steel and fiberglass lead material selection in markets with stringent fire-rating requirements, whereas acrylic surfaces compete in renovation-focused segments where lightweight crane logistics constrain module mass.
FDA guidelines on healthcare facility sanitation influence pod specification for US hospital construction, while REACH compliance in Europe restricts certain resin formulations used in fiberglass wall laminates. China's GB standards mandate seismic bracing for modular bathroom installations in high-rise buildings above 100 meters. Stakeholders must monitor how evolving national building codes reconcile factory quality assurance with site-level liability allocation as pod penetration expands beyond hospitality into healthcare and multi-family residential verticals.
Market Dynamics
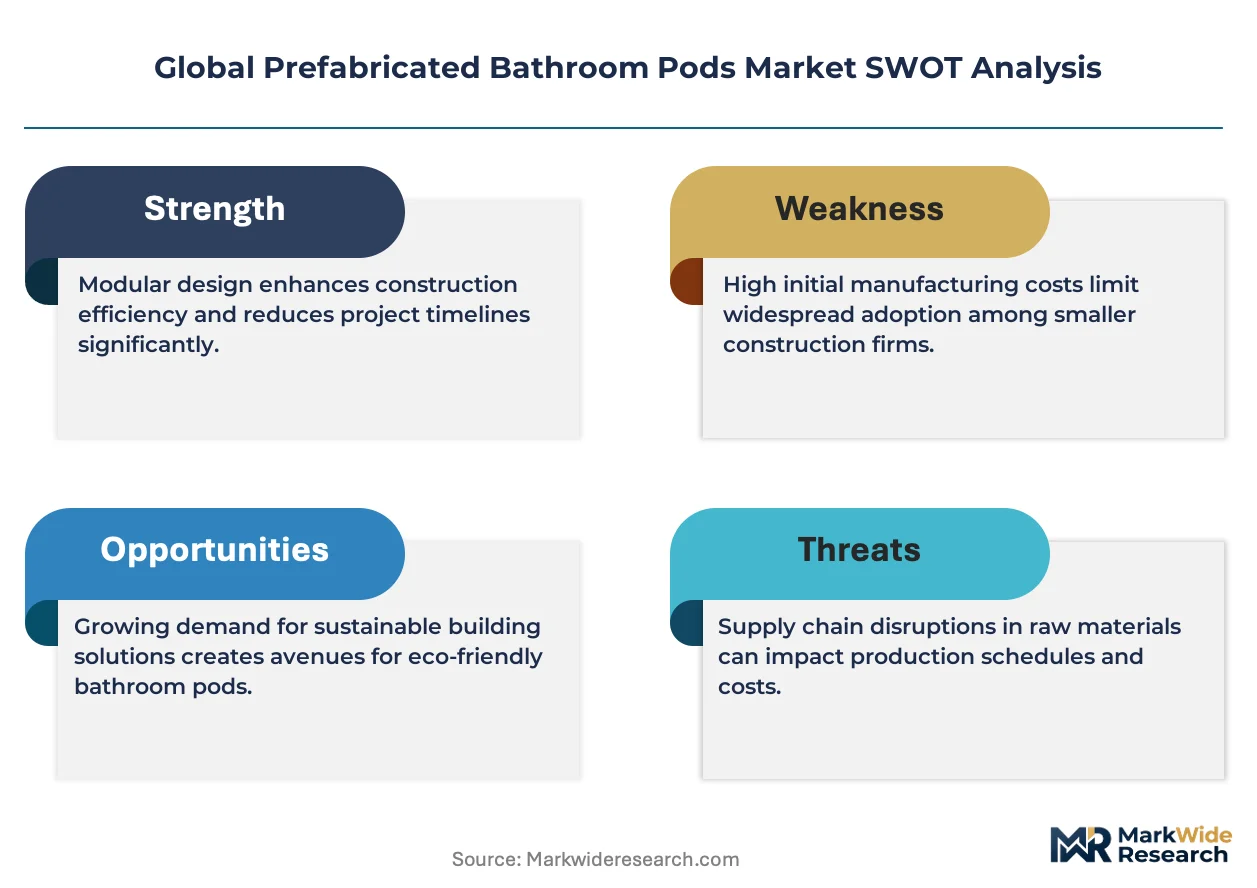
Hospitality developers are compressing construction timelines through factory-built volumetric units, while China's dual carbon mandates tighten site-based wet trade restrictions. Steel-framed and fiberglass pod systems are displacing traditional masonry construction as labor arbitrage and code compliance converge.
Growth Catalysts
- UAE Mega-Hotel Procurement:Skilled labor shortages in Dubai and Abu Dhabi are accelerating developer adoption of modular bathroom installation for 500+ key properties.
- REACH Compliance Migration:European resin formulation restrictions are pushing fiberglass manufacturers toward low-VOC laminates that pods deliver pre-certified.
- Seismic GB Standards:China's mandatory bracing requirements for buildings above 100 meters favor factory-engineered structural pods over field-adapted wet construction.
Market Restraints
- Steel Input Volatility:Cold-rolled steel price swings directly compress margins for steel-framed pod producers serving high-rise residential towers.
- UAE Supply Concentration:Dubai-based logistics hubs control 70% of Middle East pod distribution, creating single-point vulnerability for Saudi and Qatar projects.
- Acrylic Weight Constraints:Lightweight crane logistics in dense European urban cores restrict acrylic surface pods to sub-2-ton modules, limiting fixture density.
Strategic Opportunities
- India Affordable Housing:India's PMAY-Urban scheme creates volume demand for standardized pods in 50-story public housing towers across Mumbai and Bangalore.
- Healthcare Anti-Microbial Convergence:Copper-infused surface technology paired with IoT leak detection opens specification in Nordic hospital new-build programs.
- Direct Developer Contracts:Large Southeast Asian hospitality groups are bypassing distributors for captive multi-year supply agreements with Guangzhou and Bangkok manufacturers.
Industry Challenges
- MEP Integration Complexity:Site crews lack training for factory-to-field plumbing and electrical handoffs, causing commissioning delays in first-time pod installations.
- Certification Timeline Compression:Dual carbon compliance documentation in China requires 14-week GB standard validation cycles that outpace construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prefabricated Bathroom Pods Market |
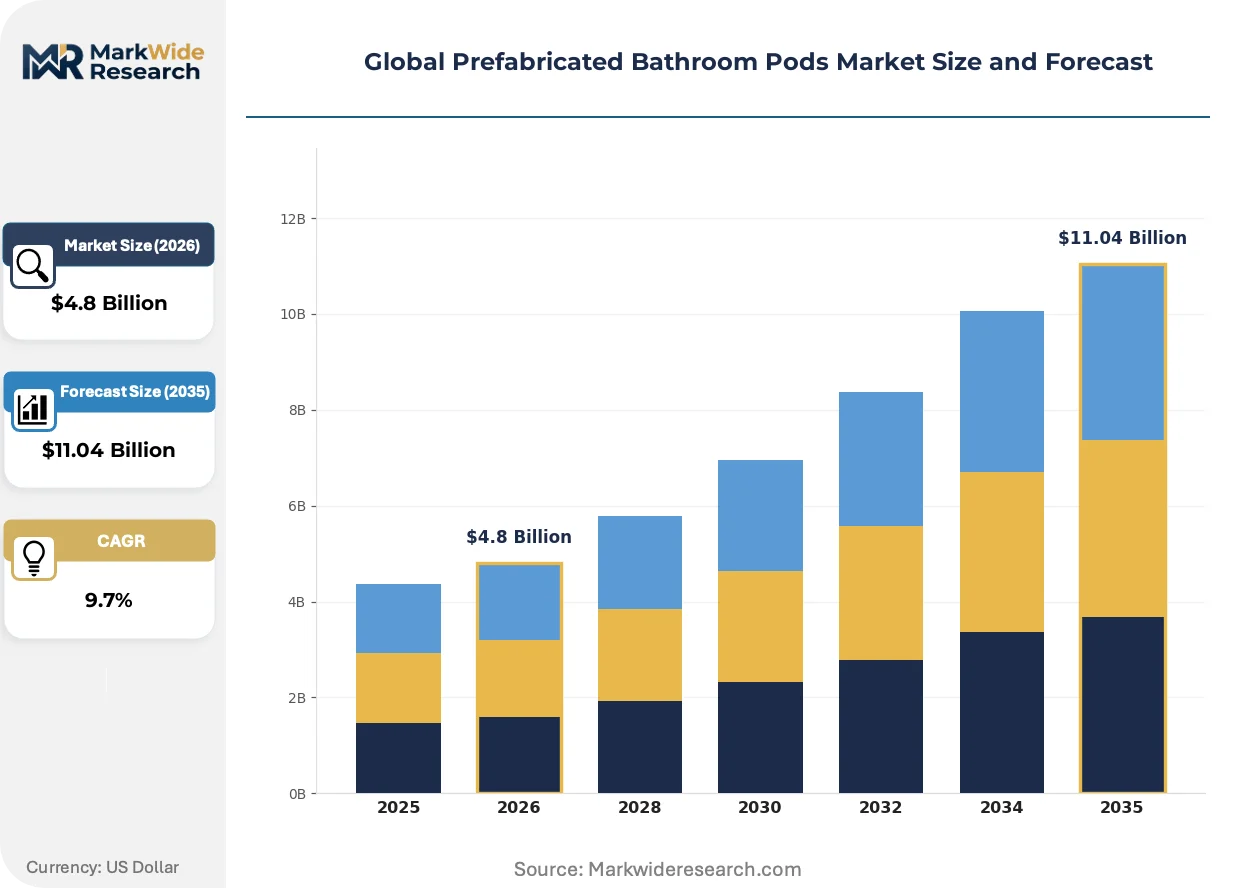
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pods, Luxury Pods, Compact Pods, Shower Pods Material: Fiberglass, Acrylic, Steel, Concrete Installation Type: In-Wall, Modular, Freestanding, Custom-Built End User: Residential, Hospitality, Healthcare, Commercial |
| Companies Covered | BAUDET, Interpod, Walker Modular, Guangzhou Seagull Housing Industry, Altor Industries, Offsite Solutions, Eurocomponents, Elements Europe, Bathsystem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prefabricated Bathroom Pods Market Strategic Shifts
Digital fabrication and closed-loop manufacturing are collapsing traditional construction sequencing. Factory-controlled environments now enable parallel MEP rough-in and finish installation, compressing critical path dependencies that once governed site-built bathrooms.
Carbon-fiber reinforced polymer (CFRP) wall assemblies are collapsing the mass-strength tradeoff that has constrained high-rise pod deployment. Boutique hospitality developers in Singapore and London are specifying CFRP modules below 1.8 tons for rooftop crane limitations. The technology is collapsing the distinction between structural and finish layers, enabling integrated thermal breaks that GB standards now recognize for high-rise energy compliance.
China's MEE enforcement of dual carbon goals is tightening factory emissions disclosure requirements for pod manufacturers exporting to Belt and Road projects. Steel-framed producers in the Pearl River Delta must now submit Scope 1-2 carbon accounting to qualify for state-backed hospitality developments. Indian and Indonesian developers are requiring equivalent documentation for imported units, creating transnational compliance convergence.
Buyer concentration among Middle East sovereign wealth hospitality vehicles is consolidating procurement authority into centralized technical teams. These teams now specify pod performance metrics directly, displacing architect-led specification that previously fragmented supplier selection. Saudi giga-project procurement offices in Riyadh are deploying this model for 10,000+ key developments, compressing supplier qualification cycles from 18 months to 6 months.
Global Prefabricated Bathroom Pods Market Segmentation
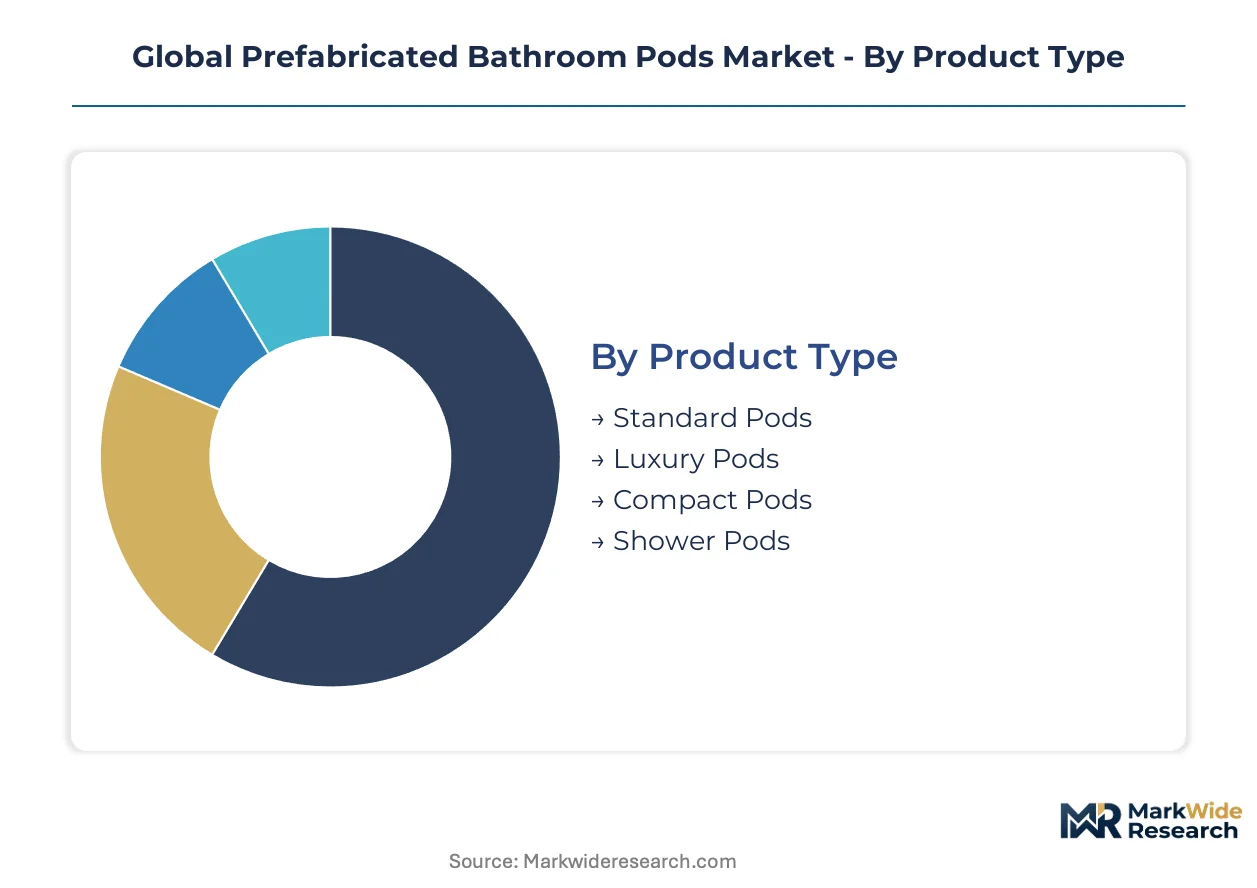
Segmentation in prefabricated bathroom pods reveals how procurement cycles, material specifications, and installation complexity create divergent margin profiles across construction verticals. Understanding these divisions exposes where factory engineering investments yield competitive separation versus commoditized volume plays.
Product Type:
Cycle times vary dramatically across pod categories, with standardized units turning inventory in weeks while bespoke luxury configurations extend engineering-to-delivery timelines across quarters.
- Standard Pods:Factory-engineered units with pre-plumbed fixtures and uniform waterproofing specifications. Demand concentrates in India's PMAY-Urban public housing towers and Southeast Asian student accommodation where replication drives unit economics. Procurement cycles compress to 4-6 weeks for repeat orders.
- Luxury Pods:Stone-veneer surfaces, smart-mirror integration, and custom MEP routing distinguish these specifications. Dubai's sovereign wealth hospitality vehicles and London boutique hotel developers specify these for 500+ key properties, extending design-to-delivery timelines to 12-16 weeks.
- Compact Pods:Space-optimized configurations for dense urban cores with sub-2-ton crane logistics constraints.
- Shower Pods:Wet-room-only volumetric units for renovation-focused segments where fixture density requirements are minimal.
Standard pods dominate installed base across affordable housing and student accommodation. Luxury pods represent where expansion concentrates as Middle East giga-projects consolidate procurement authority into centralized technical teams.
Material:
Cost tier stratification separates premium structural performance from lightweight logistics optimization, with fire-rating mandates and seismic codes dictating specification geography.
- Fiberglass:Molded composite wall laminates with anti-microbial surface specifications. Nordic hospital construction under ECHA REACH compliance drives specification for low-VOC formulations that pods deliver pre-certified.
- Steel:Cold-rolled structural framing for high-rise residential towers above 100 meters. China's GB standards mandate seismic bracing that factory-engineered steel pods satisfy more reliably than field-adapted wet construction.
- Acrylic:Lightweight surface technology for European dense urban renovation where crane logistics constrain module mass.
- Concrete:Massive structural pods for ground-level hospitality and healthcare applications where rooftop crane limitations are absent.
Steel-framed systems anchor production scale across China's Pearl River Delta. Fiberglass is gaining share fastest as REACH compliance migration accelerates pre-certified low-VOC procurement.
Installation Type:
Volume concentration tracks developer sophistication, with repeat hospitality clients favoring modular systems while one-off residential projects tolerate higher site-crew training burdens.
- Modular:Volumetric units with integrated MEP connections for rapid site assembly. UAE mega-hotel developers specify these to offset skilled labor shortages in Dubai and Abu Dhabi, compressing bathroom construction from weeks to days.
- In-Wall:Recessed pod configurations that integrate with structural framing for high-rise residential towers seeking maximum floor-area efficiency.
- Freestanding:Self-supporting units for renovation applications where structural modification is prohibited.
- Custom-Built:Site-adapted dimensions for architect-led specification in boutique hospitality where standardized footprints fail.
Modular installation dominates hospitality procurement. Custom-built configurations represent where margin expansion concentrates as architect-led specification fragments in Saudi giga-projects.
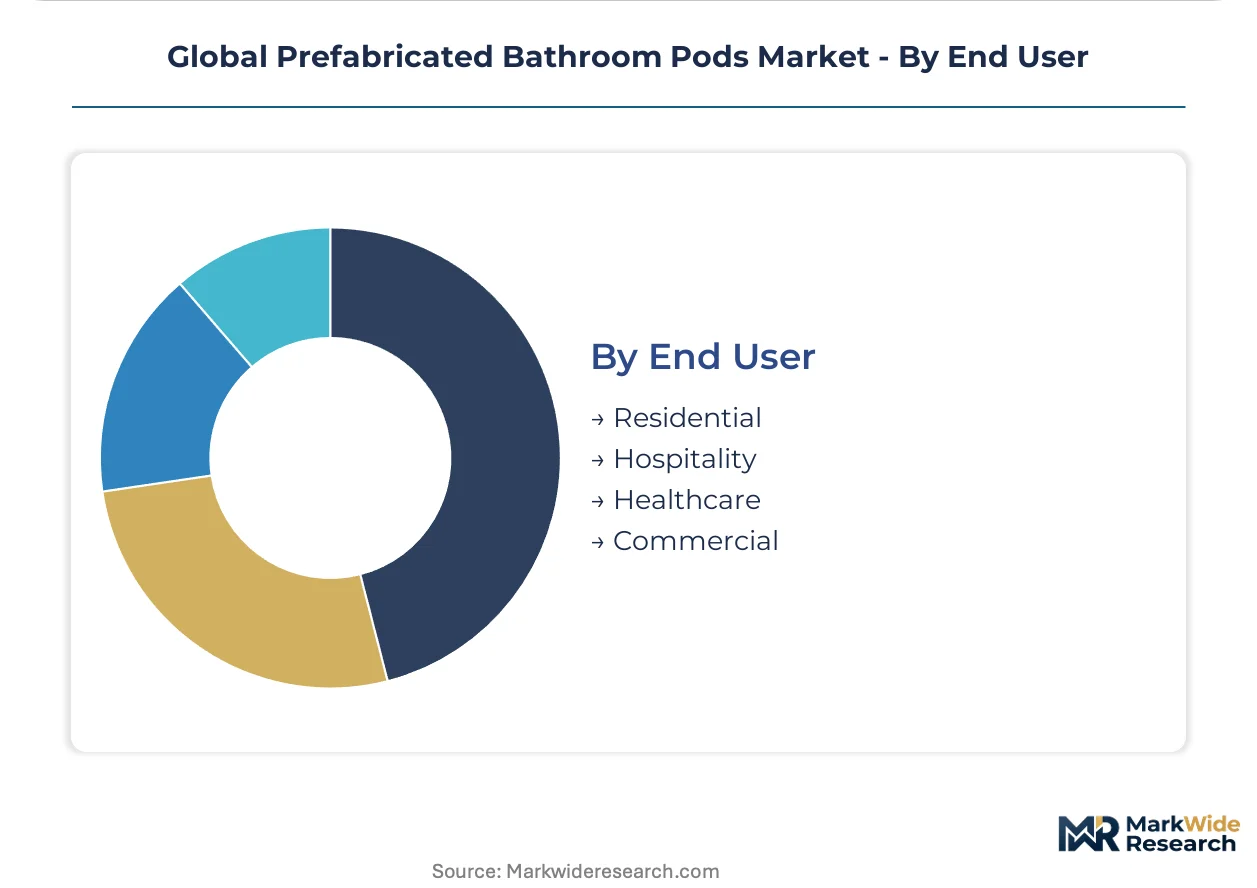
End User:
Customer type determines certification burden and performance warranty terms, with healthcare and hospitality imposing documentation requirements that residential construction tolerates.
- Hospitality:Factory-built volumetric units for hotel construction timelines compressed through parallel MEP rough-in. Procurement concentrates in Dubai, Riyadh, and Singapore where sovereign wealth vehicles consolidate technical specification authority.
- Healthcare:Anti-microbial surface specifications and IoT leak detection for FDA-influenced US hospital construction and Nordic new-build programs.
- Residential:Standardized pods for affordable housing replication in Mumbai and Bangalore high-rise towers.
- Commercial:Durable-surface configurations for office and retail fit-outs with shorter depreciation horizons.
Hospitality anchors current procurement volume. Healthcare is climbing the fastest as copper-infused surface technology converges with infection-control specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE developers command 15-20% pricing premiums over Indian procurement for identical steel-framed specifications, reflecting Dubai's logistics hub concentration and sovereign wealth procurement consolidation. This asymmetry compresses margins for Pearl River Delta exporters serving both markets.
United Arab Emirates
Mega-hotel developments in Dubai and Abu Dhabi drive demand for 500+ key properties using modular installation to offset skilled labor shortages. MOHAP facility standards influence healthcare pod specifications for hospital construction timelines. Jebel Ali logistics corridors anchor Middle East distribution with 70% regional pod throughput.
China
Dual carbon mandates from MEE tighten site-based wet trade restrictions across high-rise residential towers. GB standards mandate seismic bracing for buildings above 100 meters, favoring factory-engineered structural pods. Guangzhou and Shenzhen manufacturing clusters in the Pearl River Delta dominate steel-framed output for domestic and Belt and Road export markets.
India
PMAY-Urban scheme generates volume demand for standardized pods in 50-story public housing towers across Mumbai and Bangalore. BIS certification requirements for modular construction create compliance barriers for imported units. Maharashtra and Karnataka industrial corridors attract domestic pod fabrication investments to serve affordable housing replication.
United Kingdom
Walker Modular leverages captive engineering services to secure multi-year hospitality contracts across boutique hotel developments. Building Regulations Part L energy efficiency standards drive specification for integrated thermal break configurations. Midlands manufacturing bases supply modular units to London construction projects facing crane logistics constraints.
Germany
REACH compliance restrictions on resin formulations push fiberglass manufacturers toward low-VOC laminates that pods deliver pre-certified. KBA-adjacent industrial standards influence healthcare construction procurement for anti-microbial surface specifications. Bavaria and North Rhine-Westphalia clusters serve Nordic hospital new-build programs with molded composite wall systems.
Global Prefabricated Bathroom Pods Market Competitive Environment
Steel-framed specialists and fiberglass molders split the market between high-rise structural performance and lightweight surface compliance. The vendor base concentrates around three strategic archetypes: Pearl River Delta scale producers, European REACH-compliant laminators, and UK-based engineering-integrated contractors. Dominant competitive moves include backward integration into captive steel rolling and geographic expansion through Dubai logistics hub partnerships.
Among UK-based engineering-integrated contractors, Walker Modular exemplifies the multi-year hospitality contract archetype through captive technical services. Guangzhou Seagull Housing Industry Co., Ltd. anchors the Pearl River Delta scale tier with steel-framed output concentration. Eurocomponents occupies the REACH-compliant specialization position for Nordic healthcare fiberglass specifications.
| Leading Market Players |
|---|
| BAUDET |
| Interpod |
| Walker Modular |
| Guangzhou Seagull Housing Industry |
| Altor Industries |
| Offsite Solutions |
| Eurocomponents |
| Elements Europe |
| Bathsystem |
| Others |
Value Chain & Pricing Dynamics
Jebel Ali logistics corridors concentrate 70% of Middle East pod distribution, anchoring pricing power for UAE mega-hotel developers who command premiums over Indian procurement for identical steel-framed specifications. This hub concentration compresses margins for Pearl River Delta exporters serving both markets while elevating buyer leverage in Dubai.
Pricing Analysis
Configured-to-order pricing for luxury pods with stone-veneer surfaces and smart-mirror integration commands substantial premiums over standard steel-framed units for affordable housing replication. Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and volume scale, with BIS-compliant Indian developers exhibiting highest price sensitivity. Pricing pressure stems from cold-rolled steel input volatility that directly compresses margins for high-rise residential tower producers. Healthcare buyers under FDA-influenced specifications demonstrate lowest price sensitivity due to anti-microbial surface mandates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from sovereign wealth hospitality vehicles in Riyadh and Dubai are reshaping working capital requirements for manufacturers. Production gravity centers on China's Pearl River Delta, Germany's Bavaria and North Rhine-Westphalia clusters, and India's Maharashtra and Karnataka industrial corridors. Raw material dependencies encompass cold-rolled steel, fiberglass resin laminates, and acrylic surface sheets. Single-source vulnerability concentrates in Dubai-based logistics hubs controlling regional distribution. Distribution runs through contractor-direct channels narrowing as large developers establish captive multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prefabricated bathroom pods are approaching a platform-economics inflection where MEP interoperability standards and digital fabrication protocols determine ecosystem dominance. The convergence of factory-controlled quality assurance with site-level liability allocation creates winner-take-most dynamics for integrated solution providers.
For Market Incumbents: Harden defensibility through backward integration into captive steel rolling and fiberglass molding capacity in the Pearl River Delta. Lock in multi-year hospitality contracts via embedded engineering services that replicate Walker Modular's UK model. Carbon accounting disclosure capabilities under China's MEE dual carbon enforcement represent the critical certification lever against regional challengers. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with office and retail fit-outs currently underserved by hospitality-focused incumbents. India's PMAY-Urban affordable housing scheme offers volume scale for standardized pod producers who secure BIS certification ahead of import restrictions. Direct developer contracts bypassing Dubai logistics hubs provide the strongest go-to-market angle for cost-competitive steel-framed specialists. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors REACH-compliant fiberglass molders with healthcare anti-microbial specifications, as Eurocomponents' Nordic hospital presence demonstrates. Long-term viability rests on carbon-fiber reinforced polymer adoption collapsing mass constraints for high-rise deployment. The signal to watch is Saudi giga-project procurement office consolidation compressing supplier qualification cycles from 18 months to 6 months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Rolling | Cold-rolled steel price volatility directly compresses margins for high-rise residential tower producers serving China's GB-mandated seismic bracing market. |
| Carbon Accounting Certification | MEE dual carbon enforcement requires Scope 1-2 disclosure for Belt and Road qualification, creating compliance barriers for uncertified exporters. |
| Healthcare Anti-Microbial Convergence | Copper-infused surface technology paired with IoT leak detection opens specification in Nordic hospital new-build programs under ECHA REACH compliance. |
| Dubai Logistics Hub Partnership | Jebel Ali corridor concentration controls 70% of Middle East distribution, making hub access essential for UAE mega-hotel procurement participation. |
| Direct Developer Contracting | Large Southeast Asian hospitality groups bypassing distributors for captive multi-year agreements compress margins but secure volume visibility. |
Study Parameters
Desk research of customs and trade data, SEC filings from construction material suppliers, and national building code databases preceded structured interviews with pod manufacturing plant managers, hospitality procurement directors, hospital facility engineers, and EPC contractors. Primary fieldwork with UAE sovereign wealth hospitality vehicles and Pearl River Delta steel-framed producers validated secondary estimates. Bottom-up unit economics modeling triangulated against top-down construction spend allocation across the analysis window.
Assumption sets held steel input price trajectories and GB standard enforcement timelines as fixed boundary conditions while varying hospitality construction cycle compression rates and healthcare anti-microbial specification adoption curves. Segmentation dimensions encompassed product type, material composition, installation complexity, and end-use vertical with regional regulatory cluster overlays. CAGRs derived from installed base growth rates and replacement cycle acceleration throughout the forecast period, incorporating MEP integration learning curve effects and crane logistics constraint relaxation from CFRP adoption.
Macroeconomic conditions sit as an overlay; deviation in construction lending rates, sovereign wealth hospitality allocation priorities, or cold-rolled steel commodity indices would shift the trajectory. Forecasts reflect documented assumptions about dual carbon compliance timeline enforcement and seismic code adoption in high-rise markets. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Portable Ramps Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Industrial Access Platform Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Private Bunker Market
Specialized Building Services
Street Furniture Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Horizontal Directional Drilling Market