
 Industrial Access Platform Market | 2026-2036
Industrial Access Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Access Platform Market Outlook
Modular platform configurations is pivoting buyer procurement patterns across the industrial access sector. EGA leverages its aluminum fabrication expertise to dominate lightweight platform segments. Southern Metal Fabricators anchors its position through custom steel configurations for heavy-process industries. Zarges differentiates via European-engineered folding systems that compete on transport efficiency.
An industrial access platform is a fabricated elevated structure—typically constructed from aluminum or steel with specified load ratings between 300 and 1,000 pounds—designed to provide safe personnel positioning for maintenance, inspection, or material handling tasks. Scissor lifts and boom lifts command the largest installed base, though electric-powered variants are capturing the fastest replacement cycle as facilities phase out diesel units for indoor air-quality compliance. Hydraulic technology still occupies the margin-rich heavy-lift segment where pneumatic alternatives lack sufficient force density.
OSHA standards for fall protection, ANSI A92 aerial lift requirements, and EPA emissions regulations for non-road engines collectively reshape product design priorities and fleet replacement timelines. The EU Machinery Directive and CE marking obligations create parallel compliance burdens for exporters serving European contractors. Stakeholders must monitor electrification cost curves against residual diesel-equipment utilization economics to time capital deployment.
Market Dynamics
Electrification of fleet assets is compressing replacement cycles as OSHA indoor air-quality enforcement tightens and Gulf Coast petrochemical operators accelerate diesel-phaseout programs.
Growth Catalysts
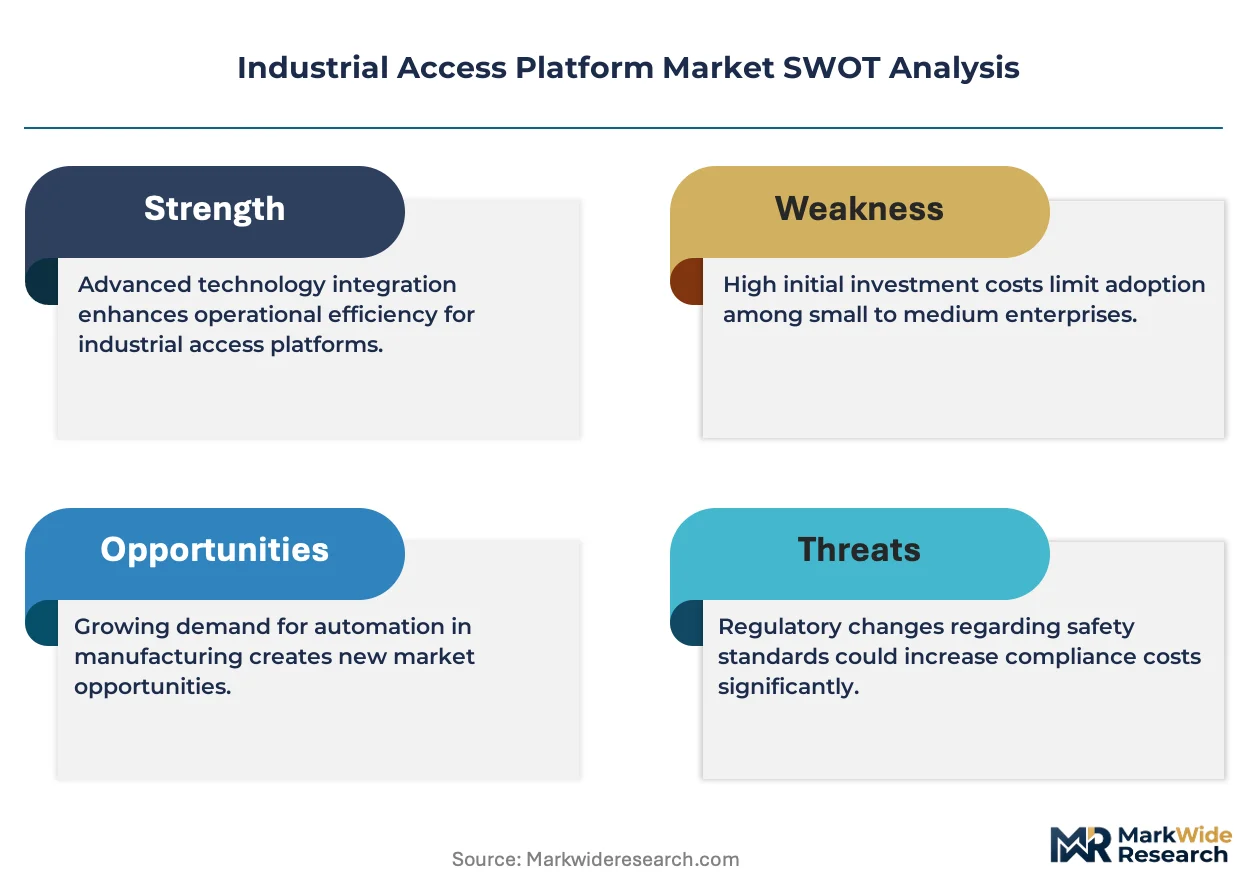
- OSHA Fall-Protection Enforcement:Revised Subpart D walking-working surface rules mandate guardrail systems on platforms above four feet, forcing facility upgrades across manufacturing and warehousing operations.
- Aluminum Alloy Advances:6061-T6 and 6082-T6 extrusions deliver 40% weight reduction versus steel without load-rating compromise, enabling single-operator deployment in maintenance corridors.
- Texas-Louisiana Petrochemical Corridor:Turnaround season intensity drives concentrated demand for rapid-deployment platforms in refinery and downstream chemical processing units.
Market Restraints
- Steel Price Volatility:Hot-rolled coil input costs swing with scrap metal and energy pricing, compressing margin stability for custom-fabricated heavy-load configurations.
- Hydraulic Component Concentration:Precision cylinder and seal manufacturing concentrates in German and Japanese supplier bases, exposing lead-time risk for North American platform assemblers.
- Pneumatic Force Density Ceiling:Compressed-air systems lack sufficient power-to-weight ratio for lifts above 500-pound capacity, limiting substitution in heavy-process segments.
Strategic Opportunities
- India Infrastructure Buildout:National Manufacturing Zones and Smart Cities Mission create greenfield demand for compliant access equipment in power generation and metro rail construction.
- Battery-Electric Convergence:Lithium iron phosphate pack integration with brushless DC drivetrains enables all-day continuous operation previously requiring diesel gensets.
- Rental Channel Penetration:United Rentals and Sunbelt Equipment are expanding aerial platform fleets, creating pull-through for OEM service-contract attachments and telemetry subscriptions.
Industry Challenges
- Welding Certification Bottlenecks:AWS D1.2 structural aluminum welding qualification timelines stretch 12-16 weeks, constraining production scaling for qualified fabricators.
- ANSI A92.20 Compliance Migration:Load-sensing and tilt-angle cutout integration requires control-system redesigns, extending engineering validation cycles for existing platform families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Access Platform Market |
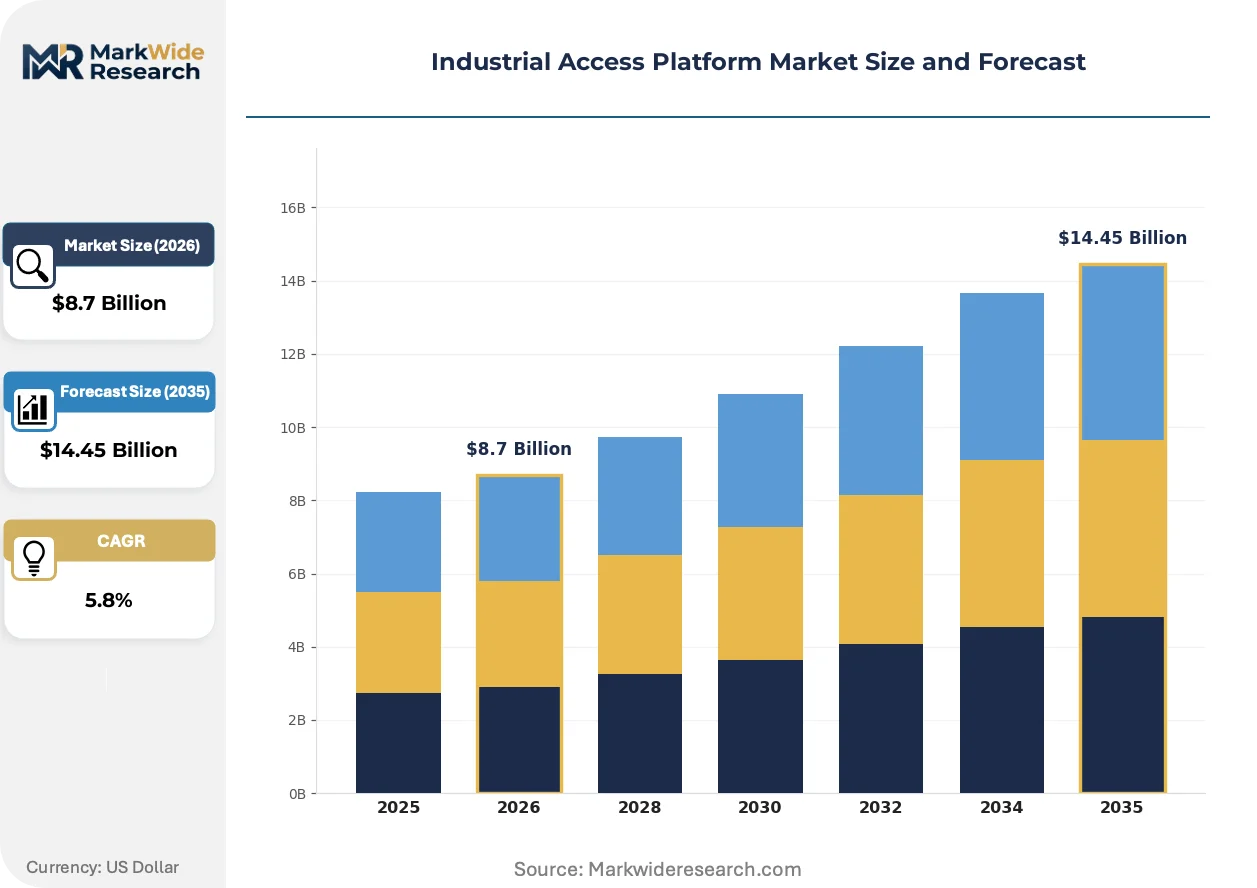
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissor Lifts, Boom Lifts, Mast Lifts, Personnel Lifts Application: Construction, Maintenance, Warehousing, Oil & Gas End User: Contractors, Event Managers, Retailers, Manufacturers Technology: Hydraulic, Electric, Pneumatic, Mechanical |
| Companies Covered | EGA, Southern Metal Fabricators, ErectaStep, GSM Industrial, Inc., Zarges, Tri-Arc, LLC, Ballymore, Steelway, COTTERMAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Access Platform Market Strategic Shifts
Telemetry integration and predictive maintenance protocols are redefining fleet management economics, while material substitution and regulatory phaseouts accelerate product obsolescence timelines.
Carbon fiber-reinforced polymer decking is absorbing impact-damage loads at 60% lower weight than traditional plywood or aluminum plate systems. Offshore wind turbine technicians are specifying these decks for nacelle access platforms where helicopter transport imposes strict mass limits. The technology is absorbing premium pricing power in corrosion-critical marine and chemical environments where lifecycle replacement costs dominate procurement decisions.
EPA Tier 4 Final and CARB standards for non-road diesel engines are forcing engine-aftertreatment complexity that adds $8,000-$12,000 per diesel lift unit. Equipment lessors in California and Texas are accelerating electric-fleet rotation to avoid maintenance burden and residual-value risk. The regulatory pressure is compressing diesel-equipment holding periods and expanding secondary-market supply of pre-Tier 4 assets.
Integrated fleet telematics are displacing paper-based inspection logs and reactive service scheduling. Construction and industrial facility managers now demand OEM-provided uptime dashboards, geofencing alerts, and usage-based billing rather than flat-rate rental agreements. This behavioral shift concentrates purchasing influence among national account procurement teams and marginalizes independent equipment dealers lacking software integration capabilities.
Industrial Access Platform Market Segmentation
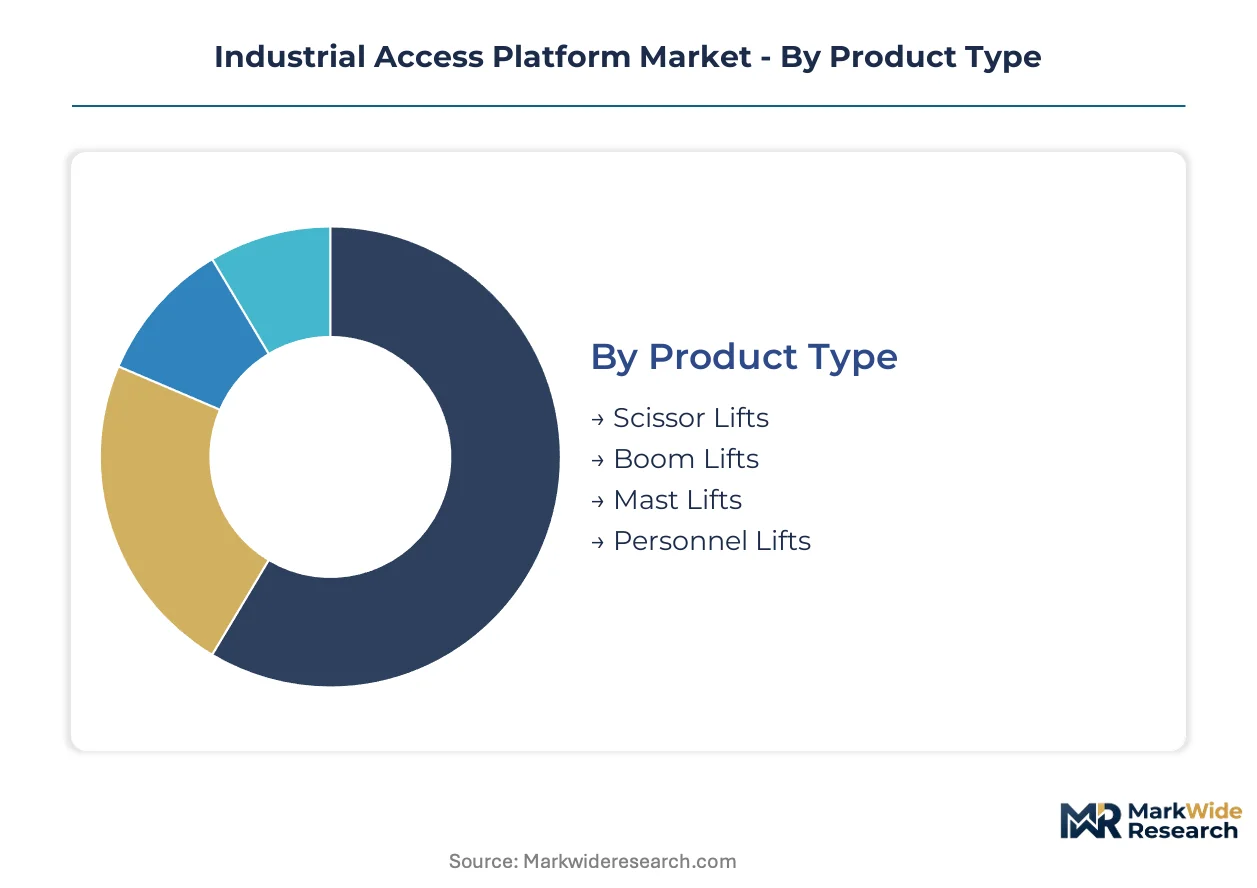
Industrial access platform procurement splits across four dimensions that determine equipment specification, compliance burden, and lifecycle economics. Buyers prioritize load ratings, powertrain compatibility with facility air-quality rules, and deployment speed for turnaround schedules.
Product Type:
Supply concentration for scissor and boom lift assemblies clusters around three North American fabrication centers with integrated hydraulic component sourcing.
- Scissor Lifts:Vertical-only elevation platforms utilizing crossed-link pantograph mechanisms deliver 500-1,000 pound load ratings with platform heights reaching 50 feet. Demand concentrates in Texas and Louisiana petrochemical facilities where OSHA indoor air-quality enforcement accelerates electric-variant procurement for enclosed vessel maintenance.
- Boom Lifts:Articulated or telescopic arm configurations provide horizontal outreach exceeding 80 feet for infrastructure inspection and utility work. Gulf Coast turnaround contractors specify these for flare stack and distillation column access where scaffolding erection timelines exceed project economics.
- Mast Lifts:Single-mast vertical platforms with compact footprints suit narrow warehouse aisles and retail atrium maintenance. Equipment lessors favor these for urban multi-tenant building contracts.
- Personnel Lifts:Push-around or self-propelled units under 500 pounds capacity serve single-operator tasks in ceiling infrastructure and HVAC servicing. Event staging companies in Las Vegas and Orlando drive replacement cycles for lightweight aluminum configurations.
Today's leader: Scissor Lifts. Tomorrow's challenger: Boom Lifts.
Application:
Cost tier stratification separates capital-intensive permanent installations from rental-dependent seasonal deployment models.
- Construction:New commercial and residential building drives demand for rough-terrain diesel units with four-wheel drive and oscillating axles. Urban high-rise projects in Miami and Seattle specify electric slab scissor lifts for interior finishing work.
- Maintenance:Scheduled turnaround and reactive repair operations require rapid-deployment platforms with corrosion-resistant finishes. Refinery operators along the Houston Ship Channel maintain captive fleets exceeding 200 units per facility.
- Warehousing:E-commerce fulfillment center expansion creates demand for narrow-aisle mast lifts with non-marking tires and 24-foot vertical reach. Amazon and Walmart distribution networks drive standardization toward 19-foot platform heights.
- Oil & Gas:Offshore platform and pipeline maintenance specify explosion-proof electric variants and marine-grade aluminum construction. Permian Basin operators prioritize rental flexibility over ownership due to drilling cycle volatility.
Maintenance commands current procurement volume. Warehousing climbs fastest on e-commerce infrastructure buildout.
End User:
Customer type determines ownership model, service contract attachment rates, and telemetry adoption intensity.
- Contractors:General and specialty construction firms balance fleet ownership against United Rentals and Sunbelt Equipment rental agreements. Large mechanical contractors in California maintain mixed diesel-electric fleets to satisfy CARB compliance zones.
- Event Managers:Staging and entertainment production requires rapid-load trailer-mounted units for concert and convention deployment. Las Vegas production companies specify lightweight aluminum personnel lifts for ceiling rigging access.
- Retailers:Big-box and grocery chains favor low-maintenance electric mast lifts for in-house facilities teams. Walmart operates a standardized fleet across 4,700 US locations with centralized OEM service contracts.
- Manufacturers:Automotive and aerospace plants integrate platforms into continuous production lines with custom deck configurations. Boeing's Everett facility specifies carbon fiber-reinforced decking for final assembly bay access.
Contractors anchor rental channel volume. Manufacturers drive telemetry integration and predictive maintenance adoption.
Technology:
Margin structure varies sharply by powertrain complexity, with hydraulic systems commanding premium pricing in heavy-lift segments.
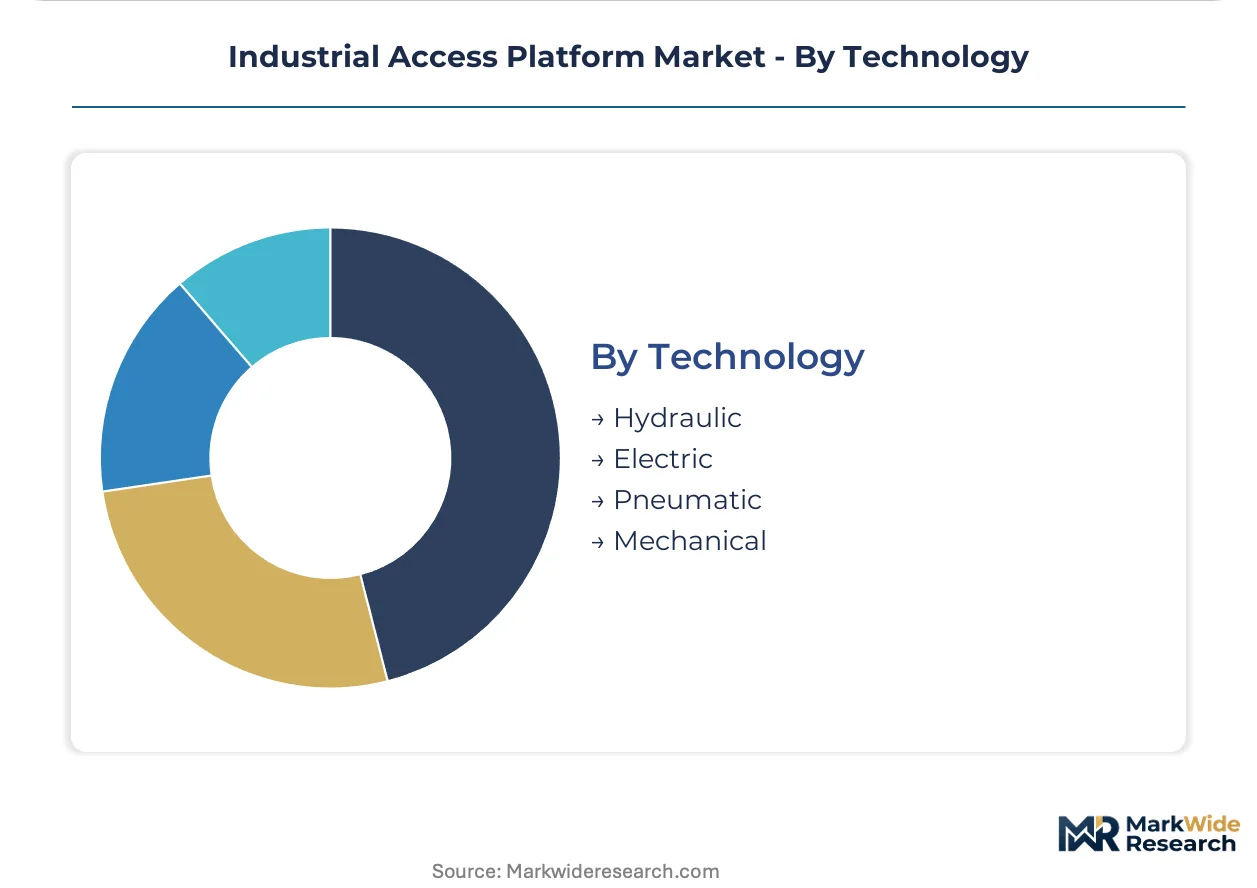
- Hydraulic:Fluid-power systems deliver force density exceeding 3,000 psi for lifts above 500-pound capacity and 40-foot heights. German and Japanese precision cylinder suppliers constrain North American assembler lead times.
- Electric:Lithium iron phosphate battery packs with brushless DC drivetrains enable all-day continuous operation previously requiring diesel gensets. California and Texas equipment lessors accelerate fleet rotation to avoid Tier 4 Final maintenance burden.
- Pneumatic:Compressed-air systems serve explosion-sensitive environments with intrinsic safety advantages. Force density limitations restrict application to sub-500-pound capacity lifts in chemical processing units.
- Mechanical:Hand-cranked or push-around units without powered elevation serve low-frequency maintenance tasks. Educational institutions and small municipalities favor these for budget-constrained procurement.
Electric systems gain share fastest on regulatory phaseout pressure. Hydraulic retains margin dominance in heavy-process verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial access platform industry traces its modern fabrication lineage to post-war American steel and aluminum processing centers, with European engineering traditions later refining modular folding systems for transport efficiency.
United States
OSHA fall-protection enforcement and Gulf Coast petrochemical turnaround schedules drive fleet replacement cycles. EPA Tier 4 Final emissions standards for non-road diesel engines accelerate electric-variant procurement in California and Texas. The Houston Ship Channel corridor hosts captive fleet concentrations exceeding 200 units per refinery facility.
Germany
Precision hydraulic component manufacturing concentrates in Baden-Württemberg and Bavaria, supplying cylinder and seal assemblies to North American assemblers. EU Machinery Directive and CE marking obligations create compliance burdens for exporters. Stuttgart-based engineering clusters dominate force-density optimization for heavy-lift segments.
China
National Manufacturing Zones and Smart Cities Mission infrastructure buildout creates greenfield demand for compliant access equipment. GB standards and MIIT industrial safety protocols reshape product specifications for domestic contractors. Yangtze River Delta fabrication centers scale aluminum extrusion capacity for regional supply.
India
Metro rail construction and power generation infrastructure expansion concentrate demand in Maharashtra and Gujarat. BIS certification requirements and CEA electrical safety standards govern equipment imports. Mumbai-Pune industrial corridor contractors prioritize rapid-deployment platforms for turnaround schedules.
Japan
Automotive and aerospace manufacturing integration drives custom deck configuration demand. METI industrial safety guidelines and JIS structural standards enforce load-rating compliance. Nagoya-Chubu production clusters specify carbon fiber-reinforced decking for final assembly bay access.
Industrial Access Platform Market Competitive Environment
Premium-margin players sit above commodity-margin players across material specialization and compliance certification tiers. The vendor base organizes into three strategic archetypes: aluminum-focused lightweight specialists, steel-oriented heavy-process fabricators, and European-engineered modular system providers. Consolidation pressure concentrates among rental channel suppliers seeking telemetry integration capabilities. Dominant competitive moves include backward integration into hydraulic component sourcing and geographic expansion through distribution partnerships.
Within the aluminum fabrication tier, EGA exemplifies lightweight platform specialization through extrusion expertise. Southern Metal Fabricators anchors the custom steel configuration segment for heavy-process industries. Zarges occupies a position representing European-engineered folding systems that compete on transport efficiency and rapid deployment logistics.
| Leading Market Players |
|---|
| EGA |
| Southern Metal Fabricators |
| ErectaStep |
| GSM Industrial, Inc. |
| Zarges |
| Tri-Arc, LLC |
| Ballymore |
| Steelway |
| COTTERMAN |
| Others |
Value Chain & Pricing Dynamics
AWS D1.2-certified aluminum welders in the Texas-Louisiana corridor command wage premiums that compress margin spreads between economy-grade steel platforms and premium aluminum configurations. Labor-cost differentials in this skilled-trade concentration directly widen pricing-tier spreads as fabricators pass qualification scarcity through to end-user contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber-reinforced decking systems from aluminum extrusion platforms from basic steel weldments. Price differentiation hinges on OSHA fall-protection certification tier and after-sales telemetry bundling. Pricing pressure stems from EPA Tier 4 Final compliance costs compressing diesel-equipment residual values. Rental channel buyers exhibit highest price sensitivity; petrochemical facility fleet managers show lowest.
Supply Chain Analysis
Workforce-availability constraints in Baden-Württemberg, Houston, and Yangtze River Delta fabrication centers extend lead times for precision hydraulic assemblies. Component sourcing draws from German cylinder specialists, Japanese seal manufacturers, and Chinese aluminum extruders. Single-source vulnerability concentrates in precision hydraulic component supply. Distribution runs through United Rentals and Sunbelt Equipment national account channels with telemetry-enabled service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA Subpart D enforcement and EPA emissions phaseouts create mandated replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Lock in backward integration into lithium iron phosphate battery pack sourcing to secure electric-variant margin capture. Capture ANSI A92.20 load-sensing certification capacity before engineering validation bottlenecks tighten. Defend against emerging telemetry-native entrants by embedding predictive maintenance protocols into captive service contracts. For New Entrants and Emerging Players: Carbon fiber-reinforced polymer decking technology offers white-space penetration into offshore wind nacelle access where helicopter transport mass limits create premium pricing tolerance. Target India metro rail construction contractors with rapid-deployment folding systems for greenfield infrastructure. Pursue rental channel partnerships with telemetry-integrated service offerings as primary go-to-market path. For Investors and Strategic Acquirers: Equipment lessors are the most active acquirer in this space, consolidating regional fleets to achieve national account procurement scale. Five-to-ten-year viability rests on electrification capex conversion rates and telemetry subscription attachment economics. Monitor diesel-equipment auction volume as inflection signal for residual-value risk compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | In-house lithium iron phosphate sourcing secures electric-variant margin capture against commodity cell volatility. |
| Telemetry Platform Development | Predictive maintenance dashboards displace paper inspection logs and concentrate purchasing influence among national accounts. |
| ANSI A92.20 Certification Investment | Load-sensing and tilt-angle cutout compliance extends engineering validation cycles but locks out uncertified competitors. |
| India Distribution Partnership | Maharashtra and Gujarat metro rail contractors prioritize rapid-deployment platforms for infrastructure buildout schedules. |
| Carbon Fiber Decking Scale-Up | Offshore wind turbine OEMs specify CFRP nacelle platforms where helicopter transport imposes strict mass limits. |
Study Parameters
Multiple input streams — maintenance director interviews, OEM procurement team discussions, rental channel operator consultations, and aftermarket service head surveys — were reconciled against customs trade data, OSHA enforcement records, SEC equipment manufacturer filings, and petrochemical turnaround schedules. Secondary validation drew from EPA emissions compliance databases and ANSI standards documentation. Bottom-up unit economics triangulated against top-down market sizing.
Historical shipment data cross-referenced against panel input from fabrication center managers and hydraulic component distributors anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, powertrain technology, application vertical, end-user ownership model, and regional regulatory cluster. CAGRs derived from replacement cycle compression rates and fleet electrification adoption curves. Forecast inputs incorporated aluminum alloy price trajectories and welding certification pipeline constraints.
The model holds under steady OSHA enforcement intensity and EPA emissions phaseout schedules; deviation in steel scrap volatility or hydraulic component trade restrictions would shift replacement cycle timing. Forecasts reflect documented assumptions regarding electrification cost curve convergence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Street Furniture Market
Specialized Building Services
Portable Ramps Market
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Private Bunker Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Horizontal Directional Drilling Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
Clean Room Pass Box Market