
 Automatic Industrial Doors Market | 2026-2036
Automatic Industrial Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Industrial Doors Market Analysis
Energy-performance certification tiers are rotating toward the center of procurement decisions as facility operators prioritize thermal efficiency and air-sealing specifications. ASSA ABLOY leverages its broad certification portfolio to anchor premium positioning across cold-storage and pharmaceutical installations. Hörmann Group sustains manufacturing scale advantages in sectional door systems through captive steel-forming operations in Germany. EFAFLEX specializes in high-speed fabric and spiral door technologies that dominate cleanroom and automotive paint-shop applications.
Automatic industrial doors are electromechanically actuated barrier systems engineered to cycle at speeds between 0.5 and 2.5 meters per second, incorporating polyurethane-insulated panels or reinforced PVC curtains with integrated safety edge sensors and programmable logic controllers. Their primary purpose is to regulate environmental separation, traffic flow, and access control in facilities where thermal retention, dust exclusion, or pressure differential maintenance is operationally critical. Roll-up doors command substantial share in warehousing and logistics corridors where vertical clearance constraints limit alternative configurations. High-speed doors represent the fastest-expanding product category, driven by cold-chain integrity requirements and just-in-time material handling protocols. Sensor-activated technology is displacing manual override systems as default specifications in new construction, reflecting labor-cost and hygiene considerations.
The EU Green Deal and REACH compliance frameworks in Europe, alongside OSHA workplace safety standards in the United States, mandate minimum insulation values and pinch-point protection that reshape product design priorities and certification costs. China's GB standards for building energy conservation and SAMR product safety enforcement are tightening import and domestic manufacturing requirements for automated entrance equipment. Stakeholders must monitor evolving carbon-border adjustment mechanisms and regional content thresholds that will determine competitive access to public infrastructure and industrial development contracts.
Market Dynamics
Energy-efficiency mandates from the EU Green Deal are forcing facility operators to retire legacy door installations and adopt thermally optimized barrier systems with integrated sensor networks and programmable logic controllers.
Growth Catalysts
- Cold-chain infrastructure expansion:Pharmaceutical and food processing facilities are installing high-speed spiral doors to maintain pressure differentials and temperature integrity during material transfers.
- REACH compliance deadlines:European manufacturers must phase out legacy sealing compounds, accelerating replacement cycles for industrial entrance systems across Germany, France, and the Netherlands.
- Just-in-time logistics protocols:E-commerce fulfillment centers in the United States are specifying rapid-cycle roll-up doors to minimize air infiltration during high-frequency truck loading operations.
Market Restraints
- Steel and aluminum price volatility:Sectional door manufacturers face margin compression from fluctuating raw material costs for insulated panel substrates and track hardware.
- Controller chip supply concentration:Programmable logic controller shortages from Taiwanese semiconductor foundries delay door system deliveries and extend lead times for sensor-integrated installations.
- Legacy pneumatic system entrenchment:Older warehousing facilities retain compressed-air actuated doors, creating substitution friction against electromechanical alternatives despite efficiency advantages.
Strategic Opportunities
- India warehouse automation:Cold storage capacity expansion under the PLI scheme creates demand for high-speed fabric doors with bacterial-resistant coatings in pharmaceutical corridors.
- Carbon border adjustment mechanisms:EU import tariffs on high-carbon steel products incentivize local manufacturing of insulated door panels and captive steel-forming investments.
- Predictive maintenance convergence:Integration of vibration sensors and cloud analytics enables door OEMs to offer uptime-guaranteed service contracts displacing traditional break-fix arrangements.
Industry Challenges
- Mechatronics technician scarcity:Installation and servicing of sensor-integrated high-speed doors requires cross-trained personnel proficient in both mechanical drive systems and PLC diagnostics.
- Multi-certification timelines:Products must simultaneously satisfy OSHA pinch-point standards, CE machinery directives, and GB energy conservation ratings, extending product launch cycles.
- Retrofit integration complexity:Existing facility control architectures often lack ethernet connectivity for smart door systems, requiring costly building management system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Industrial Doors Market |
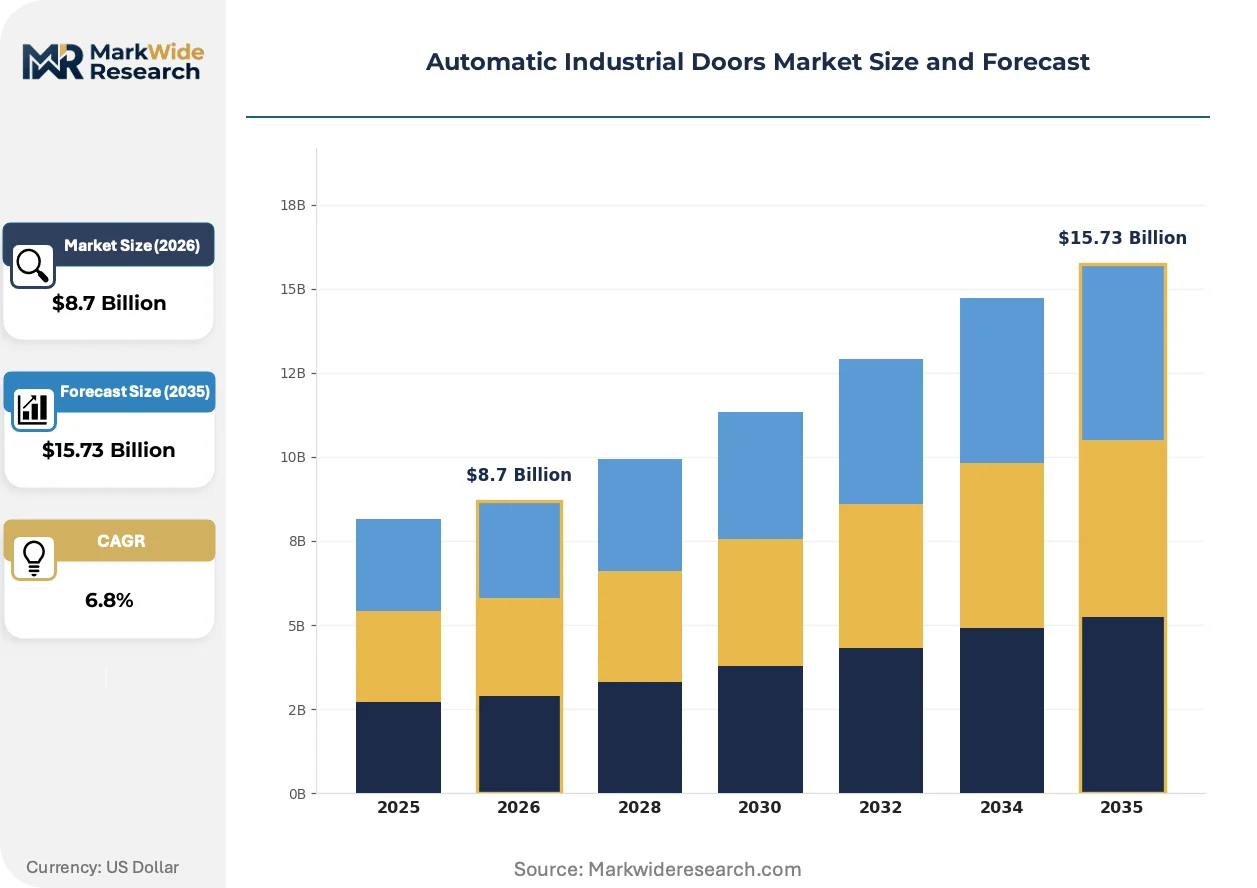
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sectional Doors, Roll-Up Doors, High-Speed Doors, Folding Doors End User: Manufacturing, Warehousing, Retail, Logistics Technology: Automatic Controls, Sensor-Activated, Remote-Controlled, Manual Override Installation Type: New Construction, Renovation, Retrofit, Custom Installation |
| Companies Covered | ASSA ABLOY, Hörmann Group, Dormakaba Group, Novoferm, FAAC Group, EFAFLEX, GEZE, Agta Record, Alpha Deuren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Industrial Doors Market Emerging Trajectories
Sensor fusion and edge computing are redefining how industrial doors interact with facility traffic management, transforming barrier systems from passive hardware into data-generating infrastructure nodes.
Photoelectric and radar sensor arrays are decomposing the traditional safety edge as the sole hazard detection mechanism. Automotive paint shops in Germany and cleanroom facilities in South Korea are deploying multi-modal detection stacks that combine light curtains with millimeter-wave presence sensing. This convergence is decomposing the market for standalone safety components and compressing procurement toward integrated intelligent door packages.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents in polyurethane insulation panels. Door manufacturers serving cold-storage applications must reformulate core materials or source alternative foam chemistries to maintain thermal performance ratings. European pharmaceutical distribution centers are prioritizing suppliers with verified low-global-warming-potential insulation certifications in their technical specifications.
Lifecycle contracting is displacing capital purchase models for high-throughput installations. Third-party logistics operators in the United States are negotiating performance-based agreements where door OEMs retain ownership and guarantee operational availability. This transfer of capital burden to manufacturers is visible most acutely in refrigerated warehousing corridors serving grocery retail distribution networks.
Automatic Industrial Doors Market Segmentation
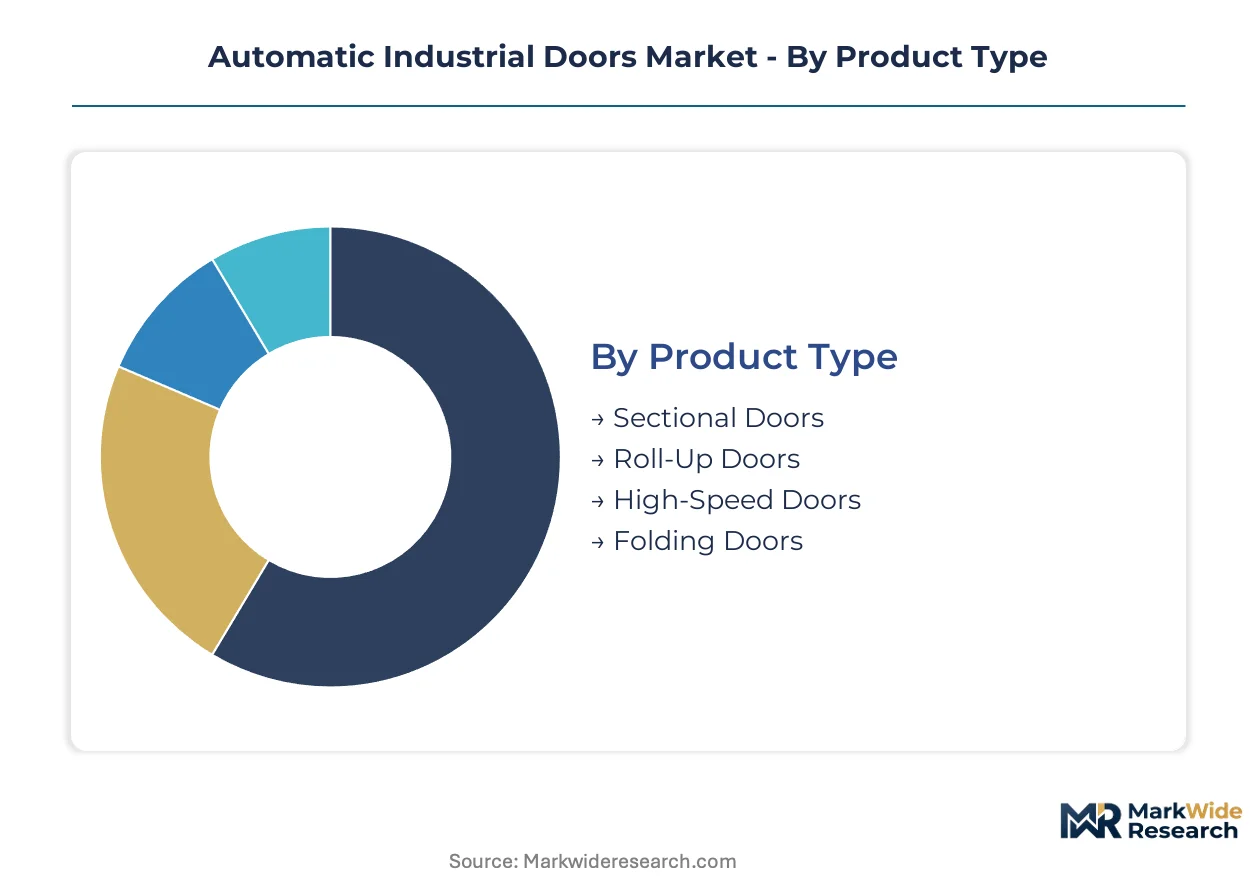
Segmentation in automatic industrial doors reveals how regulatory pressure and operational intensity reshape procurement priorities across facility types. Product specifications diverge sharply between cold-chain applications demanding thermal certification and general warehousing focused on cycle speed.
Product Type:
REACH compliance deadlines and EU F-Gas Regulation reformulation mandates are fragmenting competitive positioning across insulation-dependent categories.
- Sectional Doors:These systems employ polyurethane-insulated steel panels with R-values certified under evolving EU thermal performance tiers. German automotive assembly plants specify sectional configurations for pressurized paint booths where acoustic dampening complements climate control. REACH-mandated phase-out of legacy blowing agents is accelerating replacement demand across Benelux cold-storage facilities.
- High-Speed Doors:Fabric and spiral designs cycle at 2.0-2.5 meters per second using reinforced PVC curtains with integrated radar sensing arrays. Pharmaceutical distribution corridors in the United States specify these for maintaining FDA-validated pressure differentials during material transfers. Cold-chain integrity requirements are compressing procurement timelines for validated high-speed installations.
- Roll-Up Doors:Steel or aluminum slat constructions dominate logistics corridors with vertical clearance constraints.
- Folding Doors:Accordion configurations serve aircraft hangars and heavy equipment bays requiring maximum opening width.
Established volume favors sectional installations; emerging adoption favors high-speed fabric systems.
End User:
Operational intensity and contamination sensitivity determine technology specification depth across facility categories.
- Warehousing:E-commerce fulfillment centers specify rapid-cycle roll-up configurations with PLC-integrated traffic management. OSHA pinch-point mandates are displacing manual override systems in United States distribution networks. Just-in-time logistics protocols demand sub-second sensor response times.
- Manufacturing:Cleanroom-rated high-speed doors with HEPA-compatible sealing dominate semiconductor and pharmaceutical production. South Korean display panel fabs specify millimeter-wave presence detection for automated guided vehicle corridors. Contamination control requirements override capital cost considerations.
- Logistics:Cross-dock facilities prioritize cycle speed over thermal performance in temperate climates.
- Retail:Back-of-house receiving areas specify mid-tier automatic controls with breakaway bottom bars.
Manufacturing commands specification premiums; warehousing drives absolute unit volume.
Technology:
Controller chip availability and mechatronics technician scarcity are bifurcating adoption between integrated and basic systems.
- Sensor-Activated:Photoelectric and radar arrays combine with edge computing for predictive hazard detection. German automotive paint shops deploy multi-modal stacks replacing standalone safety edges. Taiwan semiconductor foundry concentration creates supply vulnerability for PLC-dependent installations.
- Automatic Controls:Programmable logic controllers with ethernet connectivity enable building management system integration. United States refrigerated warehousing contracts increasingly specify uptime-guaranteed service arrangements with remote diagnostics. Legacy pneumatic entrenchment in older facilities creates substitution friction.
- Remote-Controlled:Radio-frequency handheld units persist in hazardous environment applications where wired sensors risk ignition.
- Manual Override:Basic configurations remain specified for low-cycle agricultural and light industrial settings.
Sensor-activated systems claim specification leadership; automatic controls retain installed base dominance.
Installation Type:
Building management system architecture determines integration complexity and margin capture across project categories.
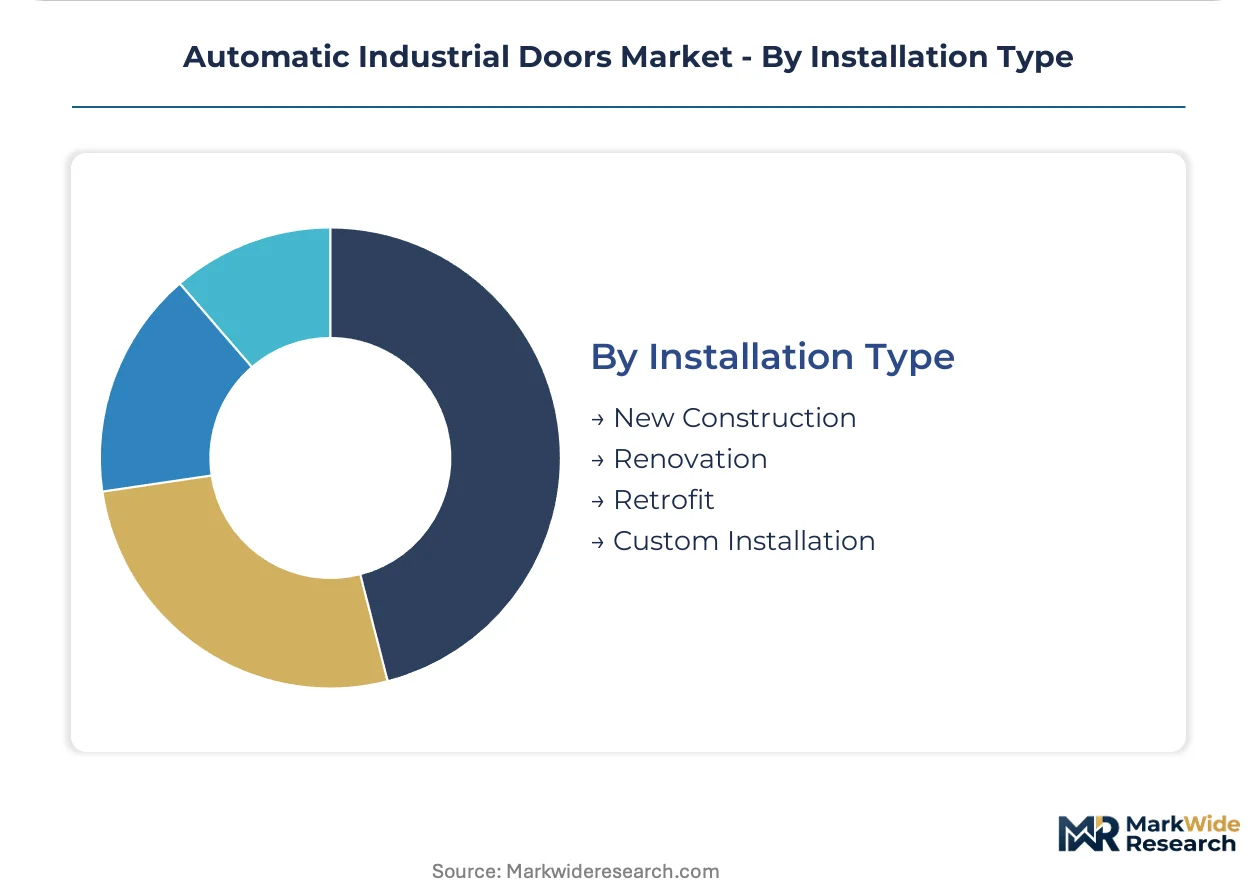
- Retrofit:Existing facilities lacking ethernet infrastructure require costly control system upgrades for smart door integration. European pharmaceutical distribution centers under EU Green Deal energy mandates prioritize thermal performance retrofits over full replacement. Controller compatibility with legacy architectures constrains product selection.
- New Construction:Integrated specification during design phase enables optimal sensor placement and power routing. United States cold storage greenfield projects specify lifecycle contracting with OEM-retained ownership. Upfront capital burden transfer to manufacturers is visible in grocery retail distribution networks.
- Renovation:Partial facility upgrades balance thermal improvement against operational continuity requirements.
- Custom Installation:Non-standard opening dimensions and seismic-rated track systems serve specialized industrial applications.
New construction enables full technology deployment; retrofit projects dominate absolute project flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing hubs in Germany and China generate surplus capacity for door system components, while import-dependent markets in India and the Middle East absorb this supply through infrastructure buildouts. Trade flows concentrate insulated panel substrates and controller assemblies across three dominant corridors.
United States
OSHA workplace safety standards and IRA energy-efficiency tax credits drive retrofit demand across refrigerated warehousing networks. Cold storage greenfield projects in the Midwest and Southeast specify lifecycle contracting arrangements. Chicago and Dallas-Fort Worth logistics clusters anchor specification activity for rapid-cycle roll-up configurations.
Germany
EU Green Deal mandates and REACH compliance deadlines accelerate replacement cycles for legacy sealing compounds. Captive steel-forming operations in North Rhine-Westphalia sustain manufacturing scale advantages for sectional door systems. Stuttgart and Wolfsburg automotive corridors deploy high-speed spiral doors for pressurized paint booth applications.
China
GB standards for building energy conservation and SAMR product safety enforcement tighten domestic manufacturing requirements. Dual carbon goals compress procurement timelines for thermally optimized barrier systems in Yangtze River Delta cold-chain facilities. Shanghai and Suzhou pharmaceutical distribution centers validate high-speed fabric installations.
India
PLI scheme incentives for cold storage capacity expansion create demand for bacterial-resistant high-speed doors in pharmaceutical corridors. BIS certification requirements reshape import substitution patterns for automated entrance equipment. Maharashtra and Gujarat warehouse automation clusters specify rapid-cycle configurations under just-in-time logistics protocols.
United Arab Emirates
MOHAP pharmaceutical distribution standards and logistics free zone investments concentrate demand for cleanroom-rated door systems. Dubai South and Jebel Ali corridor facilities prioritize sensor-activated technologies for high-frequency material handling. Carbon border considerations influence sourcing decisions for insulated panel substrates.
Automatic Industrial Doors Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and manufacturing scale. The vendor base organizes around three structural tiers: multinational conglomerates with broad certification portfolios, mid-scale regional fabricators with captive component production, and niche specialists focused on single technology categories. Strategic differentiation concentrates on thermal performance validation, sensor integration depth, and service contract structuring. Consolidation activity targets PLC diagnostics capabilities and regional installation networks.
Within the premium-tier certification vector, ASSA ABLOY and Hörmann Group exemplify divergent scale strategies. ASSA ABLOY occupies a position anchored by portfolio breadth across cold-storage and pharmaceutical verticals. Hörmann Group represents manufacturing concentration through in-house steel-forming operations. EFAFLEX sits within the specialization archetype, anchoring high-speed fabric and spiral technology positioning for contamination-sensitive applications.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Hörmann Group |
| Dormakaba Group |
| Novoferm |
| FAAC Group |
| EFAFLEX |
| GEZE |
| Agta Record |
| Alpha Deuren |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon blowing agents simultaneously gate supplier qualification and stratify price tiers across polyurethane-insulated door categories. Manufacturers must reformulate core materials or source alternative foam chemistries to maintain thermal performance ratings, compressing margins for uncertified competitors while rewarding validated low-global-warming-potential suppliers with premium positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on CE machinery directive compliance depth and captive steel-forming integration. Cost compression in economy-tier sectional doors is intensifying because of aluminum price volatility and Taiwanese PLC chip shortages. E-commerce fulfillment centers exhibit highest price sensitivity due to volume procurement, while pharmaceutical cleanroom operators prioritize certification over unit cost.
Supply Chain Analysis
Taiwan Strait semiconductor transit underwrites controller chip availability for sensor-integrated high-speed door systems. Manufacturing gravity centers on Germany, China, and the United States for insulated panel substrates and track hardware assemblies. Raw material dependencies span polyurethane foam chemicals, galvanized steel coils, and programmable logic controllers. Single-source vulnerability in Taiwanese foundry concentration threatens delivery timelines. Distribution runs through regional installation networks and OEM-direct service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pneumatic door retrofits pose the most credible substitution threat to electromechanical system incumbents, particularly in legacy warehousing facilities where compressed-air infrastructure delays upgrade cycles.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance sensors and uptime-guaranteed service contracts that pneumatic alternatives cannot match. Deepen backward integration into steel-forming operations to defend margin position against raw material volatility. Prioritize PLC diagnostics capability acquisition to offset technician scarcity risks. For New Entrants and Emerging Players: Differentiate on bacterial-resistant fabric coatings for Indian pharmaceutical corridors under PLI scheme expansion. Target retrofit integration services where legacy building management system upgrades create execution complexity incumbents avoid. Lead with ethernet-native door controllers that bypass costly infrastructure overhauls. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-speed spiral door manufacturing due to cleanroom validation infrastructure requirements. Long-term viability favors specialists with verified EU Green Deal thermal certification portfolios over commodity sectional fabricators. Watch carbon border adjustment mechanism implementation timing as inflection signal for regional manufacturing investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Forming | Captive supply of galvanized coil reduces exposure to EU carbon border tariffs on imported substrates. |
| Predictive Maintenance Platform Launch | Vibration analytics and cloud diagnostics enable performance-based service contracts displacing break-fix arrangements. |
| Low-GWP Insulation Certification | Verified thermal chemistry qualifies suppliers for EU F-Gas Regulation-compliant pharmaceutical and cold-storage specifications. |
| Regional Installation Network Acquisition | Control over mechatronics technician labor pools addresses scarcity constraints in sensor-integrated system deployment. |
| PLC Controller Supply Agreement | Long-term foundry partnerships mitigate Taiwanese semiconductor concentration risks extending delivery lead times. |
Methodological Framework
Initial hypotheses were tested against primary input from facility maintenance directors, plant engineers at automotive and pharmaceutical manufacturers, OEM procurement teams, and aftermarket service heads, then refined against secondary validation. Secondary sources encompassed EU ECHA REACH registration databases, OSHA workplace safety directive filings, customs trade flow records for insulated panel substrates, and SEC 10-K disclosures from listed door system manufacturers. Bottom-up unit economics triangulated with top-down sector spend estimates to anchor volume and value outputs.
Variance decomposition across the projection horizon isolates drivers by product type, end-use facility category, technology tier, and installation mode. Growth trajectories were derived from segment-level replacement cycle analysis and greenfield capacity expansion pipelines. Industry-specific forecast inputs incorporated EU Green Deal implementation timelines and Indian PLI scheme cold storage capacity targets.
Material uncertainties — semiconductor supply disruptions, steel tariff adjustments, and REACH compliance deadline shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity. Practitioners should keep alternative scenarios live as carbon border mechanism coverage and F-Gas Regulation phase-down schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Industrial Access Platform Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Street Furniture Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Portable Ramps Market
Specialized Building Services
Private Bunker Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
Horizontal Directional Drilling Market
Specialized Building Services
Europe Stair Lift Market