
 Global Automated Industrial Door Market | 2026-2036
Global Automated Industrial Door Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Industrial Door Market Analysis
The automated industrial door sector is rebalancing between premium sensor-integrated systems and commodity roller configurations. Hörmann Group leverages its manufacturing scale across Central Europe to dominate the premium overhead door tier. Gandhi Automations Pvt Ltd anchors its position in South Asia through specialized high-speed door engineering for pharmaceutical cleanrooms. dormakaba Holding AG differentiates via advanced access-control integration with smart building platforms.
Automated industrial doors are electromechanical barrier systems engineered to cycle at speeds exceeding one meter per second, utilizing polyurethane-insulated curtain panels or aluminum slat assemblies to maintain thermal envelopes in conditioned facilities. Their primary purpose is to regulate environmental separation while enabling high-frequency vehicle and pedestrian throughput in industrial operations. Roller doors lead the product type category due to established supply chains and retrofit compatibility across aging warehouse stock. Sensor-based technology captures the fastest expansion as logistics operators mandate touchless entry protocols and real-time traffic data integration. Smart integration sits at the highest margin tier, though penetration remains limited to greenfield distribution centers with full building automation architectures.
EU Ecodesign requirements and ASHRAE 90.1 standards in the United States directly shape insulation performance thresholds and cycle-efficiency testing protocols for door manufacturers. China's GB standards and Japan's METI energy conservation guidelines add compliance layers for suppliers serving East Asian industrial construction. Stakeholders must monitor evolving cybersecurity mandates for connected door systems as smart integration expands beyond access control into operational technology networks.
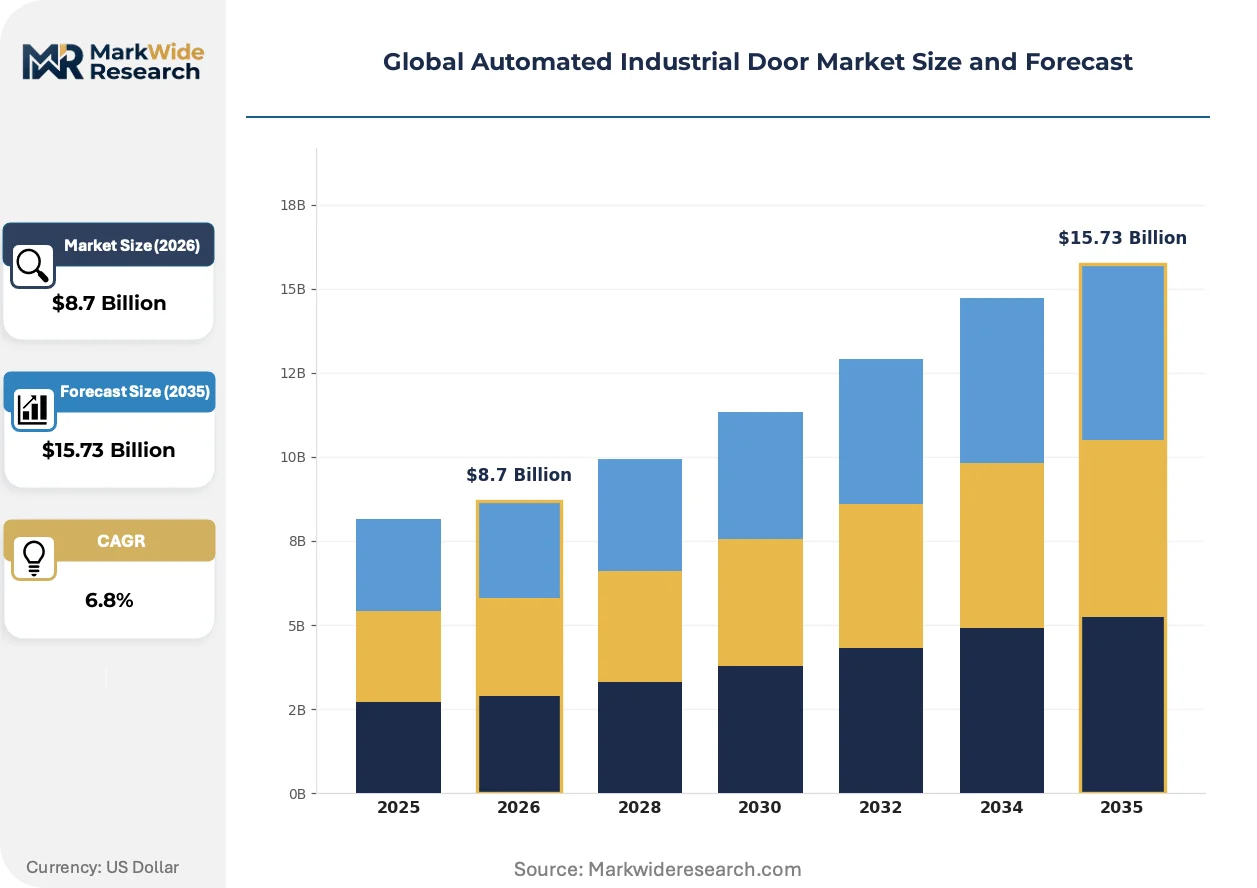
Market Dynamics
The automated industrial door market is rebalancing around sensor-integrated rapid-cycle systems as warehouse operators face escalating thermal envelope mandates and throughput optimization pressures. This structural pivot favors electromechanical platforms that unify environmental separation with real-time traffic data capture.
Growth Catalysts
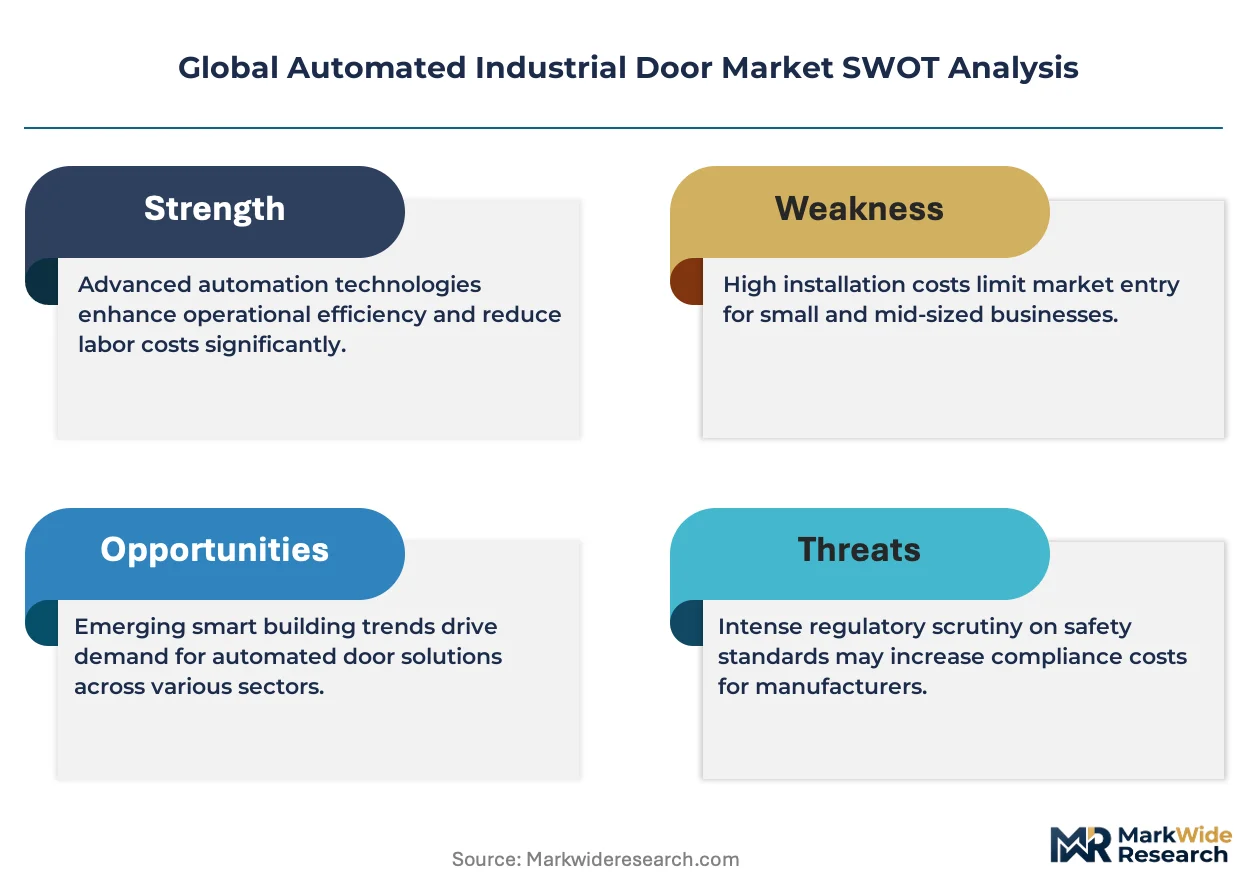
- EU Ecodesign insulation thresholds:Warehouse operators in Germany and the Netherlands are retrofitting aging facilities with polyurethane-insulated rapid-cycle doors to meet thermal performance mandates. Cold-chain logistics corridors drive replacement velocity.
- Sensor-based touchless entry protocols:High-throughput distribution centers in the United States are mandating microwave and infrared sensor arrays to eliminate contact points and capture vehicle-flow analytics. ASHRAE 90.1 cycle-efficiency testing accelerates specification.
- Pharmaceutical cleanroom engineering:South Asian manufacturers are deploying specialized high-speed curtain systems with positive-pressure seals. Regulatory inspections from CDSCO and WHO-GMP certification requirements tighten environmental control specifications.
Market Restraints
- Aluminum slat and polyurethane input volatility:Curtain panel assemblies face raw material cost pressure from energy-intensive polymer production and primary aluminum smelting. European electricity pricing directly impacts insulation core manufacturing economics.
- Supply concentration in electromechanical drive systems:Precision motor and gearbox assemblies concentrate among German and Japanese industrial automation suppliers. Geopolitical friction threatens component availability for non-integrated door manufacturers.
- Legacy facility retrofit compatibility:Aging warehouse stock in the United States and Western Europe presents structural limitations for rapid-cycle door mounting. Header space constraints and uneven concrete thresholds block sensor-integrated system deployment.
Strategic Opportunities
- India's pharmaceutical manufacturing expansion:CDSCO-inspected facilities and export-oriented formulation plants are creating demand for contamination-controlled rapid-cycle barriers. Domestic engineering capabilities remain underdeveloped relative to volume requirements.
- Smart building platform convergence:Integration of door control systems with BACnet and Modbus building automation networks enables predictive maintenance and energy analytics. Greenfield distribution centers in the United Arab Emirates are specifying fully integrated architectures.
- Japan's METI energy conservation guidelines:Industrial facility retrofits qualify for subsidized high-efficiency envelope upgrades. Rapid-cycle doors with verified thermal transmittance ratings capture incentive program eligibility.
Industry Challenges
- Cybersecurity hardening for connected systems:Smart door controllers with IP-enabled access management require IEC 62443-aligned security protocols. Operational technology network segmentation demands specialized integration expertise scarce among traditional door installers.
- Certification timeline compression:EU CE marking and US UL 325 safety standard testing create extended product validation cycles. Manufacturers face resource allocation trade-offs between innovation velocity and multi-jurisdiction compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Industrial Door Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Folding Doors, Roller Doors, Overhead Doors End User: Manufacturing Facilities, Warehouses, Retail Outlets, Logistics Centers Installation Type: New Installation, Retrofitting, Maintenance, Upgrade Technology: Sensor-Based, Remote Control, Automatic Opening, Smart Integration |
| Companies Covered | Assa Abloy AB, Hart Door Systems, Gandhi Automations Pvt Ltd, Hörmann Group, Novoferm GmbH, Maviflex, Gilgen Door Systems AG, dormakaba Holding AG, Nabtesco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Industrial Door Market Emerging Trajectories
Automated industrial door technology is converging around unified control architectures that merge environmental separation with building automation and access management. This integration is compressing the traditional boundary between standalone door systems and facility-wide operational platforms.
Machine-vision traffic detection is unifying vehicle recognition, cycle timing optimization, and thermal loss monitoring into single-sensor arrays. Third-party logistics operators in Germany and the United States are deploying these integrated detection systems at high-velocity cross-dock facilities. The technology is unifying previously separate door control, security, and energy management procurement decisions into single-vendor relationships.
EU F-Gas Regulation phase-down schedules are accelerating specification of non-refrigerated rapid-cycle doors as alternatives to air-curtain thermal barriers. Industrial cold-storage operators face escalating compliance costs for hydrofluorocarbon-based climate control. European warehouse developers are responding by prioritizing high-speed insulated door systems that reduce reliance on mechanical refrigeration envelopes.
Buyer procurement patterns are consolidating around lifecycle cost modeling that weights energy performance, maintenance intervals, and downtime risk against initial capital outlay. Large retail distribution networks in the United States are unbundling door specification from general contractor packages. Direct manufacturer relationships are displacing traditional distributor channels in facilities exceeding 500,000 square feet.
Global Automated Industrial Door Market Segmentation
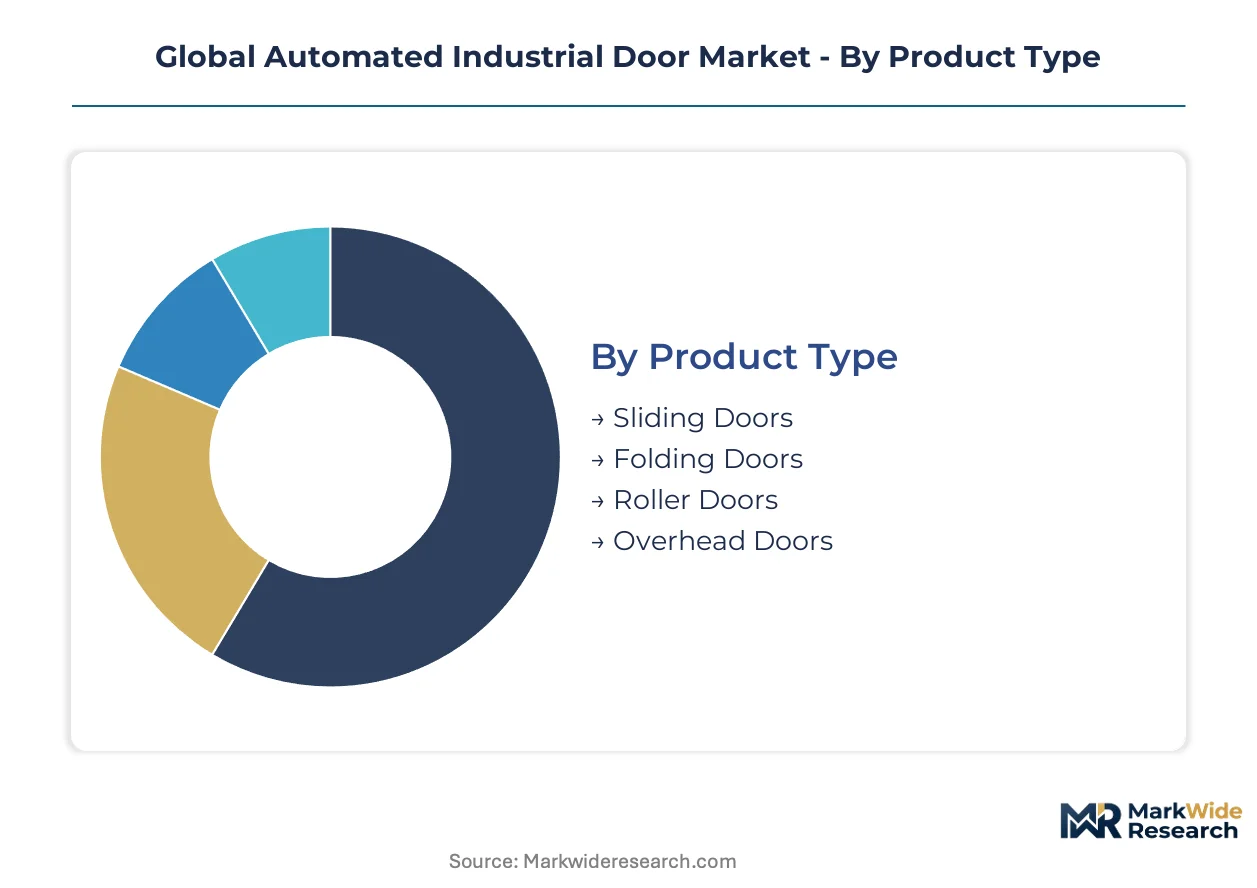
Automated industrial door procurement decisions fragment across four structural dimensions, each imposing distinct certification burdens and lifecycle cost profiles. Facility operators weight thermal performance mandates against retrofit compatibility when mapping specifications to operational requirements.
Product Type:
UL 325 safety certification and CE marking requirements vary sharply by door mechanism, with rapid-cycle systems facing extended validation timelines for electromechanical subassemblies.
- Roller Doors:Steel or aluminum slat assemblies coil around overhead drums, delivering established supply chains and broad retrofit compatibility across aging warehouse stock in Germany and the United States. Cold-chain logistics operators specify polyurethane-insulated variants to satisfy EU Ecodesign thermal transmittance thresholds.
- Overhead Doors:Sectional panel systems with torsion spring counterbalance mechanisms dominate premium commercial specifications. German manufacturing clusters concentrate production of precision-track hardware meeting DIN standards for high-cycle durability.
- Sliding Doors:Horizontal track-mounted systems serve wide-opening aircraft hangar and heavy manufacturing applications. Japanese industrial facilities favor these configurations for seismic resilience under JIS structural loading protocols.
- Folding Doors:Accordion-style fabric or metal curtain systems address constrained header spaces in legacy facilities. Demand concentrates in European urban logistics hubs where building envelope modifications face heritage preservation restrictions.
Roller doors sit at the top of the volume ranking, with smart-integrated overhead configurations climbing the fastest.
End User:
Capital deployment intensity and procurement authority structures diverge substantially across facility operator categories, shaping vendor relationship dynamics.
- Warehouses:High-throughput distribution centers mandate rapid-cycle specifications with sensor arrays for thermal loss minimization. ASHRAE 90.1 cycle-efficiency testing drives specification in United States cold-storage networks.
- Logistics Centers:Cross-dock facilities prioritize vehicle-flow analytics integration with building automation platforms. Third-party operators in the United Arab Emirates specify fully integrated architectures for greenfield developments.
- Manufacturing Facilities:Production environment separation demands contamination-controlled barriers. Indian pharmaceutical plants require CDSCO-inspected cleanroom door systems with positive-pressure seals.
- Retail Outlets:Customer-facing locations balance aesthetic requirements with energy performance. Loading dock configurations dominate automated door procurement for big-box networks.
Warehouses command the largest installed base, while logistics centers are expanding most aggressively.
Installation Type:
Revenue recognition timing and margin profiles shift dramatically across project lifecycle stages, with aftermarket services capturing recurring revenue streams.
- New Installation:Greenfield construction enables full smart-building integration without structural constraints. United States distribution center builds increasingly unbundle door specification from general contractor packages.
- Retrofitting:Aging facility upgrades face header space limitations and concrete threshold irregularities. European electricity pricing volatility complicates insulation core replacement economics.
- Maintenance:Preventive service contracts address electromechanical wear in high-cycle environments. Predictive maintenance capabilities emerge through sensor-enabled condition monitoring.
- Upgrade:Control system modernization extends operational life of mechanical door assemblies. BACnet and Modbus protocol integration enables building automation convergence.
Retrofitting generates the highest project volume currently, with upgrade services showing the steepest margin expansion.
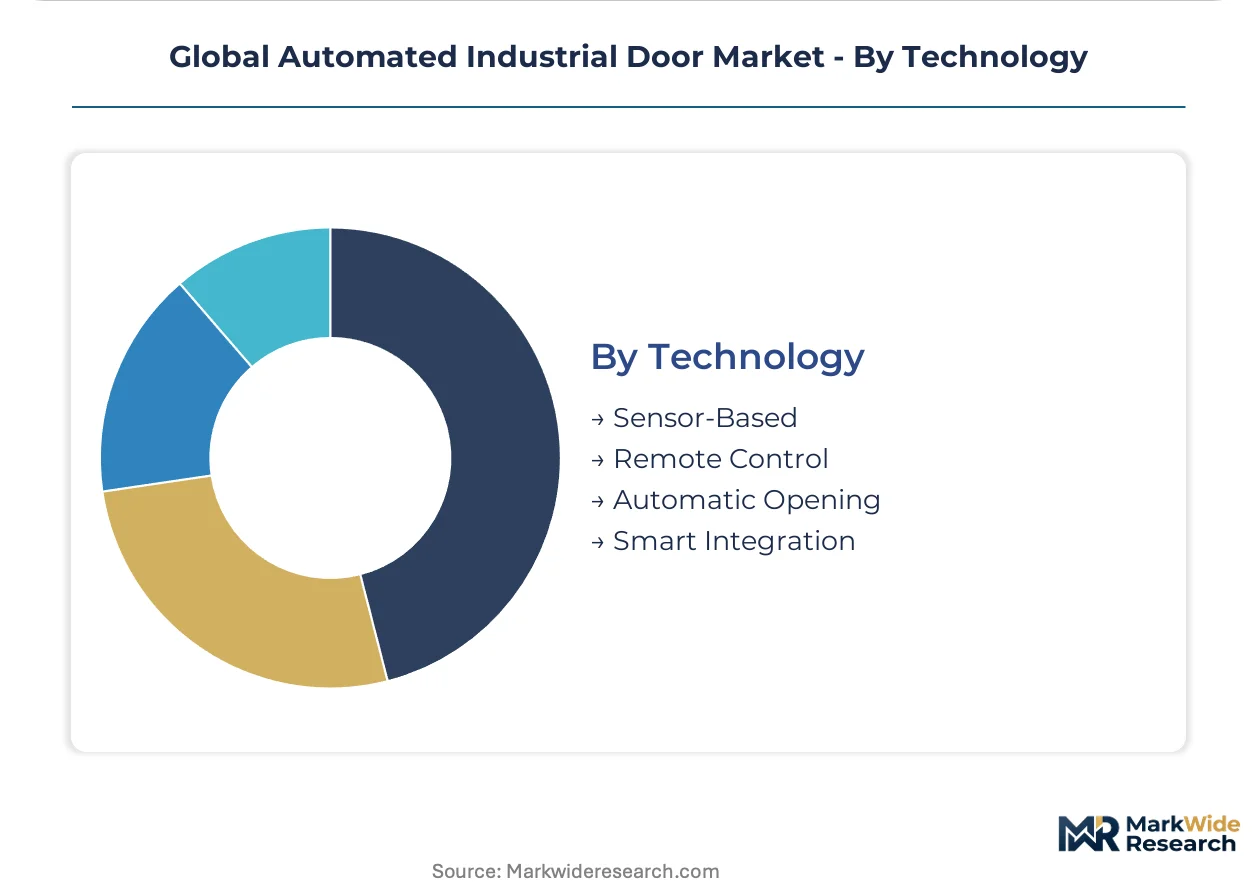
Technology:
Intellectual property intensity and cybersecurity compliance obligations escalate through the technology hierarchy, with connected systems requiring IEC 62443-aligned security protocols.
- Sensor-Based:Microwave and infrared arrays enable touchless entry with real-time traffic data capture. United States high-velocity cross-dock facilities mandate these systems for both hygiene protocols and flow optimization.
- Smart Integration:IP-enabled controllers merge access management with operational technology networks. Penetration remains limited to greenfield distribution centers with full building automation architectures.
- Automatic Opening:Pressure mat and loop detector triggers serve established industrial applications with lower connectivity requirements. These configurations avoid cybersecurity hardening costs.
- Remote Control:Radio-frequency handheld units persist in hazardous environment applications where wired connectivity proves impractical. Mining and chemical processing facilities maintain specifications.
Sensor-based systems dominate current shipments, with smart integration gaining share fastest among new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters anchor workforce concentration for precision drive systems, while Japanese electromechanical suppliers concentrate gearbox manufacturing. Indian installation labor pools support rapid deployment across South Asian pharmaceutical corridors.
United States
High-velocity cross-dock facilities in Memphis and Louisville mandate sensor-integrated rapid-cycle doors for thermal loss minimization. ASHRAE 90.1 cycle-efficiency testing drives specification across cold-storage networks. Third-party logistics operators in Dallas-Fort Worth unbundle door procurement from general contractor packages.
Germany
Polyurethane-insulated roller doors dominate retrofit activity in Ruhr Valley warehouse clusters facing EU Ecodesign thermal transmittance mandates. DIN-standard precision-track hardware manufacturing concentrates in North Rhine-Westphalia. Hörmann Group leverages Central European production scale for premium overhead door tier supply.
China
GB standards compliance shapes aluminum slat and curtain panel specifications for Yangtze River Delta distribution center construction. Domestic electromechanical drive system suppliers expand capacity for high-cycle door applications. Shanghai and Suzhou logistics hubs prioritize rapid-cycle deployment for e-commerce fulfillment velocity.
India
CDSCO-inspected pharmaceutical plants in Maharashtra and Gujarat deploy contamination-controlled high-speed curtain systems with positive-pressure seals. WHO-GMP certification requirements tighten environmental control specifications for export-oriented formulation facilities. Gandhi Automations anchors South Asian cleanroom door engineering capabilities.
Japan
METI energy conservation guidelines subsidize high-efficiency envelope upgrades across Kanto industrial corridor retrofits. JIS structural loading protocols favor sliding door configurations for seismic resilience. Osaka and Nagoya manufacturing clusters specify rapid-cycle doors with verified thermal transmittance ratings for incentive program eligibility.
Global Automated Industrial Door Market Vendor Landscape
Top-tier vendors anchor premium sensor-integrated architectures, while mid-scale fabricators compete on retrofit compatibility and regional installation density. The market exhibits tiered concentration with electromechanical specialists, building automation integrators, and regional door fabricators occupying distinct competitive positions. Strategic moves center on backward integration into drive system manufacturing and geographic expansion through distributor network acquisition.
Among European-headquartered conglomerates, Assa Abloy AB and dormakaba Holding AG exemplify building automation convergence strategies, while Hörmann Group occupies a position as a scale-driven Central European manufacturer. Gandhi Automations Pvt Ltd represents the specialist archetype focused on contamination-controlled applications. These three anchors illustrate the competitive spectrum from integrated access-control platforms to regional cleanroom engineering depth.
| Leading Market Players |
|---|
| Assa Abloy AB |
| Hart Door Systems |
| Gandhi Automations Pvt Ltd |
| Hörmann Group |
| Novoferm GmbH |
| Maviflex |
| Gilgen Door Systems AG |
| dormakaba Holding AG |
| Nabtesco Corporation |
| Others |
Supply Flow & Price Mechanics
Polyurethane insulation core manufacturing costs trace directly from European electricity pricing through to premium rapid-cycle door tiering, with energy-intensive polymer production anchoring margin structures across German and Dutch warehouse retrofit markets.
Pricing Analysis
The bundled-versus-unbundled service split separates project-based new installations from recurring maintenance contract revenue streams. Three-tier pricing structure across premium sensor-integrated, standard rapid-cycle, and economy roller configurations stratifies by ASHRAE 90.1 certification grade and after-sales service bundling. Pricing pressure stems from aluminum slat input volatility tied to primary smelting energy costs. Cold-chain logistics operators show lowest price sensitivity due to thermal envelope compliance mandates, while aging facility retrofit buyers in the United States exhibit highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Precision electromechanical drive system supply rests on German and Japanese industrial automation specialists for high-cycle motor and gearbox assemblies. Aluminum slat and polyurethane curtain panel production draws from Chinese extrusion capacity and European polymer processing clusters. Single-source vulnerability concentrates in precision-track hardware meeting DIN durability standards. Distribution runs through manufacturer-direct relationships displacing traditional channels in large-format distribution centers exceeding 500,000 square feet.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Ecodesign thermal mandate compliance costs in Germany and subsidized high-efficiency envelope upgrade incentives under Japan's METI guidelines.
For Market Incumbents: Lock in sensor-integrated system specifications through BACnet and Modbus protocol certification investments before building automation convergence accelerates. Backward integration into electromechanical drive manufacturing reduces exposure to German and Japanese component supply concentration. Threat from mid-scale regional fabricators competing on retrofit compatibility demands channel control reinforcement in distributor networks. For New Entrants and Emerging Players: CDSCO-inspected pharmaceutical cleanroom door engineering in Maharashtra and Gujarat represents an underserved buyer archetype with domestic capability gaps relative to WHO-GMP certification volume requirements. White-space targets include contamination-controlled rapid-cycle barriers for export-oriented formulation plants and predictive maintenance service contracts for aging high-cycle installations. Go-to-market angle centers on specialized positive-pressure seal engineering partnerships with regional installation labor pools. For Investors and Strategic Acquirers: Consolidation pressure builds where electromechanical drive system supply concentration intersects with cybersecurity hardening requirements for IP-enabled smart door controllers. Long-term viability favors platforms with IEC 62443-aligned security protocols and building automation integration depth over standalone hardware fabricators. Acquisition target archetype: regional specialists with cleanroom engineering capabilities and underdeveloped aftermarket service infrastructure. Signal to watch: unbundling of door specification from general contractor packages in greenfield distribution center procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive Systems | Captive supply of precision motors reduces exposure to German and Japanese component concentration. |
| Smart Building Platform Certification | BACnet and Modbus protocol integration enables predictive maintenance and energy analytics convergence. |
| Pharmaceutical Cleanroom Specialization | CDSCO and WHO-GMP certification capabilities unlock Maharashtra and Gujarat formulation plant demand. |
| Cybersecurity Protocol Investment | IEC 62443-aligned security hardening addresses operational technology network segmentation requirements. |
| Regional Installation Network Acquisition | Distributor channel control reinforces position against retrofit-focused mid-scale fabricators. |
Methodological Framework
Coverage spans Germany, the United States, China, India, and Japan, with primary inputs from each market cluster combining interviews with facility maintenance directors, warehouse procurement managers, OEM engineering teams, and aftermarket service heads with secondary validation. Trade customs data, SEC filings from building automation conglomerates, DIN and JIS standard documentation, and CDSCO facility inspection records anchored supply-side and demand-side triangulation. Bottom-up installation volume estimates and top-down construction spend allocation were cross-referenced across the analysis.
Rate-of-change decomposition separated volume growth from value-per-unit shifts across product type, end user, installation type, and technology segmentation dimensions. CAGRs were derived from regression-based trend extrapolation incorporating regulatory mandate implementation timelines, raw material cost trajectories, and greenfield construction pipeline visibility. Industry-specific forecast inputs included EU Ecodesign thermal transmittance threshold adoption curves and ASHRAE 90.1 cycle-efficiency testing penetration rates.
Inputs from facility operator interviews and regulatory filing databases were available through the study window; gaps in real-time cybersecurity incident reporting for connected door systems introduce uncertainty bands around smart integration adoption timelines. Forecasts reflect assumptions about incentive program continuity and electromechanical component supply stability. A small set of triggers—EU F-Gas Regulation enforcement intensity, Japanese METI subsidy renewal, and aluminum smelting energy cost volatility—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Portable Ramps Market
Specialized Building Services
Industrial Access Platform Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
Street Furniture Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Horizontal Directional Drilling Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Private Bunker Market