
 Private Bunker Market | 2026-2036
Private Bunker Market Size, Share, and Industry Trends Forecast 2026-2036
Private Bunker Market Insights
Steel-reinforced composite walling is shifting traditional bunker construction economics by reducing installation timelines and transportation costs versus monolithic concrete. Rising S Bunkers leverages in-house steel fabrication to control material costs across its Texas manufacturing base. Vivos Group dominates the community-scale shelter segment with multi-unit underground complexes in South Dakota and Kansas. Atlas Survival Shelters differentiates through modular galvanized steel designs that ship flat-pack to residential sites.
Private bunkers are hardened protective structures engineered to withstand blast overpressure, chemical infiltration, and extended habitation, typically incorporating NBC filtration, redundant power, and ballistic-rated entry systems with wall thicknesses exceeding 12 inches of reinforced composite or concrete. Underground bunkers command the largest product category share due to superior thermal masking and blast deflection, while mobile shelters represent the fastest-expanding segment driven by corporate security teams requiring relocatable asset protection. High net worth individuals anchor end-user demand, though government agencies sustain procurement volumes through civil defense modernization programs.
FEMA publishes safe room design criteria that shape residential product specifications, while OSHA and EPA standards govern ventilation and hazardous material containment in commercial installations. The Department of Defense MIL-STD-188 and UFC 4-010-01 further define blast resistance benchmarks for military-adjacent contracts. Stakeholders must monitor evolving state-level building code adoptions of ICC 500 storm shelter standards, as jurisdictions across Florida, Oklahoma, and Kansas tighten requirements that directly expand addressable market scope.
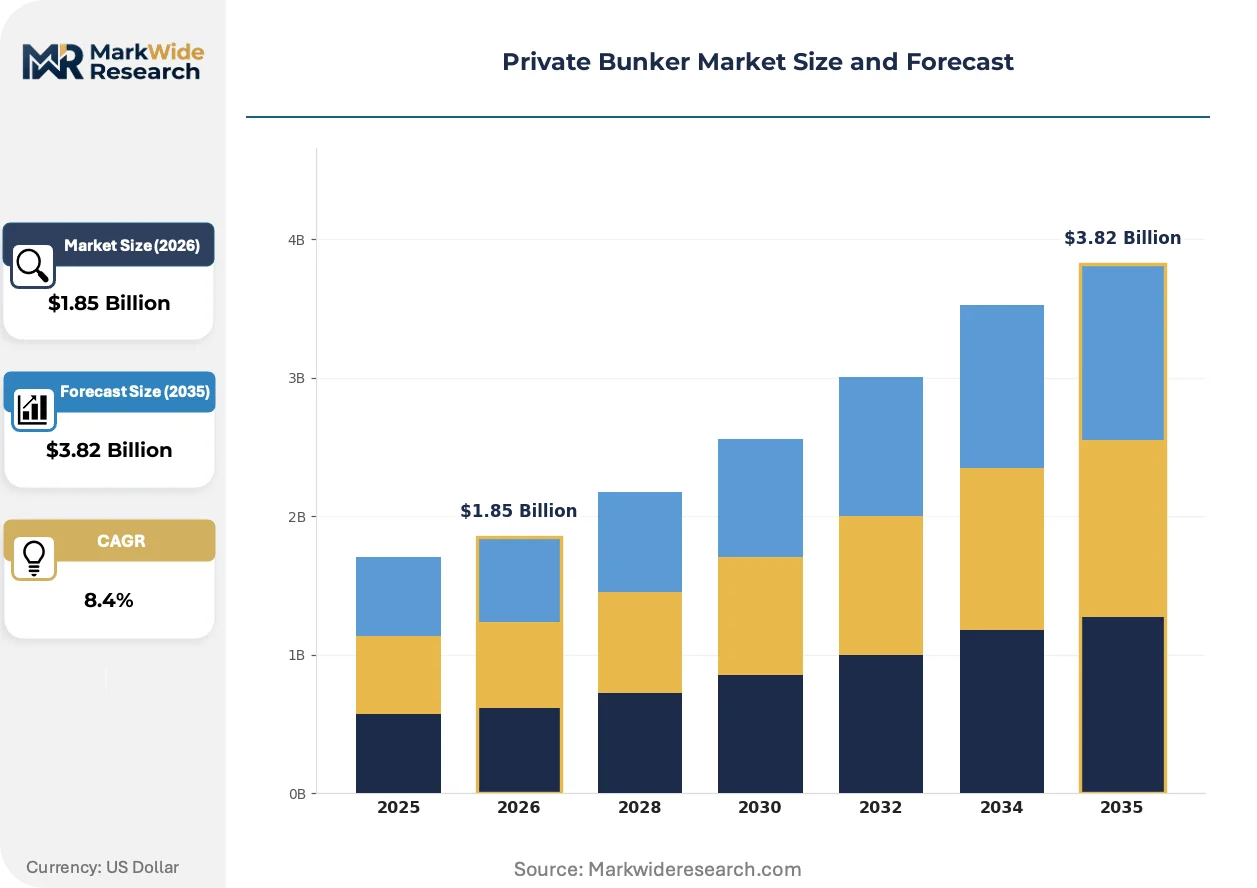
Market Dynamics
Steel-reinforced composite walling is compressing installation timelines and transportation economics, displacing monolithic concrete as the dominant construction methodology for residential and corporate shelter deployments.
Growth Catalysts
- FEMA Safe Room Guidelines:Updated federal design criteria for blast and wind resistance are mandating hardened shelter specifications across tornado-prone counties, directly expanding residential addressable demand.
- Climate Disaster Frequency:Escalating hurricane intensity and wildfire seasons in coastal and western states are accelerating household-level preparedness investments among property owners.
- Geopolitical Anxiety:Heightened international tension is driving corporate security programs to procure redundant asset protection infrastructure for critical personnel and data systems.
Market Restraints
- Steel Price Volatility:Fluctuations in hot-rolled steel and galvanized sheet inputs create margin pressure for fabricators without captive supply arrangements or long-term procurement hedges.
- Specialized Labor Scarcity:Certified welders and NBC filtration technicians concentrate in defense-adjacent regions, constraining installation capacity outside Texas and Florida corridors.
- Zoning and Permitting Friction:Municipal building departments in California and northeastern states impose extended review cycles for below-grade structures, elongating project timelines.
Strategic Opportunities
- Underpenetrated Mountain West:Colorado, Utah, and Idaho exhibit low shelter penetration relative to seismic and wildfire risk profiles, presenting greenfield residential demand.
- Corporate Mobile Shelters:Relocatable hardened units for executive protection teams represent an emerging procurement category distinct from fixed residential installations.
- ICC 500 Code Adoption:Oklahoma and Kansas municipalities are tightening storm shelter mandates, creating regulatory tailwinds for compliant product specifications.
Industry Challenges
- NBC Filtration Certification Delays:Third-party validation of chemical-biological-radiological systems against MIL-STD-188 benchmarks extends product development cycles by 8-14 months.
- Site Integration Complexity:Coordinating electrical, HVAC, and ballistic entry systems with existing residential infrastructure requires specialized subcontractor networks that fragment outside primary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Bunker Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Underground Bunkers, Above Ground Shelters, Mobile Shelters, Blast Resistant Structures, Reinforced Concrete Units End User: Military Personnel, Corporate Executives, High Net Worth Individuals, Government Agencies, Emergency Responders Security Feature: Air Filtration Systems, Surveillance Cameras, Biometric Access, Blast Doors, Emergency Power Supply Use Case: Disaster Preparedness, Tactical Operations, Long-Term Survival, Safe Rooms, Data Protection |
| Companies Covered | Rising S Bunkers, Vivos Group, Atlas Survival Shelters, Survival Condo Project, The Safe House, American Bunker, Global Bunkers, Safe House Shelters, Redoubt Bunkers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Bunker Market Trends and Innovations
Modular fabrication methods and intelligent environmental controls are transforming how protective structures are engineered, deployed, and maintained across residential and corporate end-uses.
Galvanized steel modular designs are integrating flat-pack shipping configurations with on-site bolted assembly, eliminating the need for specialized heavy-lift equipment at residential locations. High net worth households in Texas and Florida are specifying these systems for garage-concealed installations that preserve property aesthetics. The technology is integrating supply chain efficiencies that compress total project duration from 90 days to under 30 days for standard configurations.
OSHA ventilation standards for confined-space habitation are tightening filtration and air-exchange requirements for commercial installations above 200 square feet. The revised criteria mandate redundant power systems and automated atmospheric monitoring, increasing specification complexity for corporate security buyers. Defense contractors and data center operators in Virginia and Maryland are front-running compliance through early adoption of MIL-STD-188 aligned systems.
Direct-to-consumer digital channels are displacing traditional contractor-mediated sales for residential shelter procurement. Manufacturers now maintain configurator tools that generate engineered drawings and permit packages without intermediary architectural services. This pattern is most visible in Florida, where hurricane-season demand spikes overwhelm conventional construction sales capacity during compressed decision windows.
Private Bunker Market Segmentation
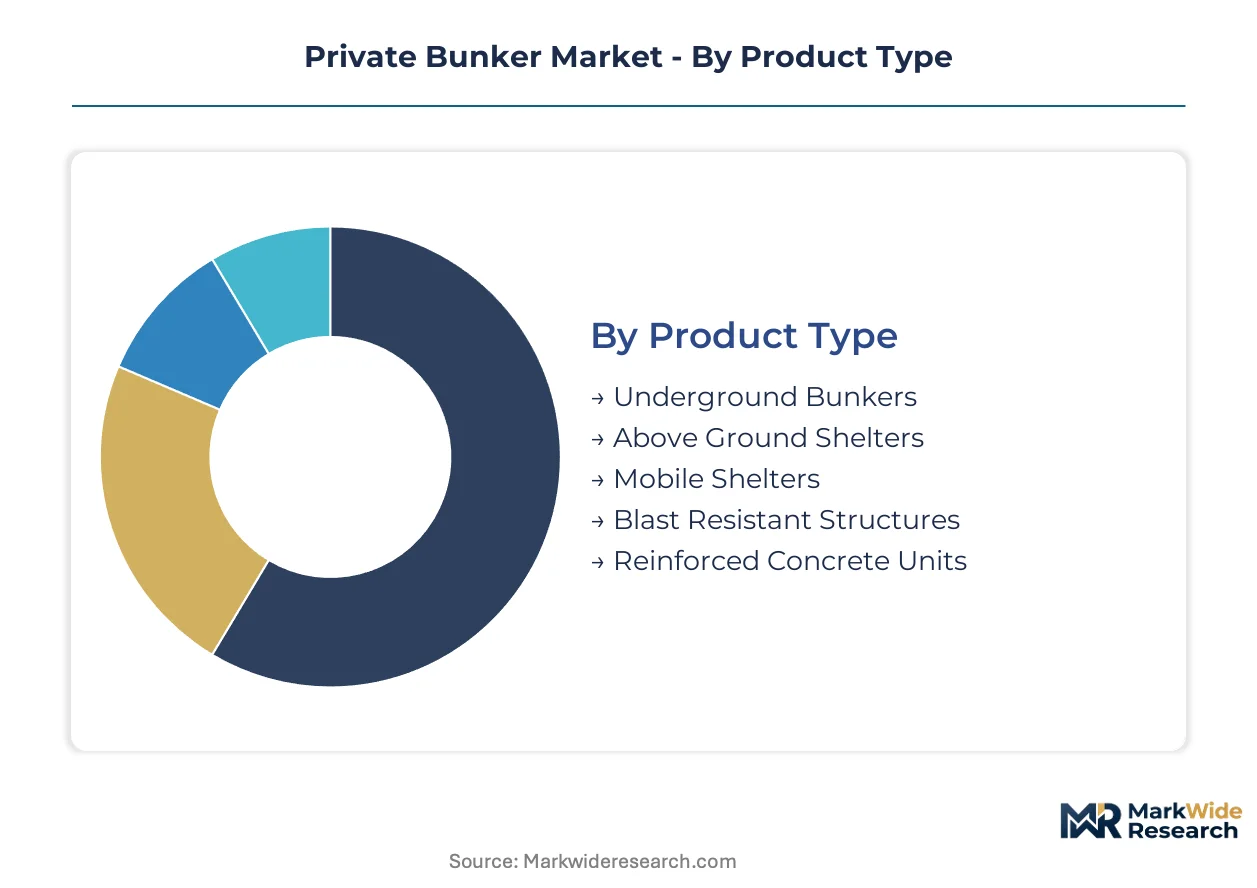
Segmentation in the private bunker market reveals how threat perception, asset value, and regulatory pressure shape procurement patterns. Buyers prioritize structural specifications and security features based on whether they face natural disasters, civil unrest, or geopolitical risk scenarios.
Product Type:
Replacement cycles favor modular steel systems over legacy concrete installations, compressing upgrade timelines from decades to under ten years for affluent households.
- Underground Bunkers:Reinforced composite or concrete structures buried below grade deliver superior thermal masking and blast deflection for residential estates. Texas and Florida high net worth households dominate procurement following updated FEMA safe room guidelines that mandate below-grade specifications for tornado-prone counties.
- Mobile Shelters:Relocatable hardened units on trailer or skid-mounted frames serve corporate security teams requiring asset protection across multiple facilities. Corporate security programs in Virginia and Maryland are accelerating procurement of these systems for executive protection details and data center redundancy.
- Above Ground Shelters:Surface-mounted reinforced structures suit sites with high water tables or bedrock constraints.
- Blast Resistant Structures:Engineered to withstand specific overpressure thresholds for military-adjacent contracts.
- Reinforced Concrete Units:Monolithic pour construction persists in government civil defense installations with century-scale durability requirements.
Volume placements concentrate in Underground Bunkers; the faster expansion belongs to Mobile Shelters.
End User:
Customer type determines specification complexity, with private buyers demanding aesthetic concealment while institutional purchasers prioritize interoperability standards.
- High Net Worth Individuals:Affluent households in disaster-prone states procure residential shelters with garage-concealed or landscape-integrated designs. Florida hurricane corridors and Texas tornado alleys exhibit the densest installation concentration as climate disaster frequency accelerates preparedness spending.
- Government Agencies:Federal and state entities modernize civil defense infrastructure through hardened command centers and redundant facilities. FEMA and Department of Defense procurement programs sustain baseline manufacturing capacity through multi-year shelter deployment contracts.
- Corporate Executives:Fortune 500 security programs invest in executive protection infrastructure for critical personnel.
- Military Personnel:Defense-adjacent contracts require MIL-STD-188 aligned blast resistance and NBC filtration.
- Emergency Responders:Fire and police departments procure community-scale shelters for continuity-of-operations planning.
Procurement volume clusters with High Net Worth Individuals; Government Agencies provide the steadiest contract flow.
Security Feature:
Feature selection tracks threat vectors, with air quality systems and access control commanding premium positioning in specification hierarchies.
- Air Filtration Systems:NBC-rated filtration units with carbon and HEPA stages protect against chemical, biological, and radiological infiltration. Third-party validation against MIL-STD-188 benchmarks extends development cycles, constraining supplier capacity for commercial installations.
- Biometric Access:Fingerprint, iris, and facial recognition entry systems prevent unauthorized penetration while logging access events. Corporate security buyers in finance and technology sectors specify these systems for data protection bunkers requiring audit trails.
- Surveillance Cameras:Hardened camera networks with low-light capability monitor perimeter and interior zones.
- Blast Doors:Ballistic-rated entry systems with multi-point locking withstand forced entry and overpressure events.
- Emergency Power Supply:Redundant battery, generator, and solar configurations sustain habitation during grid failure.
Specification frequency peaks with Air Filtration Systems; Biometric Access is climbing fastest in corporate deployments.
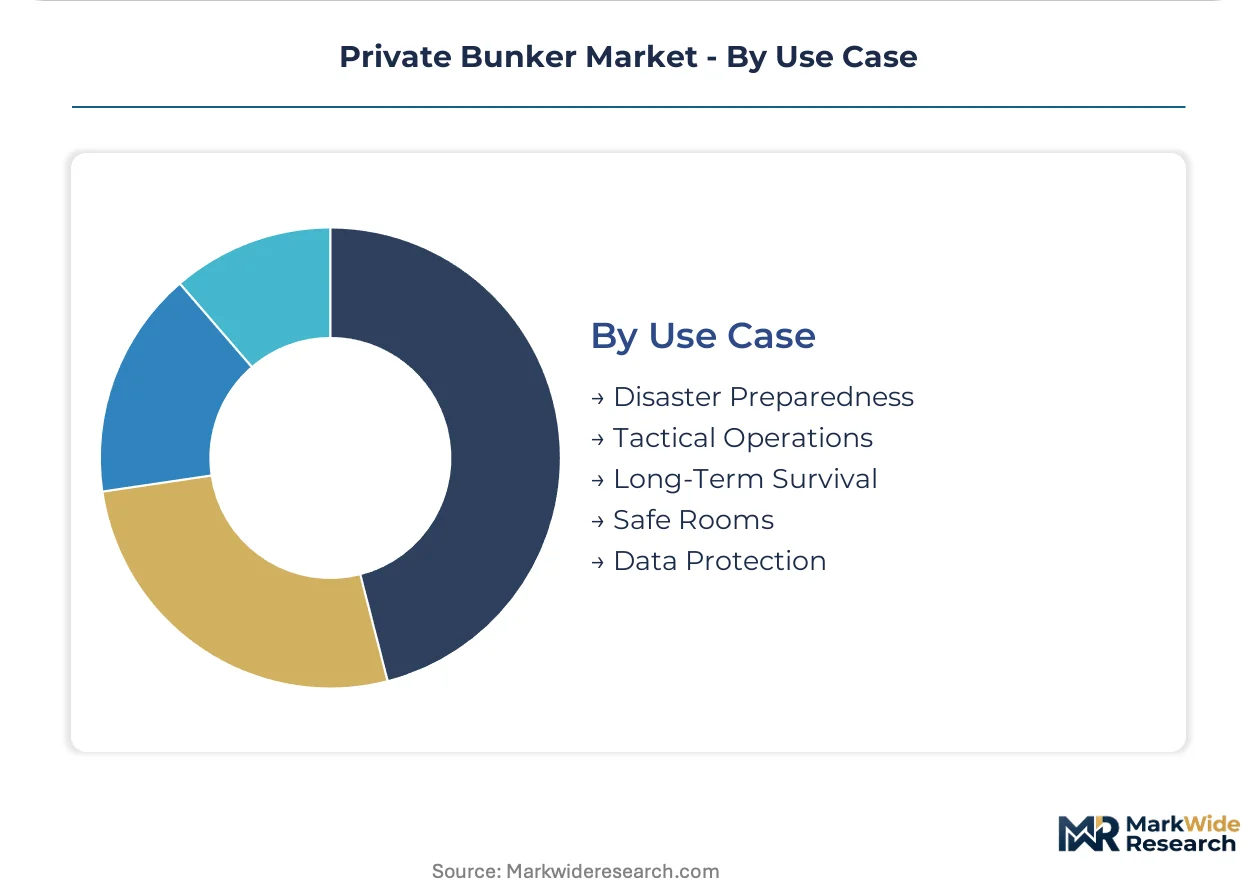
Use Case:
Application context dictates footprint, duration, and system redundancy requirements across residential and institutional deployments.
- Disaster Preparedness:Residential and community shelters engineered for 72-hour to two-week habitation during hurricanes, tornadoes, or wildfires. Florida and Oklahoma building code adoptions of ICC 500 standards are mandating compliant shelter specifications in new construction.
- Data Protection:Hardened facilities for critical server infrastructure and document archives with environmental controls. Data center operators in Virginia and Maryland are front-running OSHA ventilation compliance through early adoption of redundant atmospheric monitoring.
- Tactical Operations:Military and law enforcement command posts with secure communications and weapon storage.
- Long-Term Survival:Extended-duration shelters with hydroponics, water reclamation, and medical facilities.
- Safe Rooms:Single-purpose panic rooms within residential structures for immediate threat response.
Deployment frequency centers on Disaster Preparedness; Data Protection is gaining share fastest among corporate buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High net worth households in the United States concentrate the majority of private bunker procurement, with state-level building code adoptions and climate risk exposure creating distinct demand corridors across four additional national markets.
United States
Texas and Florida households drive residential installations following FEMA safe room guideline updates that mandate hardened shelter specifications in tornado-prone counties. The Department of Defense sustains manufacturing capacity through MIL-STD-188 aligned procurement programs for blast-resistant infrastructure. Dallas-Fort Worth and Miami-Dade industrial clusters host steel fabrication facilities supplying modular galvanized systems to affluent coastal and inland markets.
Canada
Wildfire evacuation protocols in British Columbia and Alberta are accelerating community-scale shelter investments among rural municipalities and remote resource extraction operators. Health Canada guidelines for confined-space ventilation shape commercial installation standards above 200 square feet. Calgary-based fabricators are expanding flat-pack modular production to serve prairie provinces facing escalating severe weather frequency.
Australia
Bushfire defense requirements in New South Wales and Victoria are mandating ember-resistant construction standards that extend to private protective structures on rural estates. The country's national building code regulator is evaluating ICC 500 storm shelter adoptions for cyclone-prone Queensland coastlines. Sydney and Melbourne metropolitan areas exhibit concentrated demand among technology executives and mining sector principals seeking redundant asset protection.
Switzerland
Historic civil defense infrastructure modernization is creating commercial opportunities for NBC filtration system upgrades in alpine bunker networks. Swissmedic-aligned quality standards for extended-duration habitation systems influence specification hierarchies across European premium-tier procurement. Zurich and Geneva private banking corridors sustain demand among ultra-high-net-worth individuals requiring secure document and personnel protection facilities.
Israel
Mandatory residential shelter regulations in high-threat zones sustain baseline manufacturing capacity for reinforced concrete and composite walling systems. The country's national security apparatus maintains procurement programs for tactical command posts with secure communications infrastructure. Tel Aviv and Haifa industrial districts concentrate blast-resistant engineering expertise serving both domestic requirements and export markets.
Private Bunker Market Competitive Landscape
Capacity expansion dominates the current landscape as fabricators scale steel-reinforced composite production to compress installation timelines. The vendor base clusters around three strategic archetypes: in-house steel producers controlling material costs, community-scale shelter developers operating multi-unit complexes, and modular specialists leveraging flat-pack logistics. Geographic expansion into underpenetrated mountain west states and portfolio diversification into corporate mobile shelters represent the two dominant competitive vectors reshaping positioning.
Among Texas-based fabricators, Rising S Bunkers exemplifies the captive supply archetype through in-house steel production controlling input costs. Vivos Group occupies the community-scale developer position with multi-unit underground complexes concentrated in South Dakota and Kansas. Atlas Survival Shelters represents the modular logistics specialist tier, with flat-pack galvanized designs shipping to residential sites without heavy-lift equipment requirements.
| Leading Market Players |
|---|
| Rising S Bunkers |
| Vivos Group |
| Atlas Survival Shelters |
| Survival Condo Project |
| The Safe House |
| American Bunker |
| Global Bunkers |
| Safe House Shelters |
| Redoubt Bunkers |
| Others |
Pricing and Supply Chain Analysis
Steel-reinforced composite walling is compressing both material costs and installation timelines while concentrating fabrication capacity among Texas and Florida producers with captive steel supply. This production-method transition simultaneously reduces per-unit pricing for residential buyers and tightens margin capture for integrated fabricators against concrete-dependent competitors.
Pricing Analysis
Volume placements concentrate in standard modular configurations while margins concentrate in customized NBC filtration systems and biometric integration tiers. Price differentiation hinges on ICC 500 certification grade and FEMA safe room compliance level, with galvanized steel modular units commanding premiums over above-ground alternatives. Pricing pressure stems from hot-rolled steel input volatility, compressing fabricator margins without long-term procurement hedges. Corporate security buyers exhibit lowest price sensitivity given executive protection mandates, while rural residential purchasers in underpenetrated mountain west states demand economy-tier offerings.
Supply Chain Analysis
Freight economics favor flat-pack modular designs that ship via standard trucking networks rather than specialized heavy-lift convoys required for monolithic concrete segments. Geographic supply concentration centers on Texas, Florida, and Virginia fabrication clusters serving domestic demand. Raw material dependencies include hot-rolled steel sheet, galvanized coil, and carbon-HEPA filtration media. Single-source vulnerability concentrates in certified NBC filtration component suppliers with MIL-STD-188 validation capacity. Distribution runs through direct-to-consumer digital channels displacing traditional contractor mediation, particularly in Florida hurricane-season demand spikes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular galvanized steel fabrication is displacing monolithic concrete as the dominant construction methodology, creating repositioning windows for supply-captive incumbents and technology-forward entrants.
For Market Incumbents: Anticipate margin compression from steel price volatility by securing captive supply arrangements or backward integration into steel production. Defensive consolidation should target certified NBC filtration technicians and welding capacity in defense-adjacent regions to constrain competitor installation scale. Priority investment belongs to automated configurator tools that compress sales-to-permit timelines for Florida hurricane-season demand windows. For New Entrants and Emerging Players: Enter via corporate mobile shelter procurement, where relocatable hardened units for executive protection teams represent underdeveloped demand distinct from fixed residential installations. Colorado, Utah, and Idaho present greenfield residential opportunities given low shelter penetration relative to seismic and wildfire risk profiles. Go-to-market positioning should emphasize flat-pack logistics compatibility with standard freight networks to bypass specialized heavy-lift infrastructure requirements. For Investors and Strategic Acquirers: Re-rating potential sits with community-scale shelter developers given regulatory tailwinds from ICC 500 code adoptions across Oklahoma and Kansas municipalities. Long-term viability favors fabricators with in-house steel production controlling input costs against commodity exposure. The signal to watch is state-level building code adoption velocity, as jurisdictions tightening storm shelter mandates directly expand addressable market scope.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Steel Production Integration | Backward integration into hot-rolled and galvanized coil supply insulates margin capture against commodity volatility cycles. |
| Flat-Pack Modular Platform Expansion | Standardized bolted-assembly designs compress project duration from ninety days to under thirty days for residential configurations. |
| NBC Filtration Certification Investment | MIL-STD-188 aligned validation creates eight-to-fourteen-month development moats constraining competitor capacity expansion. |
| Direct-to-Consumer Digital Channel Buildout | Configurator tools generating engineered drawings displace intermediary architectural services in Florida demand spikes. |
| Mountain West Geographic Expansion | Colorado and Idaho fabrication facilities address greenfield demand from wildfire and seismic risk exposure. |
Research Methodology
Document review covered FEMA safe room design criteria, OSHA ventilation standards, ICC 500 storm shelter specifications, and Department of Defense MIL-STD-188 benchmarks, complemented by interviews with steel fabrication plant managers, NBC filtration system engineers, corporate security procurement leads, residential shelter installation contractors, and municipal building code officials. Secondary validation drew from SEC filings of publicly traded defense contractors, customs records of steel import flows, and state-level building permit databases. Bottom-up unit economics triangulated against top-down addressable household projections across disaster-prone counties.
Cross-referencing historical installation patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, security feature tier, and use case application. CAGRs derived from unit placement trajectories weighted against regulatory adoption curves and climate disaster frequency indices. Industry-specific forecast inputs incorporated FEMA guideline revision schedules and state-level ICC 500 code adoption timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel tariff volatility and municipal permitting friction scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
Industrial Access Platform Market
Specialized Building Services
Street Furniture Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Horizontal Directional Drilling Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Portable Ramps Market