
 Portable Ramps Market | 2026-2036
Portable Ramps Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Ramps Market Outlook
The portable ramps market is consolidating around a sharp split between premium aluminum modular systems and commodity-grade steel folding products. EZ-ACCESS dominates the premium tier through its patented adjustable-length platforms and direct-to-consumer distribution network. Prairie View Industries anchors the mass-market channel with standardized folding ramps stocked through medical supply distributors and big-box retailers.
Portable ramps are load-bearing inclined surfaces engineered from aluminum alloys, steel, or reinforced polymers to bridge vertical level changes for wheelchairs, scooters, and wheeled equipment, typically rated between 600 and 1,500 pounds capacity and spanning 2 to 12 feet in deployed length. Folding ramps and wheelchair ramps command the largest revenue pools due to recurring replacement cycles in home healthcare settings, while vehicle ramps and scooter ramps generate faster growth as mobility device ownership expands among recreational and commercial fleets. Aluminum's corrosion resistance and strength-to-weight ratio sustain its position as the dominant material specification across institutional procurement channels.
The ADA Standards for Accessible Design in the United States, the EU's Construction Products Regulation, and Japan's JIS accessibility standards collectively define slope ratios, surface friction coefficients, and edge protection requirements that determine product compliance and market access. Enforcement variance across municipal building departments creates fragmented certification burdens for manufacturers serving multiple jurisdictions. Stakeholders must monitor evolving accessibility mandates tied to public infrastructure spending and residential retrofit incentive programs to anticipate demand inflections.
Market Dynamics
Portable ramp procurement is fragmenting between institutional bulk purchasing and direct-to-consumer channels, with aluminum modular systems capturing specification-driven contracts while steel folding units dominate retail velocity. This bifurcation is compressing mid-tier suppliers unable to achieve scale in either channel.
Growth Catalysts
- Medicare reimbursement expansion:CMS durable medical equipment classifications now explicitly cover threshold ramps for home-based care, channeling federal funding toward aging-in-place retrofits across the United States.
- Japan's barrier-free mandate:METI enforcement of JIS accessibility standards for public buildings and transportation infrastructure is mandating portable ramp inventory at commercial facilities nationwide.
- Reinforced polymer maturation:Glass-fiber composite manufacturing is achieving aluminum-comparable strength-to-weight ratios at 40% lower raw material volatility, enabling new entrant competition in premium segments.
Market Restraints
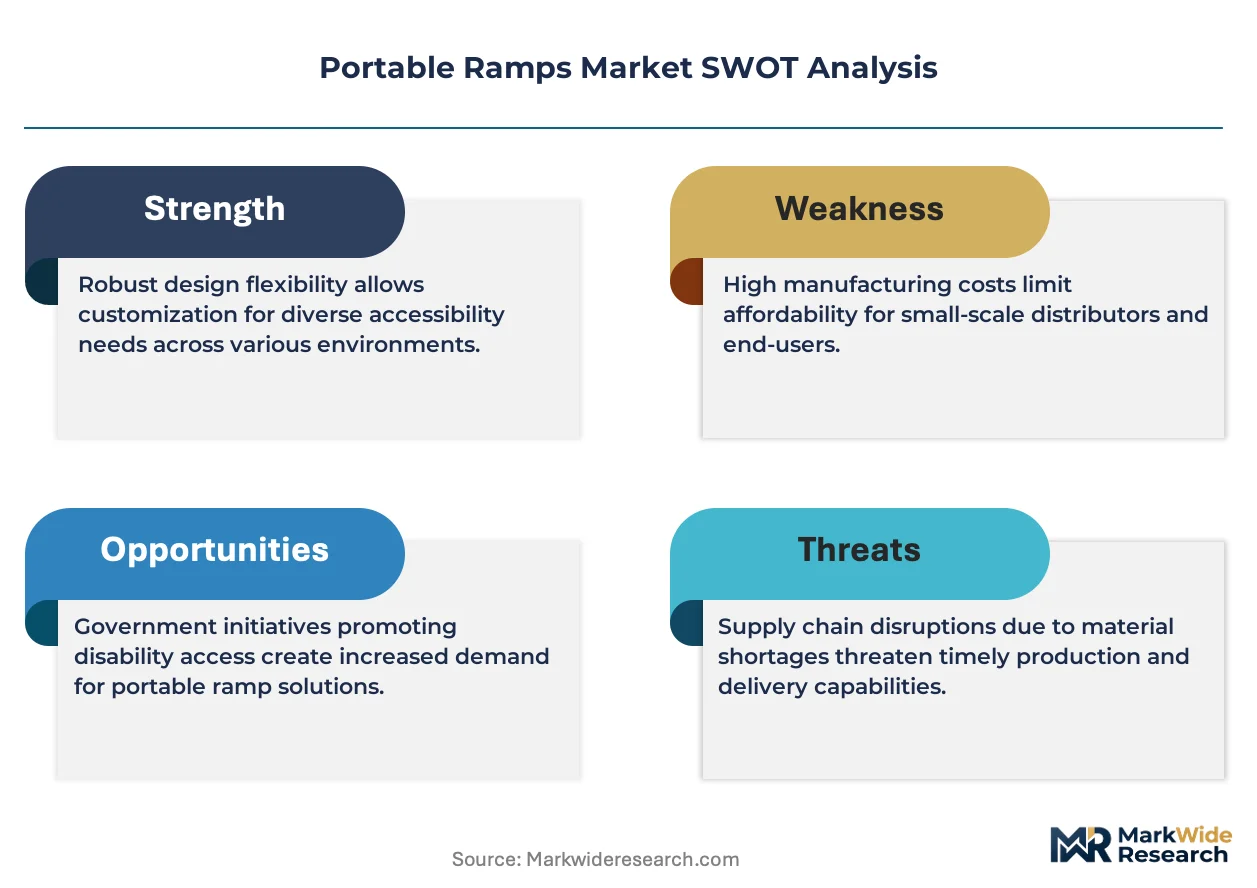
- Aluminum price volatility:LME aluminum futures swings above 15% annually are compressing fabricator margins and forcing quarterly contract renegotiations with institutional buyers.
- Regional certification fragmentation:Divergent slope ratio requirements between ADA Standards, EU Construction Products Regulation, and Japan's JIS codes multiply testing burdens for cross-border suppliers.
- Modular elevator substitution:Vertical platform lifts for residential retrofits are capturing specification share above 30-inch rise thresholds where ramp run lengths become impractical.
Strategic Opportunities
- German residential retrofit incentives:KfW banking group subsidized loans for accessibility modifications are unlocking homeowner-funded ramp installations outside traditional medical channels.
- Vehicle fleet electrification:Commercial van and last-mile delivery operators are specifying lightweight aluminum ramps for cargo area access as electric vehicle payload sensitivity increases.
- Telehealth-integrated assessment:Occupational therapy remote evaluation platforms are enabling direct-to-patient ramp specification, bypassing traditional durable medical equipment distributors.
Industry Challenges
- Installation technician scarcity:Certified accessibility equipment installers are concentrated in metropolitan markets, creating service gaps in rural Medicare-eligible populations.
- Multi-jurisdiction compliance latency:Municipal building department variance in ADA enforcement interpretation extends product approval timelines by 60-90 days for national distribution programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Ramps Market |
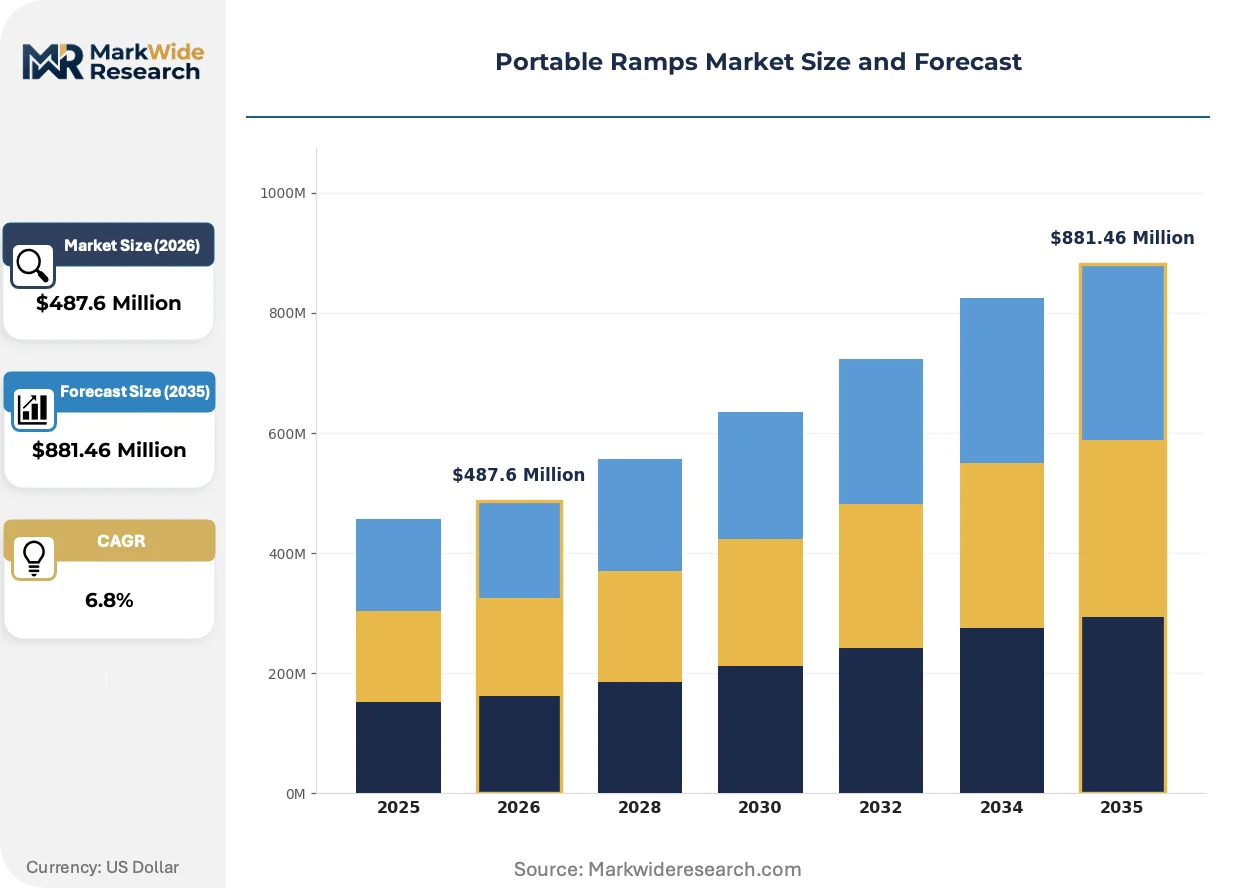
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Ramps, Wheelchair Ramps, Scooter Ramps, Vehicle Ramps Material: Aluminum, Steel, Plastic, Rubber End User: Individuals, Healthcare Facilities, Transportation Services, Recreational Vehicle Owners Application: Home Use, Commercial Use, Outdoor Activities, Event Setup |
| Companies Covered | Roll-a-Ramp, Dura-Ramp, EZ-ACCESS, Handi-Ramp, Titan Ramps, National Ramp, Gateway Ramp, Ramps & Access, Prairie View Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Ramps Market Strategic Shifts
Portable ramp engineering is converging with connected health infrastructure and sustainable materials science, shifting competitive advantage from pure manufacturing scale toward specification integration and lifecycle service bundling.
Telescoping aluminum track systems with integrated load sensors and Bluetooth connectivity are decentralizing ramp deployment decisions from centralized facilities management to individual caregivers. Home healthcare agencies are piloting these units for real-time usage analytics and predictive maintenance scheduling. The technology is decentralizing inventory control from institutional procurement departments to point-of-care staff.
EU Construction Products Regulation harmonization with EN 131-7 standards for adjustable platform products is tightening surface friction coefficient testing protocols. Manufacturers serving European markets must now submit third-party slip-resistance certification for all tread surfaces. German and French public tender specifications are rejecting uncertified imports, compressing supplier qualification timelines.
Subscription-based ramp provision is displacing outright purchase in United States veteran affairs programs and large home health networks. Equipment-as-a-service contracts bundle installation, maintenance, and end-of-life retrieval into monthly per-patient fees. This model is most visible in California and Texas Medicaid waiver programs where capital budget constraints favor operational expenditure structures.
Portable Ramps Market Segmentation
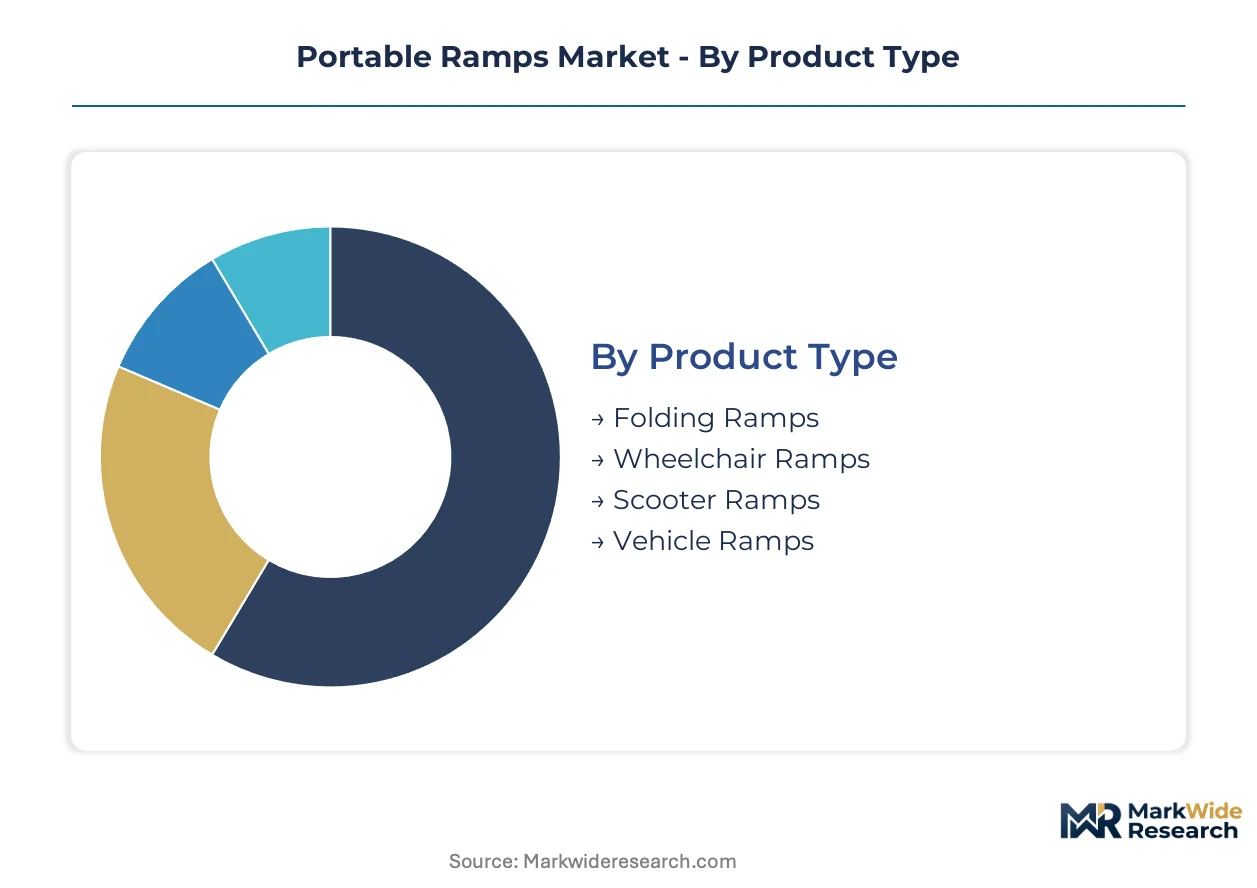
Portable ramp procurement splits sharply between specification-driven institutional contracts and retail consumer purchases. Material selection and load rating requirements vary dramatically across home healthcare, commercial retrofit, and recreational vehicle applications. Understanding these segment boundaries reveals where margin concentrates and where volume flows.
Product Type:
Customization intensity spans from adjustable-length modular platforms to fixed-dimension folding units.
- Folding Ramps:Hinged steel or aluminum panels collapse for vehicle transport and storage. Home healthcare agencies in the United States concentrate procurement here for Medicare-reimbursed aging-in-place installations where temporary deployment dominates.
- Wheelchair Ramps:Slope-compliant surfaces engineered to ADA Standards specifications with integrated edge protection and non-slip tread. Demand concentrates in residential retrofits across Germany and Japan where barrier-free mandates tighten threshold requirements for multi-unit housing.
- Scooter Ramps:Reinforced platforms rated for powered mobility device weights with wider tread surfaces.
- Vehicle Ramps:Lightweight aluminum track systems for cargo area access in commercial and recreational fleets.
Most installed capacity flows through Folding Ramps. Expansion is steepest in Vehicle Ramps.
Material:
Cost tier separation runs from commodity steel through premium aluminum to emerging polymer alternatives.
- Aluminum:Corrosion-resistant alloys deliver strength-to-weight ratios critical for portable deployment. Institutional procurement channels in the United States and Japan specify aluminum exclusively for exterior installations subject to weather exposure and frequent repositioning.
- Steel:Lower raw material costs support mass-market pricing for fixed residential installations with minimal relocation needs. Big-box retail velocity in North American markets concentrates here where purchase decisions prioritize upfront cost over lifecycle durability.
- Plastic:Glass-fiber reinforced composites achieving aluminum-comparable specifications at reduced weight.
- Rubber:Threshold bridging applications requiring conformable surfaces and vibration dampening.
Specification share concentrates in Aluminum. Emerging substitution pressure is climbing the fastest in Plastic.
End User:
Customer type determines procurement channel, with direct-to-consumer diverging sharply from institutional tender processes.
- Individuals:Direct purchasers funding accessibility modifications through personal expenditure or private insurance. German KfW subsidized loan programs are unlocking homeowner-funded installations outside traditional medical equipment distribution.
- Healthcare Facilities:Hospitals, nursing homes, and home health agencies procuring through durable medical equipment contracts. Medicare reimbursement pathways in the United States channel federal funding explicitly toward threshold ramps for home-based care.
- Transportation Services:Fleet operators specifying lightweight cargo access solutions for last-mile delivery and paratransit vehicles.
- Recreational Vehicle Owners:Enthusiast purchasers prioritizing compact storage and rapid deployment for mobility device transport.
Volume leadership sits with Healthcare Facilities. Margin expansion is most pronounced among Individuals.
Application:
Deployment environment dictates surface friction, weatherproofing, and edge protection specifications.
- Home Use:Residential entryways, interior thresholds, and temporary caregiver access points. Japan's METI enforcement of JIS accessibility standards is mandating portable ramp inventory at commercial facilities with residential-adjacent service areas.
- Commercial Use:Retail storefronts, office buildings, and public accommodation entryways subject to ADA Standards or EU Construction Products Regulation compliance. Third-party slip-resistance certification requirements under harmonized EN 131-7 standards are compressing supplier qualification timelines for European tenders.
- Outdoor Activities:Campsite, trailhead, and recreational venue deployments requiring corrosion resistance.
- Event Setup:Temporary infrastructure for conferences, festivals, and sporting venues with rapid installation and removal requirements.
Revenue concentration favors Commercial Use. Subscription-based equipment-as-a-service models are gaining share fastest in Home Use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Accessibility technicians and occupational therapists concentrate in metropolitan corridors across the United States, Germany, Japan, and Australia, anchoring regional deployment capacity for portable ramp installations. These workforce clusters align with aging demographics and tightening building codes that mandate barrier-free access in residential and commercial structures.
United States
Medicare reimbursement pathways and veteran affairs programs channel federal funding toward durable medical equipment procurement. The ADA Standards for Accessible Design enforce slope ratios and surface friction requirements for public accommodations. Home healthcare agencies in California and Texas pilot subscription-based equipment-as-a-service models that bundle installation with predictive maintenance.
Germany
KfW banking group subsidized loans unlock homeowner-funded accessibility modifications outside traditional medical distribution channels. The EU Construction Products Regulation harmonization with EN 131-7 standards tightens slip-resistance certification protocols for all tread surfaces. Fabricators in Baden-Württemberg and North Rhine-Westphalia concentrate production of modular aluminum systems for institutional tender processes.
Japan
METI enforcement of JIS accessibility standards mandates portable ramp inventory at commercial facilities and transportation infrastructure nationwide. Barrier-free mandates for multi-unit housing tighten threshold requirements in Tokyo and Osaka metropolitan zones. Manufacturers in the Chubu region around Nagoya specialize in lightweight track systems for frequent repositioning.
Australia
NDIS disability funding schemes expand individual purchasing power for home modification equipment. State-level building codes in New South Wales and Victoria adopt stricter accessibility compliance timelines for residential retrofits. Occupational therapy assessment hubs in Sydney and Melbourne coordinate telehealth-integrated ramp specification services.
United Kingdom
Local authority Disabled Facilities Grants fund threshold ramp installations for aging-in-place initiatives across England and Scotland. Building regulations Part M compliance inspections intensify for commercial entryways in London and the Southeast. Durable medical equipment distributors in the Midlands maintain inventory proximity to NHS procurement channels.
Portable Ramps Market Competitive Environment
Top-tier vendors anchor specification-driven institutional contracts, while mid-tier fabricators compete for retail velocity through standardized folding products. The market structure compresses suppliers unable to achieve scale in either channel, forcing portfolio specialization or exit. Three archetypes dominate: premium modular system specialists, mass-market steel folding producers, and emerging polymer composite entrants. Competitive moves concentrate on geographic expansion through distributor partnerships and backward integration into aluminum alloy sourcing.
Among North American accessibility equipment specialists, EZ-ACCESS and Prairie View Industries occupy positions at opposite ends of the product tier spectrum. EZ-ACCESS exemplifies the premium modular archetype through patented adjustable-length platforms, while Prairie View Industries anchors mass-market distribution through standardized folding ramps stocked in medical supply and retail channels. National Ramp represents the mid-tier consolidation pressure facing suppliers caught between specification-driven procurement and price-sensitive consumer purchases.
| Leading Market Players |
|---|
| Roll-a-Ramp |
| Dura-Ramp |
| EZ-ACCESS |
| Handi-Ramp |
| Titan Ramps |
| National Ramp |
| Gateway Ramp |
| Ramps & Access |
| Prairie View Industries |
| Others |
Value Chain & Pricing Dynamics
Glass-fiber composite manufacturing maturation simultaneously compresses raw material volatility for new entrants and fragments aluminum's historical dominance, reshaping cost economics while dispersing supply concentration across material tiers. This dual transition forces incumbent fabricators to defend premium positioning through bundled service architectures as commodity-grade alternatives erode transactional pricing power.
Pricing Analysis
Bundled equipment-as-a-service contracts diverge sharply from per-unit transactional sales, with subscription models capturing institutional accounts while retail channels remain anchored in outright purchase. Pricing stratifies across premium modular systems, standardized folding ramps, and emerging polymer alternatives, with certification grade and after-sales service bundling as the primary differentiation levers. Cost compression in steel folding tiers intensifies due to big-box retail price competition, while healthcare facilities demonstrate lowest price sensitivity given Medicare reimbursement pathways.
Supply Chain Analysis
Dual-sourcing requirements from institutional buyers mandate multi-supplier qualification for aluminum alloys and reinforced polymers, preventing single-fabricator dependence. Supply concentrates in the United States, Germany, and Japan, with raw material flows drawing from LME-traded aluminum, glass-fiber composite feedstocks, and corrosion-resistant steel alloys. Single-source vulnerability persists in specialized extrusion tooling for adjustable-length platforms. Distribution runs through durable medical equipment distributors, direct-to-consumer e-commerce, and big-box retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as home healthcare agencies and veteran affairs programs shift procurement toward premium aluminum modular systems with integrated connectivity and predictive maintenance capabilities.
For Market Incumbents: Lock in specification-driven contracts through exclusive distributor partnerships with Medicare-reimbursed home health networks. Prioritize backward integration into aluminum alloy sourcing to offset LME volatility exposure. Defend against reinforced polymer substitution by accelerating load-sensor and Bluetooth-enabled platform rollout.
For New Entrants and Emerging Players: Enter via German residential retrofit channels outside traditional medical equipment distribution, where KfW subsidized loans unlock homeowner-funded installations with less incumbent saturation. Target vehicle fleet electrification applications for commercial van operators requiring lightweight cargo access solutions. Pursue telehealth-integrated assessment partnerships to bypass established durable medical equipment distributor gatekeepers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier fabricators caught between premium modular specialization and mass-market retail scale, presenting consolidation targets. Long-term viability hinges on specification integration and lifecycle service bundling rather than pure manufacturing capacity. Watch for inflection in municipal ADA enforcement variance resolution, which would compress approval timelines and accelerate national distribution program rollout.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Sourcing | Captive supply of corrosion-resistant alloys insulates margins from LME futures volatility. |
| Bluetooth-Enabled Platform Launch | Real-time usage analytics differentiate premium offerings for home healthcare agency procurement. |
| Reimbursement Strategy Expansion | CMS durable medical equipment classification alignment channels federal funding toward threshold ramp adoption. |
| CE Marking Pathway Investment | Third-party slip-resistance certification under EN 131-7 unlocks German and French public tender participation. |
| Joint Venture with Telehealth Platforms | Remote occupational therapy assessment integration enables direct-to-patient specification bypassing distributors. |
Study Parameters
Multiple input streams — primary interviews with durable medical equipment procurement managers, home health agency operations directors, and accessibility equipment installers; secondary validation through CMS reimbursement databases, ADA Standards documentation, and EU Construction Products Regulation filings; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation.
Historical shipment data cross-referenced against panel input from industry participants anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material specification, end-user category, and application environment, with CAGRs derived from slope analysis of reimbursement expansion trajectories and regulatory mandate enforcement timelines.
Inputs from Medicare claims data and municipal building permit records were available through the study window; gaps in real-time aluminum alloy pricing transparency introduce uncertainty bands around fabricator margin projections. Deviation in METI enforcement intensity for JIS accessibility standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Street Furniture Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Horizontal Directional Drilling Market
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Private Bunker Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Industrial Access Platform Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
US and Europe Cleanrooms Market