
 US and Europe Cleanrooms Market | 2026-2036
US and Europe Cleanrooms Market Size, Share, and Industry Trends Forecast 2026-2036
US and Europe Cleanrooms Market Insights
The EU Green Deal is hardening cleanroom energy-efficiency mandates across European pharmaceutical and electronics manufacturing. Exyte AG leverages its integrated design-build capabilities to capture large-scale semiconductor facility contracts in Germany. Terra Universal, Inc. sustains a broad catalog of standardized modular systems that serve mid-tier research and biotech clients. Bouygues Group anchors its position through construction-led project delivery across French and Belgian life sciences infrastructure.
US and Europe cleanrooms are controlled environments that maintain specified airborne particulate concentrations through HEPA or ULPA filtration, typically achieving ISO 14644-1 Class 1 to Class 9 cleanliness levels for sensitive manufacturing and research operations. Their primary purpose is to prevent contamination in processes where microscopic particles compromise product yield, patient safety, or experimental validity. Modular cleanrooms lead product type demand due to faster deployment timelines and lower capital commitment for expanding facilities. Pharmaceutical end users command the largest share of value as batch integrity requirements and FDA validation protocols drive specification intensity. Prefabricated installation is accelerating fastest as site labor costs rise and just-in-time delivery models penetrate facility construction.
US FDA cGMP guidelines and EU GMP Annex 1 revisions shape contamination control standards, while EPA and REACH frameworks govern chemical emissions from cleanroom materials and consumables. The F-Gas Regulation directly impacts HVAC system selection, pushing European facilities toward alternative refrigerant architectures. Stakeholders must monitor evolving energy benchmarking requirements and assess how modular system flexibility aligns with uncertain production scale trajectories in cell and gene therapy manufacturing.
Market Dynamics
Semiconductor fabrication expansion in Germany and the Netherlands is compressing cleanroom deployment timelines while EU F-Gas Regulation mandates force HVAC system redesign across pharmaceutical and electronics facilities.
Growth Catalysts
- Advanced node semiconductor production:German and Dutch fabrication facilities require ISO Class 1-3 environments for sub-3nm chip manufacturing, expanding cleanroom footprints substantially.
- EU Green Deal energy mandates:Pharmaceutical manufacturers face binding efficiency benchmarks that accelerate replacement of legacy HVAC infrastructure with low-GWP refrigerant systems.
- Cell and gene therapy manufacturing scale-up:Massachusetts and North Carolina biotech clusters demand flexible modular cleanrooms to accommodate uncertain batch volumes and rapid process changes.
Market Restraints
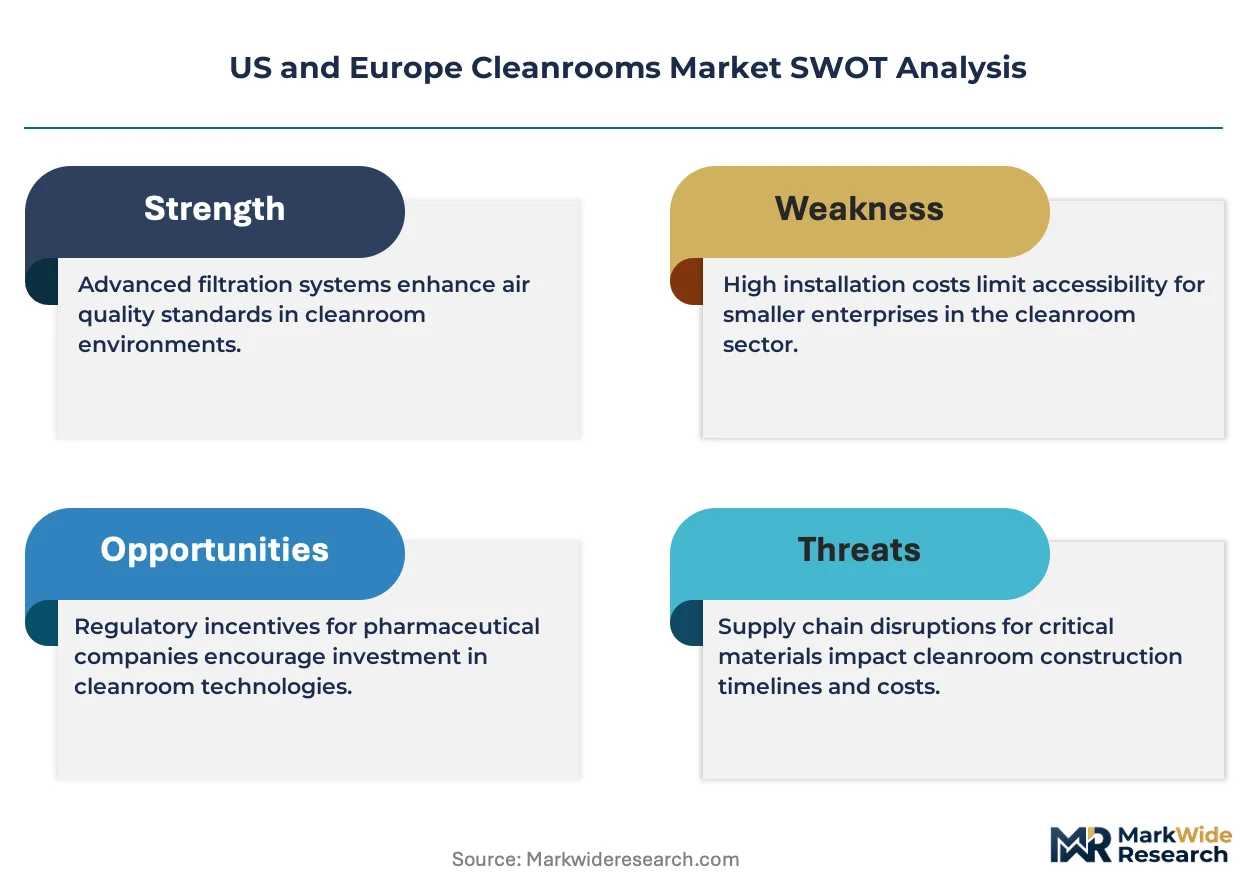
- Specialized filtration media supply concentration:HEPA and ULPA filter manufacturing concentrates among limited European and Asian suppliers, creating input cost volatility and extended lead times.
- F-Gas Regulation compliance friction:European facilities face stranded asset risk from banned refrigerants, forcing premature HVAC replacement before end-of-life.
- Site labor cost inflation:Skilled cleanroom installation technicians command premium wages in the US pharmaceutical corridor, eroding prefabrication cost advantages.
Strategic Opportunities
- Underpenetrated Belgian life sciences infrastructure:Antwerp and Ghent biotech parks lack ISO Class 5-7 capacity for emerging mRNA manufacturing, creating greenfield development potential.
- Convergence of IoT sensors and predictive HVAC maintenance:Real-time particulate and pressure monitoring integrated with machine learning reduces unplanned downtime in continuous bioprocessing.
- US Inflation Reduction Act domestic manufacturing incentives:Cleanroom investments for pharmaceutical and semiconductor reshoring qualify for accelerated depreciation and production tax credits.
Industry Challenges
- Contamination control engineer scarcity:ISO 14644-1 validation expertise and FDA cGMP compliance knowledge concentrate among aging specialists in New Jersey and Basel, constraining facility commissioning.
- Legacy facility HVAC integration complexity:Retrofitting 1990s-era pharmaceutical plants with modern low-GWP systems requires structural reinforcement and extended shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Europe Cleanrooms Market |
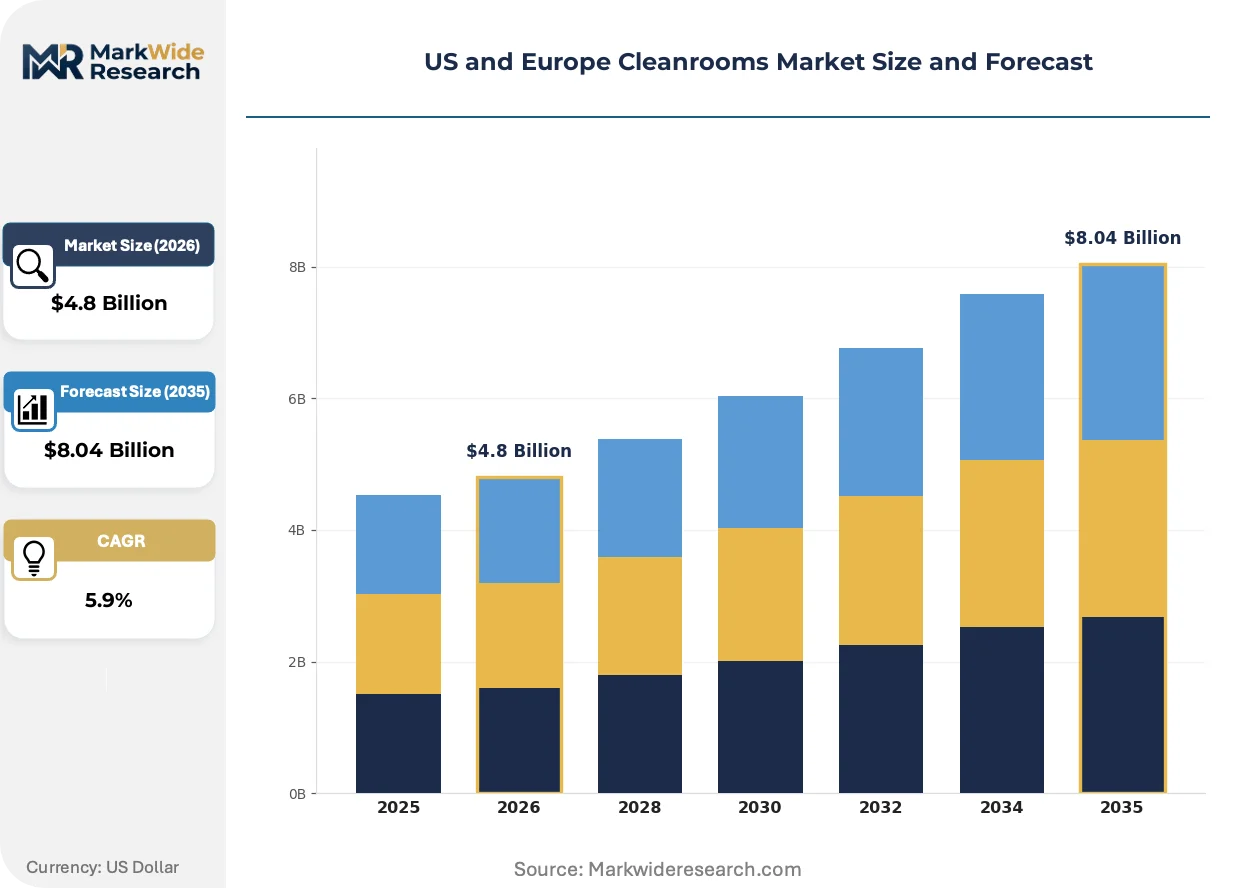
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.04 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Cleanrooms, Hardwall Cleanrooms, Softwall Cleanrooms, Passive Cleanrooms End User: Pharmaceutical, Biotechnology, Healthcare, Electronics Application: Research, Manufacturing, Quality Control, Clinical Trials Installation Type: On-site, Prefabricated, Retrofit, Temporary |
| Companies Covered | Angstrom Technology, Terra Universal, Inc., Clean Air Products, MECART, ISOLTECH Srl, Exyte AG, Bouygues Group, Ardmac Group Ltd, ABN Cleanroom Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Europe Cleanrooms Market Trends and Innovations
Cleanroom architecture is pivoting from permanent construction toward adaptive systems that accommodate volatile production scales and accelerating regulatory cycles in semiconductor and biologics manufacturing.
Prefabricated modular cleanroom systems with plug-and-play HVAC integration are overtaking conventional stick-built construction in mid-tier pharmaceutical and research applications. Biotech startups in the Research Triangle Park and Cambridge clusters specify rapid-deployment ISO Class 7-8 environments to preserve capital for equipment rather than fixed infrastructure. This technology compression is collapsing traditional 18-month facility timelines to 8-12 weeks, forcing general contractors to develop modular partnerships or exit the segment.
REACH chemical compliance and EU F-Gas Regulation amendments are hardening material specifications for cleanroom surfaces, sealants, and refrigerants. European pharmaceutical manufacturers must document substance of very high concern (SVHC) absence in wall panels and flooring while transitioning HVAC systems to hydrofluoroolefin alternatives. German semiconductor fabs face the strictest enforcement timelines, driving specification changes that propagate through supplier tiers.
Life sciences procurement teams are unbundling cleanroom construction from long-term facility service contracts, separating capital equipment vendors from operational maintenance providers. Large pharmaceutical manufacturers in North Carolina and New Jersey now bid cleanroom shells independently from environmental monitoring and certification services, compressing vendor margins. This disintermediation is most advanced among CDMOs serving cell therapy clients, where facility flexibility outweighs single-source accountability.
US and Europe Cleanrooms Market Segmentation
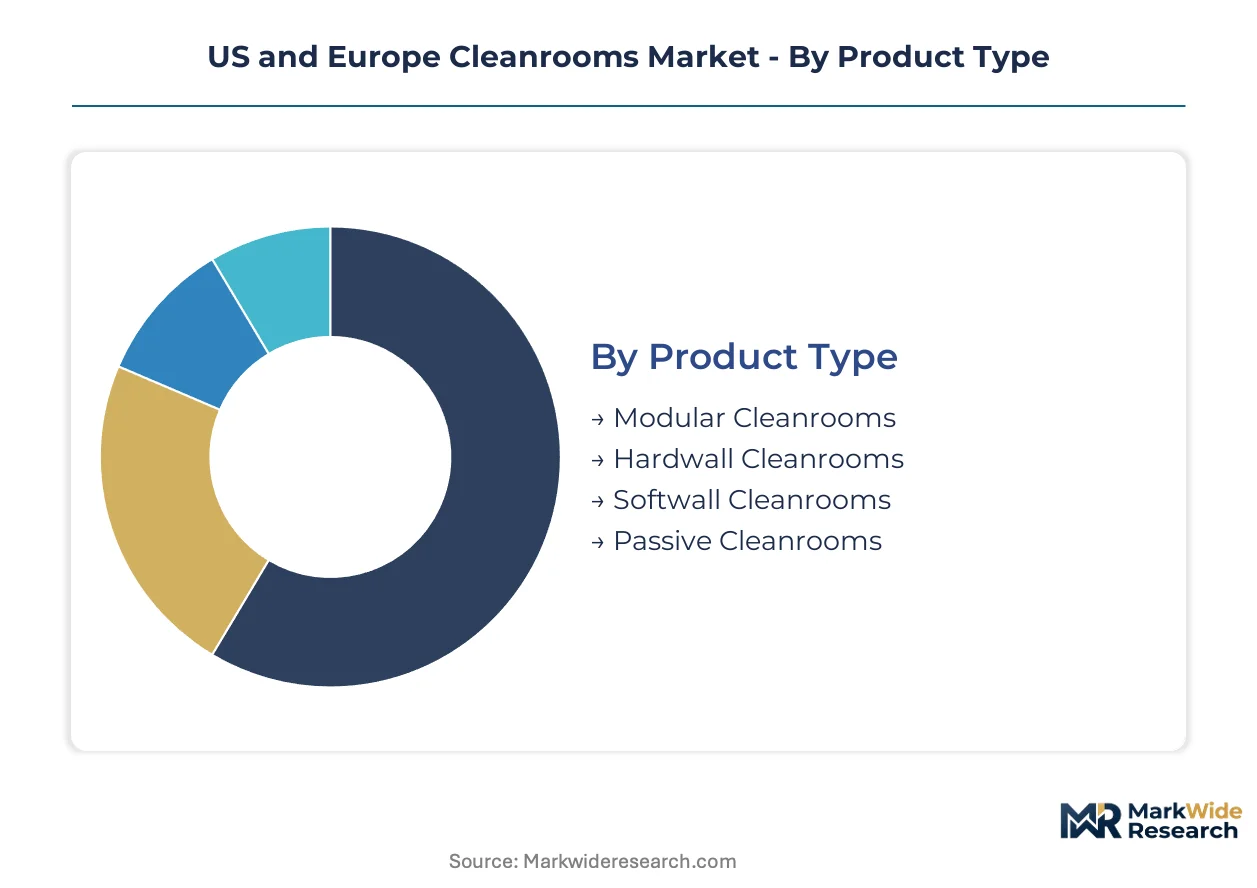
Cleanroom procurement patterns diverge sharply between standardized modular systems for rapid deployment and engineered hardwall solutions for permanent semiconductor facilities. Understanding these segmentation fractures reveals where specification intensity concentrates and where cost compression dominates.
Product Type:
Standardization depth varies from fully configurable hardwall architectures to rapidly deployable softwall enclosures, creating distinct procurement channels and margin structures across the customization spectrum.
- Modular Cleanrooms:Prefabricated wall and ceiling panels with integrated HVAC connections enable rapid reconfiguration for volatile batch volumes in Massachusetts and North Carolina cell therapy facilities. Demand concentrates among CDMOs requiring ISO Class 7-8 flexibility to accommodate shifting client pipelines without structural demolition.
- Hardwall Cleanrooms:Permanent gypsum or metal-stud construction with sealed surfaces delivers ISO Class 1-3 stability for sub-3nm semiconductor fabrication in German and Dutch fabs. Dutch ASML supplier parks and Dresden megafabs specify these for multi-decade operational lifespans despite 18-24 month construction timelines.
- Softwall Cleanrooms:Flexible PVC curtain enclosures with aluminum framing provide economical ISO Class 8-9 containment for secondary packaging and material staging in New Jersey pharmaceutical corridors.
- Passive Cleanrooms:Unpowered enclosures relying on adjacent pressurized spaces suit low-risk sampling and documentation tasks in Belgian hospital pharmacies.
Leading the category by volume: Modular Cleanrooms. Growing fastest: Hardwall Cleanrooms.
End User:
Regulatory burden intensity separates these verticals, with FDA cGMP and EU GMP Annex 1 compliance costs creating tiered specification thresholds that reshape vendor selection criteria.
- Pharmaceutical:Sterile injectable and oral solid dosage manufacturing drives ISO Class 5-7 demand across New Jersey, Massachusetts, and North Carolina corridors. FDA validation protocols and EU GMP Annex 1 particle monitoring requirements force redundant filtration and continuous environmental monitoring systems.
- Biotechnology:Cell and gene therapy manufacturing in Cambridge and Research Triangle Park clusters demands adaptive cleanroom architectures for autologous therapies with patient-specific batch scales. Massachusetts biotech startups prioritize modular systems to preserve capital for GMP equipment rather than fixed infrastructure.
- Healthcare:Hospital compounding pharmacies and surgical suites in French and Belgian systems require ISO Class 7-8 environments for aseptic preparation under national health authority oversight.
- Electronics:German and Dutch semiconductor fabs anchor demand for ultra-low particulate environments, with Dresden and Eindhoven facilities expanding footprints for advanced node production.
Pharmaceutical end users command the largest revenue share. Biotechnology applications are expanding most quickly.
Application:
Process criticality determines environmental stringency, with direct product contact operations demanding tighter control than supporting functions.
- Research:Academic and corporate R&D facilities in Cambridge and Basel specify modular ISO Class 7-8 environments for discovery-stage work where contamination tolerance exceeds GMP thresholds.
- Manufacturing:Commercial-scale biologics and semiconductor production in North Carolina and the Netherlands requires validated ISO Class 5-7 environments with continuous particulate monitoring and alarm systems.
- Quality Control:Analytical laboratories in New Jersey pharmaceutical clusters need stable ISO Class 7-8 conditions for sterility testing and endotoxin analysis under FDA oversight.
- Clinical Trials:Phase I-III manufacturing in Belgian and German CMOs demands flexible cleanroom configurations for investigational drug batches with evolving specifications.
Manufacturing applications dominate value capture. Clinical trials deployment is climbing the fastest.
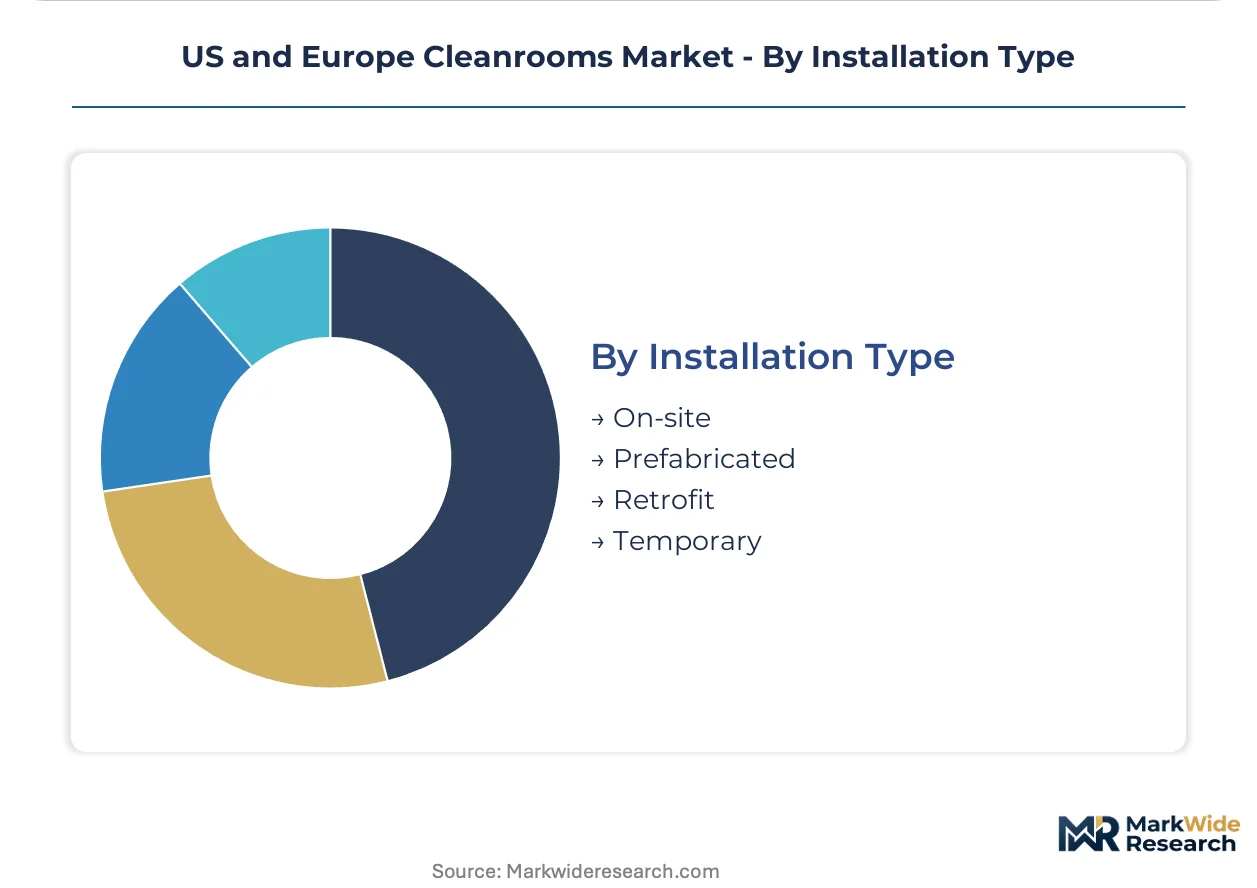
Installation Type:
Site labor economics and schedule pressure create divergent approaches, with prefabrication gaining ground as skilled technician availability tightens in key pharmaceutical corridors.
- On-site:Conventional stick-built construction persists for large semiconductor fabs in Germany where structural integration with existing facility infrastructure demands custom engineering.
- Prefabricated:Factory-built modules shipped for rapid assembly compress deployment timelines from 18 months to 8-12 weeks for Research Triangle Park biotech startups facing investor milestone pressure.
- Retrofit:HVAC and envelope upgrades in 1990s-era New Jersey pharmaceutical plants address EU F-Gas Regulation compliance and energy benchmarking mandates.
- Temporary:Rental modular units support seasonal vaccine campaigns and emergency manufacturing surges in French hospital networks.
Prefabricated installation leads volume growth. Retrofit activity shows the steepest expansion trajectory as legacy facilities face regulatory deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park in North Carolina anchors cleanroom demand across the US pharmaceutical corridor, with Massachusetts and New Jersey clusters competing for cell therapy manufacturing capacity. European expansion concentrates in German semiconductor fabrication zones and Belgian life sciences infrastructure.
United States
Massachusetts biotech startups and North Carolina CDMOs drive modular cleanroom procurement for autologous cell therapy production. The Inflation Reduction Act provides accelerated depreciation for domestic pharmaceutical manufacturing reshoring. New Jersey's sterile injectable corridor faces HVAC retrofit pressure from EPA energy benchmarking mandates.
Germany
Dresden and Munich semiconductor fabs require ISO Class 1-3 hardwall environments for sub-3nm chip fabrication timelines. The F-Gas Regulation forces premature HVAC replacement with hydrofluoroolefin alternatives. Bavarian pharmaceutical plants integrate REACH-compliant wall panels to document SVHC absence.
Netherlands
ASML supplier parks and Eindhoven fabrication facilities expand cleanroom footprints for advanced lithography component manufacturing. EU Green Deal energy-efficiency benchmarks compress HVAC system selection windows. Dutch facilities lead European adoption of predictive maintenance IoT for continuous bioprocessing.
Belgium
Antwerp and Ghent biotech parks lack ISO Class 5-7 capacity for emerging mRNA manufacturing platforms. EMA oversight of sterile drug production drives validation protocol intensity. Walloon region hospital pharmacies deploy passive cleanrooms for aseptic compounding under federal health authority regulation.
France
Paris-Saclay research clusters and Lyon pharmaceutical manufacturing anchor modular cleanroom demand for clinical trial material production. ANSM national health authority oversight shapes aseptic processing standards. French hospital networks rent temporary modular units for seasonal vaccine campaign surges.
US and Europe Cleanrooms Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the customization spectrum, with design-build integrators commanding superior returns to standardized component vendors. The vendor base separates into three strategic archetypes: integrated facility contractors, modular system fabricators, and specialized filtration engineers. Consolidation pressure concentrates among mid-tier modular suppliers facing disintermediation from unbundled procurement. Capacity expansion and strategic partnerships dominate competitive moves as general contractors develop modular partnerships or exit the segment.
Within the integrated design-build tier, Exyte AG and Bouygues Group exemplify construction-led project delivery archetypes across European semiconductor and life sciences infrastructure. Terra Universal, Inc. occupies a position among standardized modular system providers serving mid-tier research and biotech clients with rapid-deployment catalogs. These three anchors represent distinct margin tiers: facility-scale integration at premium returns, standardized modularity at volume-driven margins, and component specialization at cyclical pricing.
| Leading Market Players |
|---|
| Angstrom Technology |
| Terra Universal, Inc. |
| Clean Air Products |
| MECART |
| ISOLTECH Srl |
| Exyte AG |
| Bouygues Group |
| Ardmac Group Ltd |
| ABN Cleanroom Technology |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ISO Class 1-3 semiconductor fabs and ISO Class 7-8 biotech modular systems manifests in both pricing power and supply chain configurations across US and European cleanrooms. Premium hardwall installations for German sub-3nm chip production command value-based contracts tied to yield guarantees, while standardized modular units for North Carolina cell therapy facilities compete on capital efficiency and deployment speed.
Pricing Analysis
Yield-guarantee pricing anchors premium hardwall contracts for Dutch and German semiconductor fabrication, where uptime penalties and particulate failure clauses tie vendor compensation to operational outcomes. Three-tier pricing structure across premium, standard, and economy levels separates validated GMP environments from research-grade modular systems and temporary softwall enclosures. Cost compression in mid-tier biotech modular systems intensifies as prefabrication commoditizes and CDMO procurement teams unbundle construction from service contracts. Pharmaceutical manufacturers in New Jersey's sterile injectable corridor show least price sensitivity due to FDA validation requirements, while academic research facilities in Cambridge prioritize capital preservation.
Supply Chain Analysis
Skilled cleanroom installation technician shortages in the US pharmaceutical corridor and German semiconductor zones constrain throughput and inflate project labor costs. HEPA and ULPA filter manufacturing concentrates in Germany, Japan, and select Asian suppliers, creating input dependencies for European and North American facility builders. Supply chain risk centers on single-source vulnerability for specialized filtration media with extended qualification timelines. Distribution runs through design-build integrators for large semiconductor projects and direct-to-site modular fabricators for biotech rapid-deployment needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US and Europe Cleanrooms Market operates as a cost-of-compliance story where EU F-Gas Regulation and FDA cGMP validation create substantial barrier-to-entry moats for players with established certification expertise and documented regulatory track records.
For Market Incumbents: Acquire specialized filtration engineering capabilities to secure input supply and capture margin from captive HEPA/ULPA production. Incumbent design-build integrators like Exyte AG should expand modular partnerships or develop in-house prefabrication capacity to defend against general contractor exit from the segment and disintermediation from unbundled procurement. For New Entrants and Emerging Players: Enter via underpenetrated Belgian life sciences infrastructure in Antwerp and Ghent biotech parks, where ISO Class 5-7 capacity gaps for mRNA manufacturing create greenfield development potential. New entrants should target rapid-deployment modular systems for Massachusetts cell therapy startups, leveraging plug-and-play HVAC integration to compress sales cycles against entrenched construction-led competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by facility-scale integrators seeking to fill modular capability gaps or filtration supply security. Long-term viability favors vendors with demonstrated EU F-Gas Regulation compliance and FDA validation project histories. The signal to watch is acceleration of US Inflation Reduction Act domestic manufacturing incentive utilization for pharmaceutical and semiconductor reshoring cleanroom investments.| Strategic Initiative | Industry Significance |
|---|---|
| Modular System Fabrication Partnership | Enables general contractors to retain semiconductor and biotech project access as prefabrication displaces stick-built construction. |
| F-Gas Compliant HVAC Transition | European pharmaceutical and electronics facilities face stranded asset risk without hydrofluoroole refrigerant system upgrades. |
| Predictive Maintenance IoT Integration | Dutch facilities lead adoption of real-time particulate monitoring with machine learning for continuous bioprocessing uptime. |
| REACH-Compliant Material Certification | German semiconductor fabs require documented SVHC absence in wall panels and flooring under ECHA oversight. |
| Cell Therapy Flexible Facility Design | Massachusetts and North Carolina CDMOs demand adaptive architectures for autologous therapy batch scale uncertainty. |
Research Methodology
Document review covered SEC filings of publicly traded facility contractors, EU regulatory filings under F-Gas Regulation and REACH, and industry association publications from semiconductor and pharmaceutical manufacturing consortia, complemented by interviews with cleanroom design engineers, pharmaceutical facility directors, semiconductor fab construction managers, and HVAC system procurement leads. Secondary validation drew from EPA energy benchmarking databases, EMA GMP inspection records, and customs data on filtration media trade flows. Bottom-up project pipeline analysis and top-down market sizing triangulated volume estimates.
Cross-referencing historical deployment patterns against expert panel input on regulatory timeline acceleration shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type architecture, end-user regulatory burden intensity, application process criticality, and installation type labor economics. CAGRs derived from weighted scenario analysis incorporating facility expansion announcements and policy incentive utilization rates. Industry-specific forecast inputs included semiconductor node transition timelines and cell therapy manufacturing capacity buildout trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement or supply disruption in specialized filtration media. Forecasts reflect assumptions on regulatory implementation schedules and capital commitment timelines from major pharmaceutical and semiconductor manufacturers. Material deviation in F-Gas Regulation compliance deadlines or US domestic manufacturing incentive program expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Industrial Access Platform Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
Private Bunker Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Portable Ramps Market
Specialized Building Services
Street Furniture Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
Horizontal Directional Drilling Market