
 Construction Drone Market | 2026-2036
Construction Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Drone Market Intelligence
Aftermarket service revenue is rewriting how construction drone vendors capture lifetime value from hardware deployments. DJI leverages its sprawling service network to lock in recurring calibration and firmware support contracts across job sites. Skydio anchors its position through autonomous flight software that reduces pilot dependency on complex structural inspections. JOUAV dominates the fixed-wing segment with extended-flight platforms purpose-built for linear infrastructure corridors.
Construction drones are unmanned aerial systems typically carrying photogrammetry sensors, LiDAR modules, or multispectral cameras to capture geospatial data with centimeter-grade accuracy for earthworks quantification and progress tracking. Multi-rotor configurations lead deployment frequency due to vertical takeoff flexibility and hovering precision above active work zones, while photogrammetry technology commands the largest installed base despite LiDAR's faster penetration in vegetation-heavy terrain. GPS-denied navigation capabilities are emerging as a critical performance differentiator where urban canyons or indoor construction phases limit satellite reception.
FAA Part 107 mandates in the United States, EASA open-category frameworks in Europe, and CAAC operational certification in China collectively shape product design standards, flight altitude ceilings, and beyond-visual-line-of-sight waiver pathways. These regulatory architectures force manufacturers to embed geofencing, remote identification broadcast modules, and fail-safe return protocols as baseline features rather than premium add-ons. Stakeholders must monitor evolving airspace integration rules and operator training reciprocity agreements to anticipate which compliance investments will transfer across jurisdictions.
Market Dynamics
Autonomous flight algorithms are compressing operator training timelines while expanding drone deployability into GPS-denied environments, fundamentally altering workforce economics and site coverage models for infrastructure developers.
Growth Catalysts
- FAA Part 107 waiver expansion:Beyond-visual-line-of-sight approvals for linear infrastructure corridors accelerate survey cycle times and reduce mobilization costs for transmission line and pipeline operators.
- Photogrammetry-to-LiDAR sensor convergence:Integrated payload systems cut equipment swap downtime on megaproject sites where vegetation penetration and bare-earth accuracy requirements vary by work phase.
- Germany's federal transport infrastructure pipeline:Deutsche Bahn and Autobahn GmbH project backlogs concentrate demand for centimeter-grade topographic validation across tunnel, bridge, and track renewal programs.
Market Restraints
- Lithium-polymer battery supply concentration:Cell production clusters in China create input cost volatility and logistics exposure for hardware OEMs assembling in North America and Europe.
- EASA open-category operational ceiling restrictions:120-meter altitude limits force additional flight legs on large-site surveys, inflating labor costs and airspace coordination complexity.
- Total station and terrestrial laser scanner substitution:Established survey contractors retain capital-heavy ground-based equipment with proven legal defensibility for boundary and as-built documentation.
Strategic Opportunities
- Australia's mining rehabilitation mandates:State-level environmental compliance frameworks in Queensland and Western Australia create recurring vegetation monitoring contracts requiring multispectral drone deployment.
- 5G network slicing for real-time kinematic correction:Telecommunications infrastructure convergence enables centimeter-grade positioning without dedicated base stations, lowering entry barriers for mid-tier contractors.
- Building information modeling integration APIs:Direct data pipeline connectivity to Autodesk and Bentley platforms positions drone service providers as embedded workflow partners rather than peripheral vendors.
Industry Challenges
- Part 107 remote pilot certification bottlenecks:FAA testing center capacity constraints and recurrent training requirements throttle fleet scaling for regional drone service operators.
- Legacy survey software interoperability gaps:Proprietary point cloud formats from DJI, Skydio, and JOUAV platforms force manual translation workflows that erode productivity gains from automated capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Drone Market |
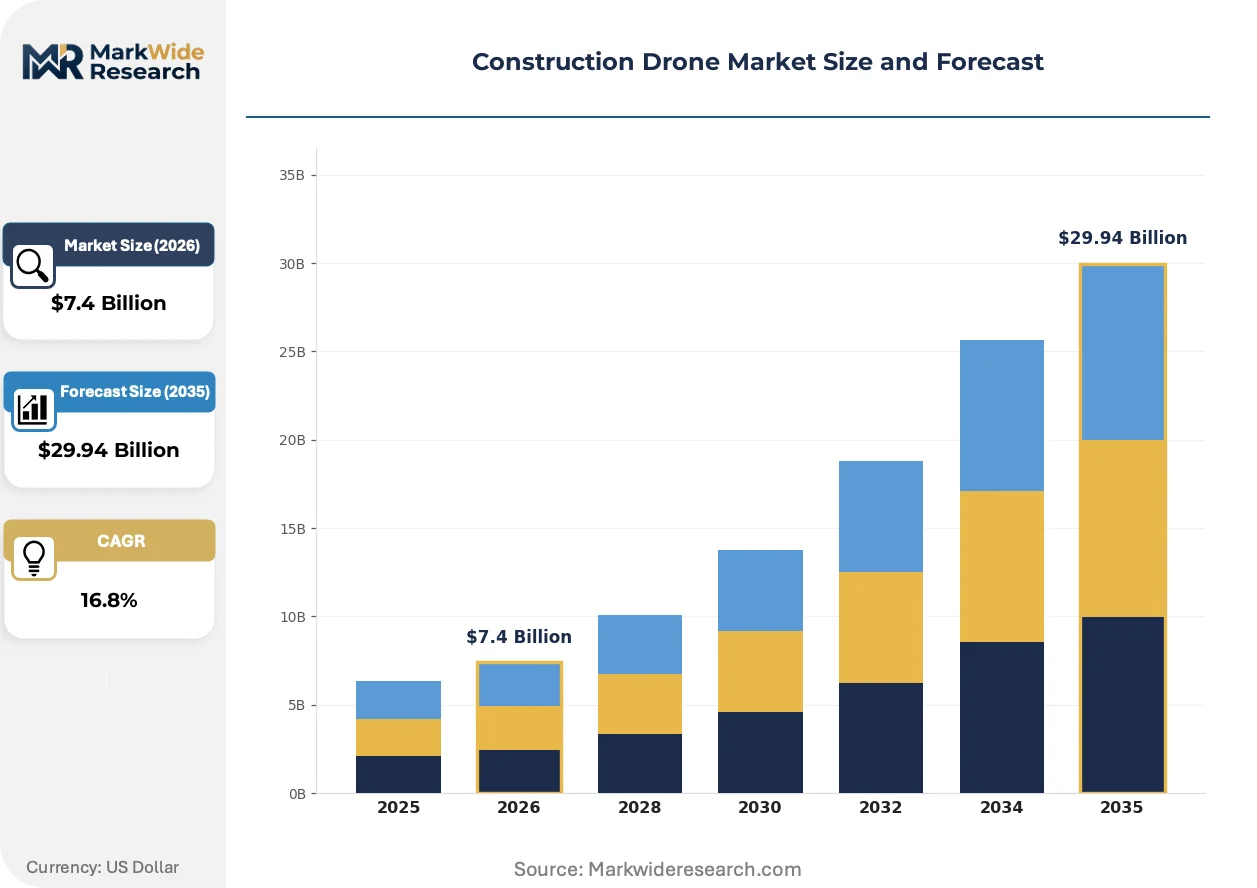
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $29.94 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Wing, Multi-Rotor, Single Rotor, Hybrid Technology: Photogrammetry, LiDAR, GPS, Visual Imaging Application: Site Surveying, Inspection, Monitoring, Mapping End User: Construction Companies, Architects, Surveyors, Engineers |
| Companies Covered | Delair, Ascent AeroSystems, DJI, Autel Robotics, AeroVironment, Skydio, JOUAV, Draganfly, Parrot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Drone Market Strategic Shifts & Innovations
Flight control architectures are pivoting from pilot-centric operation to supervised autonomy, compressing labor intensity while expanding mission profiles into structurally complex and electromagnetically noisy environments.
Visual-inertial odometry is migrating from research prototype to production-grade navigation stack for indoor construction phase documentation. General contractors deploying drones for at-risk concrete pour monitoring now specify SLAM-enabled platforms that operate without GNSS lock. This capability is compressing the addressable market gap between aerial and terrestrial capture methods.
EASA's specific category operational authorization framework is mandating structured risk assessments and conformity documentation for urban drone operations. Hardware manufacturers must embed remote identification broadcast modules and geofencing databases as baseline firmware. European infrastructure developers are responding by consolidating vendor selection around OEMs with pre-certified technical file packages.
Equipment procurement is fragmenting between capital purchase and flight-hour subscription models. Large engineering firms with irregular survey demand are piloting drone-as-a-service contracts with guaranteed data delivery SLAs. This shift is most pronounced in Germany, where midsize construction groups lack internal UAV maintenance capabilities and prefer operational expenditure treatment for compliance-sensitive capture tasks.
Construction Drone Market Segmentation
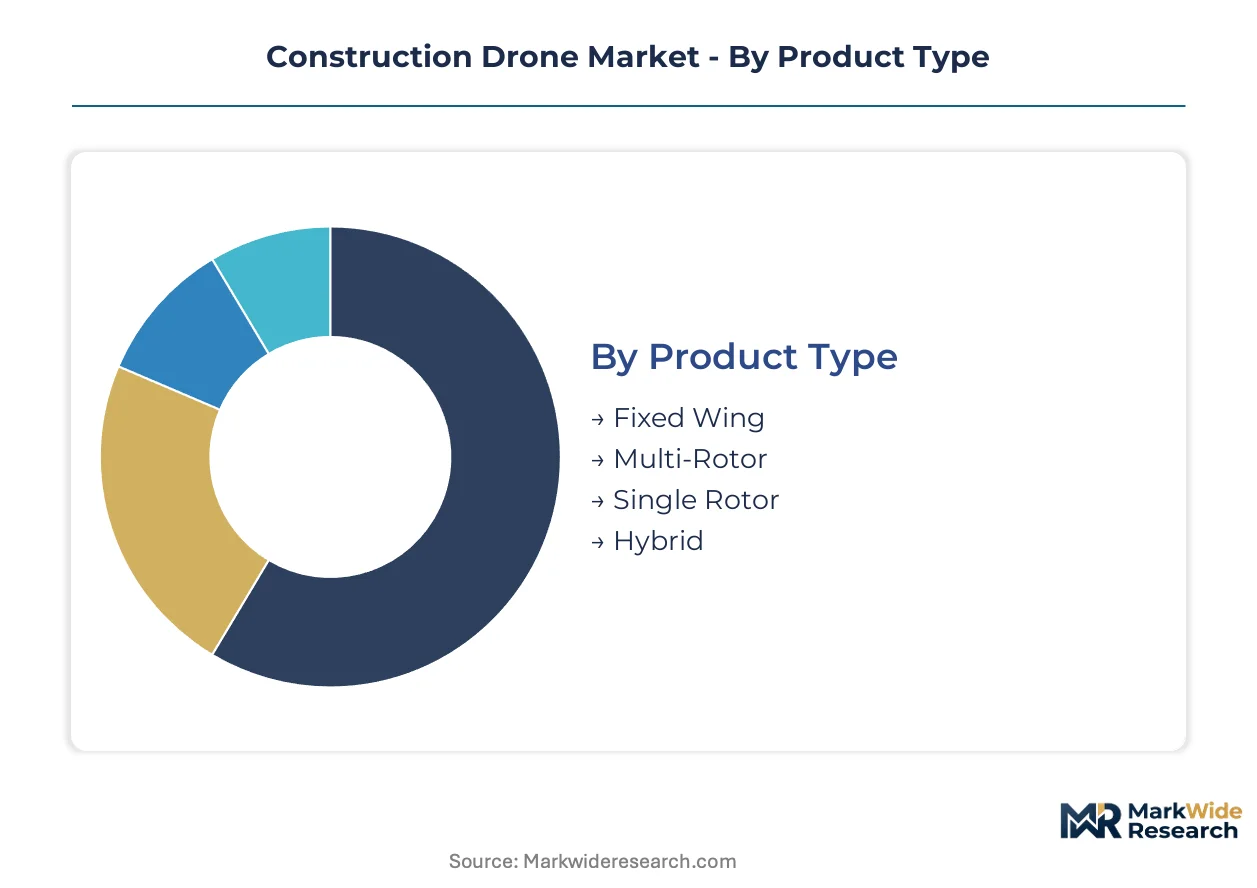
Drone segmentation in construction reveals stark trade-offs between flight endurance, sensor precision, and regulatory compliance. Procurement teams weigh capital intensity against mission versatility when matching platform configurations to project phase requirements.
Product Type:
Fixed-wing platforms turn over slowest due to capital intensity and specialized pilot certification, while multi-rotor fleets refresh fastest on job sites demanding rapid payload reconfiguration.
- Fixed Wing:Extended-flight airframes with aerodynamic lift surfaces achieve 90-minute endurance for linear corridor surveys. Deutsche Bahn's track renewal programs in Germany concentrate demand where BVLOS waivers reduce mobilization cycles across hundreds of kilometers.
- Multi-Rotor:Vertical takeoff platforms with four to eight rotors dominate active work zones through hovering precision. China's megaproject density drives replacement frequency as contractors scale from DJI Phantom to Matrice series for heavier LiDAR payloads.
- Single Rotor:Helicopter-style configurations with main-and-tail rotor assemblies offer payload capacity approaching fixed-wing efficiency with VTOL flexibility. Pipeline operators in Australia's Queensland deploy these for vegetation-heavy terrain where landing zones are constrained.
- Hybrid:Tilt-rotor or fixed-wing/VTOL transition designs merge endurance with landing versatility. Early adopters include Autobahn GmbH bridge inspection units requiring both corridor coverage and structural proximity maneuvers.
Multi-rotor systems dominate installed base. Fixed-wing platforms are where expansion concentrates for linear infrastructure operators.
Technology:
Photogrammetry sensors anchor the lowest cost tier while LiDAR modules command premium positioning for vegetation penetration and bare-earth accuracy.
- Photogrammetry:Image-based 3D reconstruction using overlapping aerial photographs delivers centimeter-grade outputs for earthworks quantification. Midsize German contractors without survey-grade budgets default to this technology for progress documentation.
- LiDAR:Laser scanning modules emitting pulsed light pulses penetrate canopy cover for digital terrain models. Australia's mining rehabilitation mandates in Western Australia accelerate adoption where vegetation monitoring requires ground-surface visibility beneath tree cover.
- GPS:GNSS receivers with real-time kinematic correction enable georeferenced data capture without ground control points. 5G network slicing trials in South Korea reduce base station dependency for mid-tier survey operations.
- Visual Imaging:Standard RGB cameras for qualitative site documentation and stakeholder reporting. General contractors deploy these for at-risk concrete pour monitoring where metric precision is secondary to real-time visibility.
Photogrammetry sensors dominate installed base. LiDAR modules are where expansion concentrates for environmental compliance and vegetation-heavy terrain.
Application:
Site surveying commands the highest flight-hour volumes while inspection applications generate premium per-hour revenue through specialized payload requirements.
- Site Surveying:Topographic measurement and earthworks quantification through photogrammetric or LiDAR capture. FAA Part 107 waiver expansion for BVLOS operations accelerates cycle times on US transmission corridor projects.
- Inspection:Structural proximity flights for bridge, facade, and tower assessment. EASA's specific category framework in Europe mandates remote identification and geofencing for urban operations, consolidating vendor selection around pre-certified OEMs.
- Monitoring:Recurrent capture for progress tracking and schedule compliance. Germany's federal transport infrastructure pipeline creates recurring demand across tunnel, bridge, and track renewal programs.
- Mapping:Large-area orthomosaic generation for master planning and as-built documentation. China's CAAC operational certification requirements shape product design standards for domestic megaproject deployments.
Site surveying dominates installed base. Inspection applications are where expansion concentrates for premium-margin specialized services.
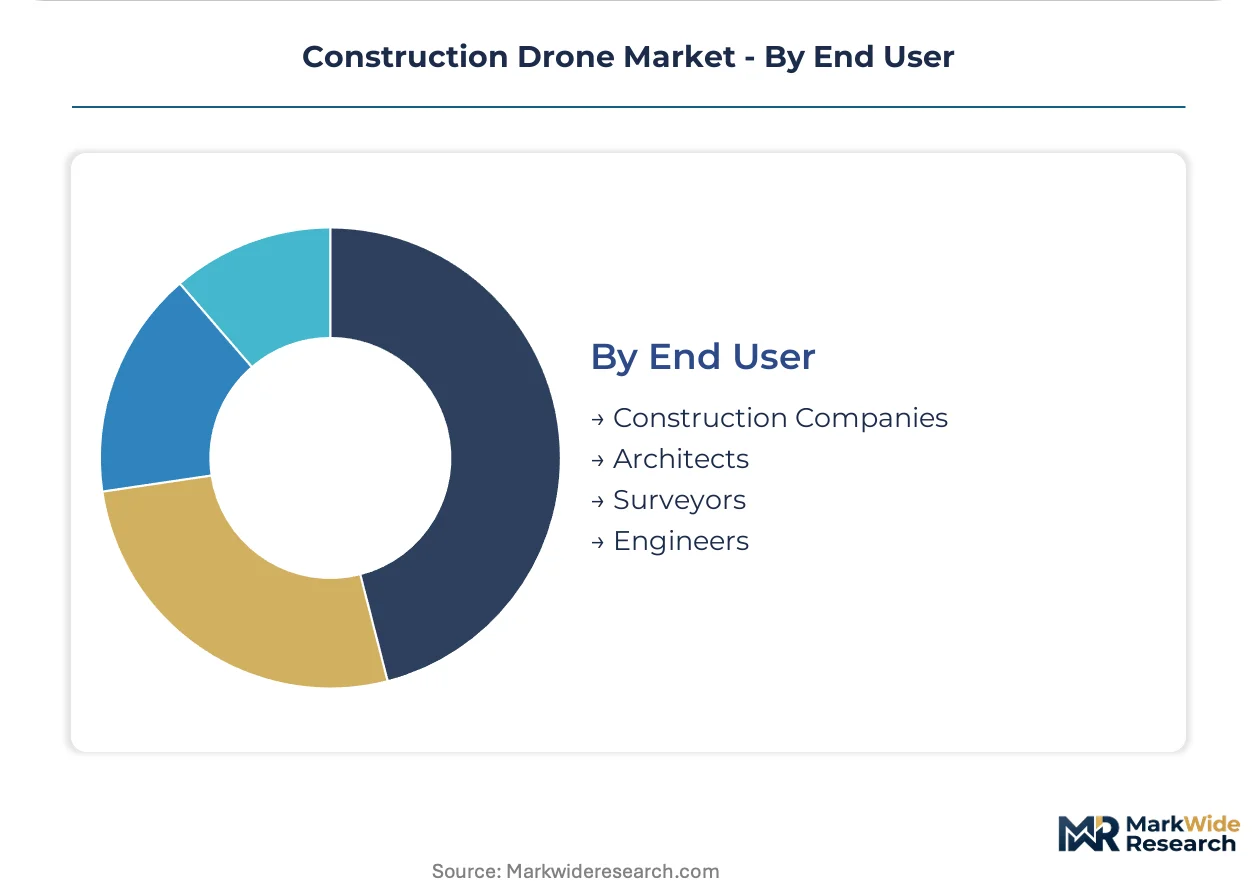
End User:
Construction companies represent the highest-volume procurement segment while surveyors command the most stringent accuracy specifications and certification requirements.
- Construction Companies:General contractors integrating drones for progress documentation and schedule verification. Germany's midsize construction groups prefer flight-hour subscription models over capital purchase due to maintenance capability gaps.
- Architects:Design-phase visualization and site context capture for schematic development. Urban canyon projects in US cities drive GPS-denied navigation requirements for early-phase documentation.
- Surveyors:Licensed professionals requiring legally defensible boundary and as-built documentation. Total station substitution resistance persists where ground-based methods retain court-admissible precedent.
- Engineers:Structural and civil engineering firms conducting load assessment and deformation monitoring. Australia's state-level environmental frameworks create recurring vegetation monitoring contracts for rehabilitation compliance.
Construction companies dominate installed base. Surveyors are where expansion concentrates as regulatory clarity and data admissibility standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive procurement dominates China's volume-driven contractor base, while German buyers absorb premium hardware costs for regulatory compliance certainty. US demand elasticity sits in the middle, with waiver-dependent operators weighing mobilization savings against certification investments.
United States
FAA Part 107 waiver expansion for beyond-visual-line-of-sight corridors accelerates transmission line and pipeline survey cycles. The FAA's recurrent training mandates and testing center capacity constraints throttle fleet scaling for regional operators. Texas and California infrastructure corridors concentrate deployment where BVLOS approvals reduce mobilization costs across hundreds of kilometers.
Germany
Deutsche Bahn and Autobahn GmbH project backlogs drive centimeter-grade topographic validation demand across tunnel, bridge, and track renewal programs. EASA's specific category framework mandates remote identification broadcast modules and geofencing databases as baseline firmware. Bavaria and North Rhine-Westphalia host the densest contractor networks for federal transport infrastructure compliance.
China
Megaproject density across high-speed rail and urban renewal compresses replacement cycles as contractors scale to heavier LiDAR payloads. CAAC operational certification requirements shape domestic product design standards for flight altitude ceilings and fail-safe protocols. The Yangtze River Delta and Pearl River Delta clusters dominate procurement volume for photogrammetry and multispectral monitoring deployments.
Australia
State-level mining rehabilitation mandates in Queensland and Western Australia create recurring vegetation monitoring contracts requiring multispectral drone deployment. The country's remote pilot licensing framework aligns with ICAO standards while preserving state-level environmental enforcement discretion. Perth and Brisbane anchor the contractor ecosystem for resource sector compliance documentation.
United Arab Emirates
Mega-project construction across NEOM and Dubai South generates demand for progress documentation and at-risk monitoring where GPS-denied navigation capabilities differentiate platform selection. The General Civil Aviation Authority's drone regulations mandate registration and operational authorization for commercial activities above 400 feet. Dubai and Abu Dhabi concentrate fleet deployments for smart city and linear infrastructure documentation.
Construction Drone Market Key Industry Players
Capability concentration sits with autonomous flight software specialists; scale advantage sits with hardware-integrated service networks. The vendor base separates into three tiers: full-stack platform OEMs with captive sensor ecosystems, flight-control software houses licensing autonomy stacks, and regional system integrators assembling third-party payloads. Consolidation pressure runs through sensor convergence trends and cross-border certification reciprocity demands. Dominant competitive moves include strategic partnerships for BIM platform integration and geographic expansion through pre-certified technical file packages.
Within the full-stack tier, DJI, Skydio, and JOUAV occupy distinct positioning vectors. DJI exemplifies the hardware-integrated service network archetype through sprawling calibration and firmware support infrastructure. Skydio represents the autonomous flight software specialist model with reduced pilot dependency for complex structural proximity missions. JOUAV anchors the fixed-wing endurance segment purpose-built for linear infrastructure corridors. These three illustrate how vendor selection criteria fragment between regulatory pre-certification, autonomy sophistication, and mission-specific airframe optimization.
| Leading Market Players |
|---|
| Delair |
| Ascent AeroSystems |
| DJI |
| Autel Robotics |
| AeroVironment |
| Skydio |
| JOUAV |
| Draganfly |
| Parrot |
| Others |
Cost & Logistics Intelligence
Shenzhen's lithium-polymer cell production clusters concentrate battery supply for North American and European hardware OEMs, translating input cost volatility into downstream pricing pressure across multi-rotor and fixed-wing platform tiers. This geographic concentration forces procurement teams to absorb margin compression or pass through logistics exposure to contractor buyers.
Pricing Analysis
Aftermarket service contracts anchor lifetime value capture for construction drone vendors, with calibration and firmware support subscriptions extending revenue streams beyond initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates autonomy-enabled platforms from basic photogrammetry rigs from entry-level visual imaging units. Price differentiation hinges on FAA Part 107 certification bundling and sensor precision grades. Cost compression in the standard tier is intensifying because DJI's service network density forces regional operators into narrower maintenance margins. Midsize German construction groups exhibit highest price sensitivity due to irregular survey demand and capital constraint preferences.
Supply Chain Analysis
Upstream feedstock for flight control chipsets draws from Taiwan semiconductor foundries, South Korea memory fabricators, and Chinese rare-earth magnet processors. Lithium-polymer cells, carbon-fiber airframes, and CMOS image sensors constitute the critical component trinity. Single-source vulnerability concentrates in battery cell supply where Chinese production dominance creates tariff exposure and logistics chokepoint risk. Distribution runs through OEM-direct channels for large engineering firms and regional system integrators for midsize contractors lacking internal UAV maintenance capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction drone market fragmentation creates white-space opportunities as autonomous flight algorithms compress operator training timelines and expand deployability into GPS-denied environments, splintering demand across specialized autonomy stacks, sensor-integrated platforms, and regional service networks.
For Market Incumbents: Pre-empt substitution threats from terrestrial laser scanners by embedding BIM platform APIs that position drone service providers as embedded workflow partners rather than peripheral capture vendors. Deepen backward integration into sensor calibration infrastructure to lock in recurring firmware support contracts. Consolidate vendor selection criteria around pre-certified technical file packages that satisfy EASA's specific category framework mandates. For New Entrants and Emerging Players: Pursue Australia's mining rehabilitation compliance segment where state-level vegetation monitoring mandates in Queensland and Western Australia create recurring multispectral deployment contracts with limited incumbent saturation. Target flight-hour subscription models for German midsize construction groups lacking internal UAV maintenance capabilities. Anchor go-to-market positioning through 5G network slicing partnerships that enable centimeter-grade positioning without dedicated base station infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among autonomous flight software specialists with reduced pilot dependency offerings, as these platforms compress labor intensity while expanding mission profiles into structurally complex environments. Long-term viability hinges on regulatory reciprocity across FAA Part 107, EASA open-category, and CAAC operational certification frameworks. Acquisition prioritization should target fixed-wing endurance platform developers with BVLOS waiver traction. The signal to watch is beyond-visual-line-of-sight approval velocity for linear infrastructure corridors.| Strategic Initiative | Industry Significance |
|---|---|
| BIM Platform Integration | Direct data pipeline connectivity to Autodesk and Bentley platforms embeds drone service providers in master planning workflows. |
| BVLOS Waiver Expansion | FAA Part 107 corridor approvals for transmission line operators reduce mobilization cycles across hundreds of kilometers. |
| Sensor Convergence Development | Integrated photogrammetry-LiDAR payload systems cut equipment swap downtime on megaproject sites with varying work phases. |
| Geographic Pre-Certification | Technical file packages satisfying EASA specific category mandates consolidate vendor selection among European infrastructure developers. |
| Subscription Model Piloting | Flight-hour contracts with guaranteed data delivery SLAs attract German midsize construction groups preferring operational expenditure treatment. |
Research Approach
Cross-validation between primary interviews with drone fleet managers at large infrastructure developers and secondary validation through FAA waiver disclosure databases anchors the qualitative findings. Stakeholder roles span survey operations directors, remote pilot certification trainers, EASA conformity assessment body representatives, and procurement leads at federal transport infrastructure agencies. Secondary sources include EASA operational authorization registries, CAAC product certification listings, and customs records for lithium-polymer cell import flows. Bottom-up platform shipment aggregation triangulates against top-down construction expenditure allocation estimates.
Calibration against historical BVLOS waiver approval trajectories and sensor payload attachment rates refines the analytical framework across the projection horizon. Segmentation dimensions span product type, sensor technology, application work phase, end-user archetype, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and payload upgrade intensity patterns. Industry-specific forecast inputs incorporate Deutsche Bahn track renewal program backlogs and Queensland mining rehabilitation compliance timelines.
Sensitivities concentrate around lithium-polymer battery supply disruptions, EASA altitude ceiling restriction modifications, and total station substitution resistance among licensed surveyors. Forecasts embed assumptions regarding operator certification reciprocity agreements and airspace integration rule evolution. Cross-checking against IEA infrastructure investment benchmarks and national transport agency capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Private Bunker Market
Specialized Building Services
Industrial Access Platform Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
Street Furniture Market
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Horizontal Directional Drilling Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Portable Ramps Market