
 Portable Toilet Market | 2026-2036
Portable Toilet Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Toilet Market Outlook
Construction site procurement is hardening as infrastructure investment accelerates across North America and Europe. Satellite Industries leverages its manufacturing scale to dominate the North American rental supply chain. PolyJohn Enterprises anchors its position through backward integration into polyethylene molding operations. Xiamen Toppla Material Technology Co., Ltd. competes on cost-efficient rotational molding for export markets.
Portable toilets are self-contained sanitation enclosures fabricated from high-density polyethylene via rotational molding, designed to receive and chemically treat human waste without connection to sewer infrastructure. Standard units occupy the volume base across construction and municipal applications, while luxury units command premium pricing at outdoor weddings and corporate events. Accessibility units face accelerating specification mandates under ADA and equivalent disability access codes across multiple jurisdictions. Rental services control the dominant distribution channel, capturing recurring revenue through fleet deployment rather than unit sale.
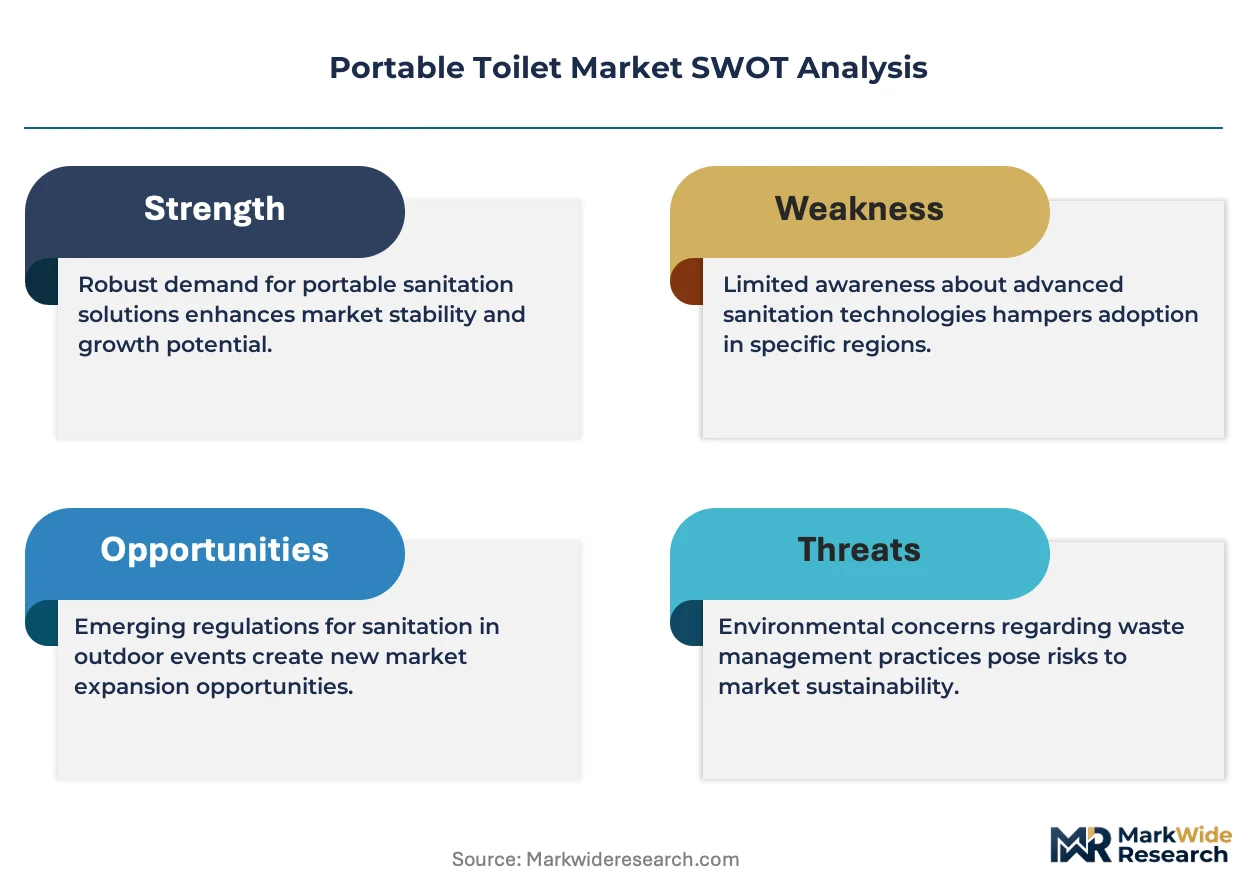
OSHA sanitation standards mandate minimum toilet-to-worker ratios on job sites, directly shaping fleet sizing for contractor segments. EPA wastewater discharge rules govern waste removal and treatment protocols, elevating compliance costs for rental operators. The EU Green Deal and REACH chemical restrictions are reshaping the European product specification landscape. Stakeholders must monitor regulatory divergence between jurisdictions when configuring product portfolios and service territories.
Market Dynamics
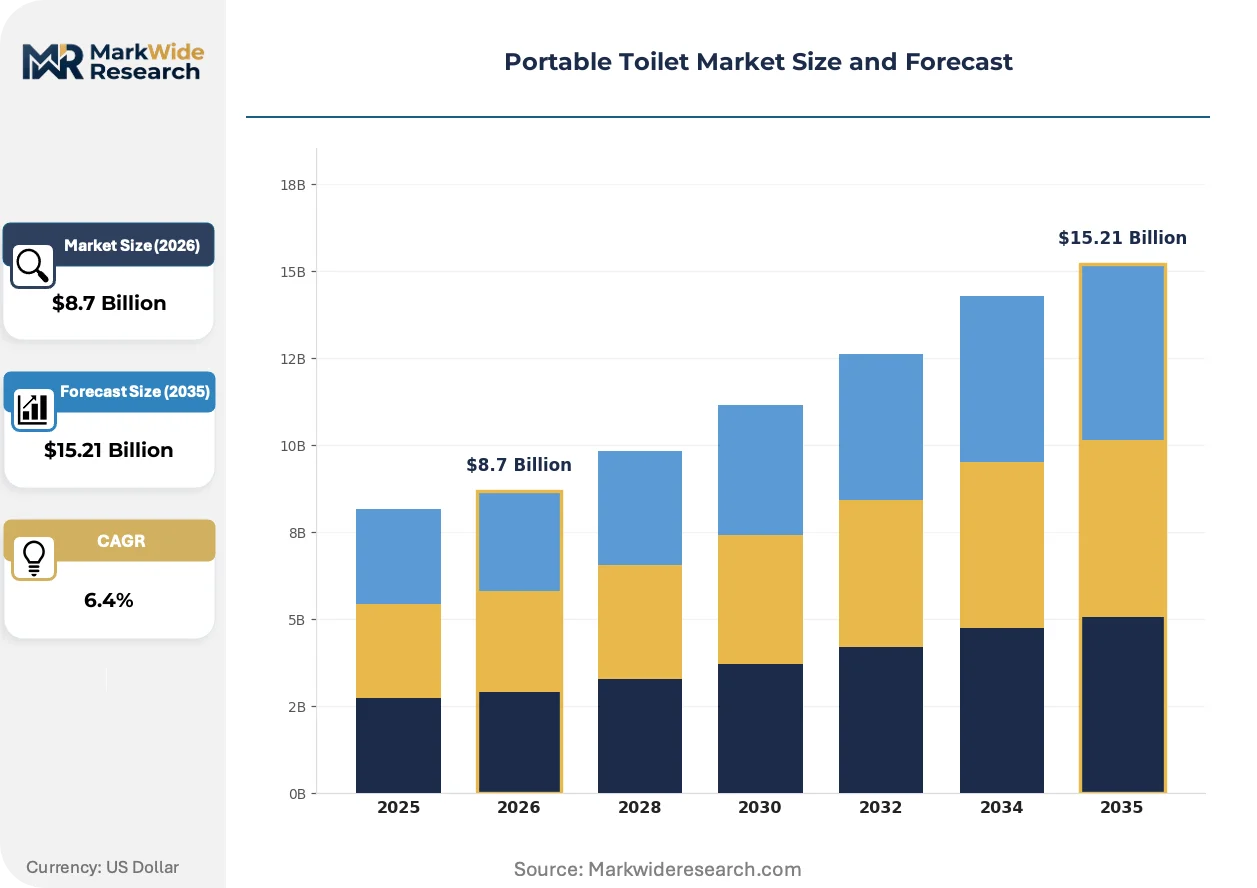
Infrastructure stimulus across North America and Europe is hardening construction site procurement standards, while EPA wastewater discharge rules and OSHA sanitation mandates compress fleet upgrade cycles for rental operators.
Growth Catalysts
- OSHA Sanitation Standards:Federal mandates specifying toilet-to-worker ratios on job sites directly expand rental fleet deployment requirements across US contractor segments.
- Polyethylene Rotational Molding:Advances in HDPE fabrication yield lighter, more durable units that reduce transport costs and extend service intervals for fleet operators.
- Remote Workforce Expansion:Mining, oilfield, and renewable energy projects in Australia and Canada sustain demand for self-contained sanitation in locations lacking sewer infrastructure.
Market Restraints
- Resin Price Volatility:Crude-linked polyethylene feedstock costs swing unpredictably, compressing margins for manufacturers without captive supply arrangements.
- Waste Hauler Concentration:Regional oligopolies in liquid waste disposal limit rental operators' negotiating leverage on pumping and treatment services.
- Chemical Treatment Restrictions:REACH and state-level biocide regulations constrain formaldehyde-based formulations, forcing reformulation investments.
Strategic Opportunities
- EU Green Deal Alignment:Circular economy incentives reward manufacturers developing recyclable HDPE formulations and solar-powered ventilation systems.
- Luxury Event Segment:Outdoor weddings and corporate gatherings in Germany and the United Kingdom absorb premium-priced flushing units with interior finishes.
- Accessibility Mandates:ADA and equivalent disability access codes across multiple US states and Australian jurisdictions accelerate specification of wheelchair-compliant units.
Industry Challenges
- Route Density Mathematics:Waste pumping logistics require minimum fleet concentration per geographic cluster to achieve unit economics, constraining expansion into sparse rural territories.
- Cross-Jurisdictional Compliance:Operators serving multiple states or countries face fragmented chemical approval processes and divergent waste discharge protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Toilet Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Units, Luxury Units, Accessibility Units, Self-Cleaning Units Application: Construction Sites, Events, Outdoor Activities, Disaster Relief End User: Contractors, Event Organizers, Campgrounds, Municipalities Distribution Channel: Direct Sales, Online Retail, Wholesalers, Rental Services |
| Companies Covered | PolyPortables, ADCO Holdings Inc., Toi Toi & Dixi, Armal, B&B Portable Toilets, Satellite Industries, Thetford, Xiamen Toppla Material Technology Co., Ltd., PolyJohn Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Toilet Market Strategic Shifts
Sanitation hardware is converging with remote monitoring systems and alternative waste treatment chemistries, reshaping how rental fleets manage asset utilization and regulatory compliance.
Sensor-enabled fill-level monitoring is decentralizing fleet management for large rental operators. GPS-integrated ultrasonic sensors transmit tank capacity data to dispatch centers, eliminating unnecessary service runs. Construction contractors with multi-site projects now demand this visibility as a standard contract term, compressing competitive differentiation timelines for technology laggards.
EPA wastewater discharge rules are tightening enforcement of manifest documentation for waste removal. Rental operators must now maintain chain-of-custody records linking each unit to treatment facility receipt. The compliance burden falls heaviest on mid-size regional fleets lacking integrated routing software, accelerating consolidation toward vertically integrated national providers.
Event planners are bundling sanitation with adjacent site services rather than sourcing standalone toilet rentals. Catering, tenting, and power vendors now sub-contract portable toilet provision, disintermediating direct relationships between end-users and rental specialists. This channel shift concentrates buyer power with multi-service event production firms in the United States and Australia, pressuring standalone rental margins.
Portable Toilet Market Segmentation
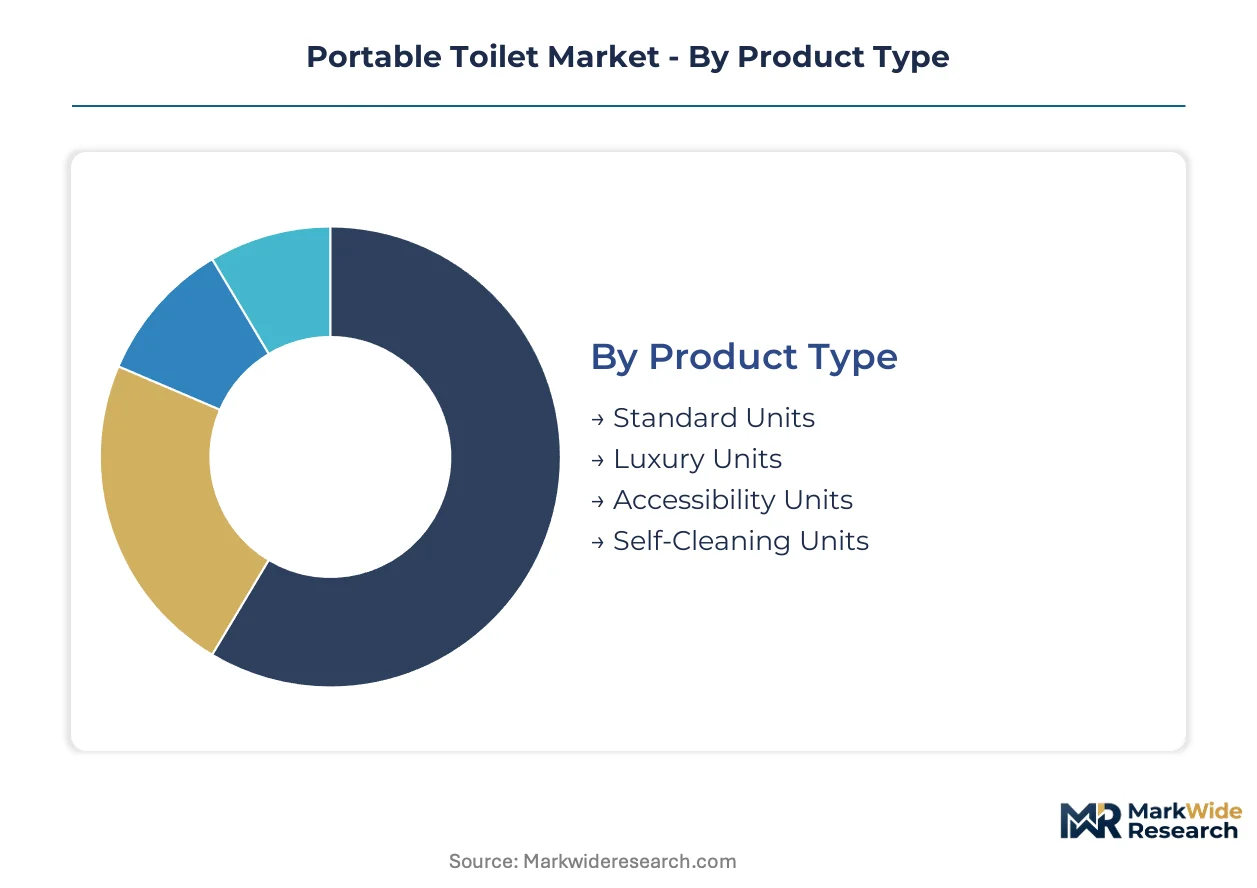
Product configuration in the portable toilet market splits between standalone rental fleet assets and integrated site-service bundles. Segmentation discipline matters because rental operators configure procurement differently than direct-sale contractors, while regulatory pressure varies sharply across construction, event, and municipal end-uses.
Product Type:
Integration depth separates standalone units deployed for basic sanitation from embedded systems combining sensors, chemical treatment, and waste monitoring.
- Standard Units:Rotationally molded HDPE enclosures with chemical holding tanks and passive ventilation. Construction sites across the United States and Germany absorb the majority of fleet placements due to OSHA and equivalent EU sanitation mandates specifying minimum worker-to-toilet ratios.
- Luxury Units:Flushing mechanisms with freshwater tanks, interior lighting, and finished surfaces. Outdoor weddings and corporate events in the United Kingdom and Australia command premium rental rates, though unit economics require higher route density to justify transport costs.
- Accessibility Units:Wheelchair-compliant footprints with grab bars and ramp-ready entry points.
- Self-Cleaning Units:Automated spray systems and UV sanitation cycles reducing service frequency.
Volume placements concentrate in Standard Units; the faster expansion belongs to Accessibility Units as ADA and equivalent disability access codes tighten across multiple jurisdictions.
Application:
Cost tier separation distinguishes capital-heavy construction procurement from event-driven rental spikes with compressed deployment windows.
- Construction Sites:Long-duration deployments with weekly pumping cycles and damage-resistant specifications. Infrastructure stimulus in the United States and Germany is hardening procurement standards, expanding fleet sizing requirements for general contractors managing multi-year projects.
- Events:Short-term rentals with premium positioning and rapid install-strike logistics. Music festivals and sporting events in Australia sustain seasonal demand spikes that strain regional fleet availability.
- Outdoor Activities:Remote deployments for camping, hunting, and recreational access.
- Disaster Relief:Emergency mobilization contracts with government procurement vehicles.
Construction Sites anchor procurement volume; Events show the steepest expansion trajectory as outdoor gathering frequency climbs post-pandemic.
End User:
Customer type determines contract structure, with recurring rental agreements dominating contractor relationships against transactional municipal procurement.
- Contractors:Multi-site construction firms with standardized fleet specifications and centralized billing. OSHA compliance requirements in the United States mandate documented sanitation provision, embedding rental services into project cost structures.
- Event Organizers:Production companies bundling sanitation with tenting, catering, and power services. Disintermediation pressures in the United States and Australia concentrate buyer power with multi-service vendors.
- Campgrounds:Seasonal operators with fixed infrastructure and limited upgrade cycles.
- Municipalities:Public parks and emergency management departments with budget-constrained procurement.
Contractors generate the densest route economics; Event Organizers are gaining share fastest as bundling reshapes channel relationships.
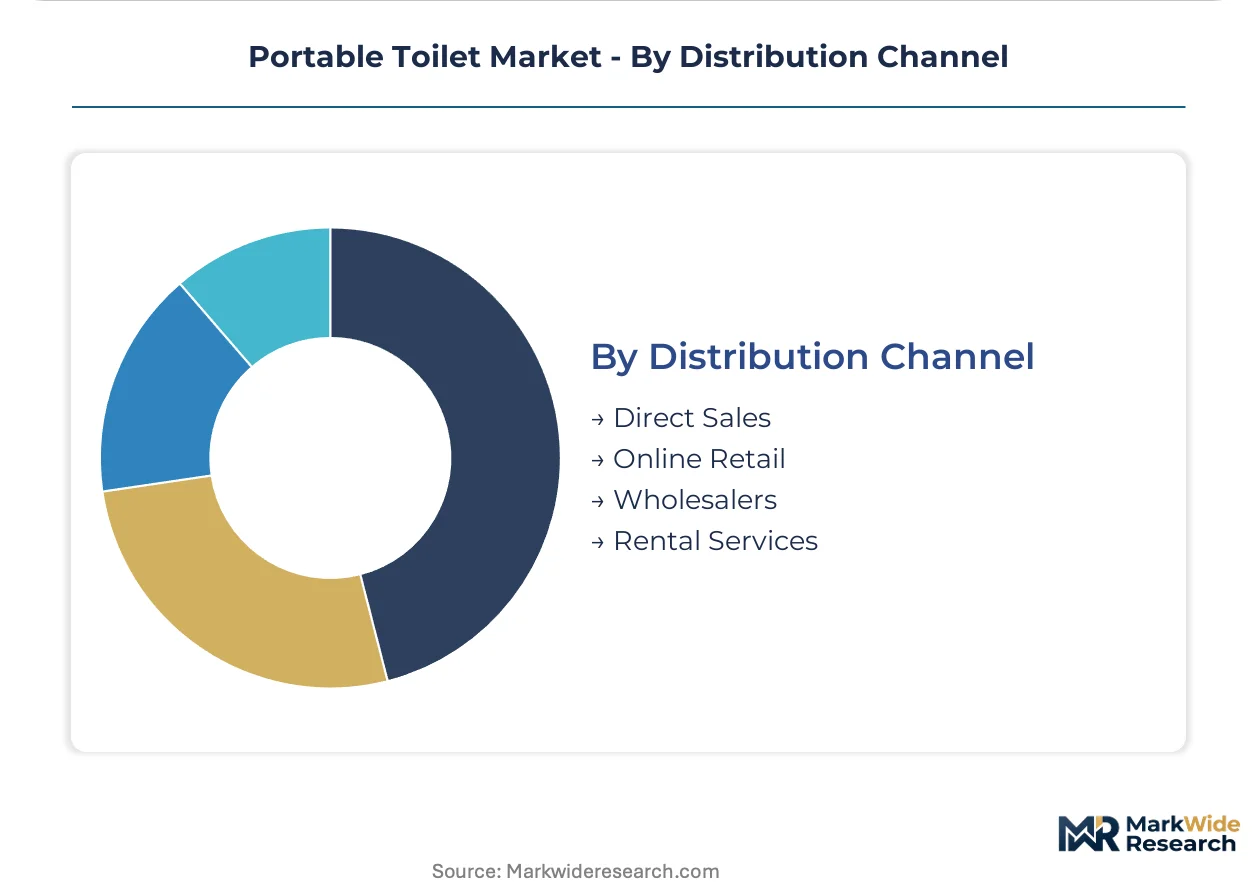
Distribution Channel:
Supply concentration favors rental services with captive fleet deployment over transactional sales channels.
- Rental Services:Fleet operators capturing recurring revenue through pumping, maintenance, and unit rotation. Vertical integration into waste hauling and treatment creates margin defense against regional disposal oligopolies in the United States.
- Direct Sales:Manufacturer-to-contractor transactions for permanent installations and disaster relief stockpiles.
- Online Retail:Small-volume consumer purchases for recreational and residential applications.
- Wholesalers:Regional distributors serving independent rental operators and construction supply houses.
Rental Services control placement volume; Direct Sales expand most quickly for permanent infrastructure and emergency preparedness programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Xiamen and Shenzhen concentrate rotational molding capacity for export-oriented portable toilet manufacturing. Special economic zones across coastal China offer VAT rebates and duty exemptions that lower production costs for HDPE fabrication. These zones anchor supply chain density for Asia-Pacific distribution.
United States
Infrastructure stimulus packages accelerate construction site procurement across Texas and Florida. OSHA sanitation standards mandate documented toilet-to-worker ratios on federal projects. Satellite Industries anchors manufacturing and rental fleet operations in the Midwest corridor.
Germany
EU Green Deal incentives reshape product specifications for circular economy compliance. REACH chemical restrictions constrain formaldehyde-based treatment formulations. Bavaria and North Rhine-Westphalia host dense rental operator clusters serving cross-border construction flows.
Australia
Mining and renewable energy projects in Western Australia sustain remote workforce sanitation demand. TGA-equivalent state-level health regulations govern waste treatment protocols. Queensland's event economy drives seasonal luxury unit rentals for outdoor festivals.
United Arab Emirates
Expo legacy infrastructure and construction megaprojects concentrate fleet deployment around Dubai and Abu Dhabi. MOHAP sanitation guidelines apply to temporary facilities on government contracts. Free zones in Jebel Ali lower import duties for European and Asian manufacturers.
Canada
Oil sands operations in Alberta and remote mining camps require self-contained sanitation without sewer connectivity. Health Canada guidelines align with provincial occupational health mandates. Ontario's construction stimulus expands rental fleet sizing for Toronto-Ottawa corridor projects.
Portable Toilet Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. The United States and Germany concentrate vertically integrated rental operators with captive manufacturing, while Chinese fabricators dominate export supply through cost-efficient rotational molding. Three archetypes define competitive positioning: integrated rental-manufacturing hybrids, pure-play HDPE molders serving distributor channels, and regional rental fleets sourcing from third-party suppliers. Capacity expansion and backward integration into polyethylene resin procurement represent the dominant competitive moves.
Among North American integrated operators, Satellite Industries and PolyJohn Enterprises exemplify the rental-manufacturing hybrid archetype. Xiamen Toppla Material Technology Co., Ltd. occupies a position within the export-focused molder tier serving distributor networks across Asia-Pacific and Middle Eastern markets.
| Leading Market Players |
|---|
| PolyPortables |
| ADCO Holdings Inc. |
| Toi Toi & Dixi |
| Armal |
| B&B Portable Toilets |
| Satellite Industries |
| Thetford |
| Xiamen Toppla Material Technology Co., Ltd. |
| PolyJohn Enterprises |
| Others |
Value Chain & Pricing Dynamics
Polyethylene resin indices and crude-linked feedstock benchmarks cascade through rotational molding costs into three-tier pricing structures across premium, standard, and economy levels. Construction contractors absorb standard-unit pricing through long-term rental agreements, while event planners face spot-market volatility for luxury fleet deployments during seasonal peaks.
Pricing Analysis
Short lead-time premiums compress margins for event-season spot orders, while extended contract windows unlock volume discounts for multi-year construction deployments. Price differentiation rests on certification grade and geographic delivery cost, with OSHA-compliant units commanding premiums over uncertified alternatives. Cost compression in the standard tier is intensifying because resin price volatility feeds directly into manufacturer pricing power. Municipal buyers exhibit highest price sensitivity due to budget-constrained procurement cycles, whereas corporate event planners demonstrate lowest sensitivity when bundling sanitation with adjacent site services.
Supply Chain Analysis
OSHA and EPA certification requirements gate supplier qualification for US contractor segments, filtering out uncertified molders from federal project eligibility. Manufacturing concentrates in the United States, Germany, and coastal China, with Xiamen and Shenzhen free trade zones anchoring export-oriented HDPE fabrication. Raw material dependencies center on polyethylene resin, chemical treatment formulations, and sensor components for fill-level monitoring. Single-source vulnerability in regional waste hauler networks constrains rental operator expansion into sparse rural territories. Distribution runs through vertically integrated rental fleets rather than transactional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around operators with captive manufacturing and waste hauling capabilities. EPA manifest documentation requirements and integrated routing software investments are forcing mid-size regional fleets toward acquisition by national providers.
For Market Incumbents: Anticipate sensor-enabled fleet management becoming a standard contract term rather than competitive differentiator, and accelerate backward integration into polyethylene resin procurement to defend margins against feedstock volatility. Satellite Industries and PolyJohn Enterprises exemplify the hybrid archetype that mid-size competitors must emulate or exit. Waste hauler concentration in regional oligopolies represents the critical margin pressure point requiring upstream control over pumping and treatment services. For New Entrants and Emerging Players: ADA and equivalent disability access codes across multiple US states and Australian jurisdictions open a window for wheelchair-compliant unit specialization. Target accessibility mandates as the most penetrable segment, where specification acceleration outpaces incumbent fleet reconfiguration. Pursue direct sales to municipal emergency preparedness programs as the optimal go-to-market angle, bypassing rental channel consolidation. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size regional rental fleets with dense route economics but lacking integrated compliance software in the United States. Long-term viability hinges on technology-enabled fleet management and cross-jurisdictional waste hauling permits. Monitor EPA enforcement actions on manifest documentation as the signal indicating acceleration toward national-provider consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Procurement | Captive polyethylene supply insulates margins from crude-linked feedstock volatility. |
| Sensor-Enabled Fleet Management Deployment | GPS-integrated fill-level monitoring eliminates unnecessary service runs for construction contractors. |
| Accessibility Unit Certification Investment | ADA-compliant specifications capture specification mandates across US state jurisdictions. |
| Waste Hauling Permit Expansion | Cross-jurisdictional pumping licenses reduce dependency on regional disposal oligopolies. |
| Solar-Powered Ventilation System Development | EU Green Deal circular economy incentives reward recyclable HDPE and renewable energy integration. |
Study Parameters
Trade publications, customs records, and EPA regulatory filings formed the secondary backbone, supplemented by primary interviews with rental fleet operators, rotational molding plant managers, construction procurement directors, and waste hauling service providers. Bottom-up unit deployment estimates triangulated against top-down infrastructure spending forecasts across the analysis window.
Bottom-up modeling aggregated fleet deployment data by product tier and application segment, while top-down validation cross-referenced construction permit volumes and event licensing statistics. Segmentation dimensions included product configuration, end-use industry, distribution channel structure, and regional regulatory cluster. CAGRs derived from weighted average of historical deployment trajectories and projected infrastructure stimulus allocation. Key inputs encompassed OSHA toilet-to-worker ratio mandates and polyethylene resin price correlation coefficients.
The model assumes a particular technology adoption path; alternative pathways for sensor-enabled waste monitoring would alter the outlook if construction contractors accelerate standardization timelines. Forecasts reflect assumptions regarding infrastructure stimulus continuity and REACH chemical restriction implementation pace. A model refresh is warranted upon material change in EPA wastewater discharge enforcement intensity or regional waste hauler consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
Construction Drone Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Street Furniture Market
Specialized Building Services
Portable Ramps Market
Specialized Building Services
Horizontal Directional Drilling Market
Specialized Building Services
Private Bunker Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Europe Stair Lift Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Industrial Access Platform Market