
 Europe Stair Lift Market | 2026-2036
Europe Stair Lift Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Stair Lift Market Foresight
Aluminum rail extrusion is pivoting from steel chassis construction across European stair lift manufacturing, cutting unit weight and simplifying on-site installation for curved rail systems. Handicare Group AB leverages its Nordic distribution network to sustain aftermarket service contracts. Stannah Lifts Holdings Ltd anchors British production with vertically integrated rail fabrication in Andover. Thyssenkrupp Elevator AG competes through building-technology cross-selling into commercial retrofit specifications.
A stair lift is a motorized seated or standing platform that travels along a fixed rail mounted to stair treads or walls, typically rated for loads between 120 kg and 160 kg with DC motor drives enabling battery backup during power interruption. The equipment serves primarily to preserve independent mobility for users with limited ambulatory capacity in multi-level structures. Straight stair lifts dominate volume due to standardized rail lengths and rapid two-hour installation protocols, while curved stair lifts command premium positioning because each rail requires photogrammetric measurement and CNC bending to match individual staircase geometry. Residential end users generate the majority of revenue, though healthcare facilities are expanding fleet procurement as hospital-at-home programs reduce acute readmissions.
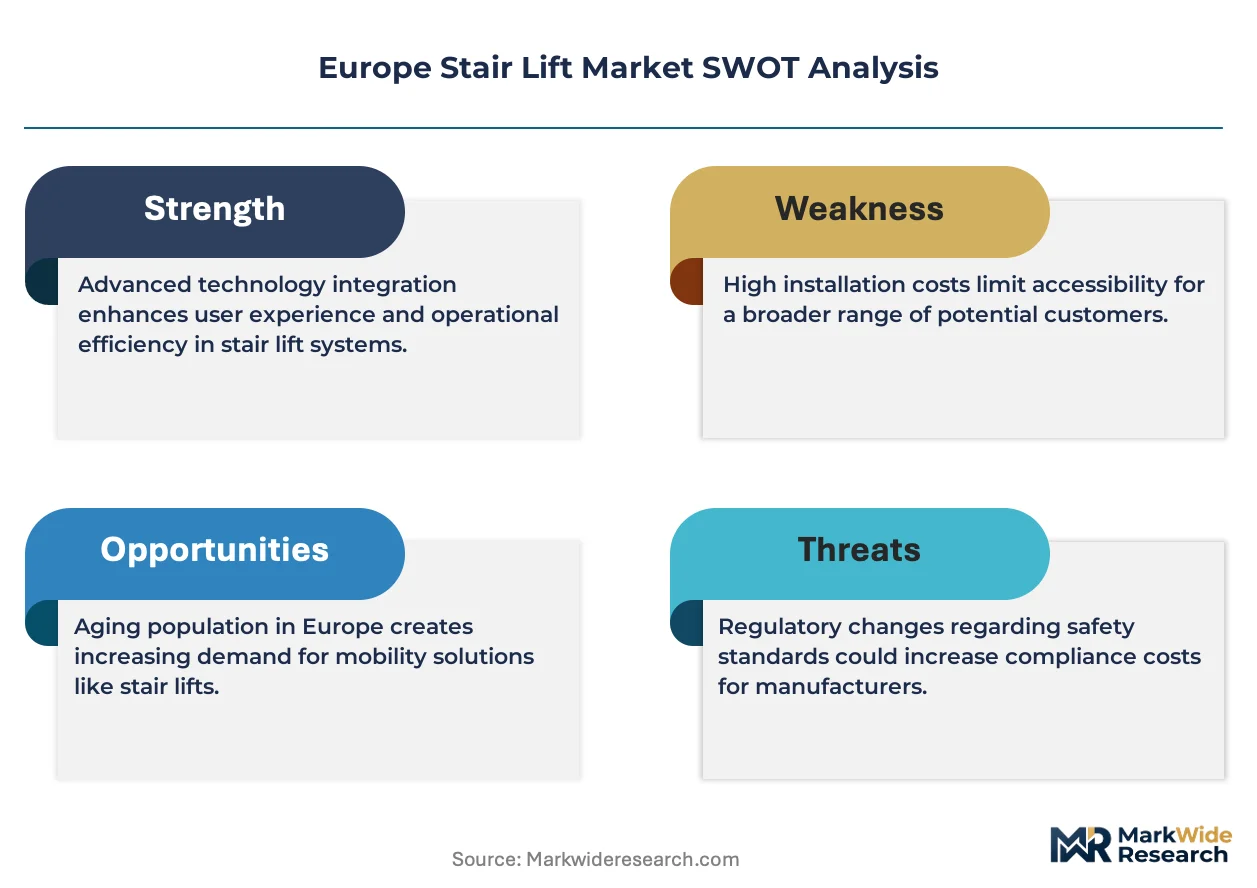
The EU Medical Device Regulation (MDR) classifies seated stair lifts as Class I medical devices, mandating clinical evaluation and post-market surveillance that elevates documentation burdens for manufacturers seeking CE marking. The ECHA REACH framework restricts certain flame retardants in seat upholstery and cable sheathing, pushing suppliers toward halogen-free polymer formulations. Germany's KBA-informed national building codes and France's accessibility mandates under the loi handicap further shape product specification sheets. Stakeholders must monitor how the EU Green Deal's embodied carbon reporting through CSRD extends to mobility equipment supply chains.
Market Dynamics
The EU Medical Device Regulation (MDR) is recalibrating competitive positioning across European stair lift manufacturing, elevating documentation burdens and post-market surveillance costs that favor scaled producers over fragmented regional assemblers.
Growth Catalysts
- France's Loi Handicap accessibility mandates:Municipal grants for historic urban housing retrofits are accelerating curved stair lift installations in Paris, Lyon, and Bordeaux districts.
- Hospital-at-home program expansion:Healthcare facilities in Germany and the United Kingdom are expanding fleet procurement to reduce acute readmissions and extend patient discharge capacity.
- Aluminum rail extrusion adoption:DC-powered units leveraging lightweight chassis construction are cutting on-site installation time for curved rail systems by enabling single-technician deployment.
Market Restraints
- CE marking compliance friction:The EU MDR's clinical evaluation requirements for Class I medical devices are extending product launch timelines by 8-14 months for manufacturers lacking established quality management systems.
- REACH-restricted flame retardants:ECHA restrictions on halogenated compounds in seat upholstery and cable sheathing are forcing reformulation of polymer supply chains at 15-20% cost premiums.
- Photogrammetric measurement dependency:Curved stair lift rail production remains bottlenecked by CNC bending capacity concentrated in Nordic and British fabrication clusters.
Strategic Opportunities
- Italy's aging-in-place policy acceleration:Regional accessibility subsidies in Lombardy and Tuscany are opening procurement channels for residential retrofit specialists serving historic multi-level housing stock.
- Service contract unbundling:Aftermarket maintenance agreements are separating from initial equipment sales, creating recurring revenue streams for distributors with Nordic network density.
- CSRD-aligned embodied carbon reporting:The EU Green Deal's corporate sustainability disclosure requirements are rewarding suppliers with documented low-carbon aluminum sourcing and circular rail take-back programs.
Industry Challenges
- Photogrammetric technician scarcity:Curved rail measurement and CAD translation requires specialized skills concentrated among aging workforce cohorts in British and German manufacturing hubs.
- Dual certification complexity:Products serving both residential and healthcare facility end-uses must maintain parallel documentation trails for CE marking and national building code compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Stair Lift Market |
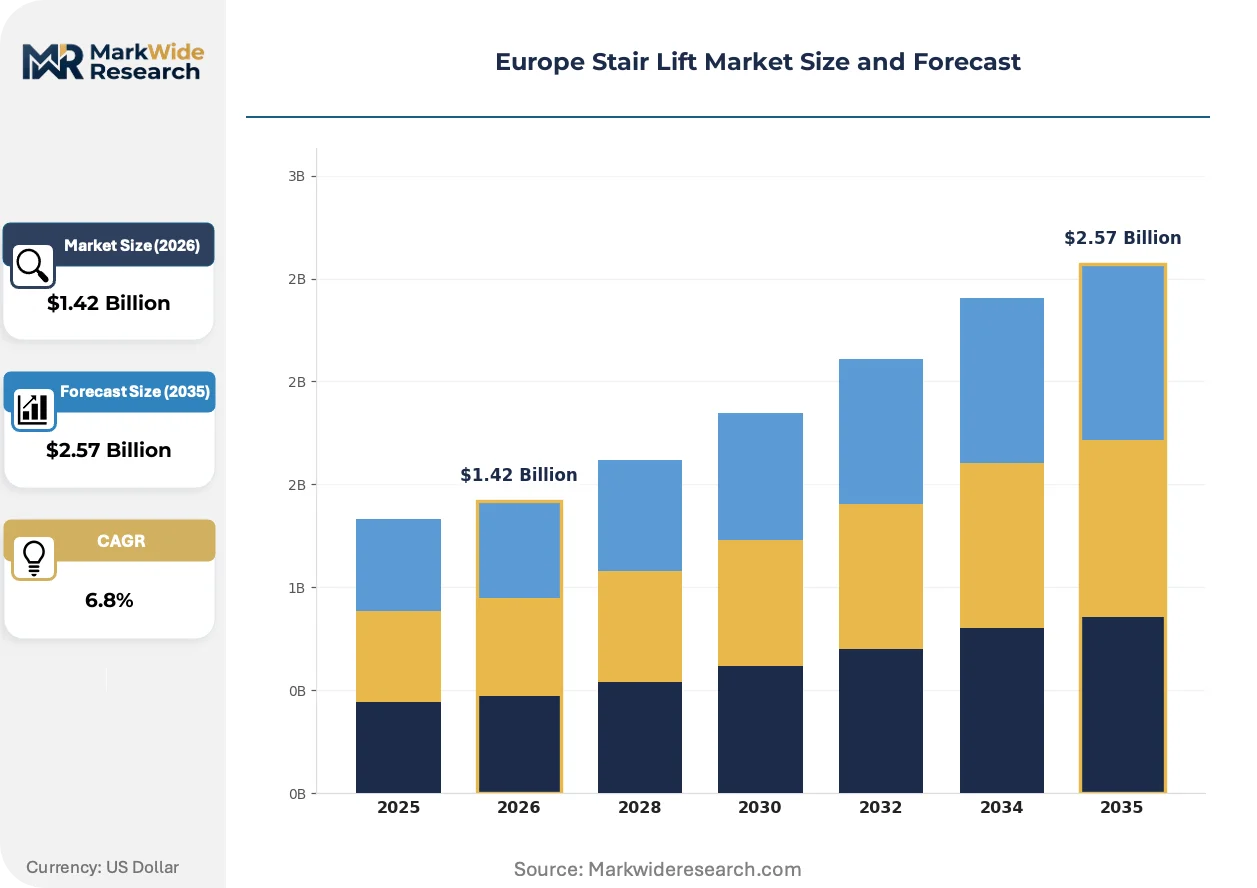
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Stair Lifts, Curved Stair Lifts, Outdoor Stair Lifts, Standing Stair Lifts End User: Residential, Commercial, Healthcare Facilities, Public Buildings Installation Type: New Installation, Retrofit Installation, Modular Installation, Custom Installation Technology: AC Powered, DC Powered, Battery Operated, Hydraulic |
| Companies Covered | Thyssenkrupp Elevator AG, Weigl Liftsysteme GmbH, Handicare Group AB, Aritco Lift AB, HIRO Lift Hillenkötter und Ronsieck GmbH, Stannah Lifts Holdings Ltd, Bruno Independent Living Aids, Inc., Vimec S.r.l., Acorn Mobility Services Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Stair Lift Market Shifts & Advancements
European stair lift manufacturing is pivoting toward modularity and connected service architectures, driven by regulatory pressure on documentation traceability and buyer demand for minimized installation disruption in occupied residential structures.
Lithium-ion battery backup systems are expanding into premium and mid-market product tiers, replacing legacy lead-acid configurations with compact DC power architectures that enable slimmer rail profiles and wall-mounted charging stations. Home healthcare providers in Germany and the United Kingdom are specifying these units for hospital-at-home fleet standardization. The technology is expanding into municipal procurement specifications as reliability metrics become weighted evaluation criteria alongside upfront capital cost.
REACH enforcement is tightening chemical compliance protocols for seat upholstery and electrical sheathing, with ECHA restrictions on halogenated flame retardants forcing polymer reformulation across Tier 2 and Tier 3 component suppliers. Manufacturers with captive compound development capabilities are internalizing specification control, while dependent assemblers face 15-20% input cost volatility. Italian and French producers serving historic housing retrofits are most exposed due to custom upholstery requirements for narrow staircase geometries.
Buyer preference is compressing toward rapid-installation protocols and unbundled after-sales service, with residential end users prioritizing same-day or next-day deployment commitments over brand loyalty. Distributors with captive installation technician networks are capturing margin from manufacturers lacking direct field service presence. This pattern is most visible in British and German markets where home healthcare intermediaries aggregate procurement volume and specify performance-based maintenance terms.
Europe Stair Lift Market Segmentation
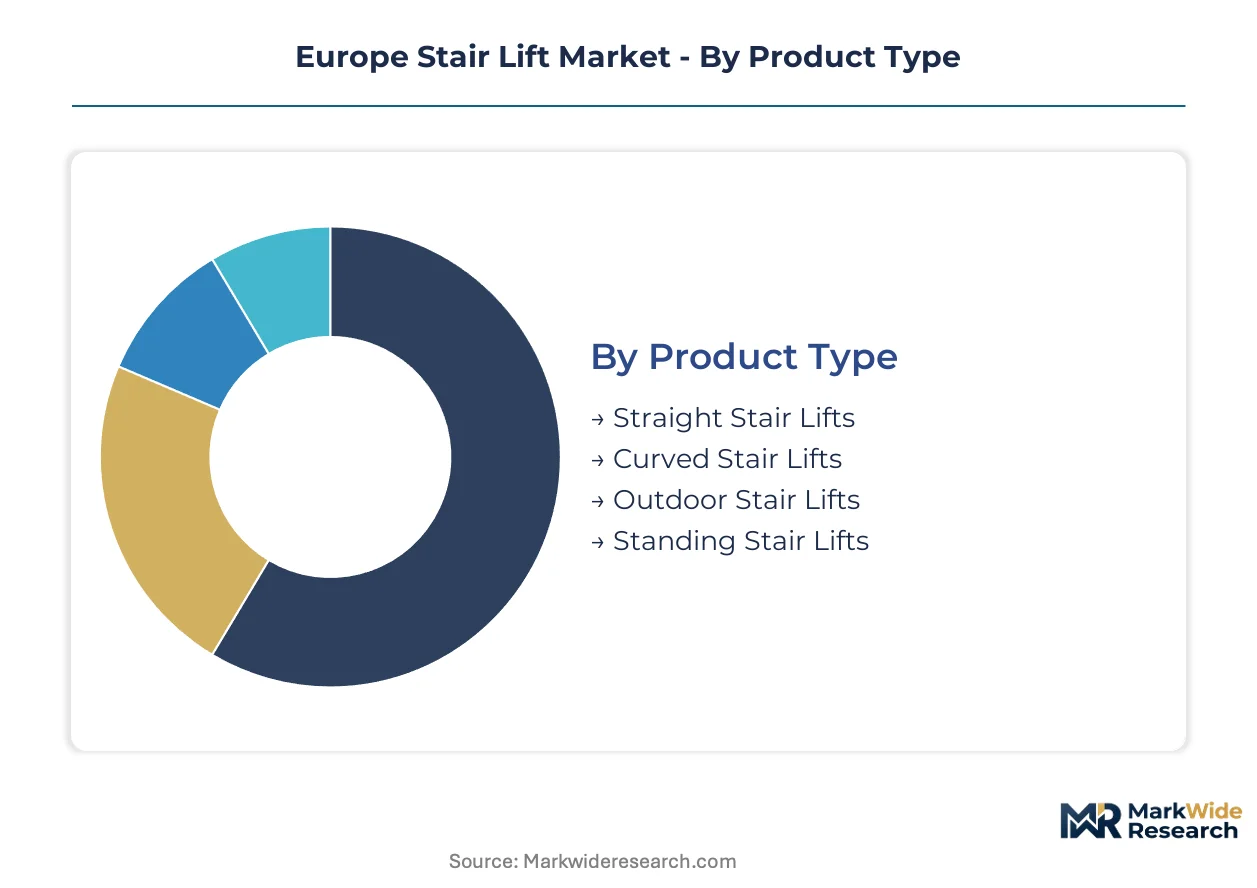
Stair lift procurement patterns in Europe diverge sharply between volume-driven residential retrofits and premium-capture curved rail systems for historic urban housing. Understanding these segment dynamics reveals where regulatory compliance costs concentrate and which technology architectures command pricing power.
Product Type:
Straight stair lifts dominate unit volume through standardized rail extrusions and rapid-installation protocols, while curved systems capture margin through custom photogrammetric engineering.
- Straight Stair Lifts:Fixed rail systems mount directly to stair treads with pre-cut aluminum extrusions rated for 120-160 kg loads. German and British home healthcare providers specify these for hospital-at-home fleet standardization due to sub-two-hour installation windows.
- Curved Stair Lifts:CNC-bent rails follow individual staircase geometry through photogrammetric measurement and CAD translation. French municipal grants for historic Paris and Lyon housing stock are accelerating demand despite Nordic and British fabrication bottlenecks.
- Outdoor Stair Lifts:Weather-sealed DC-powered units with marine-grade finishes serve exterior access ramps in Mediterranean coastal municipalities.
- Standing Stair Lifts:Perch-style platforms accommodate users with limited knee flexion in narrow Victorian and Edwardian terraced housing common across British urban centers.
Today's leader: Straight Stair Lifts. Tomorrow's challenger: Curved Stair Lifts.
End User:
Residential aging-in-place policies anchor demand volume, yet healthcare facility procurement is gaining share through hospital-at-home program expansion.
- Residential:Private homeowners in France and Italy leverage municipal accessibility grants for historic multi-level housing retrofits. REACH-compliant upholstery reformulation adds 15-20% material cost premiums for custom narrow-geometry installations.
- Healthcare Facilities:German and British acute care networks are expanding fleet procurement to extend patient discharge capacity and reduce readmission penalties. Lithium-ion battery backup specifications are becoming weighted evaluation criteria.
- Commercial:Office building retrofits in German KBA-informed code jurisdictions prioritize DC-powered units for emergency egress reliability.
- Public Buildings:Municipal accessibility mandates under France's Loi Handicap drive curved rail installations in heritage-protected administrative structures.
Residential maintains volume dominance. Healthcare Facilities are climbing the fastest as reimbursement models shift toward acute avoidance.
Installation Type:
Retrofit protocols concentrate technician deployment capacity, while modular architectures are emerging to compress project timelines in occupied structures.
- New Installation:Specified during residential construction or major renovation, enabling concealed rail mounting and integrated charging infrastructure.
- Retrofit Installation:Dominates European volume through rapid-deployment protocols in existing multi-level housing. British distributors with captive technician networks capture margin from manufacturers lacking direct field presence.
- Modular Installation:Pre-assembled rail sections with snap-fit connections reduce on-site labor hours for straight-run applications in German and Nordic markets.
- Custom Installation:Required for curved rail systems in irregular staircase geometries typical of Italian and French historic urban cores.
Retrofit Installation commands current capacity allocation. Modular Installation is gaining share fastest through buyer preference for minimized disruption.
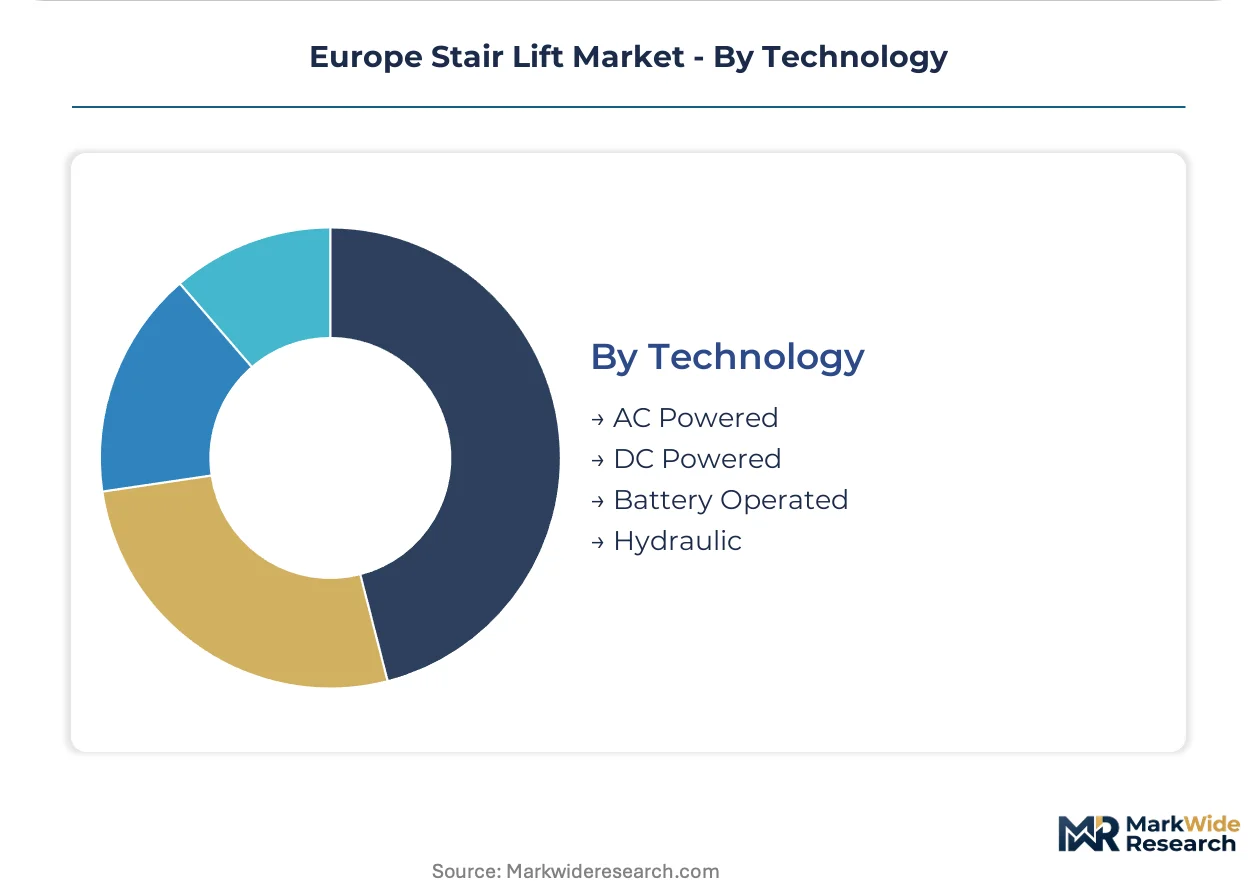
Technology:
DC-powered architectures are displacing AC alternatives across premium and mid-market tiers, driven by battery backup reliability requirements and slimmer rail profile possibilities.
- DC Powered:24V motor drives with lithium-ion battery backup enable wall-mounted charging stations and continued operation during grid interruption. German and British hospital-at-home programs are standardizing on this architecture.
- Battery Operated:Standalone power systems serve exterior installations or structures lacking reliable electrical infrastructure in rural Mediterranean municipalities.
- AC Powered:Legacy mains-connected systems persist in cost-sensitive residential retrofits where backup power is not a specified requirement.
- Hydraulic:High-load platforms for bariatric applications or commercial freight-adapted specifications remain niche due to maintenance complexity and fluid containment regulations.
DC Powered anchors technology roadmaps. Battery Operated is expanding most quickly into outdoor and off-grid deployment scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Andover fabrication cluster anchors European stair lift manufacturing through vertically integrated rail production serving curved system demand across British, French, and German markets.
Germany
Hospital-at-home program expansion drives fleet procurement of DC-powered units with lithium-ion backup among German home healthcare networks. The KBA-informed national building codes mandate emergency egress reliability specifications for commercial retrofit installations. The North Rhine-Westphalia industrial corridor concentrates CNC bending capacity for curved rail fabrication serving domestic and export demand.
United Kingdom
British distributors with captive technician networks capture aftermarket margin through rapid-installation protocols and unbundled service contracts. Stannah Lifts Holdings Ltd anchors domestic production with rail fabrication in Andover supplying curved systems for Victorian terraced housing retrofits. London and Southeast England generate concentrated demand for standing stair lifts in narrow urban staircase geometries.
France
Municipal accessibility grants under the loi handicap accelerate curved stair lift installations in historic Paris, Lyon, and Bordeaux housing districts. ANSM post-market surveillance requirements align with EU MDR clinical evaluation mandates for Class I medical device classification. The Île-de-France region concentrates specification engineering capacity for photogrammetric measurement and CAD translation services.
Italy
Regional aging-in-place subsidies in Lombardy and Tuscany open procurement channels for residential retrofit specialists serving historic multi-level housing stock. REACH restrictions on halogenated flame retardants force upholstery reformulation at 15-20% cost premiums for custom narrow-geometry installations. The Veneto and Emilia-Romagna manufacturing belts host component suppliers adapting polymer supply chains to ECHA compliance timelines.
Sweden
Nordic distribution network density enables aftermarket service contract penetration across residential and healthcare facility end users. Handicare Group AB leverages regional logistics infrastructure to sustain recurring revenue streams separate from initial equipment sales. The Stockholm-Uppsala corridor concentrates technical training capacity for photogrammetric technician development addressing workforce scarcity in curved rail measurement.
Europe Stair Lift Market Competitive Landscape
Global majors compete with regional champions across fabrication capacity and aftermarket service density. The European vendor base organizes into scaled manufacturers with captive rail production, mid-tier assemblers dependent on outsourced bending capacity, and specialized distributors controlling installation technician networks. Strategic archetypes include vertically integrated fabricators, Nordic service-heavy operators, and British retrofit-focused specialists. Competitive moves concentrate on geographic network expansion and unbundled maintenance contract capture.
Among German-anchored industrial conglomerates, Thyssenkrupp Elevator AG exemplifies building-technology cross-selling into commercial retrofit specifications. Swedish fabricators Handicare Group AB and Aritco Lift AB occupy positions within the Nordic service-network tier, leveraging regional distribution density for aftermarket contract penetration. British specialists Stannah Lifts Holdings Ltd and Acorn Mobility Services Ltd represent the retrofit-installation archetype, with Stannah anchoring vertically integrated rail production in Andover.
| Leading Market Players |
|---|
| Thyssenkrupp Elevator AG |
| Weigl Liftsysteme GmbH |
| Handicare Group AB |
| Aritco Lift AB |
| HIRO Lift Hillenkötter und Ronsieck GmbH |
| Stannah Lifts Holdings Ltd |
| Bruno Independent Living Aids, Inc. |
| Vimec S.r.l. |
| Acorn Mobility Services Ltd |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators in the British Midlands and Nordic regions anchor European stair lift manufacturing, concentrating rail-bending capacity in Andover and Stockholm-Uppsala corridors while exerting pricing discipline through captive technician networks and unbundled service contract structures.
Pricing Analysis
REACH-mandated polymer reformulation passes 15-20% input cost premiums directly to buyers of custom curved stair lifts, particularly for historic housing retrofits in France and Italy requiring narrow-geometry upholstery adaptation. Pricing stratifies across premium photogrammetric-engineered curved systems, standard DC-powered straight units, and economy AC-powered alternatives. Price differentiation rests on certification grade under EU MDR Class I medical device classification and geographic density of aftermarket service coverage. Cost compression in the economy tier intensifies because British distributors with captive installation networks capture margin from manufacturers lacking direct field presence. Healthcare facility buyers in Germany and Britain show least price sensitivity due to hospital-at-home program standardization requirements, while residential retrofit end users in Southern Europe prioritize rapid-installation commitments over brand loyalty.
Supply Chain Analysis
Dual-sourcing qualification requirements from German and British home healthcare networks mandate redundant polymer compound suppliers and secondary CNC bending capacity across Nordic and British fabrication clusters. Aluminum extrusion feedstock concentrates in Germany, Norway, and Belgium, while lithium-ion battery cells draw from South Korean and Japanese cell manufacturers. REACH restrictions on halogenated flame retardants in seat upholstery and cable sheathing create regulatory restriction exposure for Tier 2 Italian and French component assemblers dependent on external compound development. Distribution runs through home healthcare intermediaries in Germany and Britain, specialized retrofit distributors in France and Italy, and direct municipal procurement channels under Loi Handicap accessibility mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in European stair lift manufacturing hinges on aluminum rail extrusion adoption compressing installation labor costs and lithium-ion battery backup specifications shifting mid-market buyers toward premium-tier DC architectures.
For Market Incumbents: Extend aftermarket service contract penetration through Nordic distribution network density to offset equipment commoditization pressure from modular installation protocols. Consolidate photogrammetric technician training capacity in British and German manufacturing hubs to defend against workforce scarcity threatening curved rail production bottlenecks. Prioritize captive polymer compound development capabilities to neutralize REACH-driven input cost volatility exposure.
For New Entrants and Emerging Players: Launch via unbundled maintenance agreements targeting Italian regional aging-in-place subsidies in Lombardy and Tuscany, where historic multi-level housing stock lacks established retrofit specialist coverage. Penetrate standing stair lift demand in narrow British Victorian terraced housing through perch-style platform specialization. Pursue white-label supply partnerships with French municipal procurement channels under Loi Handicap grant programs rather than direct brand competition with entrenched Andover fabricators.
For Investors and Strategic Acquirers: Building-technology conglomerates with elevator cross-selling capabilities represent the most active acquirer category in this space, seeking stair lift portfolios to deepen commercial retrofit specification access. Five-to-ten year viability favors targets with vertically integrated rail fabrication and documented low-carbon aluminum sourcing aligned with CSRD disclosure requirements. Monitor EU MDR post-market surveillance documentation completeness as an inflection signal for scaled producers capable of absorbing compliance cost escalation that fragments regional assemblers.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Class I medical device compliance compresses launch timelines for manufacturers with established quality management systems. |
| Backward Integration into Rail Fabrication | Captive CNC bending capacity in Andover and Stockholm-Uppsala clusters secures curved system margin capture against photogrammetric bottlenecks. |
| Hospital System Partnership Development | German and British acute care networks standardize lithium-ion DC specifications for hospital-at-home fleet procurement. |
| Service Contract Unbundling | Aftermarket maintenance agreements separate from initial equipment sales, creating recurring revenue streams for Nordic network operators. |
| CSRD-Aligned Carbon Reporting | Documented low-carbon aluminum sourcing and circular rail take-back programs reward suppliers under EU Green Deal disclosure mandates. |
Research Methodology
Bottom-up residential and healthcare facility procurement modeling reconciled against top-down aluminum extrusion and CNC bending capacity tracking forms the analytical core of this study. Primary interviews with stair lift manufacturing executives, home healthcare procurement directors, municipal accessibility grant administrators, photogrammetric measurement technicians, and polymer compound suppliers combined with secondary validation from ECHA REACH restriction filings, EU MDR clinical evaluation databases, ANSM post-market surveillance records, and KBA-informed building code specifications. Triangulation across named stakeholder inputs and documented regulatory frameworks ensures segmentation integrity.
Historical trendline analysis of straight versus curved stair lift installation volumes, DC power architecture adoption rates, and unbundled service contract penetration established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, end-user category, installation protocol, and power technology, with regional regulatory cluster differentiation for France, Germany, Britain, Italy, and Sweden. CAGRs derive from installed base replacement cycles, municipal grant program expansion trajectories, and hospital-at-home reimbursement model shifts. Industry-specific forecast inputs incorporate photogrammetric technician workforce demographics and lithium-ion battery supply qualification timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR enforcement intensity escalation or aluminum alloy supply disruption scenarios. Deviation in REACH restriction expansion to additional halogenated compound categories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialized Building Services
Construction Drone Market
Specialized Building Services
Clean Room Pass Box Market
Specialized Building Services
US and Europe Cleanrooms Market
Specialized Building Services
Portable Toilet Rental Market
Specialized Building Services
Industrial Access Platform Market
Specialized Building Services
Building Inspection Services Market
Specialized Building Services
Global Automated Industrial Door Market
Specialized Building Services
Automatic Industrial Doors Market
Specialized Building Services
Global Prefabricated Bathroom Pods Market
Specialized Building Services
Portable Toilet Market
Specialized Building Services
Private Bunker Market
Specialized Building Services
Street Furniture Market
Specialized Building Services
Horizontal Directional Drilling Market
Specialized Building Services
Portable Ramps Market