
 Ireland Data Center Physical Security Market | 2026-2036
Ireland Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Data Center Physical Security Market Insights
Market Context
The capital-intensity divergence between integrated platform vendors and point-solution specialists is bifurcating competitive dynamics in Ireland's data center security landscape. Schneider Electric leverages its energy-management heritage to bundle power and security infrastructure, sustaining premium positioning among hyperscale entrants. Bosch Security Systems competes through video-analytics depth, while Johnson Controls anchors its presence via building-automation integration that spans thermal and physical access layers.
Technical Definition and Segment Structure
Ireland Data Center Physical Security encompasses layered protection systems—spanning biometric access control, IP-based surveillance, and intelligent perimeter detection—engineered to safeguard mission-critical infrastructure against unauthorized entry, environmental threats, and insider risk. These systems typically operate on redundant power architectures with sub-100-millisecond alarm propagation thresholds to meet Tier III and Tier IV facility standards. Surveillance cameras and access control systems command the largest installed base, though AI-based analytics represents the fastest-expanding technology segment as operators replace rules-based detection with machine-learning classifiers. Colocation providers constitute the most concentrated end-user revenue pool, while integrated installation approaches are displacing standalone deployments as facilities prioritize unified command interfaces.
Regulatory Framework
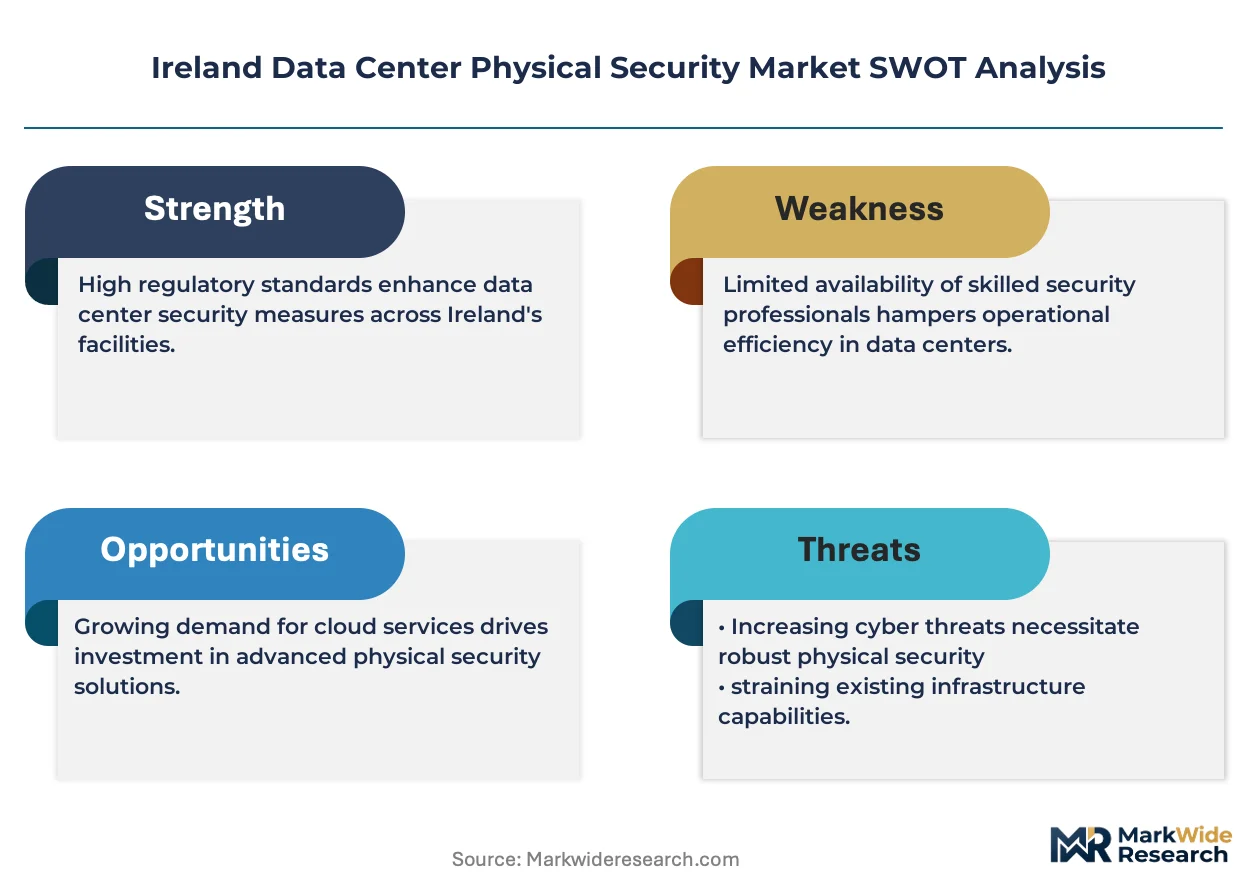
Ireland's Data Protection Commission enforces GDPR mandates that tie physical access records to data-breach notification protocols, directly elevating demand for audit-grade biometric and RFID logging systems. The National Cyber Security Centre's guidance on critical infrastructure protection, alongside ISO 27001 certification requirements prevalent among financial institutions, shapes procurement specifications and vendor qualification criteria. Stakeholders must monitor evolving EU AI Act provisions on automated surveillance, as pending classification of biometric analytics could recalibrate compliance costs and technology roadmaps for Dublin-region deployments.
Market Dynamics
Hyperscale cloud operators are consolidating Dublin-region deployments, compressing procurement cycles and forcing vendors toward unified platform architectures that merge physical access, surveillance, and environmental monitoring under single-pane command interfaces.
Growth Catalysts
- GDPR Enforcement:Ireland's Data Protection Commission mandates audit-grade physical access logging tied to breach notification protocols, compelling Tier III and Tier IV facilities to upgrade biometric and RFID systems.
- Hyperscale Expansion:Cloud operators are doubling floor space in Greater Dublin Area colocation facilities, generating concentrated demand for integrated perimeter detection and multi-factor authentication infrastructure.
- AI Video Analytics:Machine-learning classifiers are replacing rules-based detection in surveillance deployments, reducing false-positive rates and enabling predictive threat modeling for 24/7 operations.
Market Restraints
- Copper and Semiconductor Input Volatility:Supply constraints in specialized cabling and edge-computing chipsets inflate hardware lead times and compress installation margins for Irish systems integrators.
- Vendor Concentration Risk:Three European platform vendors dominate integrated security management software, creating single-source dependency for facilities requiring ISO 27001-aligned audit trails.
- EU AI Act Classification Uncertainty:Pending biometric surveillance restrictions under Brussels' artificial intelligence framework threaten to recalibrate compliance costs and delay technology roadmaps for Dublin deployments.
Strategic Opportunities
- Cork and Galway Secondary Markets:Colocation providers are diversifying beyond Dublin's power-constrained grid, opening greenfield security infrastructure opportunities in Ireland's secondary urban clusters.
- Convergence of Physical and Cyber Access:Identity-centric security platforms that unify logical and physical credentialing are creating new procurement categories for financial services and pharmaceutical data centers.
- Outcome-Based Service Contracts:Security-as-a-service models are displacing capital-heavy equipment purchases among mid-tier colocation operators seeking predictable opex structures.
Industry Challenges
- Certified Systems Integration Talent Scarcity:Shortage of technicians qualified in both IEC 62443 cybersecurity standards and physical access control deployment is extending commissioning timelines for multi-vendor environments.
- Legacy Analog Infrastructure Migration:Aging coaxial-based surveillance networks in established facilities require phased replacement strategies that maintain operational continuity during IP transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Data Center Physical Security Market |
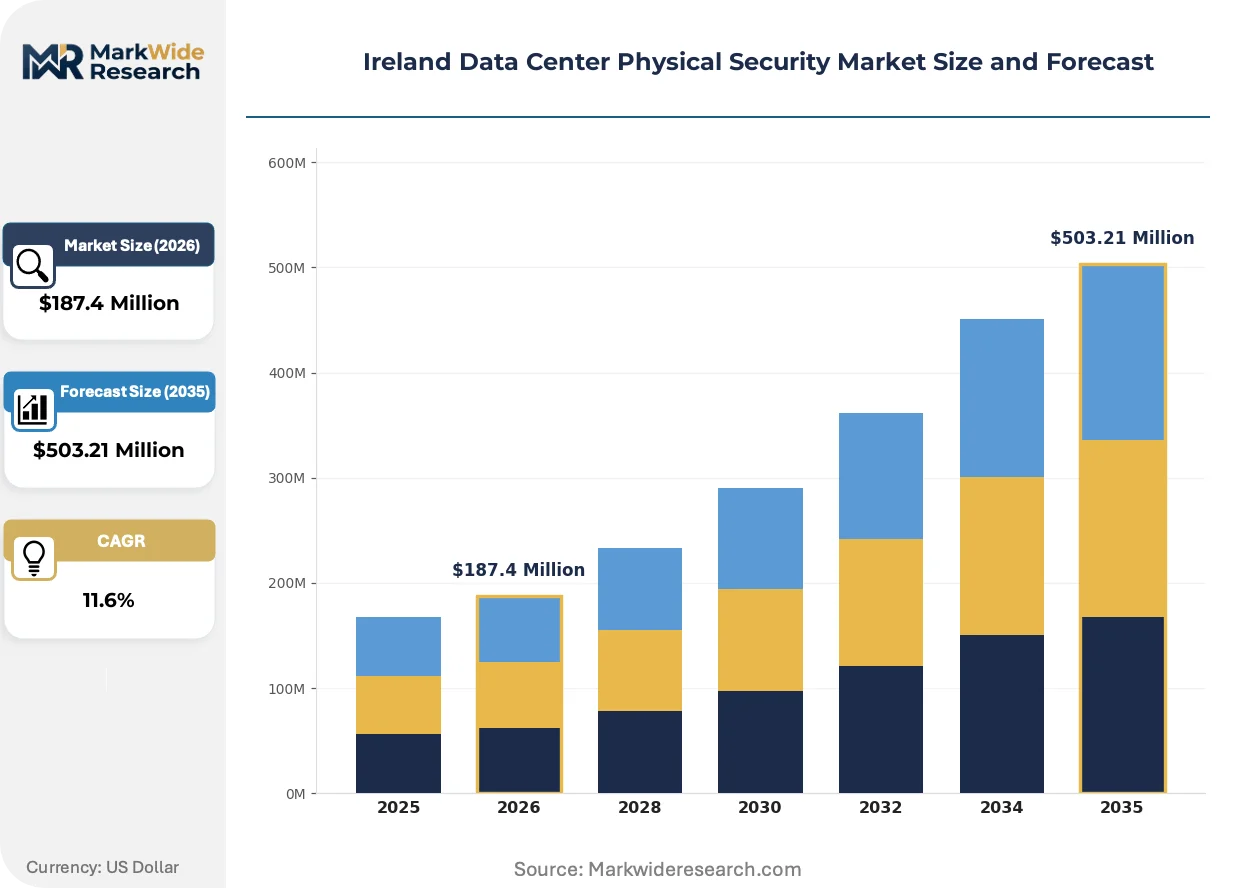
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Control Systems, Surveillance Cameras, Perimeter Security, Intrusion Detection Systems Technology: Biometric Systems, RFID, AI-based Analytics, Video Analytics End User: Colocation Providers, Enterprises, Government Agencies, Financial Institutions Installation: On-site Installation, Remote Installation, Integrated Solutions, Managed Services |
| Companies Covered | Schneider Electric, Bosch Security Systems, Johnson Controls, Cisco Systems, Securitas Technology, Honeywell International, Siemens AG, ABB Ltd, Axis Communications, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Data Center Physical Security Market Trends and Innovations
Machine-learning inference at the network edge is compressing alarm response latency and enabling autonomous threat classification without cloud dependency, reshaping procurement specifications for mission-critical facilities.
Multi-spectral video analytics is supplanting conventional visible-light surveillance in perimeter detection roles. Hyperscale operators in Dublin's western corridor are deploying thermal-visible fusion cameras at scale. This convergence is collapsing the distinction between environmental monitoring and physical security operations, forcing building-automation vendors to rearchitect platform boundaries.
GDPR's data-breach notification mandate is tightening physical access record retention requirements. Ireland's Data Protection Commission now treats unauthorized facility entry as a notifiable incident trigger. Colocation providers are responding by deploying biometric logging with immutable blockchain-anchored audit trails, prioritizing vendors with pre-certified compliance architectures.
Consolidated procurement frameworks are displacing standalone security tenders among enterprise data center operators. Buyers are bundling physical security with power and cooling infrastructure under single-master contracts. This pattern concentrates most visibly among pharmaceutical and financial services tenants in the Greater Dublin Area, where ISO 27001 certification drives preference for integrated vendor accountability.
Ireland Data Center Physical Security Market Segmentation
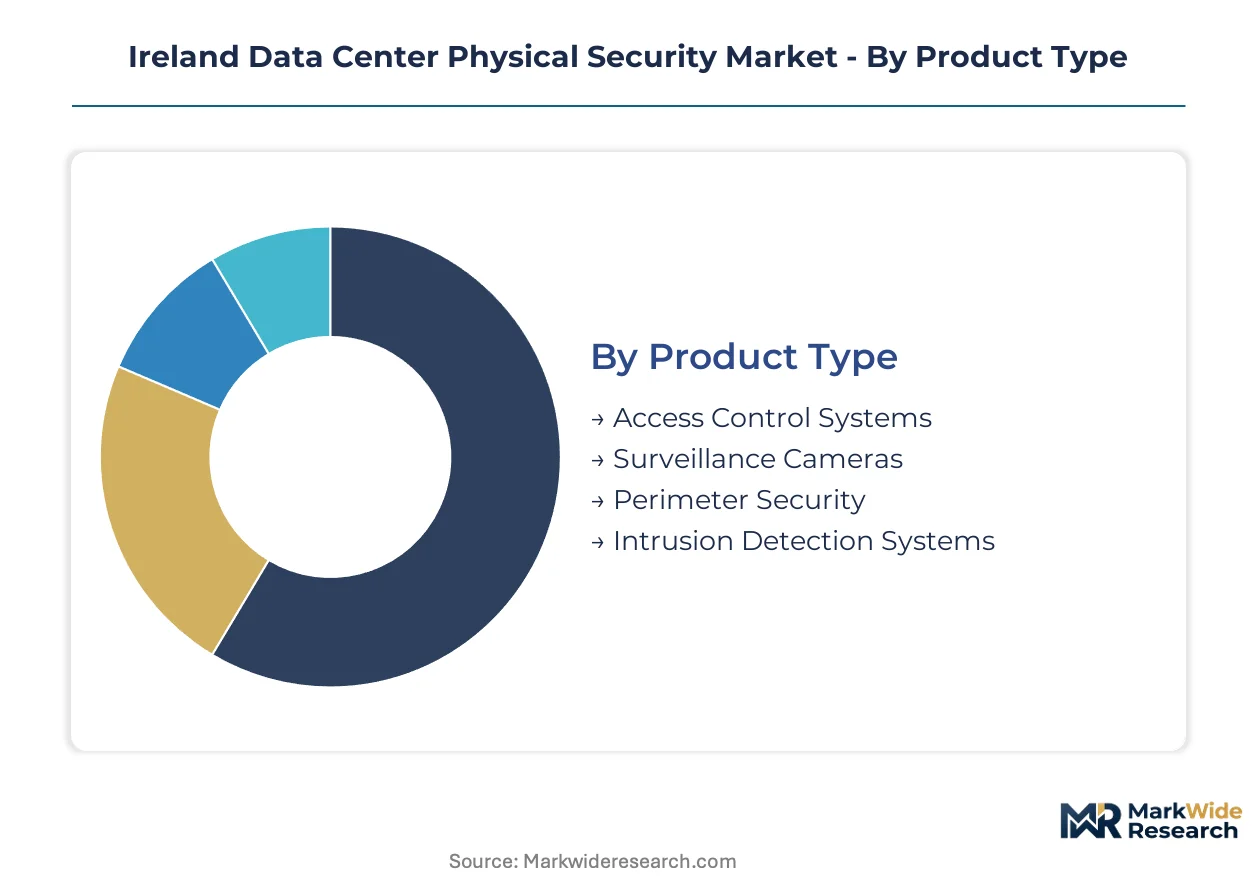
Segmentation in Ireland's data center physical security market reveals how regulatory mandates and hyperscale procurement patterns reshape technology deployment. Procurement specifications diver sharply across end-user categories, with GDPR enforcement creating tiered compliance requirements that favor integrated platform architectures over standalone solutions.
Product Type:
GDPR's breach notification protocols differentiate product categories by audit-trail depth, with biometric logging and video retention becoming mandatory specifications for Tier III and Tier IV facilities.
- Access Control Systems:Multi-factor authentication platforms incorporating biometric readers and RFID credentialing dominate hyperscale deployments. Dublin-region colocation providers mandate sub-100-millisecond latency for credential verification to maintain operational continuity during high-throughput shift changes.
- Surveillance Cameras:IP-based camera networks with edge-computing inference capabilities are displacing legacy analog infrastructure. Thermal-visible fusion cameras concentrate in perimeter roles at western Dublin hyperscale campuses, where environmental monitoring and physical security operations converge.
- Perimeter Security:Intelligent fence-mounted sensors and ground-based detection arrays protect facility boundaries.
- Intrusion Detection Systems:Motion sensors and glass-break detectors integrate with central command platforms for unified alarm management.
Established volume favors Surveillance Cameras; emerging adoption favors Access Control Systems as biometric compliance deepens.
Technology:
Cost-tier differentiation separates enterprise-grade AI platforms from standard RFID deployments, with financial institutions absorbing premium pricing for predictive analytics capabilities.
- AI-based Analytics:Machine-learning classifiers operating at the network edge enable autonomous threat detection without cloud dependency. Cork and Galway secondary market facilities prioritize these systems to reduce latency and operational risk in geographically distributed architectures.
- Biometric Systems:Fingerprint, iris, and facial recognition modalities anchor immutable audit trails required by Ireland's Data Protection Commission. Pharmaceutical data centers in the Greater Dublin Area specify these systems to satisfy ISO 27001 certification requirements.
- RFID:Contactless credentialing remains standard for mid-tier colocation operators balancing cost and compliance.
- Video Analytics:Rules-based detection algorithms serve legacy facility upgrades where full AI replacement is capital-constrained.
RFID commands the broadest installed base; AI-based Analytics represents the steepest expansion trajectory as hyperscale operators consolidate procurement.
End User:
Application-specific requirements fragment demand, with financial services and pharmaceutical tenants imposing stricter physical access logging than general enterprise users.
- Colocation Providers:Multi-tenant facilities in the Greater Dublin Area require scalable security architectures serving diverse client compliance profiles. These operators bundle physical security with power and cooling under single-master contracts, concentrating vendor accountability.
- Financial Institutions:Central Bank of Ireland oversight mandates granular access records tied to data-breach protocols. These end-users specify pre-certified compliance architectures and immutable blockchain-anchored audit trails.
- Enterprises:Single-tenant facilities prioritize integration with existing building automation systems.
- Government Agencies:National Cyber Security Centre guidance shapes procurement for critical infrastructure protection.
Colocation Providers anchor current revenue concentration; Financial Institutions drive premium technology adoption fastest.
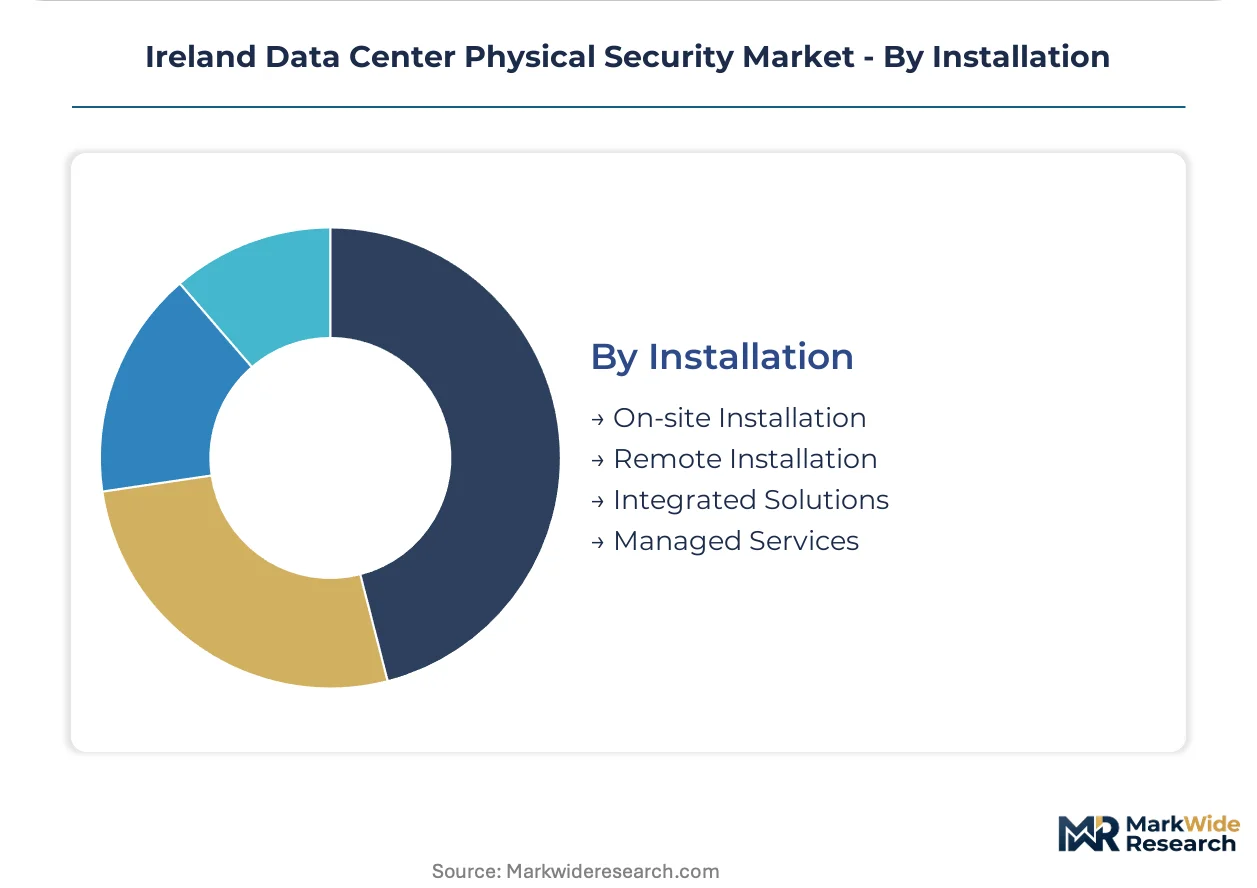
Installation:
Customer-type preferences split between capital-intensive ownership and operational expenditure models, with mid-tier operators shifting toward service-based procurement.
- Integrated Solutions:Unified command interfaces merging physical access, surveillance, and environmental monitoring displace standalone deployments. These installations dominate new hyperscale construction in Dublin's power-constrained grid.
- Managed Services:Security-as-a-service contracts with predictable opex structures attract mid-tier colocation operators seeking to avoid capital-heavy equipment purchases. Outcome-based pricing tied to uptime guarantees is gaining traction in Cork and Galway greenfield developments.
- On-site Installation:Traditional deployment model persists where facilities retain direct operational control.
- Remote Installation:Limited applicability in mission-critical environments requiring physical commissioning presence.
On-site Installation retains legacy dominance; Managed Services are expanding most quickly as procurement patterns shift toward operational expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center physical security procurement patterns diverge sharply between Ireland's power-constrained Greater Dublin Area and its emerging secondary markets, with compliance mandates and grid availability driving distinct technology deployment profiles across sub-regional clusters.
Greater Dublin Area
Hyperscale cloud operators concentrate security infrastructure spending in Dublin's western corridor, where Microsoft, Amazon, and Google operate major campuses. Ireland's Data Protection Commission enforces GDPR-mandated biometric logging for all Tier III and Tier IV facilities. Tallaght and Clondalkin host the densest colocation security deployments, with operators installing thermal-visible fusion cameras and sub-100-millisecond access control systems.
Cork
Apple's European headquarters anchors demand for integrated physical-cybersecurity platforms in Ireland's second-largest city. The National Cyber Security Centre's critical infrastructure guidance shapes procurement for financial services data centers locating outside Dublin's saturated grid. Little Island and Cork Docklands attract greenfield colocation developments seeking managed security service contracts with predictable opex structures.
Galway
Medtronic and Boston Scientific operations drive pharmaceutical-grade physical access requirements in this western hub. ISO 27001 certification pressures compel biometric systems with immutable blockchain-anchored audit trails. Oranmore and Ballybrit Industrial Estate concentrate new data center construction where AI-based edge analytics reduce latency for geographically distributed architectures.
Limerick
Dell Technologies' presence sustains enterprise data center security demand in Ireland's midwest region. The country's national data protection regulator treats unauthorized facility entry as a notifiable breach trigger across all counties. Castletroy and Raheen Industrial Estate host facilities prioritizing unified command interfaces that merge physical access with environmental monitoring.
Border Region
Strategic positioning for UK-EU data routing drives security investment in Dundalk and Drogheda. EU AI Act uncertainty over biometric surveillance classification creates procurement hesitation, delaying some technology roadmaps. These northeastern clusters attract operators seeking alternative locations to Dublin's power constraints while maintaining GDPR-aligned compliance architectures.
Ireland Data Center Physical Security Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Ireland's data center physical security market. Tier I vendors bundle power, cooling, and security infrastructure under unified platform architectures, while Tier II specialists compete on video analytics depth or biometric modality expertise. Strategic archetypes include energy-management heritage players leveraging electrical infrastructure relationships, building-automation integrators spanning thermal and access layers, and pure-play security technology vendors. Competitive moves center on single-master contract consolidation and security-as-a-service model expansion.
Within the integrated platform tier, Schneider Electric exemplifies the energy-management heritage archetype, Bosch Security Systems occupies a position among video-analytics specialists, and Johnson Controls anchors the building-automation convergence segment. These three companies represent distinct competitive vectors: bundled infrastructure provisioning, intelligent surveillance depth, and unified environmental-physical command interfaces respectively. Their market presence reflects how procurement consolidation among hyperscale and colocation operators rewards vendors capable of spanning multiple facility systems rather than delivering standalone security components.
| Leading Market Players |
|---|
| Schneider Electric |
| Bosch Security Systems |
| Johnson Controls |
| Cisco Systems |
| Securitas Technology |
| Honeywell International |
| Siemens AG |
| ABB Ltd |
| Axis Communications |
| Others |
Pricing and Supply Chain Analysis
Single-master contract consolidation among hyperscale operators locks in multi-year security infrastructure procurement at fixed pricing tiers, binding vendor margins to copper and semiconductor input trajectories while guaranteeing capacity allocation for Dublin-region deployments.
Pricing Analysis
After-sales service and managed security contracts drive lifetime value for integrated platform vendors serving Ireland's data center market. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales bundling depth. Cost compression in mid-tier RFID deployments is intensifying because copper cabling volatility inflates hardware margins. Mid-tier colocation operators exhibit highest price sensitivity, while financial institutions absorbing premium biometric systems show least elasticity.
Supply Chain Analysis
Strategic stockpiling of specialized edge-computing chipsets distinguishes hyperscale procurement from just-in-time preferences among smaller colocation operators. Supply concentrates in Germany, Netherlands, and China for biometric sensors, thermal camera modules, and IP networking equipment. Irish systems integrators draw from Taiwanese semiconductor foundries and German precision optics manufacturers. Single-source vulnerability in European platform software creates dependency risk. Distribution runs through certified systems integrators with IEC 62443 qualifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native security platforms threaten incumbent physical security vendors as hyperscale operators internalize surveillance and access control development, forcing traditional suppliers to defend integration value.
For Market Incumbents: Fortify platform stickiness by embedding blockchain-anchored audit trails that preempt GDPR compliance substitution from software-native competitors. Deepen backward integration into edge-computing hardware to offset semiconductor supply volatility. Anchor presence through building-automation convergence spanning thermal and physical access layers. For New Entrants and Emerging Players: Security-as-a-service gaps in Cork and Galway secondary markets offer white-space entry where incumbents under-serve mid-tier colocation operators. Target managed service contracts with outcome-based pricing structures. Pursue pharmaceutical data centers in Galway's Ballybrit Industrial Estate where ISO 27001 certification demands create premium procurement categories. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform vendors with security-as-a-service offerings, positioning them for durable cash flow across the projection horizon. Prioritize acquisition targets with pre-certified GDPR compliance architectures and established hyperscale relationships. Watch EU AI Act biometric surveillance classification decisions as inflection indicators for compliance cost recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Security-as-a-Service Expansion | Mid-tier colocation operators in Cork and Galway seek predictable opex structures over capital-heavy equipment purchases. |
| Biometric Compliance Certification | Pre-certified GDPR architectures from Ireland's Data Protection Commission accelerate procurement cycles for financial institutions. |
| Edge Analytics Integration | Machine-learning inference at network edge reduces alarm latency for Tier III and Tier IV facilities in Dublin's western corridor. |
| Secondary Market Geographic Expansion | Power-constrained Dublin grid pushes greenfield development toward Oranmore and Little Island with unified security requirements. |
| Physical-Cybersecurity Convergence | Identity-centric platforms unifying logical and physical credentialing capture pharmaceutical and financial services procurement. |
Research Methodology
Cross-validation between primary interviews with data center security directors and secondary validation through regulatory filings anchors the qualitative findings in this study. Stakeholder consultations spanned facility security managers at hyperscale operators, procurement leads at colocation providers, systems integration specialists, and compliance officers at financial institutions. Secondary sources included Ireland's Data Protection Commission enforcement notices, National Cyber Security Centre guidance documents, ISO 27001 certification databases, and EU AI Act draft provisions. Bottom-up installation tracking and top-down market sizing triangulate volume estimates.
Sensitivity analysis across input cost scenarios and regulatory timing variations stress-tests projection robustness across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user category, installation approach, and regional cluster. CAGRs derive from fitted growth curves applied to verified base-year estimates. Forecast inputs incorporate hyperscale capex disclosure patterns and GDPR enforcement trajectory assumptions.
Underlying assumptions cover copper and semiconductor price stability, EU AI Act classification timelines, and hyperscale expansion continuity, with deviation risk concentrated in supply chain volatility and regulatory delay scenarios. Revision becomes warranted when biometric surveillance restrictions cross implementation thresholds or grid capacity constraints accelerate beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Switzerland Data Center Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Server Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Jakarta Data Center Market