
 United States Data Center Server Market | 2026-2036
United States Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
United States Data Center Server Market Insights
Accelerated computing architectures is tilting server design toward GPU-dense configurations optimized for AI inference and training workloads. Dell Technologies anchors the enterprise segment through direct-to-customer channel control and extensive service integration. Super Micro Computer specializes in high-density, liquid-cooled rack systems that reduce power usage effectiveness for hyperscale operators. Hewlett Packard Enterprise extends its position via composable infrastructure software that disaggregates compute, storage, and networking resources across hybrid environments.
Data center servers are enterprise-grade computing platforms built on x86, ARM, or custom ASIC processor architectures, typically housed in standardized 19-inch rack enclosures with redundant power supplies and hot-swappable components, designed to process, store, and distribute digital workloads across networked environments. Blade servers are gaining structural prominence in AI training clusters where space and thermal constraints favor shared chassis infrastructure over discrete rack units. Cloud-based deployment models are expanding fastest among mid-market enterprises that lack capital for on-premises infrastructure refresh cycles. Rack servers retain the largest installed base in colocation facilities across Northern Virginia and Dallas-Fort Worth, where lease structures favor tenant-owned equipment over hyperscale buildouts.
NIST cybersecurity frameworks and EPA Energy Star server specifications shape procurement standards for federal agencies and energy-conscious enterprises, while OSHA electrical safety regulations govern installation protocols in multi-tenant data center environments. The FCC's broadband infrastructure programs indirectly stimulate edge server demand by subsidizing network buildouts that require distributed compute nodes. Stakeholders must weigh liquid cooling retrofits against new construction as power densities exceed 50 kilowatts per rack in primary markets.
Market Dynamics
The CHIPS and Science Act is redirecting domestic semiconductor fabrication toward server-grade silicon, compressing procurement timelines for hyperscale operators while elevating capital intensity across the supply base.
Growth Catalysts
- AI Training Cluster Expansion:Hyperscale cloud providers are scaling GPU-dense rack deployments across Virginia, Texas, and Arizona to support generative model development. This concentration is pulling advanced liquid-cooled architectures into mainstream procurement cycles.
- CHIPS Act Domestic Incentives:Federal subsidies for onshore advanced packaging and wafer fabrication are shortening lead times for custom ASIC server processors. Domestic foundry capacity is reducing dependency on East Asian supply chains for mission-critical components.
- Edge Computing Federal Subsidies:FCC broadband infrastructure programs are funding distributed compute node deployment in underserved counties. Edge server demand is accelerating where fiber backhaul investments require localized processing capacity.
Market Restraints
- Neon Gas Supply Concentration:Ukrainian and Russian neon purification facilities supply over half of global semiconductor-grade neon, creating vulnerability in excimer laser lithography for server processor manufacturing.
- Power Density Physical Limits:Air-cooled rack architectures face thermal dissipation ceilings below 30 kilowatts per rack, forcing premature infrastructure obsolescence in legacy colocation facilities.
- OSHA Electrical Safety Compliance:Multi-tenant data center installation protocols require certified electricians for hot-work permits, extending deployment timelines and labor costs in Northern Virginia and Dallas-Fort Worth corridors.
Strategic Opportunities
- Direct Liquid Cooling Retrofit Services:Existing colocation facilities in Ashburn and Phoenix are engaging engineering firms to upgrade legacy air-handling infrastructure. Retrofit contracts capture margin pools unavailable in commodity server sales.
- Composable Infrastructure Software:Disaggregated resource orchestration enables hybrid cloud portability across on-premises and hyperscale environments. Mid-market enterprises lacking capital for full refresh cycles represent underserved demand.
- EPA Energy Star Server Specifications:Federal procurement mandates are tilting agency RFPs toward certified efficient configurations. Compliance consulting and pre-certified product lines capture public-sector wallet share.
Industry Challenges
- Thermal Engineering Talent Scarcity:Liquid cooling system design requires specialized fluid dynamics expertise absent from traditional HVAC training pipelines. Certification programs at Arizona State University and Virginia Tech are insufficient to meet demand.
- Legacy x86 Application Compatibility:ARM-based server migrations face software porting costs and performance validation cycles that delay procurement decisions in financial services and healthcare verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Data Center Server Market |
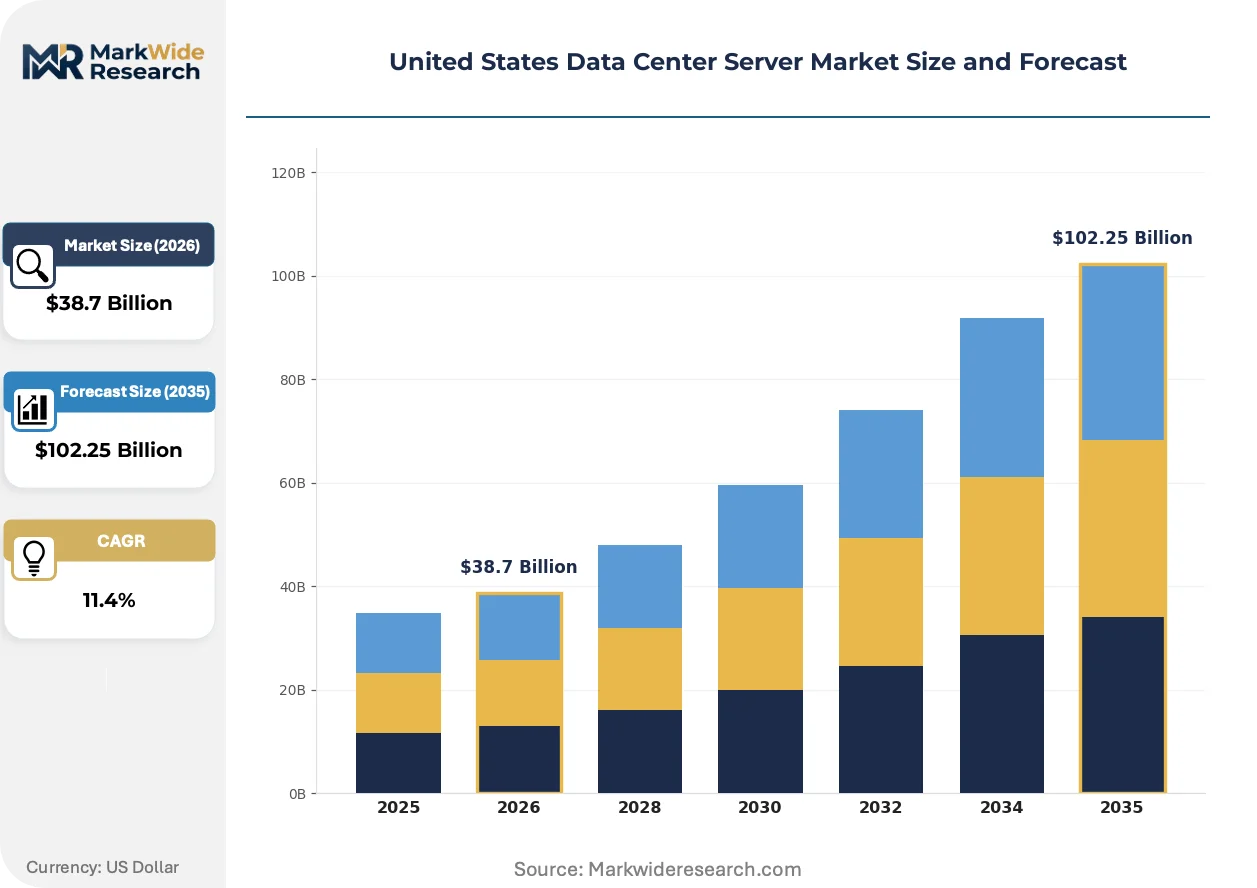
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Modular Servers Deployment Model: On-Premises, Colocation, Cloud-Based, Hybrid End User: SMEs, Large Enterprises, Government, Educational Institutions Service Type: Maintenance, Integration, Upgrades, Support |
| Companies Covered | International Business Machines Corporation, Super Micro Computer, Dell Technologies, Inspur Electronic Information Industry, Quanta Computer, Hewlett Packard Enterprise, Cisco Systems, Amazon Web Services, Lenovo Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Data Center Server Market Trends and Innovations
Server architecture is bifurcating between AI-optimized GPU clusters and efficiency-focused general-purpose platforms, with thermal management and software-defined disaggregation emerging as the decisive design axes.
Liquid cooling infrastructure is migrating from experimental hyperscale deployments to enterprise refresh standards. Direct-to-chip cold plate systems now dissipate over 50 kilowatts per rack in AI training environments. Dell Technologies and Super Micro Computer are integrating factory-installed liquid cooling into mainstream rack server SKUs. This migration is compressing the addressable market for traditional air-handling equipment suppliers and elevating fluid dynamics engineering to core competency status.
EPA Energy Star server specifications and NIST cybersecurity frameworks are tightening procurement gatekeeping for federal agencies and regulated industries. Compliance documentation now extends to supply chain provenance and firmware attestation. Defense contractors and healthcare systems are prioritizing pre-certified configurations to accelerate security authorization timelines. This regulatory layering is fragmenting vendor qualification pools and elevating compliance engineering overhead.
Colocation customers are unbundling server procurement from facility leases, purchasing tenant-owned equipment while negotiating power-density-based pricing. Wholesale data center operators in Northern Virginia are responding with metered liquid cooling service tiers. This behavioral shift is transferring capital burden from operators to end-users while creating recurring service revenue streams for thermal management monitoring. The pattern is most pronounced among SaaS providers with variable compute loads and limited balance sheet capacity for infrastructure ownership.
United States Data Center Server Market Segmentation
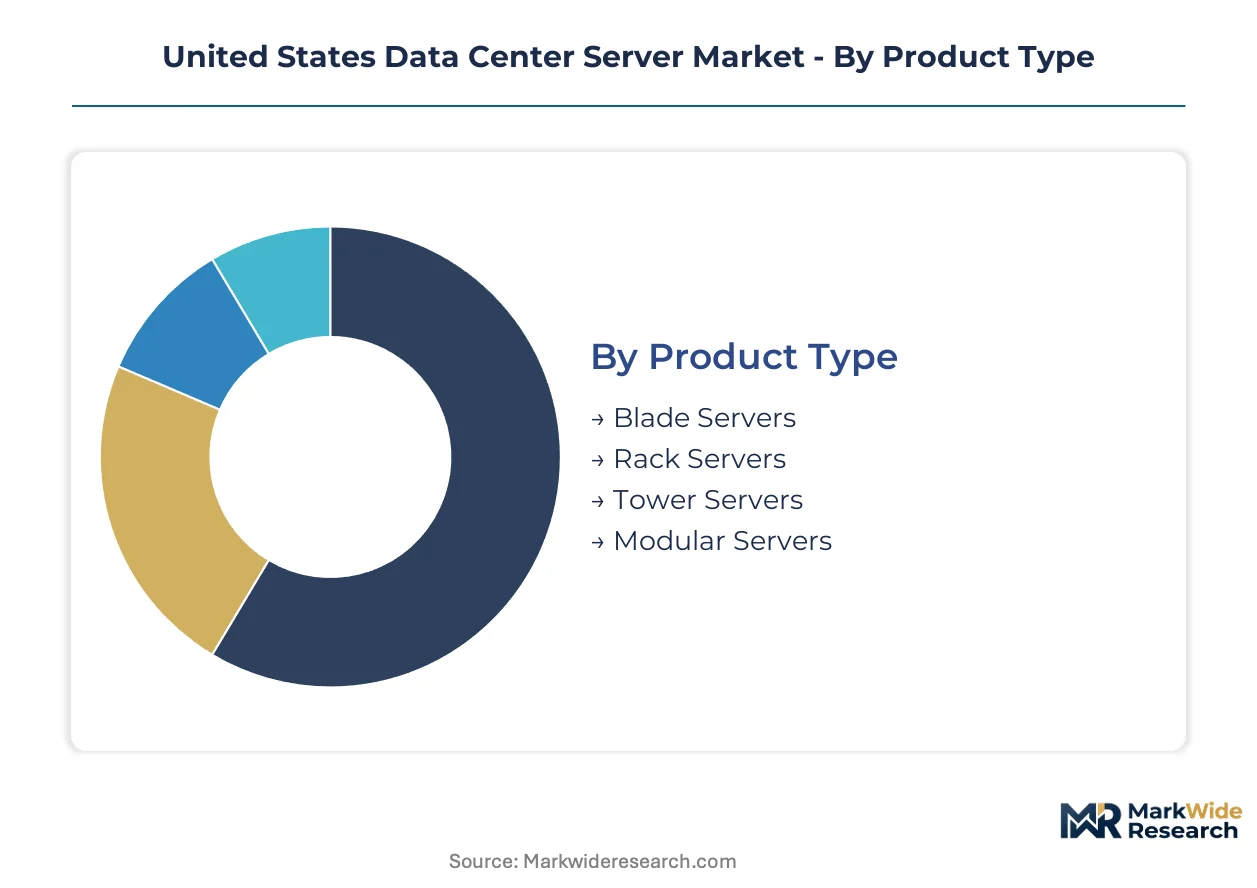
Server procurement cycles vary dramatically across form factors and deployment modes, with AI training clusters driving 18-month refresh intervals while legacy enterprise workloads extend to five-year cycles. Understanding these velocity differentials helps vendors align inventory, service contracts, and thermal engineering resources to where replacement demand concentrates.
Product Type:
Blade servers turn over fastest in hyperscale environments where GPU density requirements outpace chassis capacity, while tower servers in remote edge locations persist longest due to limited on-site technical staff.
- Rack Servers:Standardized 19-inch enclosures house x86 and ARM processors with redundant power and hot-swappable storage. Northern Virginia's Ashburn corridor and Dallas-Fort Worth colocation facilities anchor demand, where tenant-owned equipment models favor discrete rack units over shared infrastructure.
- Blade Servers:Shared chassis architectures consolidate compute, networking, and storage into high-density sleds. AI training clusters across Phoenix and Austin are pulling liquid-cooled blade configurations into mainstream procurement as power densities exceed 50 kilowatts per rack.
- Tower Servers:Vertical standalone units serve branch offices and edge locations lacking raised-floor facilities. Rural broadband expansion under FCC infrastructure programs is stimulating deployment in county government offices and agricultural processing sites.
- Modular Servers:Disaggregated chassis designs enable independent scaling of compute and storage resources. Federal agencies pursuing NIST cybersecurity compliance are evaluating modular architectures for segmented workload isolation.
Rack servers dominate installed base across colocation and enterprise data centers. Blade servers are where expansion concentrates as hyperscale operators reconfigure for AI training densities.
Deployment Model:
Capital availability and workload predictability determine whether organizations own infrastructure, lease capacity, or consume compute as a service.
- On-Premises:Enterprises retain full ownership of server hardware within corporate facilities. Financial services firms in New York and Chicago maintain on-premises deployments for regulatory data sovereignty despite higher capital intensity.
- Colocation:Tenants procure dedicated servers housed in third-party facilities with shared power and cooling infrastructure. Northern Virginia operators are introducing metered liquid cooling tiers as customers unbundle server ownership from facility leases.
- Cloud-Based:Hyperscale providers own and operate server infrastructure consumed via subscription models. Mid-market SaaS vendors in Austin and Denver are migrating variable workloads to cloud-based deployment to preserve balance sheet capacity.
- Hybrid:Orchestrated workloads span on-premises and cloud environments with policy-driven placement. Healthcare systems facing HIPAA compliance requirements are adopting hybrid models to segregate protected health information from public cloud resources.
On-premises retains the largest installed base among regulated industries. Cloud-based deployment is climbing the fastest as capital-constrained enterprises defer infrastructure ownership.
End User:
Budget scale and procurement authority shape whether server acquisitions flow through centralized IT, specialized agencies, or departmental budgets.
- Large Enterprises:Fortune 500 technology and financial services firms operate dedicated procurement teams with direct vendor relationships. These organizations negotiate custom configurations and multi-year service agreements for data center refresh cycles.
- SMEs:Small and medium enterprises lack capital for on-premises infrastructure and rely on channel partners for pre-configured systems. Cloud-based consumption models are displacing direct server purchases in this segment.
- Government:Federal, state, and local agencies follow EPA Energy Star and NIST cybersecurity specifications in competitive procurement processes. Defense contractors prioritize pre-certified configurations to accelerate security authorization timelines.
- Educational Institutions:Universities and research laboratories deploy servers for computational research and campus IT services. NSF-funded research clusters at Arizona State University and Virginia Tech are driving GPU-dense rack procurement.
Large enterprises dominate server procurement volume. Government represents the steepest expansion trajectory as federal infrastructure modernization programs accelerate.
Service Type:
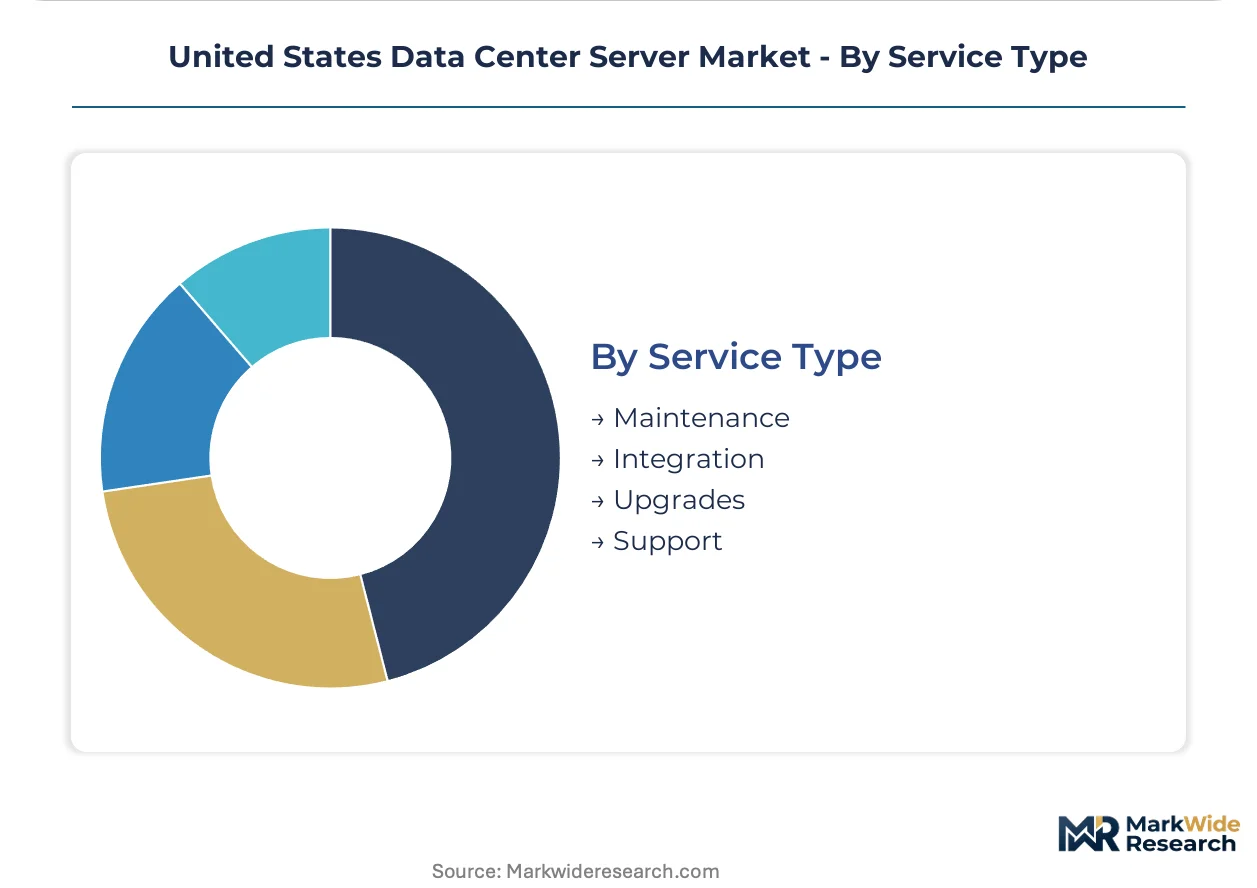
Revenue attachment rates vary from break-fix maintenance to comprehensive lifecycle management, with liquid cooling retrofits creating new service categories.
- Maintenance:Preventive and corrective service contracts cover hardware replacement and firmware updates. Colocation customers in Phoenix are extending maintenance terms to defer capital expenditure on new server acquisitions.
- Integration:Professional services for rack assembly, network cabling, and software provisioning. OSHA electrical safety regulations require certified electricians for hot-work permits in multi-tenant facilities, extending integration timelines.
- Upgrades:Processor, memory, and storage refresh within existing chassis. Direct liquid cooling retrofits are emerging as a specialized upgrade category for legacy air-cooled facilities exceeding thermal limits.
- Support:Technical assistance and remote monitoring services. Hyperscale operators are outsourcing Tier 1 support to capture operational expenditure efficiencies.
Maintenance captures the largest service revenue pool. Upgrades are gaining share fastest as power density constraints force thermal infrastructure reinvestment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud providers and AI training clusters concentrate server procurement in specific metropolitan corridors where power availability and fiber density align. Virginia, Texas, and Arizona anchor domestic demand expansion.
Virginia
Data center operators in Loudoun and Prince William counties consume server capacity for cloud and AI training workloads. Virginia's data center sales and use tax exemption program sustains facility investment despite land constraints. Ashburn's "Data Center Alley" hosts the densest concentration of colocation and hyperscale buildouts in the United States.
Texas
Austin and Dallas-Fort Worth metro areas attract GPU-dense cluster deployments from cloud providers and autonomous vehicle developers. ERCOT grid interconnection rules and property tax abatements for large power users reduce operational cost exposure. Dallas-Fort Worth colocation facilities report accelerating tenant-owned server procurement for AI inference workloads.
Arizona
Phoenix and Mesa data center corridors absorb server shipments for hyperscale expansion and enterprise disaster recovery. Arizona's renewable energy tax credits and water-efficient cooling regulations favor liquid-cooled architectures. Phoenix operators are retrofitting legacy air-handling infrastructure to support 50+ kilowatt rack densities.
California
Silicon Valley and Sacramento Valley facilities serve enterprise R&D and media rendering workloads with stringent latency requirements. California's Title 24 building energy efficiency standards and SB 100 renewable procurement mandates elevate capital costs for new server deployments. Sacramento's proximity to hydroelectric generation attracts power-intensive training clusters.
Illinois
Chicago metro colocation providers serve financial services and healthcare enterprises with regulatory data sovereignty requirements. Illinois data center tax incentives and Commonwealth Edison rate structures support enterprise-owned server retention. Downtown Chicago facilities specialize in low-latency trading infrastructure with sub-millisecond connectivity to financial exchanges.
United States Data Center Server Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The market structure consolidates around vertically integrated systems vendors and modular component suppliers serving distinct buyer archetypes. Three strategic archetypes dominate: direct-channel enterprise vendors, high-density thermal specialists, and cloud-native hardware designers. Competitive moves center on liquid cooling technology licensing and composable infrastructure software partnerships.
Within the enterprise systems tier, Dell Technologies and Hewlett Packard Enterprise exemplify channel-controlling archetypes with extensive service integration. Super Micro Computer occupies a specialist position in high-density, liquid-cooled rack configurations. These three anchors represent divergent approaches to thermal engineering and deployment model flexibility.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Super Micro Computer |
| Dell Technologies |
| Inspur Electronic Information Industry |
| Quanta Computer |
| Hewlett Packard Enterprise |
| Cisco Systems |
| Amazon Web Services |
| Lenovo Group |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Taiwanese advanced packaging facilities is compressing foundry margins and tilting server processor pricing toward buyers, while simultaneously accelerating domestic fab investment under CHIPS Act incentives that reshape procurement timelines for hyperscale operators.
Pricing Analysis
Cost-plus contracts indexed to silicon wafer spot prices dominate procurement for custom ASIC server processors, with hyperscale cloud providers leveraging volume scale to secure fixed-price multi-year offtakes. Price differentiation separates liquid-cooled GPU-dense configurations from air-cooled general-purpose racks, with EPA Energy Star certification commanding modest premiums in federal agency RFPs. Pricing pressure stems from ARM-based alternatives displacing legacy x86 sockets in enterprise refresh cycles. Mid-market SMEs exhibit highest price sensitivity, deferring on-premises acquisitions for cloud-based consumption models.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for server motherboard and power supply assemblies. Manufacturing concentrates in Taiwan, South Korea, and China for advanced logic processors, memory modules, and passive components. Neon gas purification from Ukrainian and Russian facilities feeds excimer laser lithography, creating single-source vulnerability for semiconductor-grade inputs. Distribution runs through direct OEM channels for enterprise accounts and value-added resellers serving SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Data Center Server Market is undergoing high-growth disruption as AI training clusters force 18-month refresh cycles against traditional five-year enterprise baselines, with liquid cooling infrastructure emerging as the decisive capital allocation pivot.
For Market Incumbents: Insulate rack server margin pools by backward integration into liquid cooling component manufacturing, capturing retrofit service revenue as legacy colocation facilities exceed thermal limits. Prioritize NIST cybersecurity pre-certification to accelerate federal agency procurement timelines against emerging ARM-based competitors. For New Entrants and Emerging Players: Pursue direct liquid cooling engineering contracts in Phoenix and Ashburn corridors where legacy air-handling infrastructure requires urgent thermal upgrades. Target mid-market hybrid cloud orchestration software as the most penetrable segment, offering composable infrastructure management without capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GPU-dense AI training clusters as power densities exceed 50 kilowatts per rack and require specialized fluid dynamics expertise. Acquisition candidates with thermal engineering capabilities and established relationships with hyperscale cloud providers present strongest long-term viability. The signal to watch is foundry utilization rates at domestic CHIPS Act subsidized facilities as indicator of supply security premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Licensing | Enables legacy colocation operators in Northern Virginia to capture 50+ kilowatt rack densities without new construction. |
| Composable Infrastructure Software Partnership | Accelerates hybrid cloud portability for healthcare systems facing HIPAA compliance requirements. |
| Direct-to-Chip Cold Plate Manufacturing Scale-Up | Positions suppliers for factory-installed integration by Dell Technologies and Super Micro Computer. |
| EPA Energy Star Pre-Certification Program | Captures federal agency wallet share under mandated procurement specifications. |
| Thermal Engineering Talent Pipeline Development | Addresses scarcity of fluid dynamics expertise through Arizona State University and Virginia Tech partnerships. |
Research Methodology
A spread of perspectives from hyperscale cloud procurement officers, colocation facility operators, thermal engineering firms, and semiconductor supply chain managers converged on the working assumptions that underpin this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, hyperscaler capex disclosures, and FCC broadband infrastructure program documentation. Bottom-up server shipment estimates triangulated against top-down data center power consumption projections.
Demand-supply balance modeling anchored the forecast framework across the analysis window, with segmentation by form factor, deployment model, and end-user vertical informing volume trajectories. CAGRs were derived from replacement cycle velocity differentials between AI training clusters and legacy enterprise workloads. Key inputs included foundry capacity expansion timelines under CHIPS Act incentives and edge computing node deployment rates under FCC subsidy programs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting hyperscaler capital allocation or federal infrastructure appropriations would shift the trajectory. Forecasts reflect documented assumptions regarding domestic foundry yield ramps and neon gas supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Managed IT Infrastructure Services Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Canada Data Center Storage Market