
 United States Metal Cans Market | 2026-2036
United States Metal Cans Market Size, Share, and Industry Trends Forecast 2026-2036
United States Metal Cans Market Analytics
Lightweight aluminum alloy formulation is reshaping canbody gauge reduction across the United States packaging sector. Ball Corporation leverages its captive recycling infrastructure to secure prime aluminum access at scale. Crown Holdings Inc. anchors its position through deep relationships with Coca-Cola and PepsiCo bottling networks. Silgan Holdings Inc. specializes in steel food cans, where its three-piece seaming technology sustains cost advantages in vegetable and soup processing channels.
Metal cans are cylindrical containers fabricated from aluminum or tinplate steel, typically ranging from 0.097 mm to 0.407 mm in wall thickness, engineered to provide hermetic sealing, light exclusion, and stackable logistics for shelf-stable goods. Beverage cans command the dominant product type position as aluminum's infinite recyclability aligns with brand sustainability commitments, while specialty cans represent the fastest-growing category as aerosol and shaped formats penetrate personal care and premium spirits. Food processors remain the most volume-intensive end user segment, though margin pools concentrate with chemical suppliers demanding corrosion-resistant linings for solvent and coating products.
The FDA governs indirect food additive migrations under 21 CFR 175.300, while EPA enforcement of hazardous waste rules shapes can coating chemistries and facility siting decisions. OSHA's permissible exposure limits for hexavalent chromium drive capital allocation toward water-based and powder coating conversions. Stakeholders must monitor state-level extended producer responsibility expansions beyond California, as Illinois and New York legislatures advance similar frameworks that would reshape collection infrastructure economics and recycled content verification requirements.
Market Dynamics
California's SB 54 extended producer responsibility law is forcing beverage and food processors to re-engineer collection infrastructure and lightweight can designs ahead of compliance deadlines. This regulatory pressure compounds with FDA food-contact substance notification requirements to reshape capital allocation across the Midwest manufacturing belt.
Growth Catalysts
- Aluminum alloy lightweighting:Beverage canbody gauge reduction below 0.097 mm enables material cost savings and transport efficiency gains. Sparkling water and craft beer producers accelerate format conversion from glass.
- SB 54 compliance timelines:California's extended producer responsibility mandates drive investment in closed-loop recycling systems and post-consumer content verification protocols.
- Midwest cluster density:Ohio, Indiana, and Illinois host concentrated canmaking and filling operations that minimize logistics friction between sheet rolling and beverage bottling.
Market Restraints
- Prime aluminum supply concentration:Domestic smelter capacity constraints and import dependence create input cost volatility for canbody sheet producers.
- Hexavalent chromium coating phaseout:OSHA permissible exposure limits force capital-intensive conversions to water-based and powder coating chemistries at existing facilities.
- Steel food can substitution pressure:Flexible pouch formats and aseptic carton technologies displace three-piece steel cans in vegetable and soup processing channels.
Strategic Opportunities
- Aerosol and shaped specialty formats:Personal care and premium spirits applications represent underpenetrated white space for aluminum extrusion and necking innovations.
- Illinois and New York EPR expansion:Proposed extended producer responsibility frameworks would extend California-style collection infrastructure economics to additional state markets.
- Chemical can corrosion-resistant linings:Solvent and coating product suppliers demand upgraded epoxy phenolic and vinyl organosol formulations that command premium positioning.
Industry Challenges
- Water-based coating line conversions:Legacy solvent-based coating infrastructure requires extended downtime and specialized technician training for EPA hazardous waste rule compliance.
- Post-consumer scrap sorting purity:Mixed-waste collection systems contaminate aluminum streams with steel and plastic, degrading closed-loop recycling economics for can-to-can remelting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Metal Cans Market |
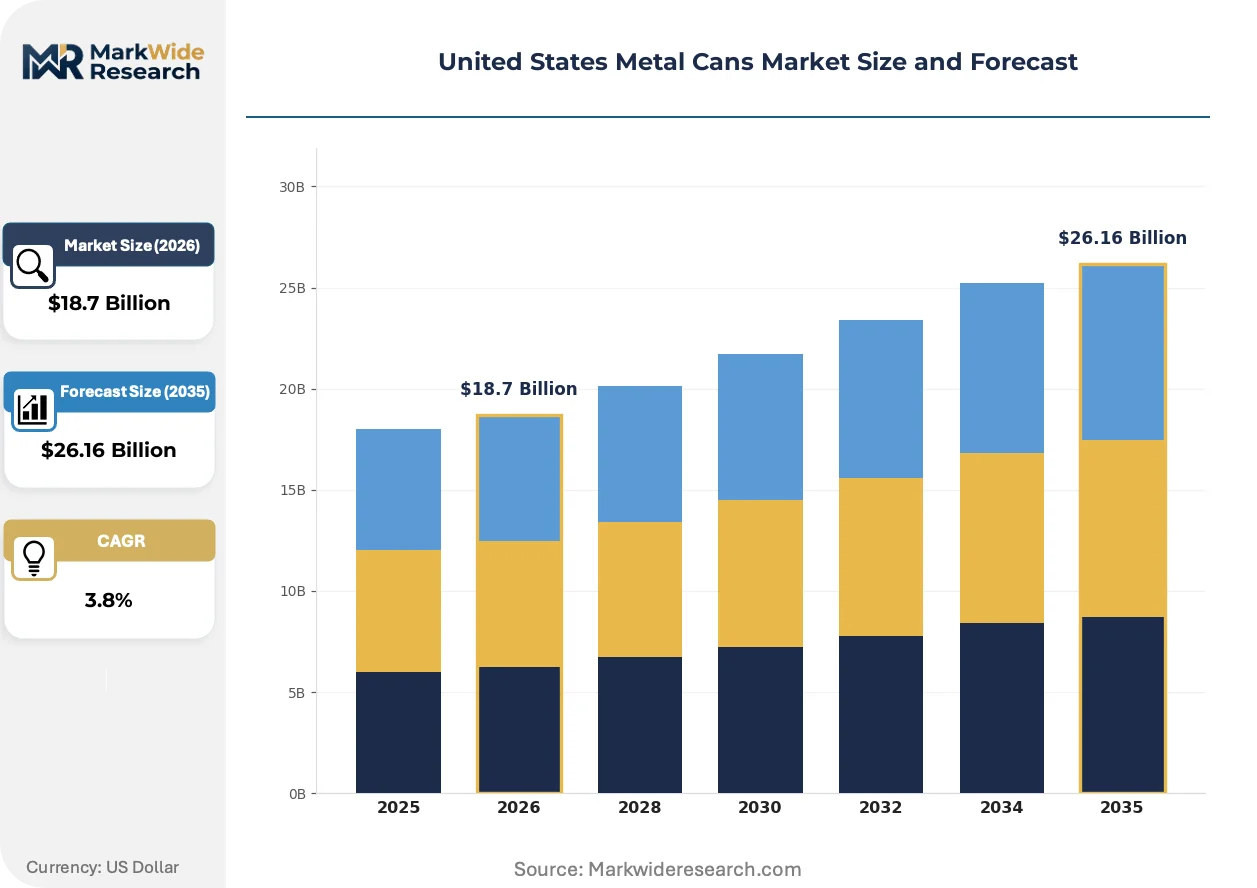
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Specialty Cans, Beverage Cans End User: Beverage Manufacturers, Food Processors, Chemical Suppliers, Household Products Size: Small Cans, Medium Cans, Large Cans, Extra Large Cans Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Wholesalers |
| Companies Covered | Crown Holdings Inc., Ball Corporation, Silgan Holdings Inc., Ardagh Metal Packaging S.A., CAN-PACK S.A., Mauser Packaging Solutions, Envases Group, Trivium Packaging, CCL Container, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Metal Cans Market Evolving Landscape
Active and intelligent packaging integration is reshaping how beverage brands differentiate shelf presence and supply chain transparency. These developments span material science, regulatory compliance architecture, and procurement behavior.
Digital printing on aluminum can surfaces is migrating from rotary offset to direct-to-shape inkjet systems. Craft beer and premium spirits producers adopt variable-data decoration for limited-run releases and regional marketing campaigns. This technology is migrating from niche premium positioning toward mid-volume sparkling water and ready-to-drink cocktail segments.
FDA's updated food-contact substance notification requirements under 21 CFR 175.300 are compressing coating chemistry approval timelines. Epoxy-based internal linings face heightened scrutiny for bisphenol migration thresholds. Vegetable and soup processors in the Midwest are accelerating vinyl organosol and polyester-amide alternative validations to maintain shelf-stable product registrations.
Beverage brand procurement teams are consolidating supplier relationships around vertically integrated aluminum recyclers. Long-term offtake agreements with captive recycling infrastructure operators are replacing spot-market prime aluminum purchases. This concentration is most visible among Coca-Cola and PepsiCo bottling networks in Ohio and Indiana, where logistics integration with canmaking facilities reduces working capital requirements.
United States Metal Cans Market Segmentation
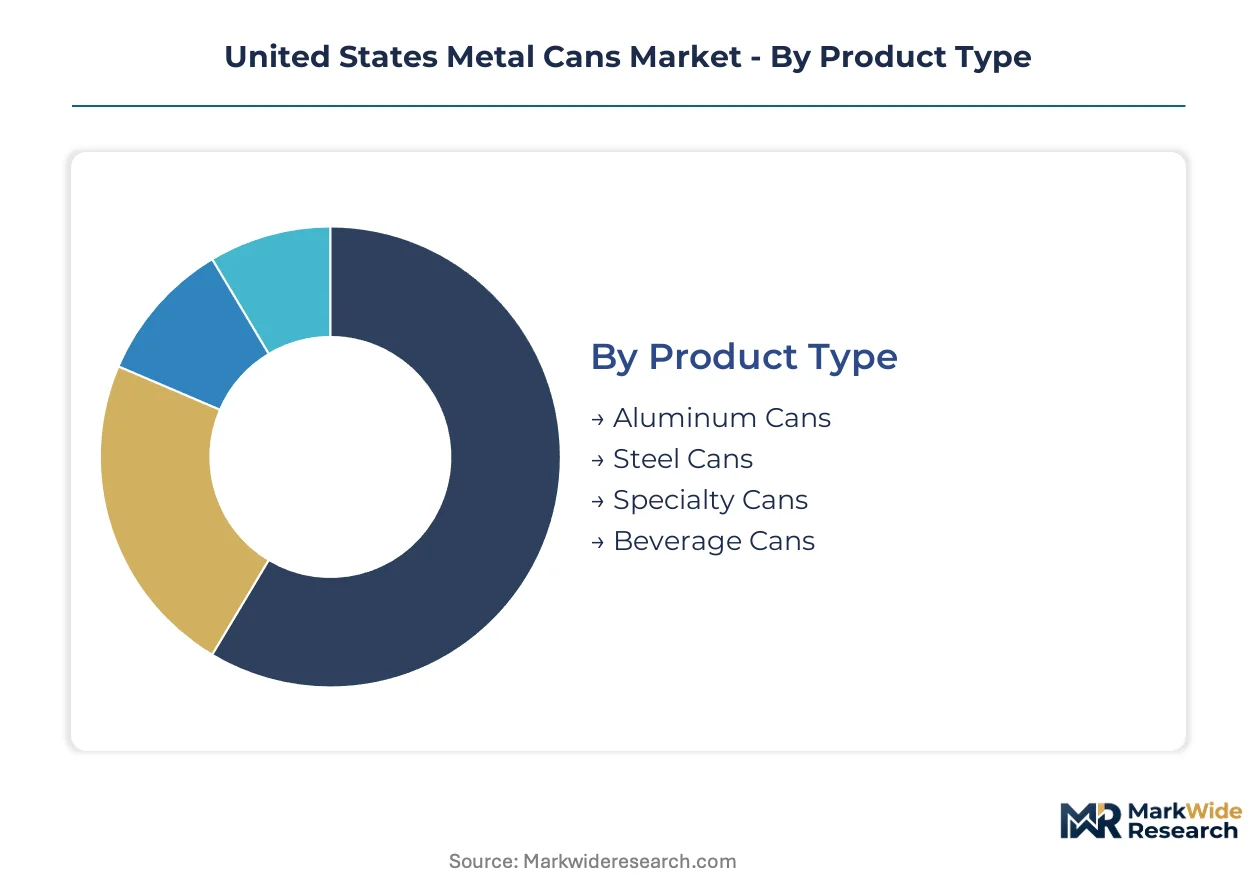
Segmentation in the United States metal cans market reveals how material specifications, end-use requirements, and logistics configurations create distinct competitive arenas. Each dimension carries unique margin profiles and capital intensity thresholds that reshape supplier positioning across the Midwest manufacturing belt.
Product Type:
Material composition and fabrication method separate product tiers by cost structure and recyclability economics.
- Aluminum Cans:Fabricated from 3104-H19 alloy sheet with wall thickness ranging 0.097 mm to 0.407 mm. Beverage bottlers in Ohio and Indiana concentrate procurement around captive recycling infrastructure operators to secure prime aluminum access at scale.
- Beverage Cans:Two-piece drawn-and-wall-ironed construction dominates carbonated soft drinks, sparkling water, and craft beer. California SB 54 compliance timelines accelerate lightweighting investments below 0.097 mm gauge for transport efficiency gains.
- Steel Cans:Three-piece tinplate construction sustains cost advantages in shelf-stable food applications where hermetic sealing tolerances exceed aluminum economics.
- Specialty Cans:Aerosol and shaped formats penetrate personal care and premium spirits channels through extrusion and necking innovations.
Aluminum Cans command the established base. The steepest expansion runs through Specialty Cans.
End User:
Customer type determines coating chemistry requirements, volume predictability, and contract duration structures.
- Beverage Manufacturers:Sparkling water and craft beer producers drive format conversion from glass to aluminum. Long-term offtake agreements with vertically integrated recyclers replace spot-market prime aluminum purchases across Coca-Cola and PepsiCo bottling networks.
- Food Processors:Vegetable and soup processing channels in the Midwest sustain three-piece steel can demand despite flexible pouch substitution pressure. FDA 21 CFR 175.300 compliance accelerates vinyl organosol and polyester-amide lining validations.
- Chemical Suppliers:Solvent and coating product suppliers demand corrosion-resistant epoxy phenolic linings that command premium positioning.
- Household Products:Aerosol propellant compatibility requirements shape canbody specifications for cleaning and personal care applications.
Beverage Manufacturers anchor volume concentration. Food Processors face the steepest margin compression from format substitution.
Size:
Dimensional specifications correlate with end-use consumption patterns and logistics optimization thresholds.
- Small Cans:Single-serve beverage and personal care formats dominate. Craft beer limited-run releases and regional marketing campaigns drive variable-data decoration demand.
- Medium Cans:Standard 12-ounce beverage specifications concentrate procurement volumes across Midwest filling operations.
- Large Cans:Food service and institutional channels for vegetable and soup products sustain steel can economics.
- Extra Large Cans:Industrial chemical and coating product containment requires specialized corrosion-resistant lining formulations.
Medium Cans capture the volume core. Small Cans gain share fastest through premium positioning and digital printing adoption.
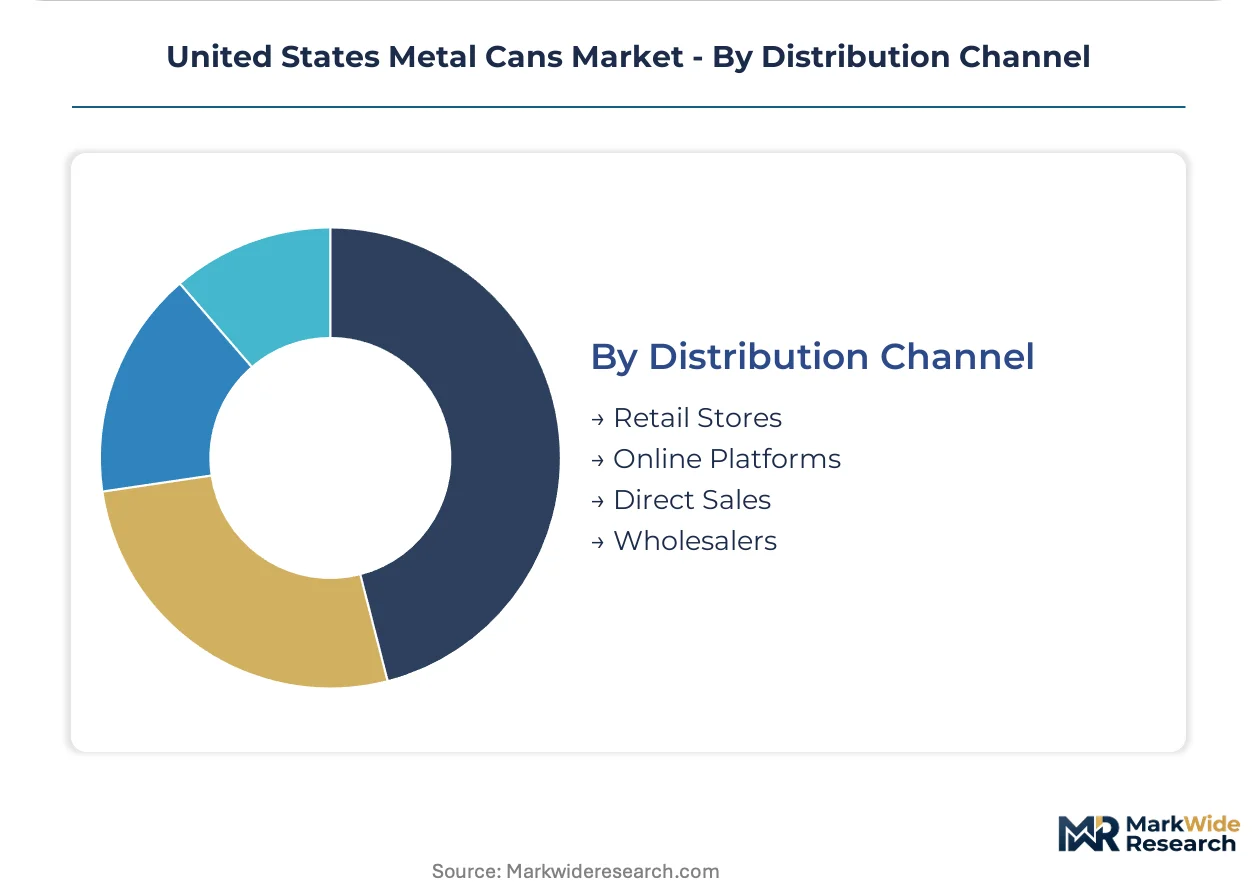
Distribution Channel:
Channel structure determines working capital requirements and inventory velocity constraints for canmakers.
- Retail Stores:Mass merchandisers and convenience chains consolidate procurement around direct supplier relationships with canmaking facilities in Ohio, Indiana, and Illinois.
- Direct Sales:Beverage bottling networks leverage logistics integration with adjacent canmaking plants to minimize transport friction between sheet rolling and filling operations.
- Wholesalers:Regional distributors serve smaller food processors and household product manufacturers with fragmented volume profiles.
- Online Platforms:Emerging procurement channel for specialty and limited-run formats where variable-data decoration supports direct-to-consumer brand strategies.
Retail Stores and Direct Sales concentrate volume. Online Platforms climb fastest as craft and premium segments expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian aluminum sheet exports flow primarily into Ohio and Indiana beverage can manufacturing corridors, where Midwest filling operations convert imported coil into two-piece containers for Coca-Cola and PepsiCo bottling networks.
Midwest Manufacturing Belt
Ohio, Indiana, and Illinois host the densest concentration of canmaking and filling operations in the United States. Beverage bottlers in these states leverage logistics integration with adjacent aluminum rolling mills to minimize transport friction between sheet production and container fabrication. California's SB 54 extended producer responsibility mandates are forcing Midwest processors to re-engineer lightweight can designs for compliance. Cleveland and Chicago anchor the regional supply chain, where Ball Corporation and Crown Holdings operate integrated facilities serving sparkling water and craft beer producers converting from glass formats.
Southeast
Florida and Georgia beverage markets are expanding aluminum can demand through sparkling water regional distribution centers. The EPA's hazardous waste enforcement rules are driving coating chemistry conversions at legacy solvent-based facilities in Atlanta and Tampa. Charlotte and Miami serve as logistics hubs connecting Midwest sheet production to Latin American export markets, with canmaking operations concentrating near Port Everglades and Savannah port infrastructure.
California
The state's SB 54 extended producer responsibility law imposes the strictest collection infrastructure requirements on beverage and food processors nationwide. California's food-contact substance notification protocols under FDA 21 CFR 175.300 are accelerating vinyl organosol and polyester-amide lining validations for vegetable and soup processors. Los Angeles and San Francisco Bay Area facilities are investing in closed-loop recycling systems and post-consumer content verification protocols ahead of compliance deadlines.
Pacific Northwest
Oregon and Washington craft beer producers are driving specialty can format demand through limited-run releases and regional marketing campaigns. OSHA's permissible exposure limits for hexavalent chromium are forcing capital-intensive coating line conversions at Portland and Seattle-area facilities. The region's aluminum smelter heritage provides legacy technical workforce capacity for advanced alloy formulation and gauge reduction below 0.097 mm.
Southwest
Texas chemical suppliers demand corrosion-resistant epoxy phenolic linings for solvent and coating product containment in industrial-scale aluminum containers. The state's permissive regulatory environment for manufacturing siting attracts canmaking capacity expansion from Midwest operators seeking labor cost arbitrage. Houston and Dallas-Fort Worth serve as distribution nodes for aerosol and shaped specialty formats penetrating personal care and premium spirits channels.
United States Metal Cans Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated aluminum recyclers with captive sheet production capacity. Three strategic archetypes dominate competitive positioning: beverage-focused alloy lightweighting specialists, steel food can cost leaders, and specialty format innovators. M&A activity concentrates on recycling infrastructure acquisitions, while capacity expansion targets Midwest logistics corridors adjacent to Coca-Cola and PepsiCo bottling networks.
Among United States-based operators, Ball Corporation exemplifies the vertically integrated recycler archetype through captive aluminum access at scale. Crown Holdings Inc. anchors the beverage can segment with deep bottling network relationships across Ohio and Indiana. Silgan Holdings Inc. occupies the steel food can specialist position, sustaining cost advantages in vegetable and soup processing channels through three-piece seaming technology.
| Leading Market Players |
|---|
| Crown Holdings Inc. |
| Ball Corporation |
| Silgan Holdings Inc. |
| Ardagh Metal Packaging S.A. |
| CAN-PACK S.A. |
| Mauser Packaging Solutions |
| Envases Group |
| Trivium Packaging |
| CCL Container |
| Others |
Value Network & Pricing Analysis
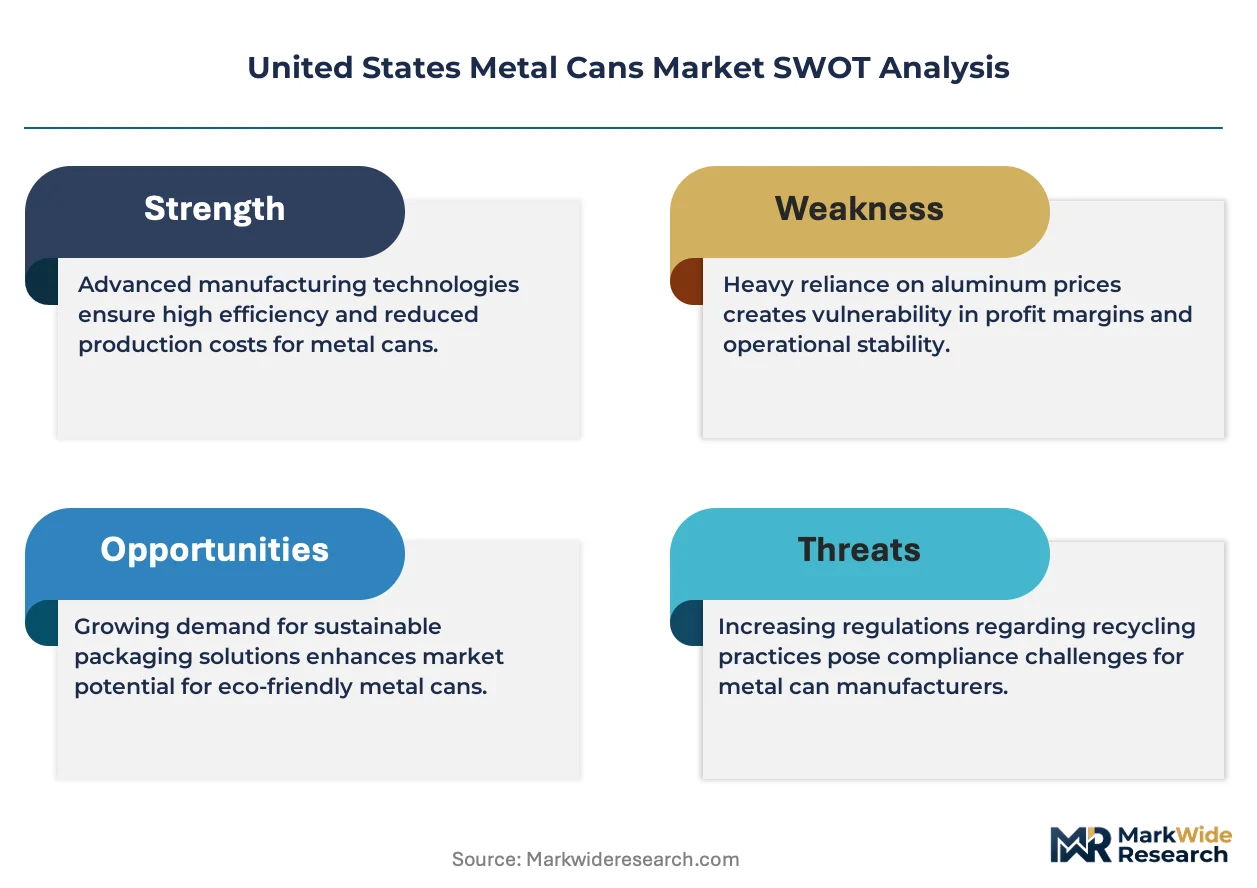
The Ohio-Indiana-Illinois manufacturing belt concentrates canmaking capacity within a 300-mile radius of Midwest aluminum rolling mills, creating tight supply-demand coupling that hands pricing power to integrated sheet producers when prime aluminum availability tightens. Beverage bottlers locked into long-term offtake agreements with Ball Corporation and Crown Holdings avoid spot-market volatility, while smaller food processors face widening spreads between contract and spot pricing for tinplate steel.
Pricing Analysis
Prior-generation solvent-based coating chemistries command steep discounts against water-based and powder formulations as EPA hazardous waste enforcement accelerates legacy line obsolescence. Contract-based long-term offtake agreements dominate beverage procurement, with price differentiation driven by volume scale and captive recycling access versus spot-market prime aluminum exposure. Cost compression in three-piece steel food cans intensifies as flexible pouch formats erode vegetable and soup processor volumes. Chemical suppliers demanding corrosion-resistant epoxy phenolic linings exhibit least price sensitivity, while mass-market beverage bottlers squeeze canmakers hardest on per-unit economics.
Supply Chain Analysis
Ball Corporation and Crown Holdings control the majority of domestic canbody fabrication capacity through vertically integrated rolling and coating operations. Raw material flows draw from Canadian smelter output, domestic recycled scrap streams, and imported alloy sheet from South American rolling mills. Single-source vulnerability concentrates in 3104-H19 alloy supply for lightweight beverage canbody production, where domestic smelter capacity constraints create input bottlenecks. Distribution runs through direct sales to Coca-Cola and PepsiCo bottling networks co-located with Midwest canmaking plants, supplemented by regional wholesalers serving fragmented food processor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible pouch and aseptic carton technologies threaten metal can incumbents across shelf-stable food segments, forcing substitution defense investments in lightweight aluminum and specialty format innovation to preserve beverage and industrial chemical containment volumes.
For Market Incumbents: Insulate core beverage relationships through captive recycling infrastructure investments in Ohio and Indiana that lock in prime aluminum cost advantages against spot-market entrants. Accelerate water-based coating line conversions ahead of OSHA hexavalent chromium enforcement deadlines to avoid extended downtime penalties that would cede share to compliant competitors. For New Entrants and Emerging Players: Build out aerosol and shaped specialty can capabilities targeting Pacific Northwest craft beer limited releases and Texas chemical supplier corrosion-resistant lining demand, where incumbent capacity constraints create white-space openings. Pursue direct-to-consumer online platform distribution for variable-data decorated small formats that bypass entrenched retail and direct sales channel control. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underoptimized metal can divisions lacking vertical integration into recycling or sheet production. Long-term viability hinges on aluminum alloy lightweighting trajectory and EPR regulatory expansion across Illinois and New York; monitor state legislative committee markup schedules as inflection signals for collection infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Infrastructure Acquisition | Captive aluminum access secures prime material cost advantages against spot-market volatility. |
| Water-Based Coating Conversion | EPA hazardous waste compliance eliminates regulatory enforcement exposure at legacy facilities. |
| Specialty Format Capacity Expansion | Aerosol and shaped can production captures premium spirits and personal care white-space demand. |
| Long-Term Offtake Agreement | Beverage bottler commitments reduce working capital requirements through logistics integration. |
| EPR Compliance System Investment | California SB 54 readiness positions operators for Illinois and New York regulatory expansion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EPA enforcement databases, and state legislative tracking systems. Interviews with canmaking plant managers, beverage procurement directors at Coca-Cola and PepsiCo bottling networks, food processor supply chain leads, and chemical supplier packaging engineers informed demand-side validation. Customs trade data, aluminum industry association shipment reports, and FDA food-contact substance notification filings provided supply-side triangulation against bottom-up capacity estimates and top-down market sizing.
Forecast inputs span product type segmentation by material composition and fabrication method, end-user differentiation across beverage, food, chemical, and household product channels, and size dimensional specifications from single-serve through industrial formats. Modeled CAGRs derive from volume trajectory analysis across the projection horizon, incorporating aluminum alloy lightweighting adoption curves, SB 54 compliance investment timing, and steel food can substitution elasticities.
Practitioners should monitor prime aluminum smelter capacity utilization rates, state EPR legislative committee markups, and water-based coating conversion completion timelines for early signals of supply constraint or regulatory acceleration. Quarterly review of Midwest manufacturing belt capacity announcements and California SB 54 implementation guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
Aluminum Aerosol Cans Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
Aluminum Foil Packaging Market
Metal Packaging
Brass Foils Market
Metal Packaging
Metal Cans Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Three Piece Cans Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
Tin Cans Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Pressurized Metal Containers Market