
 Archival Grade Blu-Ray Discs Market | 2026-2036
Archival Grade Blu-Ray Discs Market Size, Share, and Industry Trends Forecast 2026-2036
Archival Grade Blu-Ray Discs Market Insights
ISO/IEC 16963 optical disc longevity testing is redrawing competitive boundaries in archival media supply. Panasonic Corporation leverages in-house sputtering expertise to sustain premium positioning in institutional channels. Millenniata Inc. differentiates through proprietary rock-like recording layer technology aimed at century-scale retention. Sony Corporation anchors professional broadcast and government archive segments with established BD-R XL formulations.
Archival grade Blu-ray discs employ inorganic phase-change or dye-polymer recording layers deposited on polycarbonate substrates, engineered for 50 to 100 year data retention under controlled environmental conditions. BD-R XL dominates value capture in the capacity segment, as 100GB triple-layer configurations command sustained premiums from enterprise archiving contracts. The format segment tilts toward double-layer and triple-layer variants where institutional buyers prioritize capacity density per disc over per-gigabyte media cost.
FDA 21 CFR Part 11 shapes electronic record retention requirements that indirectly steer pharmaceutical and clinical trial operators toward verified optical archive media. Japan's METI promotes domestic optical storage supply chains through industrial technology grants targeting next-generation disc manufacturing. ECHA REACH compliance on polycarbonate and rare-earth stabilizer content constrains European-sourced raw material pathways. Stakeholders must monitor how evolving national digital preservation frameworks assign legal validity to specific physical media formats.
Market Dynamics
ISO/IEC 16963 longevity certification is filtering supplier eligibility and concentrating procurement around verified optical media manufacturers. Government archives and cultural institutions now mandate compliant write-once media, compressing the addressable vendor base to sputtering-capable producers.
Growth Catalysts
- Long-term digital preservation mandates:National archives in Japan, Germany, and the United States now require century-scale retention protocols, expanding institutional procurement of BD-R XL media for born-digital records.
- FDA 21 CFR Part 11:Pharmaceutical and clinical trial operators face electronic record retention requirements that steer validation toward tamper-evident optical archive formats with audit trail integrity.
- Rock-like recording layer advances:Proprietary inorganic phase-change materials now target 100-year data retention under controlled temperature and humidity specifications.
Market Restraints
- Rare-earth stabilizer cost volatility:ECHA REACH compliance constraints on polycarbonate and rare-earth content in European-sourced substrates elevate raw material input costs for triple-layer disc production.
- Supply concentration in Japanese sputtering:Dedicated archival product lines concentrate among domestic optical media manufacturers, creating single-source risk for institutional buyers requiring ISO/IEC 16963-compliant media.
- Cloud storage substitution:Enterprise data centers increasingly default to magnetic tape and distributed cloud architectures for secondary backup, compressing addressable demand for physical optical archives.
Strategic Opportunities
- Underpenetrated government archives:India's National Archives and state-level cultural institutions lack systematic optical preservation infrastructure, creating first-mover positioning for certified media suppliers.
- Healthcare imaging convergence:DICOM-compliant medical imaging archives in radiology and pathology departments present emerging demand for WORM optical media with forensic verification chains.
- METI industrial technology grants:Japan's Ministry of Economy, Trade and Industry promotes next-generation disc manufacturing through targeted subsidies for longevity-testing facility expansion.
Industry Challenges
- ISO/IEC 16963 certification timelines:Accelerated stress-testing protocols require 1,000-hour thermal-humidity cycling that extends product qualification cycles and delays revenue recognition for new disc formulations.
- Sputtering equipment capex intensity:Inorganic recording layer deposition requires vacuum sputtering systems with six-figure capital outlays, constraining mid-tier manufacturers from entering the archival grade segment.
- Legacy migration complexity:Government archives operating hybrid paper-digital systems face integration friction when embedding optical WORM media into existing enterprise content management workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Archival Grade Blu-Ray Discs Market |
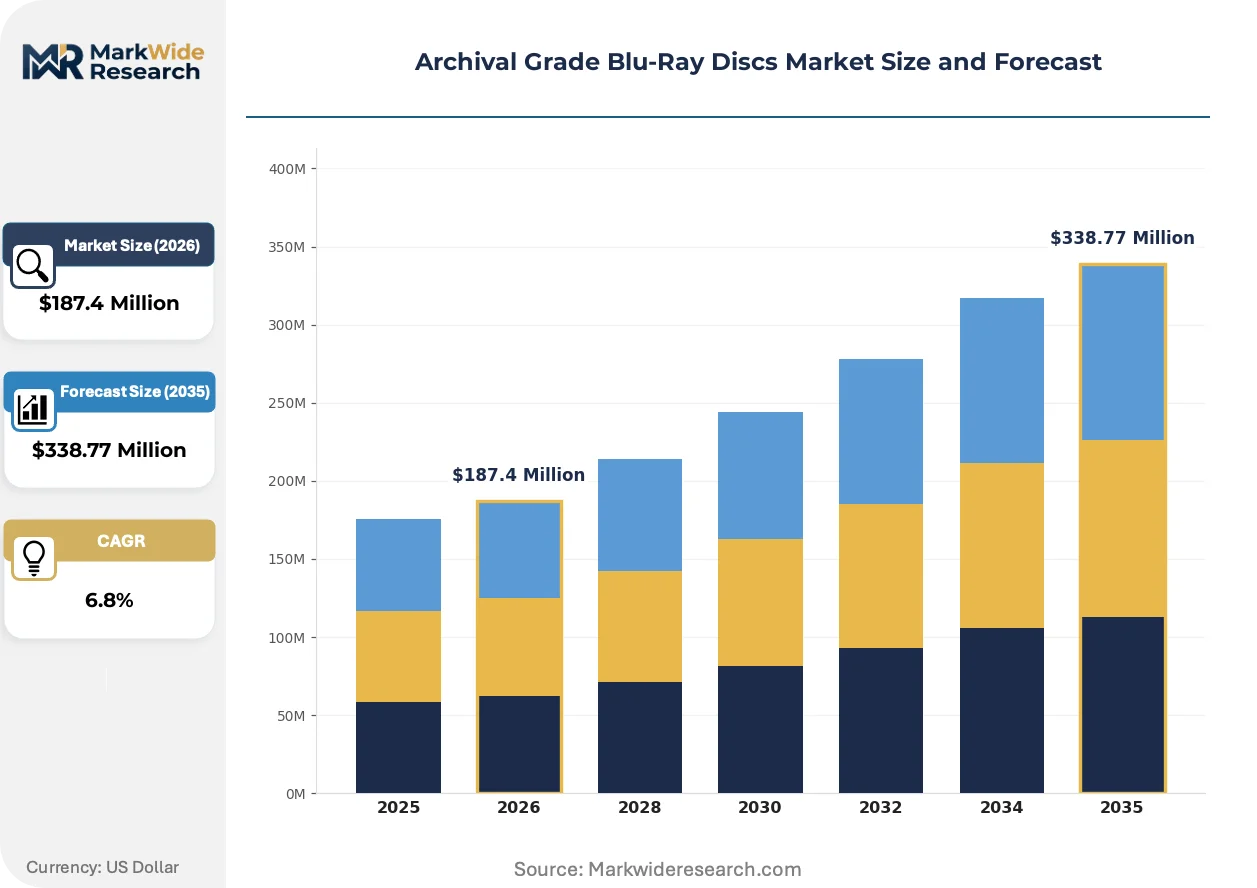
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BD-R, BD-RE, BD-R XL, BD-RE DL Capacity: 25GB, 50GB, 100GB, 128GB Format: Standard, Double Layer, Triple Layer, Quad Layer Distribution Channel: Online Retailers, Electronics Stores, Wholesale Distributors, Office Supply Stores |
| Companies Covered | Sony Corporation, Panasonic Corporation, Verbatim Ltd., Millenniata Inc., Ritek Corporation, CMC Magnetics Corporation, Optical Disc Systems Pte Ltd., Mitsubishi Chemical Media Co., Ltd., TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Archival Grade Blu-Ray Discs Market Trends and Innovations
Recording layer chemistry and institutional procurement protocols are the twin axes of change. Manufacturers now compete on accelerated aging validation, while buyers consolidate around pre-qualified supplier lists.
Triple-layer BD-R XL configurations are decomposing the traditional cost-per-gigabyte calculus in enterprise archiving. National libraries and broadcast archives in Japan now specify 100GB discs for master file preservation, accepting premium media costs in exchange for reduced physical storage footprint. This shift is decomposing demand concentration around lower-capacity double-layer formats.
Japan's METI promotes domestic optical storage supply chains through industrial technology grants targeting next-generation disc manufacturing. The policy redirects public research funding toward sputtering process optimization and substrate purity improvements. Archival institutions within Japan now prioritize domestically sourced media for sovereign data retention requirements.
Direct procurement from sputtering-capable manufacturers is displacing distributor-mediated purchasing in institutional channels. Government archives and pharmaceutical operators now negotiate frame contracts with certified producers, bypassing wholesale intermediaries. This pattern is most visible in Germany, where federal and state-level archives consolidate purchasing through central procurement offices with technical pre-qualification requirements.
Archival Grade Blu-Ray Discs Market Segmentation
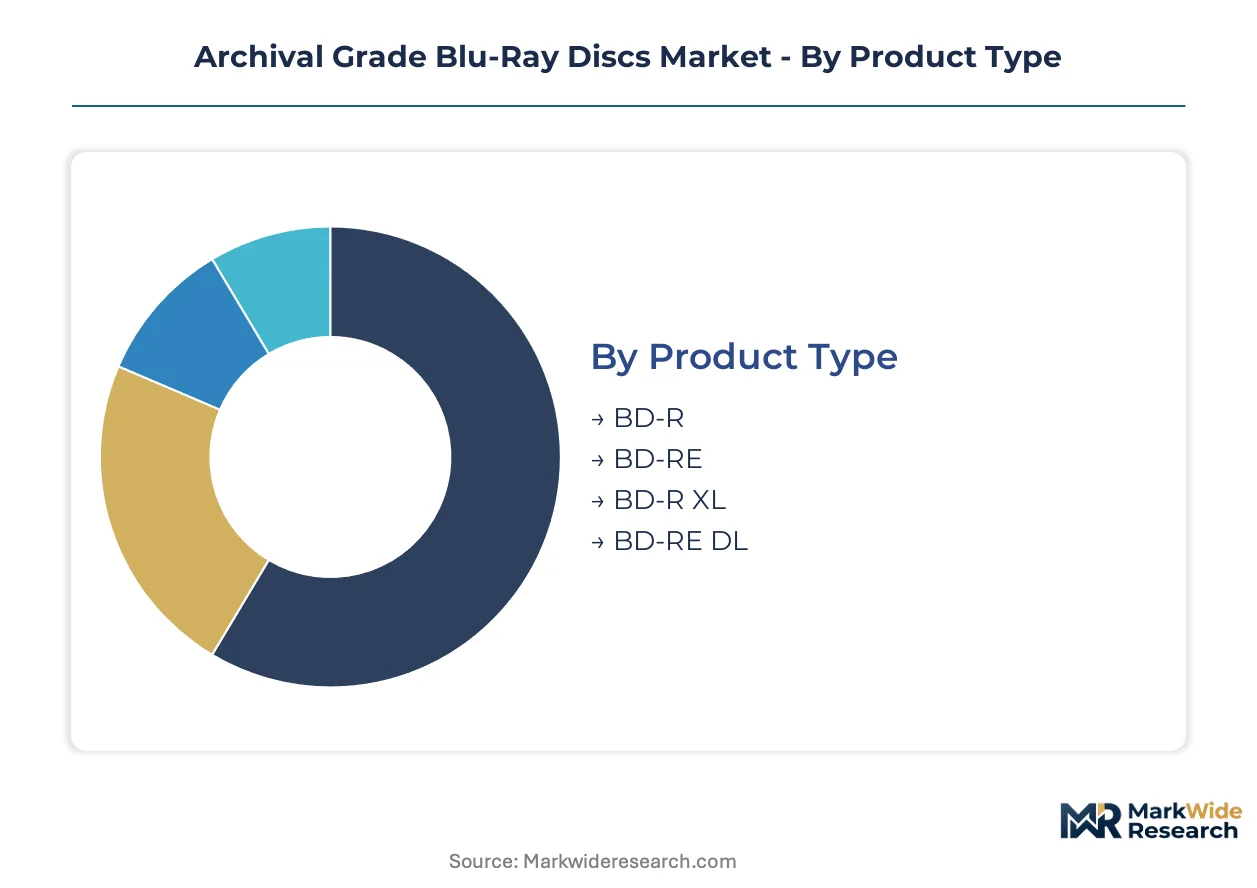
ISO/IEC 16963 certification requirements fragment procurement patterns across product tiers, with institutional buyers filtering segments by verified longevity claims rather than nominal specifications alone. Capacity and layer configurations now map directly to compliance-grade procurement workflows in government archives and pharmaceutical operations.
Product Type:
FDA 21 CFR Part 11 and Japan's METI procurement guidelines differentiate write-once from rewritable formats through audit trail integrity requirements.
- BD-R:Write-once dye-polymer or inorganic phase-change recording layers deposited on polycarbonate substrates. Institutional buyers in Germany's federal archives specify BD-R for born-digital record preservation, prioritizing tamper-evident WORM characteristics over rewritable convenience.
- BD-R XL:Triple-layer configurations with 100GB native capacity employing expanded groove structures. Japan's national broadcast archives and pharmaceutical operators in the United States drive procurement concentration here, accepting premium unit costs for reduced physical storage footprints in climate-controlled vaults.
- BD-RE:Phase-change rewritable format with crystalline-amorphous state cycling. Limited archival adoption due to rewrite cycle limits and forensic verification concerns.
- BD-RE DL:Double-layer rewritable variant. Niche presence in temporary production workflows rather than long-term preservation protocols.
BD-R handles the majority of throughput; BD-R XL is the fastest mover on share.
Capacity:
Cost-per-gigabyte calculus inverts as institutional buyers prioritize physical storage density over media unit economics.
- 100GB:Triple-layer BD-R XL configurations now specified in Japan's national library master file preservation contracts. METI industrial technology grants subsidize domestic manufacturing scale for this tier, compressing effective procurement costs for sovereign data retention programs.
- 50GB:Double-layer standard dominates mid-tier pharmaceutical and clinical trial archiving where FDA 21 CFR Part 11 compliance mandates intersect with moderate volume requirements. German state-level archives consolidate purchasing here for hybrid paper-digital migration projects.
- 25GB:Single-layer legacy format. Declining institutional relevance outside cost-constrained small archive conversions.
- 128GB:Quad-layer experimental capacity. Limited commercial availability pending ISO/IEC 16963 qualification cycles for next-generation sputtering processes.
50GB maintains current volume leadership; 100GB is expanding most quickly in procurement specifications.
Format:
Layer count determines sputtering equipment requirements and supplier eligibility under accelerated stress-testing protocols.
- Triple Layer:100GB native capacity requiring precision groove depth control across three stacked recording layers. Japan's domestic optical media manufacturers maintain dedicated production lines here, with METI grants targeting substrate purity improvements for century-scale retention claims.
- Double Layer:50GB capacity with dual recording layers. German federal procurement offices pre-qualify suppliers on this format first, establishing technical baselines before triple-layer frame contract negotiations.
- Standard:Single-layer 25GB configuration. Baseline format for ISO/IEC 16963 certification entry, with shorter qualification timelines.
- Quad Layer:Experimental 128GB architecture. Awaiting commercial sputtering process validation and institutional buyer specification updates.
Double Layer anchors current procurement volumes; Triple Layer is climbing the fastest in specification mandates.
Distribution Channel:
Technical pre-qualification requirements are displacing traditional wholesale intermediaries in institutional procurement.
- Wholesale Distributors:Consolidated purchasing through Germany's central procurement offices and Japan's government supply chains still routes partially through qualified distributors with ISO/IEC 16963 documentation capabilities.
- Online Retailers:Direct procurement from sputtering-capable manufacturers via B2B portals. Pharmaceutical operators in the United States negotiate frame contracts here, bypassing intermediaries for audit trail integrity.
- Electronics Stores:Consumer and small business presence. Minimal institutional archive penetration due to lack of technical certification documentation.
- Office Supply Stores:Generic media retail. No archival grade product lines with ISO/IEC 16963 compliance documentation.
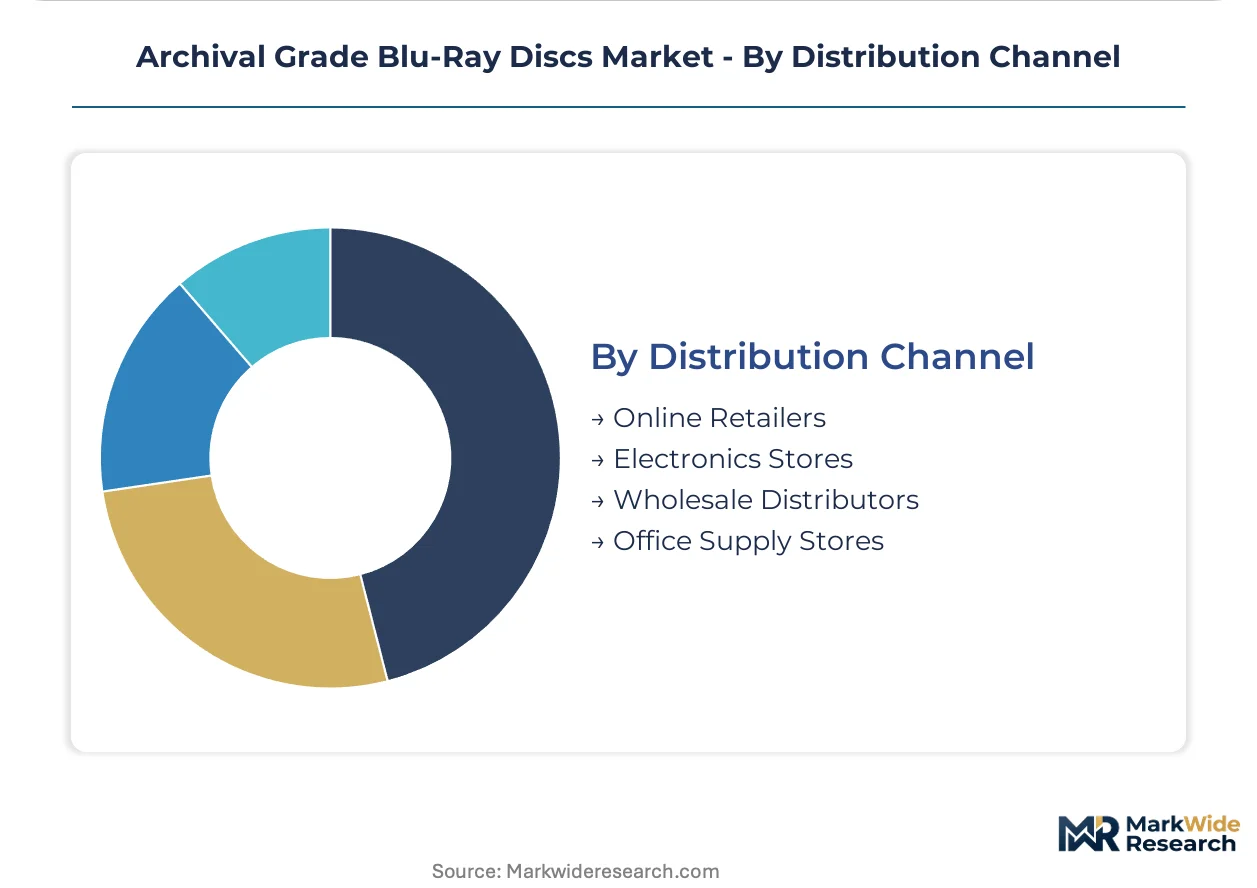
Wholesale Distributors retain legacy contract flows; Online Retailers are gaining share fastest in direct manufacturer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Yokohama's container throughput underwrites Japan's dominance in precision optical media exports, while Frankfurt's data corridor anchors European institutional procurement networks for verified archival storage.
Japan
National library master file preservation contracts and METI industrial technology grants drive procurement concentration in triple-layer BD-R XL formats. Japan's Ministry of Economy, Trade and Industry subsidizes sputtering process optimization for century-scale retention claims. Domestic optical media manufacturers in the Kanto region maintain dedicated archival product lines with ISO/IEC 16963 certification.
Germany
Federal and state-level archives consolidate purchasing through central procurement offices with technical pre-qualification requirements. ECHA REACH compliance constraints on polycarbonate substrates elevate raw material input costs for European-sourced production. The Frankfurt-Rhine-Main metropolitan area hosts distributor-mediated contract flows for hybrid paper-digital migration projects.
United States
FDA 21 CFR Part 11 electronic record retention requirements steer pharmaceutical and clinical trial operators toward tamper-evident optical archive formats. Pharmaceutical operators negotiate frame contracts directly with certified producers via B2B portals. The Boston-Cambridge biotech corridor generates sustained demand for WORM media with forensic verification chains.
India
The National Archives and state-level cultural institutions lack systematic optical preservation infrastructure, creating first-mover positioning opportunities for certified media suppliers. The country's national archival regulator has yet to mandate century-scale retention protocols for born-digital records. Mumbai and Delhi-NCR clusters show emerging interest in DICOM-compliant medical imaging archives for radiology departments.
South Korea
Broadcast archives and cultural heritage institutions are expanding procurement of ISO/IEC 16963-compliant media for master file preservation. The national broadcasting regulator influences technical specifications for long-term digital asset retention. Seoul Capital Area manufacturers leverage existing optical disc production expertise to enter archival grade segments.
Archival Grade Blu-Ray Discs Market Competitive Landscape
Listed leaders compete with private specialists across certification and capacity tiers. The vendor base concentrates around sputtering-capable producers with in-house longevity testing facilities, compressing the addressable supplier pool for institutional buyers. Three strategic archetypes dominate: vertically integrated electronics conglomerates with dedicated archival divisions, specialty optical media pure-plays with proprietary recording layer formulations, and contract manufacturers serving private-label institutional channels. Competitive moves center on direct procurement relationships with government archives and METI grant-funded capacity expansion for triple-layer production.
Within the conglomerate tier, Sony Corporation and Panasonic Corporation exemplify scale-driven positioning through established broadcast and government archive segments. Millenniata Inc. occupies a specialist position focused on proprietary rock-like recording layer technology. These three entities anchor the competitive structure, with Sony and Panasonic representing Japanese sputtering expertise and Millenniata exemplifying the century-retention pure-play archetype.
| Leading Market Players |
|---|
| Sony Corporation |
| Panasonic Corporation |
| Verbatim Ltd. |
| Millenniata Inc. |
| Ritek Corporation |
| CMC Magnetics Corporation |
| Optical Disc Systems Pte Ltd. |
| Mitsubishi Chemical Media Co., Ltd. |
| TDK Corporation |
| Others |
Pricing and Supply Chain Analysis
Sputtering equipment utilization rates above 80% in Japan's Kanto region concentrate manufacturing scale among three domestic producers, compressing unit economics for triple-layer BD-R XL media while elevating price floors for ISO/IEC 16963-compliant output. This capacity concentration grants verified manufacturers pricing power over institutional buyers facing single-source risk, yet METI subsidy flows partially offset procurement premiums for sovereign data retention programs.
Pricing Analysis
Certification level (ISO/IEC 16963-grade) creates the primary spread between archival and consumer optical media, with FDA 21 CFR Part 11 validation adding further premiums for pharmaceutical procurement. Three-tier pricing structure across premium certified, standard institutional, and economy archival levels segments buyer tiers, with rare-earth stabilizer cost volatility under ECHA REACH constraints intensifying margin pressure in European-sourced production. Government archives in Germany and Japan show lowest price sensitivity due to century-scale retention mandates, while India's emerging cultural institutions operate as the most cost-constrained segment.
Supply Chain Analysis
Port of Yokohama container throughput underwrites Japan's dominance in precision optical media exports, with South Korean and Taiwanese manufacturers holding secondary positions in substrate supply. Polycarbonate substrates, rare-earth stabilizers, and sputtering-target metals constitute critical input dependencies, with ECHA REACH compliance constraining European raw material pathways. Single-source vulnerability concentrates in Japanese sputtering-capable producers with ISO/IEC 16963 testing facilities. Distribution runs through direct manufacturer relationships with government procurement offices, displacing traditional wholesale intermediaries in institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house vacuum sputtering expertise and accelerated longevity testing capabilities now constitute the decisive asset gap separating qualified suppliers from excluded competitors. The addressable vendor base compresses to manufacturers with six-figure capital equipment and 1,000-hour thermal-humidity cycling protocols.
For Market Incumbents: Fortify positioning through backward integration into sputtering-target metal supply and expansion of ISO/IEC 16963 testing capacity. Cloud storage substitution in enterprise backup segments threatens medium-term volume erosion, requiring incumbents to deepen sovereign data retention relationships with Japan's METI-subsidized procurement channels. For New Entrants and Emerging Players: Lead with certification-first positioning in India's underpenetrated National Archives and state-level cultural institutions, where systematic optical preservation infrastructure remains absent. DICOM-compliant medical imaging archives in radiology departments offer the most penetrable application wedge, with direct B2B portal contracting bypassing established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty optical media pure-plays with proprietary recording layer formulations over diversified electronics conglomerates. Long-term viability hinges on 5-10 year digital preservation mandate durability in government archives. The signal to watch is India's national archival regulator adoption of century-scale retention protocols, which would validate first-mover infrastructure investments.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 16963 Certification Investment | Filters supplier eligibility for German federal archive procurement contracts. |
| Backward Integration into Sputtering Targets | Secures rare-earth metal supply chains against ECHA REACH compliance volatility. |
| Direct B2B Portal Procurement Launch | Bypasses wholesale intermediaries for FDA 21 CFR Part 11 pharmaceutical buyers. |
| METI Grant-Funded Capacity Expansion | Subsidizes triple-layer BD-R XL scale for Japan's sovereign data retention programs. |
| DICOM-Compliant Medical Imaging Partnership | Opens radiology department demand for WORM optical media with forensic chains. |
Research Methodology
Cross-validation between primary interviews with optical media manufacturing executives and secondary analysis of METI industrial technology grant disclosures anchors the qualitative findings. Procurement officers at Germany's federal and state-level archives, pharmaceutical quality assurance directors, and sputtering equipment specialists provided operational perspective. FDA 21 CFR Part 11 guidance documents, ECHA REACH substance restriction databases, ISO/IEC 16963 testing protocols, and Japanese customs export statistics supplied secondary validation. Bottom-up capacity estimates triangulate against top-down procurement flow analysis.
Sensitivity analysis across rare-earth stabilizer cost scenarios and cloud storage substitution rates frames the forecast uncertainty. Segmentation dimensions include recording layer chemistry, layer count, capacity tier, and institutional buyer type. CAGRs derive from installed base depreciation curves and replacement demand modeling. Sputtering equipment capex cycles and METI subsidy allocation patterns constitute industry-specific forecast inputs throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained government digital preservation mandate durability or ECHA REACH regulatory stability would require recalibration. Forecasts reflect documented assumptions on institutional procurement consolidation and certification timeline compression. Practitioners should keep alternative scenarios live as India's national archival framework and pharmaceutical cloud migration preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Substrates for Magnetic Disks Market
Data Storage
Flash Memory Market
Data Storage
USB 3.1 Flash Drive Market
Data Storage
APAC Next Generation Storage Market
Data Storage
Data Center Ssds Market
Data Storage
APAC SSD Caching Market
Data Storage
Digital Recording System Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Zoned Flash Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
SSD Controller Market
Data Storage
Middle East and Africa Data Storage Market
Data Storage
Europe Flash Memory Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
NOR Flash Market