
 Optical Disk Market | 2026-2036
Optical Disk Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Disk Market Insights
Aftermarket service revenue for optical media refurbishment and archival migration is narrowing as enterprises shift toward hybrid cloud-cold storage strategies. Sony Corporation leverages its proprietary Blu-ray manufacturing scale to sustain premium archival disc output. Panasonic Corporation anchors industrial-grade optical storage for broadcast and medical imaging archives. Verbatim Americas LLC competes through specialized write-once media for legal and financial compliance markets.
An optical disk is a flat, circular polycarbonate substrate coated with reflective metallic and dye layers, read by laser diodes at wavelengths ranging from 780 nm for CDs to 405 nm for Blu-ray, designed for non-volatile data retention spanning decades. The product type dimension shows Blu-ray discs capturing enterprise archival margins while CD volumes mature in consumer retro markets. Writable formats dominate enterprise procurement for compliance-driven archiving, whereas read-only media sustains software distribution and multimedia publishing. The end user structure reveals enterprises and educational institutions as the residual demand pool as consumer adoption of physical media continues declining.
The US FDA and Japan's METI both reference optical media durability standards for medical and governmental record retention, while REACH compliance in Europe governs polycarbonate and rare-earth element usage in disc substrates. These regulatory frameworks elevate product certification costs but also preserve optical disk relevance in sectors where magnetic and solid-state alternatives lack proven longevity. Stakeholders must weigh format obsolescence risk against the regulatory durability requirements that continue validating optical technology in select compliance-driven verticals.
Market Dynamics
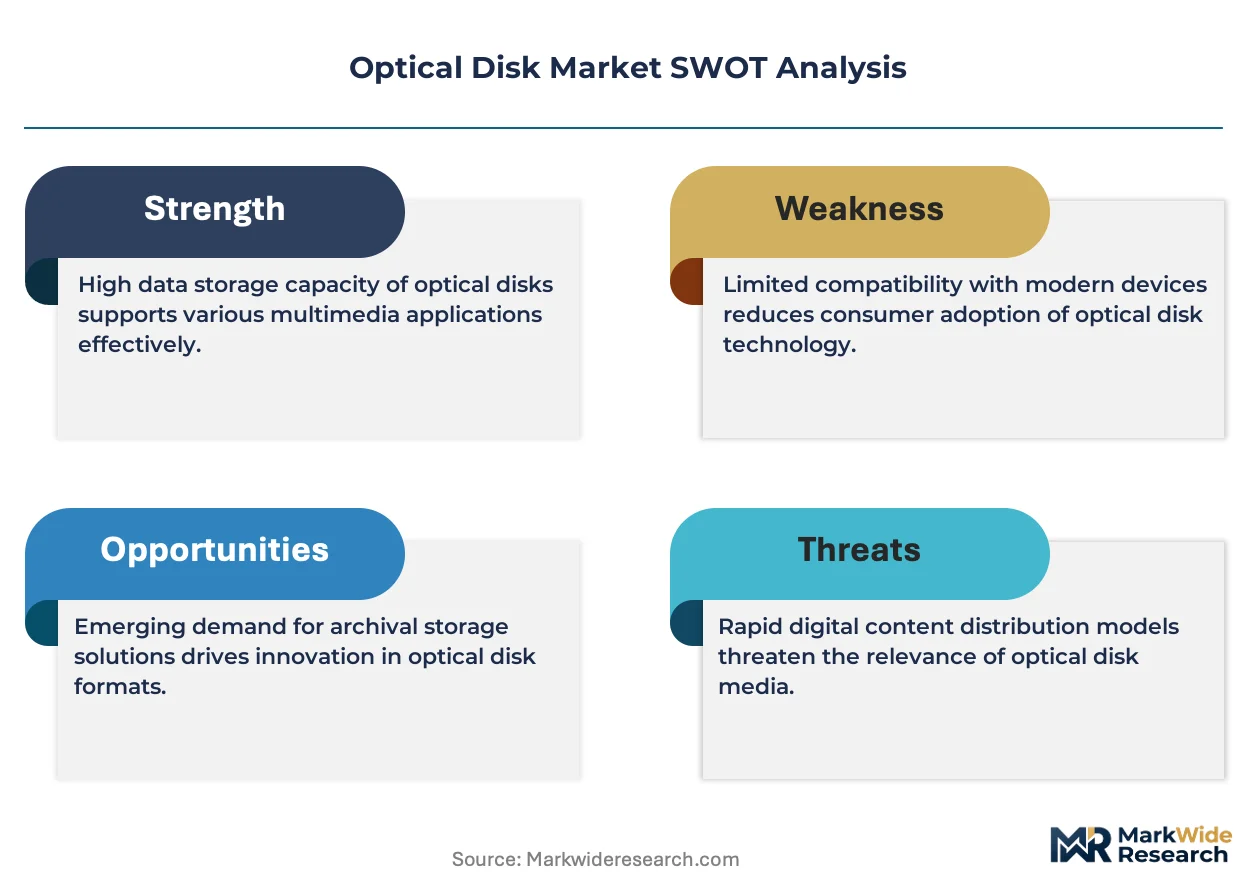
Enterprise migration to hybrid cloud-cold storage architectures is compressing the addressable base for standalone optical media while simultaneously elevating certification requirements for archival-grade discs in regulated verticals.
Growth Catalysts
- Japan METI archival mandates:Long-term digital preservation standards require optical media durability benchmarks that only certified manufacturers can meet, sustaining premium product demand.
- Medical imaging retention:US FDA 21 CFR Part 11 compliance drives hospital procurement of write-once optical media for immutable audit trails in radiology and pathology departments.
- German federal cold storage:Federal archival mandates specify optical media for compliance-driven document retention, creating institutional procurement volume.
Market Restraints
- Polycarbonate resin volatility:Feedstock price fluctuations for optical-grade polycarbonate substrates compress manufacturing margins unpredictably.
- Japanese manufacturing concentration:Premium archival disc production clusters in Japanese facilities, exposing supply continuity to single-geography risk.
- Cloud object storage substitution:Amazon Glacier and comparable services displace optical media in non-regulated enterprise backup applications.
Strategic Opportunities
- EU CSRD disclosure requirements:Corporate sustainability reporting mandates create demand for immutable ESG data archives that optical media can satisfy.
- Quantum-dot archival layers:Integration of nanocrystal recording layers with conventional polycarbonate substrates extends retention horizons beyond current dye-based limits.
- Legal discovery services:Law firms and e-discovery vendors represent underpenetrated channels for write-once compliance media in litigation hold workflows.
Industry Challenges
- ISO 18927 certification timelines:Extended testing protocols for optical disc longevity delay product launches and tie up R&D capital.
- Legacy tape migration complexity:Enterprises struggle to integrate optical archives with existing LTO infrastructure, slowing hybrid storage adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Disk Market |
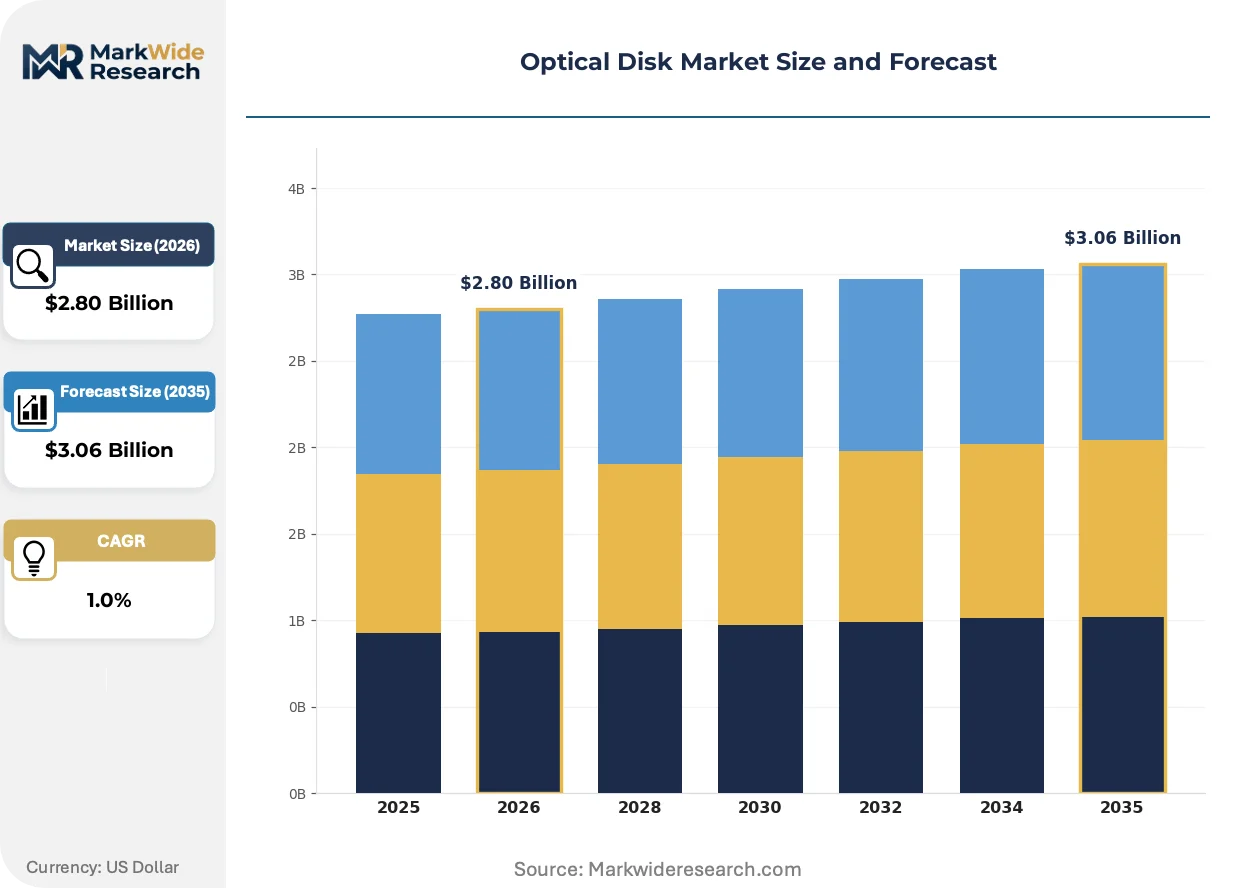
| Market Size in 2026 | $2.80 Billion |
| Market Size in 2035 | $3.06 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DVD, Blu-ray, CD, HD DVD Format: Writable, Read-only, Rewritable, Hybrid Application: Data Storage, Multimedia, Software Distribution, Archiving End User: Consumers, Enterprises, Educational Institutions, Media Houses |
| Companies Covered | Sony Corporation, Toshiba Corporation, Samsung Electronics, Panasonic Corporation, Verbatim Americas LLC, Ritek Corporation, TDK Corporation, Taiyo Yuden Co., Ltd., Maxell Holdings, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Disk Market Trends and Innovations
Archival storage technology is bifurcating between high-durability optical formats for compliance and cloud-native object stores for operational data, with innovation concentrating on extending optical media lifespan.
Silica glass data storage is collapsing the theoretical limits of optical retention by encoding information in nanostructures within quartz substrates. Microsoft Research and academic partners are piloting this technology for century-scale archives. The approach is collapsing conventional assumptions about media refresh cycles in national libraries and scientific data repositories.
REACH Substance of Very High Concern listings are tightening restrictions on polycarbonate additives and rare-earth stabilizers used in disc manufacturing. ECHA evaluations are forcing reformulation of substrate compositions. European manufacturers are responding by accelerating alternative polymer qualification programs.
Enterprise buyers are consolidating storage vendor relationships and demanding bundled archival services rather than discrete media procurement. Systems integrators and managed service providers are capturing optical media margin through subscription-based cold storage offerings. This pattern is most pronounced in German and Japanese enterprise markets where procurement centralization has advanced furthest.
Optical Disk Market Segmentation
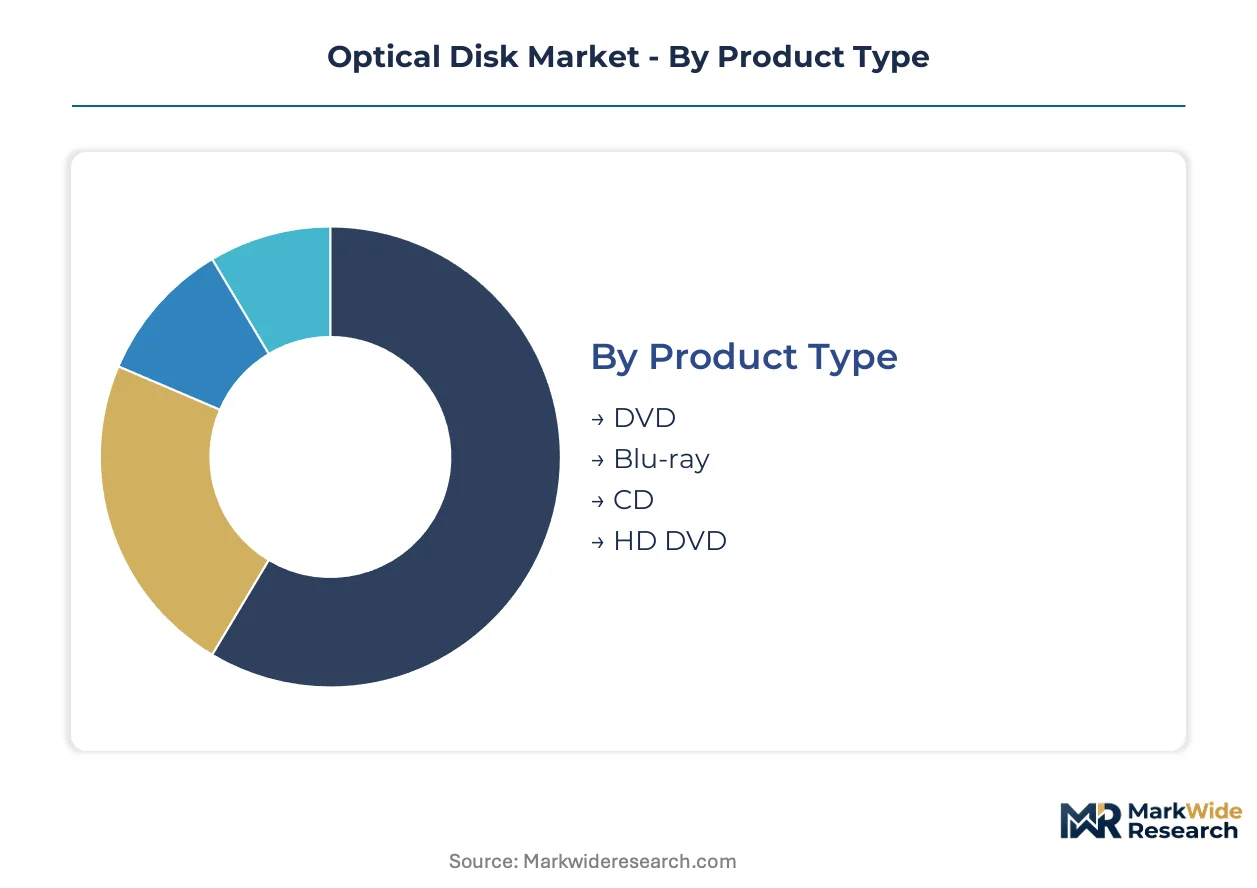
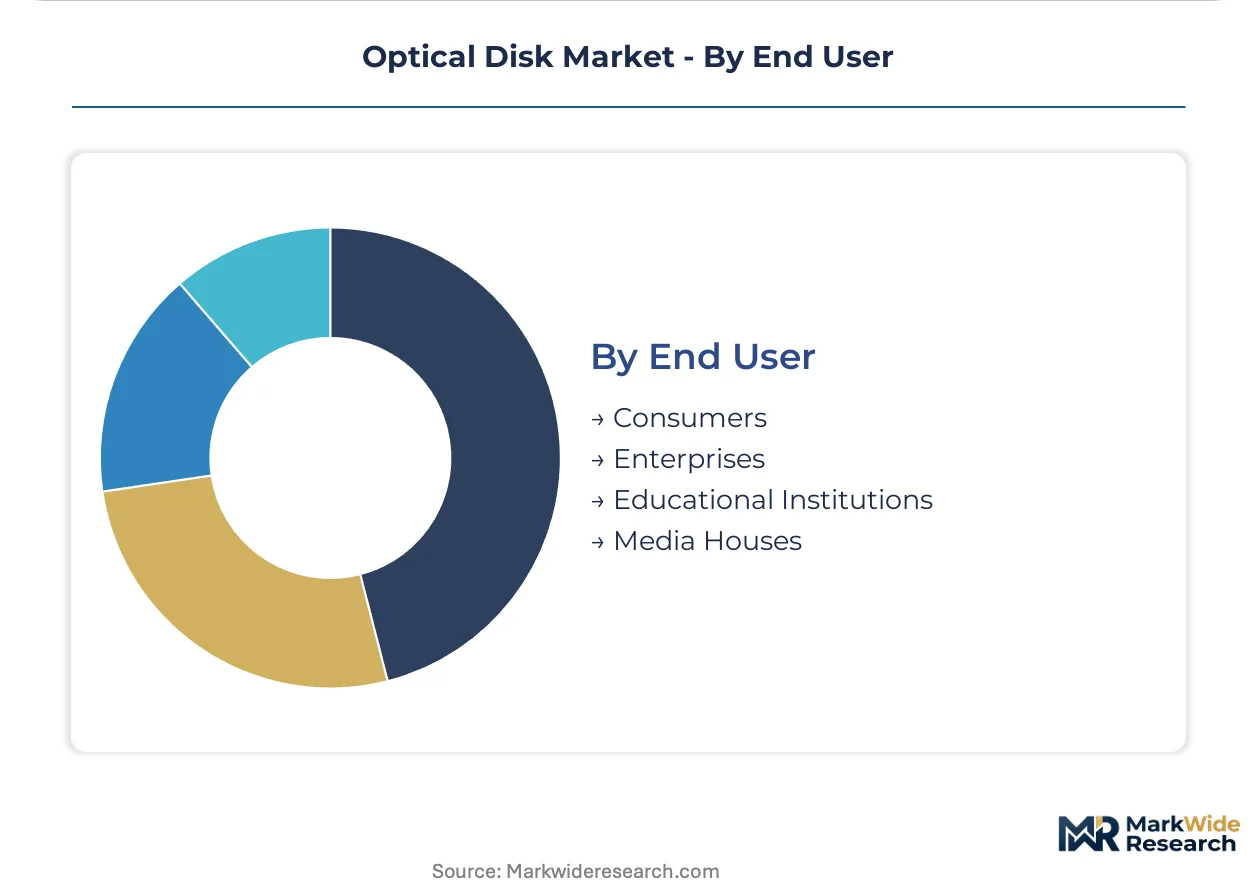
Optical disk segmentation reveals how enterprise compliance requirements and consumer nostalgia markets pull the same technology in opposite directions. Format durability specifications and write-once immutability create divergent value propositions across end-use verticals.
Product Type:
Cost tier differentiation separates archival-grade premiums from commoditized consumer formats with minimal overlap in procurement channels.
- Blu-ray:Multi-layer polycarbonate substrates with 405 nm laser readability support 50-100 GB native capacity. Enterprise data centers in Germany and Japan procure archival-grade variants for regulatory-mandated cold storage, paying durability certification premiums that consumer channels cannot support.
- DVD:Dual-layer construction achieves 8.5 GB using 650 nm red laser diodes. Remaining demand concentrates in educational institutions and developing-market government archives where legacy infrastructure compatibility outweighs density requirements.
- CD:700 MB capacity and 780 nm infrared laser specification now serves retro gaming collectors and independent music distribution niches.
- HD DVD:Obsolete format retained only in specialized broadcast archive migration services handling legacy Toshiba equipment conversions.
Blu-ray commands the established base. The steepest expansion runs through DVD as budget-constrained institutions delay infrastructure refresh cycles.
Format:
Application context determines whether write capability represents a compliance feature or a liability in procurement decisions.
- Writable:Organic dye or phase-change recording layers permit single or limited rewriting cycles. Hospital radiology departments and financial compliance officers in the US specify write-once variants for immutable audit trails under FDA 21 CFR Part 11 and SEC record retention rules.
- Read-only:Physical pit-and-land mastering creates permanent data structures. Software publishers and multimedia distributors in Japan continue replication contracts for offline distribution security.
- Rewritable:Phase-change alloy layers enable thousands of rewrite cycles. Broadcast production houses use these for temporary workflow storage before final archival transfer.
- Hybrid:Dual-zone construction combines read-only and writable areas. Niche applications include kiosk distribution systems requiring updatable content alongside fixed base images.
Writable formats dominate procurement volume. Hybrid configurations are gaining share fastest in interactive media deployment scenarios.
Application:
Customer risk tolerance separates applications where media longevity justifies premium pricing from those where obsolescence acceptance permits cost minimization.
- Archiving:Decades-long retention specifications require ISO 18927-certified media with accelerated aging validation. German federal archives and Japan's national library system mandate optical media for statutory preservation periods exceeding magnetic tape reliability horizons.
- Data Storage:Backup and nearline tier applications face active displacement by cloud object storage except where air-gapped security requirements prevail.
- Multimedia:Consumer video and audio distribution continues contracting as streaming penetration advances.
- Software Distribution:Physical media persists for enterprise licensing in bandwidth-constrained environments and offline installation requirements.
Archiving commands the established base. Data storage applications are expanding most quickly in hybrid cloud-cold storage integration projects.
End User:
Procurement sophistication varies dramatically between institutional buyers with formal durability specifications and consumer purchasers prioritizing unit cost.
- Enterprises:Formal RFP processes specify media longevity certifications, supply chain traceability, and vendor audit rights. Compliance officers in regulated verticals maintain approved vendor lists with annual recertification requirements.
- Educational Institutions:Budget constraints favor DVD formats and multi-year procurement contracts with deferred payment structures.
- Media Houses:Broadcast and film production operations require real-time write performance and compatibility with legacy nonlinear editing systems.
- Consumers:Residual demand concentrates in collector markets and regions with unreliable broadband infrastructure.
Enterprises command the established base. Educational institutions represent the steepest expansion trajectory as digital preservation mandates extend to secondary and post-secondary record retention requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese buyers absorb archival-grade premiums without volume elasticity, while Indian educational procurement collapses toward lowest-cost DVD formats. German federal mandates create price-inelastic institutional demand. US hospital compliance officers prioritize certification over unit cost.
Japan
METI longevity benchmarks and national library preservation statutes sustain premium Blu-ray procurement. The agency's digital archive standards mandate 50-year retention validation. Tokyo-Osaka manufacturing corridors concentrate archival-grade disc production for domestic and export compliance markets.
Germany
Federal archival mandates specify optical media for statutory document retention in cold storage applications. BSI technical guidelines reinforce procurement specifications for immutable record-keeping. Bavarian data center clusters anchor enterprise-grade media consumption for financial and pharmaceutical compliance verticals.
United States
FDA 21 CFR Part 11 drives hospital radiology departments toward write-once media for immutable audit trails. SEC record retention rules sustain financial services procurement despite cloud migration pressures. Greater Boston medical research institutions maintain specialized optical archive infrastructure for longitudinal study data.
China
Provincial government digitization programs create residual demand for DVD-format distribution in bandwidth-constrained western regions. MIIT standardization efforts for optical media quality influence procurement specifications. Yangtze River Delta manufacturing bases supply cost-optimized media for domestic educational and government markets.
South Korea
Broadcast archive migration projects sustain demand for rewritable formats in production workflows. MFDS medical device record retention guidelines align with optical durability requirements. Seoul Capital Area post-production houses concentrate specialized media procurement for content preservation pipelines.
Optical Disk Market Competitive Landscape
Capability concentration sits with Japanese manufacturers possessing archival certification infrastructure; scale advantage sits with diversified electronics conglomerates with polycarbonate substrate supply control. The vendor base stratifies across three tiers: premium archival specialists, mid-market compliance suppliers, and commodity consumer media fabricators. Dominant competitive moves include backward integration into optical-grade polycarbonate resin production and strategic partnerships with systems integrators for bundled cold storage service offerings.
Among Japanese precision manufacturers, Sony Corporation, Panasonic Corporation, and Taiyo Yuden Co., Ltd. occupy positions defined by METI certification proximity and proprietary dye-layer formulations. These entities exemplify the capability-driven tier where regulatory compliance credentials outweigh manufacturing scale in procurement decisions. Their positioning reflects decades-long accumulation of accelerated aging test data and substrate formulation expertise that newer entrants cannot replicate within certification timeline constraints.
| Leading Market Players |
|---|
| Sony Corporation |
| Toshiba Corporation |
| Samsung Electronics |
| Panasonic Corporation |
| Verbatim Americas LLC |
| Ritek Corporation |
| TDK Corporation |
| Taiyo Yuden Co., Ltd. |
| Maxell Holdings, Ltd. |
| Others |
Pricing and Supply Chain Analysis
The Yokohama-Osaka maritime corridor channels optical-grade polycarbonate resin from petrochemical complexes to disc manufacturing plants, with freight cost volatility amplifying margin compression at Japanese archival-grade producers while enabling sharper price differentiation between certified premium tiers and commodity consumer formats.
Pricing Analysis
Aftermarket service revenue from archival migration contracts and extended warranty programs drives lifetime value capture for vendors serving German federal archives and Japanese national libraries. Three-tier pricing structure across archival-certified premium, standard enterprise, and economy consumer levels reflects ISO 18927 certification investment and dye-layer formulation complexity. Pricing pressure stems from Amazon Glacier displacement in non-regulated enterprise backup segments. Educational institutions in India and China exhibit highest price sensitivity, while US hospital compliance officers and German federal procurement offices prioritize certification durability over unit cost.
Supply Chain Analysis
Upstream optical-grade polycarbonate resin production concentrates in Japan, South Korea, and Germany, with bisphenol-A feedstock and rare-earth stabilizer additives subject to REACH Substance of Very High Concern evaluations. Japanese manufacturing clusters anchor archival-grade disc fabrication, exposing supply continuity to single-geography seismic and logistics disruption risks. Distribution runs through systems integrators and managed service providers bundling cold storage subscriptions, particularly in German and Japanese enterprise markets where procurement centralization has advanced furthest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise fragmentation between compliance-driven archival demand and cloud-displaced operational storage creates niche specialization opportunities for vendors targeting immutable record-keeping verticals.
For Market Incumbents: Harden archival certification moats by accelerating ISO 18927 test data accumulation and dye-layer formulation IP that emerging competitors cannot replicate within regulatory timelines. Deepen backward integration into optical-grade polycarbonate resin production to buffer margin compression from feedstock volatility. Threat substitution from silica glass archival technology demands pre-emptive nanocrystal recording layer R&D investment. For New Entrants and Emerging Players: Pursue legal discovery services and e-discovery vendor channels as underpenetrated white-space targets for write-once compliance media in litigation hold workflows. European Union CSRD disclosure requirements create demand for immutable ESG data archives that lack established vendor relationships. Go-to-market positioning should emphasize bundled archival services through subscription-based cold storage offerings rather than discrete media procurement. For Investors and Strategic Acquirers: Japanese precision manufacturers with METI certification proximity and proprietary substrate expertise represent the most defensible acquisition archetype for long-term archival storage viability assessment. Watch quantum-dot archival layer commercialization timelines as the critical inflection signal distinguishing century-scale retention leaders from legacy dye-based obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polycarbonate Resin | Captive supply of optical-grade substrates buffers margin compression from REACH-regulated additive restrictions. |
| Quantum-Dot Archival Layer Development | Nanocrystal recording layers extend retention horizons beyond conventional dye-based limits for national library contracts. |
| Systems Integrator Partnership Programs | Subscription-based cold storage bundles capture optical media margin through managed service provider channels. |
| EU CSRD Compliance Service Packaging | Immutable ESG data archive offerings align with Corporate Sustainability Reporting Directive disclosure mandates. |
| ISO 18927 Certification Acceleration | Extended longevity testing protocols create regulatory barriers that newer entrants cannot overcome within product launch windows. |
Research Methodology
Initial hypotheses were tested against primary input from optical media procurement officers at German federal archives, hospital biomedical engineering directors in US radiology departments, Japanese national library preservation specialists, and enterprise compliance officers in financial services, then refined through secondary validation against METI digital preservation standards documentation, FDA 21 CFR Part 11 guidance filings, ECHA REACH substance evaluations, and customs trade data for optical-grade polycarbonate resin flows. Bottom-up demand modeling from end-user segmentation and top-down supply validation from manufacturing capacity assessments were triangulated to reconcile volume estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, format immutability specifications, application durability requirements, and end-user procurement sophistication tiers. CAGRs were derived from regression analysis of historical procurement patterns and regulatory mandate implementation schedules, incorporating silica glass archival technology pilot timelines and cloud object storage displacement rates as industry-specific forecast inputs.
Sensitivities concentrate around REACH substance restriction expansions affecting polycarbonate additives, seismic disruption to Japanese manufacturing concentration, and accelerated cloud migration in non-regulated enterprise segments. Cross-checking against national library procurement budget disclosures and federal archival mandate implementation progress is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market
Data Storage
North America SSD Caching Market
Data Storage
Americas Flash Memory Market
Data Storage
Ethernet Storage Market
Data Storage
APAC SSD Caching Market
Data Storage
Distributed Storage System Market
Data Storage
Global Digital Storage Devices Market
Data Storage
Middle East and Africa Data Storage Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
Wi-Fi SD Cards Market
Data Storage
Data Center Ssds Market
Data Storage
Data Storage Devices Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
HDD Head Assembly Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Multiprotocol Storage Market