
 Channel Storage Systems Market | 2026-2036
Channel Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Channel Storage Systems Market Analytics
E-commerce fulfillment is repositioning channel storage demand as retailers prioritize same-day delivery density. Dell Technologies Inc. leverages its server-storage integration to anchor enterprise warehouse deployments. Pure Storage Inc. differentiates through all-flash architectures that reduce retrieval latency in high-velocity distribution centers. Huawei Technologies Co., Ltd. competes on modular system designs tailored to Asian manufacturing footprints.
Channel storage systems integrate motorized vertical carousels, mini-load cranes, and dynamic shelving with control software to maximize cubic density and retrieval speed in facilities with constrained floor space. These systems typically operate at heights exceeding twelve meters with throughput rates measured in totes or bins per hour, serving inventory buffering and order consolidation functions. Vertical carousels dominate current installed base value due to proven reliability in small-parts handling, while robotics-enabled mini-load systems represent the fastest-expanding segment as labor costs climb. Cloud computing integration across technology layers is creating new margin pools in software subscriptions and predictive maintenance services.
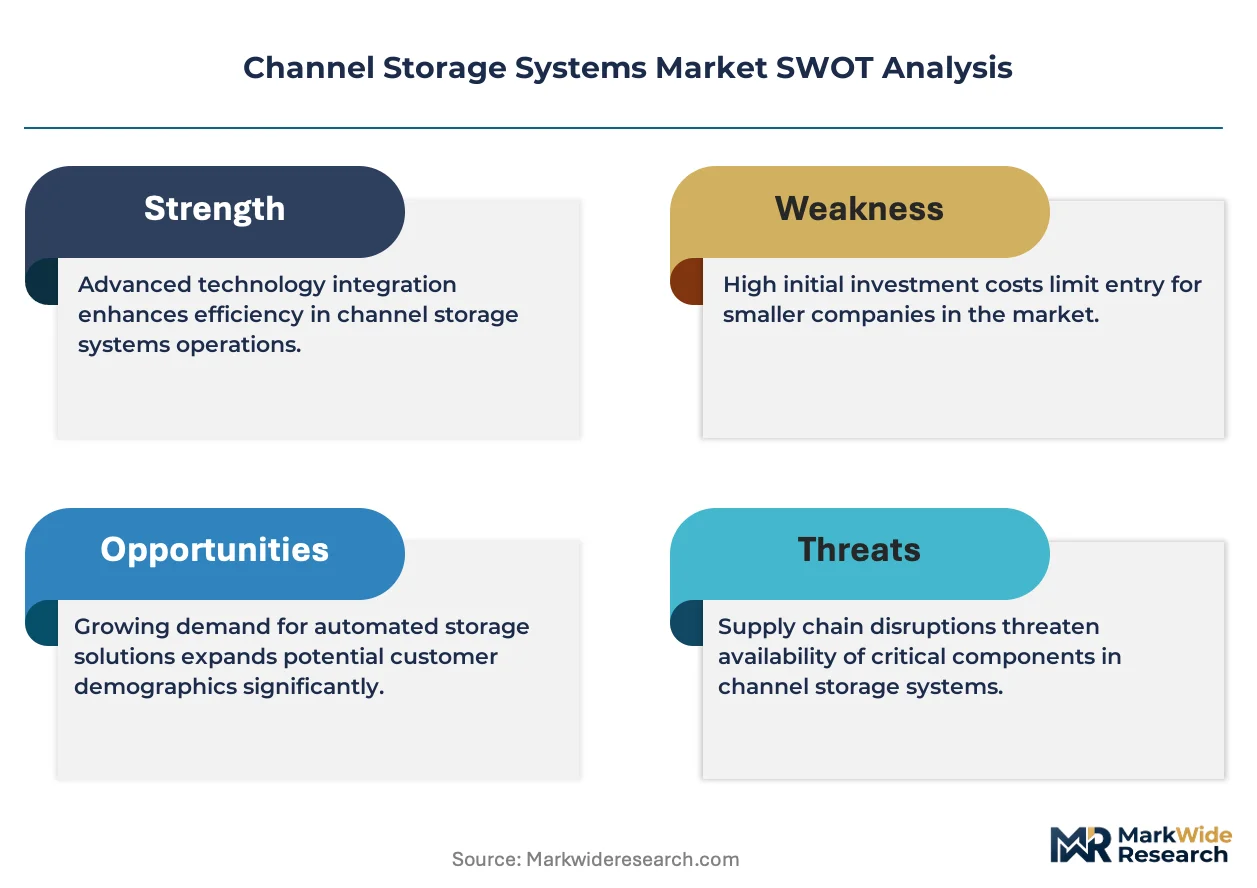
FDA traceability requirements for pharmaceutical distribution reshape channel storage specifications in the United States, mandating lot-level tracking that favors RFID-enabled systems. The EU Green Deal and REACH chemical safety standards pressure European vendors to redesign drive mechanisms and coating materials for reduced environmental impact. Stakeholders must weigh modular installation approaches against turnkey system commitments as facility lifecycles compress and reconfiguration flexibility gains strategic weight.
Market Dynamics
E-commerce fulfillment density requirements are compressing facility footprints while pushing retrieval velocity thresholds upward, forcing warehouse operators to trade horizontal expansion for vertical cubic utilization.
Growth Catalysts
- EU Green Deal efficiency mandates:The framework's energy performance standards for automated equipment accelerate replacement cycles in European distribution centers. Retrofit demand concentrates in Germany and France.
- Pharmaceutical cold-chain expansion:Temperature-controlled biologics distribution requires validated channel storage with lot-level traceability. FDA serialization rules tighten specification requirements.
- Robotics-enabled mini-load systems:Labor cost escalations in North American fulfillment networks drive adoption of crane-based automated storage and retrieval systems.
Market Restraints
- Steel and rare-earth magnet volatility:Drive motor and structural component costs fluctuate with commodity indexes, compressing system integrator margins.
- Control software vendor concentration:Proprietary warehouse management system interfaces limit interoperability, locking buyers into single-source maintenance contracts.
- Conventional fixed-rack substitution:Low-velocity SKU operations in secondary distribution nodes favor static shelving over motorized alternatives.
Strategic Opportunities
- India warehouse automation:PLI scheme incentives for logistics infrastructure and fragmented cold-chain networks create first-mover advantages for modular system deployments.
- RFID-WMS convergence:Real-time inventory visibility integration opens subscription revenue streams in pharmaceutical and aerospace verticals.
- Carbon border adjustment mechanisms:EU CBAM compliance requirements favor locally manufactured drive systems with documented supply chain emissions.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of twelve-meter vertical carousels and mini-load cranes requires cross-trained automation specialists unavailable in secondary logistics markets.
- ISO 3691-4 safety certification timelines:Collaborative robot integration with channel storage systems extends commissioning periods by four to eight months.
- Legacy WMS migration complexity:Brownfield facilities running decade-old inventory platforms face data architecture gaps when connecting to cloud-native control layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Channel Storage Systems Market |
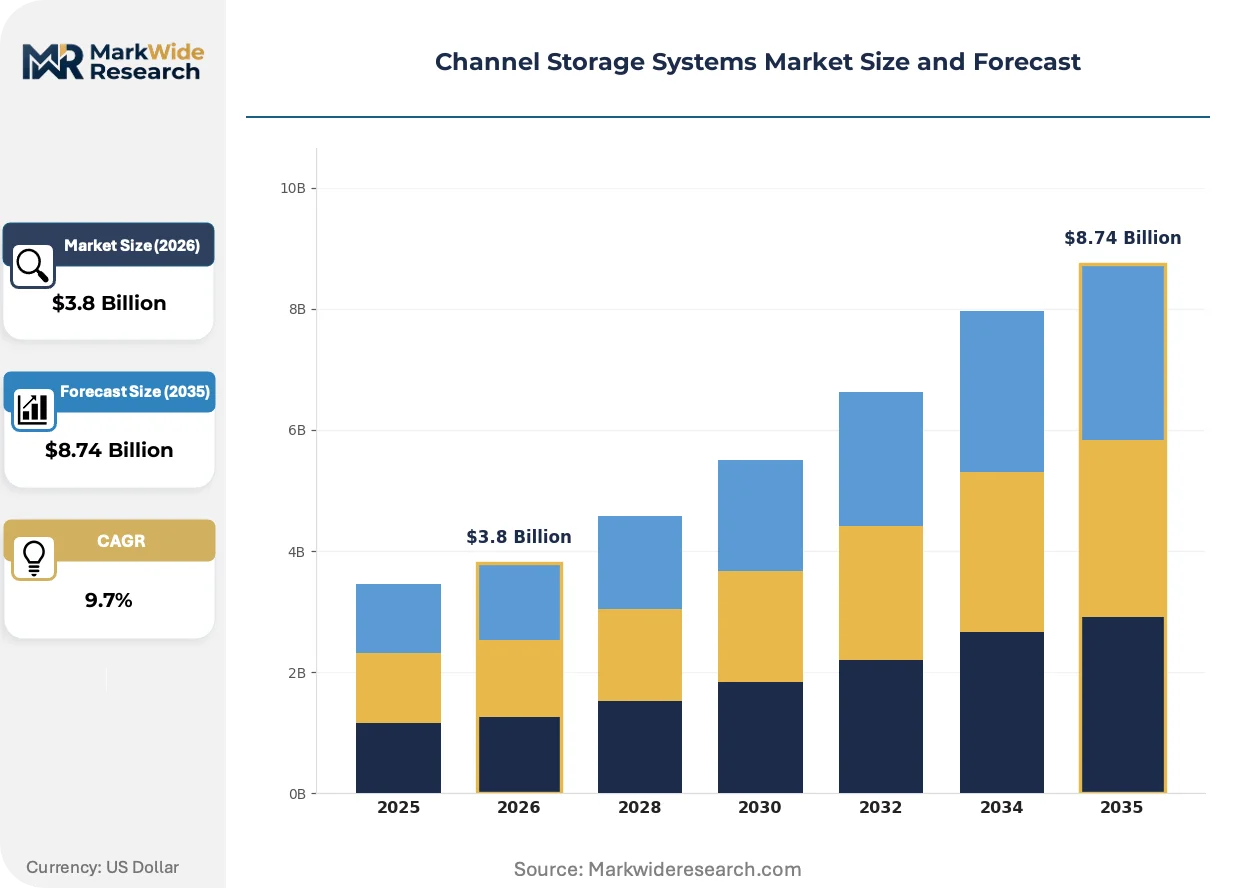
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Carousels, Mini-load Systems, Dynamic Shelving, Automated Guided Vehicles Technology: RFID, IoT Solutions, Robotics, Cloud Computing End User: Retail, Warehousing, Manufacturing, E-commerce Installation: On-site, Modular, Customized, Turnkey Systems |
| Companies Covered | Dell Technologies Inc., Hewlett Packard Enterprise Company, NetApp Inc., Cisco Systems, Inc., Broadcom Inc., IBM Corporation, Pure Storage Inc., Huawei Technologies Co., Ltd., Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Channel Storage Systems Market Evolving Landscape
Software-defined storage orchestration is decoupling hardware utilization from fixed mechanical constraints, enabling dynamic capacity allocation across fluctuating demand cycles.
All-flash storage controllers is overtaking disk-based alternatives in high-velocity fulfillment nodes. Pharmaceutical distributors and electronics retailers are adopting solid-state architectures to compress retrieval latency below fifty milliseconds. This shift is overtaking conventional hard-drive arrays in new installations, reducing mechanical failure points while raising energy density requirements.
REACH chemical safety standards are forcing coating and lubricant reformulations across European-manufactured channel storage equipment. Drive mechanism suppliers must substitute legacy hydraulic fluids with bio-based alternatives. German automotive parts distributors face the tightest compliance deadlines, accelerating supplier qualification processes.
Third-party logistics providers are unbundling storage-as-a-service from capital ownership, shifting warehouse automation from capex to opex accounting. Contract terms now structure per-pallet or per-retrieval pricing rather than equipment purchase. This model is spreading fastest in Netherlands and Belgium, where multi-tenant fulfillment campuses concentrate shared infrastructure investment.
Channel Storage Systems Market Segmentation
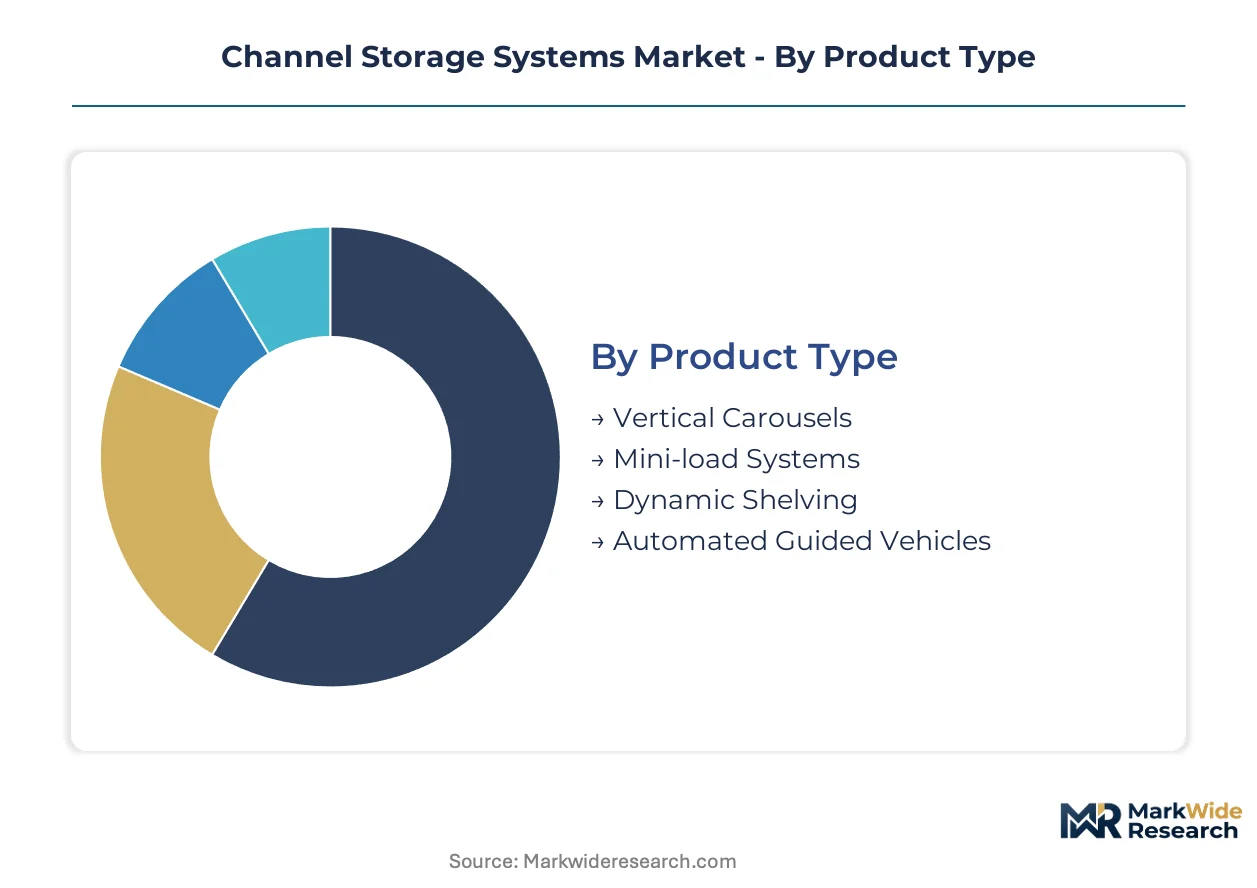
Channel storage systems fragment across hardware configurations, control layers, and deployment models that carry vastly different capital profiles. Procurement decisions hinge on matching throughput requirements to the right combination of mechanical density and software sophistication.
Product Type:
Capital intensity varies sharply across mechanical architectures, with vertical infrastructure demanding heavier foundation work than mobile alternatives.
- Vertical Carousels:Rotating shelf systems mounted on vertical tracks deliver retrieval heights exceeding twelve meters. German automotive parts distributors and pharmaceutical wholesalers in the United States anchor current installed base value, driven by proven reliability in small-parts handling and dense SKU environments.
- Mini-load Systems:Crane-based automated storage and retrieval systems operate at throughput rates measured in totes per hour. North American e-commerce fulfillment networks absorb the steepest expansion trajectory as labor cost escalations force automation upgrades in facilities with constrained floor space.
- Dynamic Shelving:Motorized shelf units adjust position based on demand patterns. European third-party logistics providers in the Netherlands favor these configurations for multi-tenant campuses with fluctuating inventory profiles.
- Automated Guided Vehicles:Mobile robots transport goods between storage zones and picking stations. Asian manufacturing footprints increasingly deploy AGV-integrated workflows to bridge fixed storage with flexible material flow.
Vertical carousels absorb the bulk of installed capacity; mini-load systems are expanding most quickly.
Technology:
Control layer investments now rival mechanical hardware in total project cost, with cloud-native architectures commanding premium pricing over legacy PLC systems.
- RFID:Radio-frequency identification enables lot-level traceability without line-of-sight scanning. FDA serialization mandates for pharmaceutical distribution reshape specifications in the United States, favoring RFID-enabled systems for validated cold-chain operations.
- IoT Solutions:Sensor networks monitor equipment health, energy consumption, and environmental conditions. Predictive maintenance subscriptions generate recurring revenue for system integrators serving high-velocity fulfillment nodes.
- Robotics:Collaborative robot integration extends commissioning timelines by four to eight months due to ISO 3691-4 safety certification requirements. Robotics-enabled configurations climb fastest in facilities facing mechatronics technician scarcity.
- Cloud Computing:Software-defined orchestration decouples hardware utilization from fixed mechanical constraints. Dynamic capacity allocation across demand cycles creates new margin pools in subscription-based control services.
RFID dominates compliance-driven pharmaceutical deployments; cloud computing is climbing fastest as brownfield facilities modernize control architectures.
End User:
Customer scale and SKU velocity determine whether standardized configurations suffice or demand customized engineering.
- Retail:Same-day delivery density requirements compress facility footprints while pushing retrieval velocity thresholds upward. Electronics retailers adopt all-flash storage controllers to compress latency below fifty milliseconds.
- Warehousing:Third-party logistics providers unbundle storage-as-a-service from capital ownership, shifting automation from capex to opex accounting with per-pallet pricing structures.
- Manufacturing:Just-in-time production lines require tight integration between channel storage and assembly sequencing. REACH chemical safety standards force coating and lubricant reformulations across European-manufactured equipment.
- E-commerce:Order volume surges drive adoption of dense storage automation in fulfillment centers. EU Green Deal energy performance standards accelerate replacement cycles in European distribution networks.
E-commerce commands the steepest investment growth; warehousing holds the largest existing footprint.
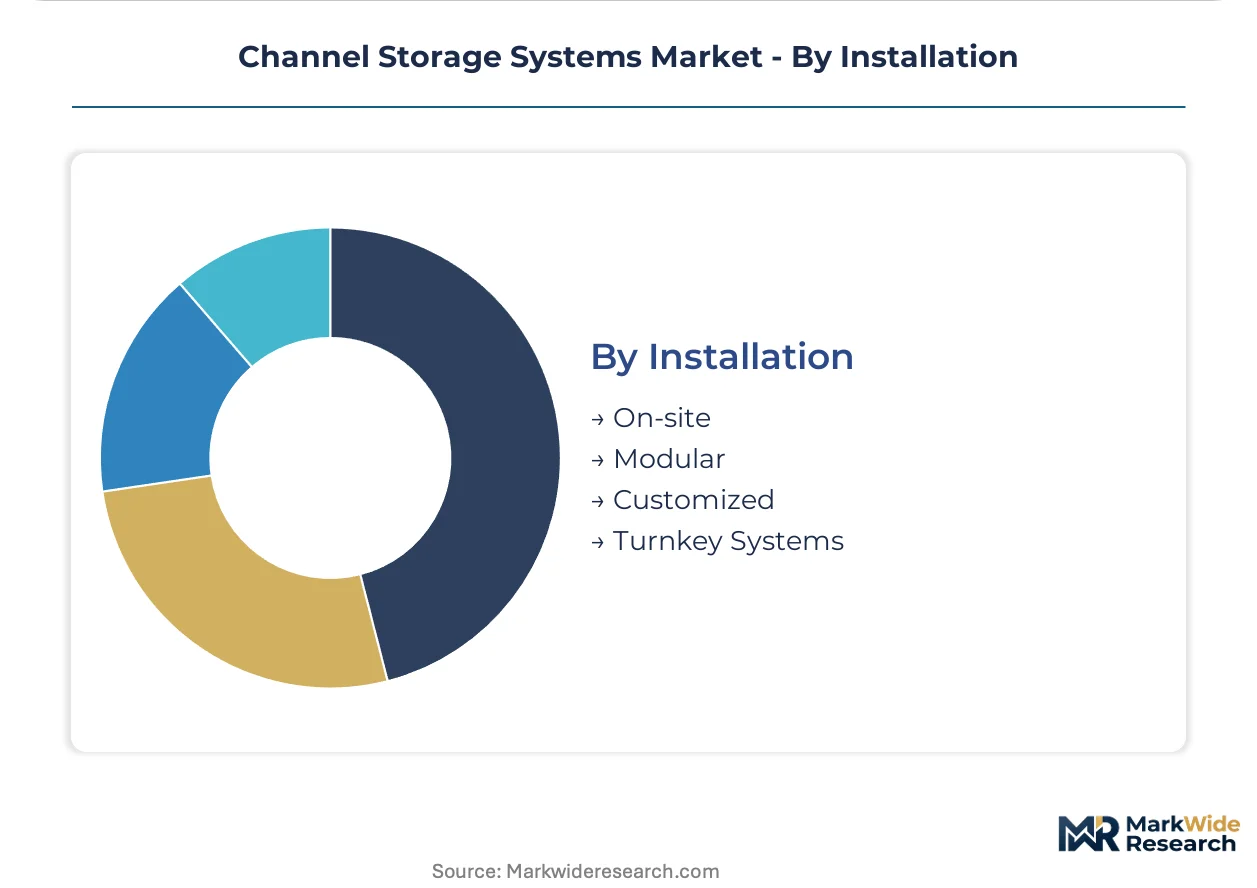
Installation:
Deployment approach determines project risk allocation and facility lifecycle flexibility as reconfiguration needs intensify.
- On-site:Traditional construction with civil works and permanent foundations suits greenfield facilities with stable demand forecasts. Steel and rare-earth magnet volatility compresses integrator margins on fixed-price contracts.
- Modular:Pre-engineered components enable phased expansion and relocation. India's PLI scheme incentives for logistics infrastructure create first-mover advantages for modular system deployments in fragmented cold-chain networks.
- Customized:Engineered-to-order solutions address unique facility constraints or integration requirements. Proprietary warehouse management system interfaces limit interoperability, locking buyers into single-source maintenance contracts.
- Turnkey Systems:Single-source responsibility for design, installation, and commissioning reduces coordination burden. Brownfield facilities running decade-old inventory platforms face data architecture gaps when connecting to cloud-native control layers.
Turnkey systems hold the majority of legacy commitments; modular approaches are gaining share fastest as facility lifecycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Netherlands and special economic zones in India concentrate new channel storage deployments as logistics operators chase tax-advantaged automation infrastructure.
Germany
Automotive parts distributors in Stuttgart and pharmaceutical wholesalers in Frankfurt drive dense vertical carousel installations. EU Green Deal energy performance standards accelerate replacement cycles in Baden-Württemberg facilities. The KBA automotive regulator coordinates with ECHA on REACH-compliant coating materials for warehouse equipment.
United States
E-commerce fulfillment networks in Pennsylvania and Ohio absorb mini-load crane systems as labor costs climb. FDA serialization mandates for pharmaceutical cold-chain reshape specifications in New Jersey distribution corridors. Dallas-Fort Worth logistics campuses anchor RFID-enabled traceability deployments for biologics handling.
China
MIIT industrial upgrade programs subsidize automated storage in Yangtze River Delta manufacturing parks. Dual carbon goals pressure Shenzhen and Suzhou facilities to retrofit vertical carousels with energy-efficient drive systems. Shanghai free trade zones pilot cloud-native warehouse management integration.
India
PLI scheme incentives for logistics infrastructure concentrate modular system deployments in Maharashtra and Gujarat. CDSCO pharmaceutical traceability rules tighten cold-chain specifications in Mumbai-Pune distribution corridors. Telangana's Hyderabad pharma cluster validates RFID-enabled channel storage for export compliance.
Netherlands
Third-party logistics providers in Rotterdam and Venlo unbundle storage-as-a-service with per-pallet pricing structures. ECHA REACH standards force lubricant reformulations in Dutch-manufactured equipment. Eindhoven's multi-tenant fulfillment campuses pioneer dynamic shelving for fluctuating inventory profiles.
Channel Storage Systems Market Competitive Landscape
Top-tier vendors anchor enterprise warehouse deployments, while mid-tier specialists compete on modular configurations for regional logistics operators. The vendor base separates into three strategic archetypes: server-storage integrators leveraging data center expertise, all-flash architecture specialists, and modular system fabricators serving Asian manufacturing footprints. Consolidation pressure intensifies as control software subscriptions create recurring revenue pools. Geographic expansion and technology licensing dominate competitive moves as steel volatility compresses hardware margins.
Among server-storage integrators, Dell Technologies Inc. and Hewlett Packard Enterprise Company occupy positions where data center expertise transfers to warehouse automation contexts. Pure Storage Inc. exemplifies the all-flash architecture tier, while Huawei Technologies Co., Ltd. sits within the modular fabrication segment. These three anchors represent distinct strategic vectors: integration breadth, latency reduction specialization, and regional manufacturing adaptation. Each archetype faces different margin pressures from cloud-native control layer adoption.
| Leading Market Players |
|---|
| Dell Technologies Inc. |
| Hewlett Packard Enterprise Company |
| NetApp Inc. |
| Cisco Systems, Inc. |
| Broadcom Inc. |
| IBM Corporation |
| Pure Storage Inc. |
| Huawei Technologies Co., Ltd. |
| Fujitsu Limited |
| Others |
Value Network & Pricing Analysis
FDA serialization mandates for pharmaceutical cold-chain operations are forcing system integrators to absorb RFID hardware costs upfront, compressing margins on turnkey contracts while shifting pricing power toward buyers with validated qualification requirements. Steel and rare-earth magnet volatility feeds back into procurement strategies, with German automotive distributors now demanding fixed-price multi-year agreements to hedge input cost exposure.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent attach to modular vertical carousel configurations, while spot inventory of standardized mini-load crane components trades at discounts to contract manufacturing schedules. Three-tier pricing structure across premium certified, standard compliant, and economy non-validated levels segments the installed base, with ISO 3691-4 safety certification commanding the widest spreads. Pricing pressure stems from cloud-native control layer commoditization as software subscriptions displace perpetual licensing. Third-party logistics providers exhibit highest price sensitivity due to per-pallet opex accounting models, whereas pharmaceutical wholesalers prioritize traceability assurance over unit cost.
Supply Chain Analysis
CE marking and FDA 21 CFR Part 11 qualification gates restrict drive motor sourcing to qualified suppliers in Germany, Japan, and the United States, excluding lower-cost Asian alternatives from validated deployments. Rare-earth permanent magnets for servo motors draw from concentrated Chinese processing capacity, while precision steel rack components source from German and South Korean rolling mills. Single-source vulnerability in neodymium magnet supply creates exposure to export restriction shocks. Distribution runs through system integrator channels with captive installation crews, limiting direct OEM access to end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Control software subscription revenue pools are triggering a vertical-integration race, with hardware incumbents acquiring cloud-native orchestration layers to capture recurring margin streams.
For Market Incumbents: Hedge against margin compression in mechanical hardware by acquiring predictive maintenance software specialists and securing captive rare-earth magnet supply through offtake agreements with Australian and Canadian mining projects. Proprietary WMS interface lock-in faces regulatory pressure from EU interoperability mandates, threatening maintenance contract renewal rates. For New Entrants and Emerging Players: Regional system integrators in India's PLI-subsidized logistics corridors represent the most penetrable channel partner type, offering localized commissioning capabilities without incumbent legacy WMS entanglements. White-space targets include modular cold-chain deployments in Telangana's pharma cluster and dynamic shelving retrofits in Netherlands multi-tenant campuses. Lead with subscription-based control layer pricing to displace capex-heavy turnkey competitors. For Investors and Strategic Acquirers: The window for entry favors cloud-native control layer specialists with ISO 3691-4 safety certification pipelines already in progress. Long-term viability hinges on software-defined orchestration capabilities decoupled from fixed mechanical hardware. Watch for EU CBAM compliance documentation requirements as the inflection signal favoring European-manufactured drive systems with verified supply chain emissions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Australian and Canadian mining offtakes secure neodymium supply chains against Chinese export restrictions. |
| Cloud-Native Control Layer Acquisition | Software subscriptions capture recurring revenue pools as hardware margins compress from steel volatility. |
| ISO 3691-4 Safety Certification Fast-Track | Accelerated collaborative robot integration timelines reduce commissioning delays in robotics-enabled mini-load deployments. |
| RFID-WMS Convergence Partnership | FDA serialization compliance creates subscription revenue streams in pharmaceutical and aerospace verticals. |
| Modular System Fabrication Scale-Up | India PLI scheme incentives concentrate first-mover advantages in fragmented cold-chain networks. |
Research Methodology
Trade association filings, customs import records, and equipment registration databases formed the secondary backbone, cross-referenced against primary interviews with warehouse automation directors, mechatronics procurement leads, and third-party logistics operators. Bottom-up and top-down triangulation validated installed base estimates against capital expenditure disclosures and facility commissioning records.
Bottom-up modeling of unit shipments by product type and technology layer converged with top-down demand sizing from e-commerce fulfillment square footage expansion and pharmaceutical cold-chain capacity additions. Segmentation dimensions spanned mechanical architecture, control technology, end-use vertical, and installation approach across the projection horizon. CAGRs derived from logistic curve penetration modeling of automation intensity per facility, with inputs including labor cost trajectories and EU Green Deal replacement cycle acceleration.
Caveats apply where steel and rare-earth commodity spikes, FDA traceability rule delays, or mechatronics technician availability constraints could materially shift the outlook. A model refresh is warranted upon material change in EU CBAM implementation timelines or PLI scheme incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Middle East and Africa Data Storage Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
Recordable Optical Disc Market
Data Storage
Ireland Data Center Storage Market
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
Blu-Ray Drive Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Global Portable Data Storage Market
Data Storage
Universal Flash Storage Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
Optical Disk Market
Data Storage
Solid State Array Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Europe Flash Memory Market