
 HIPAA-Compliant Messaging Services Market | 2026-2036
HIPAA-Compliant Messaging Services Market Size, Share, and Industry Trends Forecast 2026-2036
HIPAA-Compliant Messaging Services Market Foresight
The United States is narrowing the gap between legacy pager networks and modern encrypted messaging platforms across its hospital systems. TigerConnect leverages deep EHR integration to sustain enterprise-grade deployments in large health systems. Spok anchors its position through specialized critical alerting infrastructure that competes with newer cloud-native entrants. OhMD differentiates by focusing on direct physician-patient texting workflows that occupy a distinct niche in ambulatory settings.
HIPAA-compliant messaging services constitute encrypted communication platforms engineered to meet the technical safeguards of the HIPAA Security Rule, including end-to-end encryption, access controls, audit logging, and automatic message expiration. These systems serve the primary commercial purpose of enabling real-time clinical coordination while preventing unauthorized disclosure of protected health information. Cloud-based technology deployments lead the infrastructure mix due to scalability advantages and reduced on-site maintenance burdens for IT departments. Secure messaging products command the largest share of platform spending as hospitals prioritize replacing unencrypted SMS and consumer applications. Patient engagement modules represent the fastest-expanding product category as value-based care models incentivize proactive outreach and automated follow-up protocols.
FDA oversight of clinical decision support integrations, HIPAA enforcement by the Office for Civil Rights, and state-level medical board telehealth regulations collectively shape product development priorities and go-to-market strategies for platform vendors. The HITECH Act's breach notification provisions create direct financial liability that accelerates replacement of non-compliant communication tools. Stakeholders must monitor evolving state privacy laws that extend beyond federal HIPAA minimums to impose additional consent and data localization requirements.
Market Dynamics
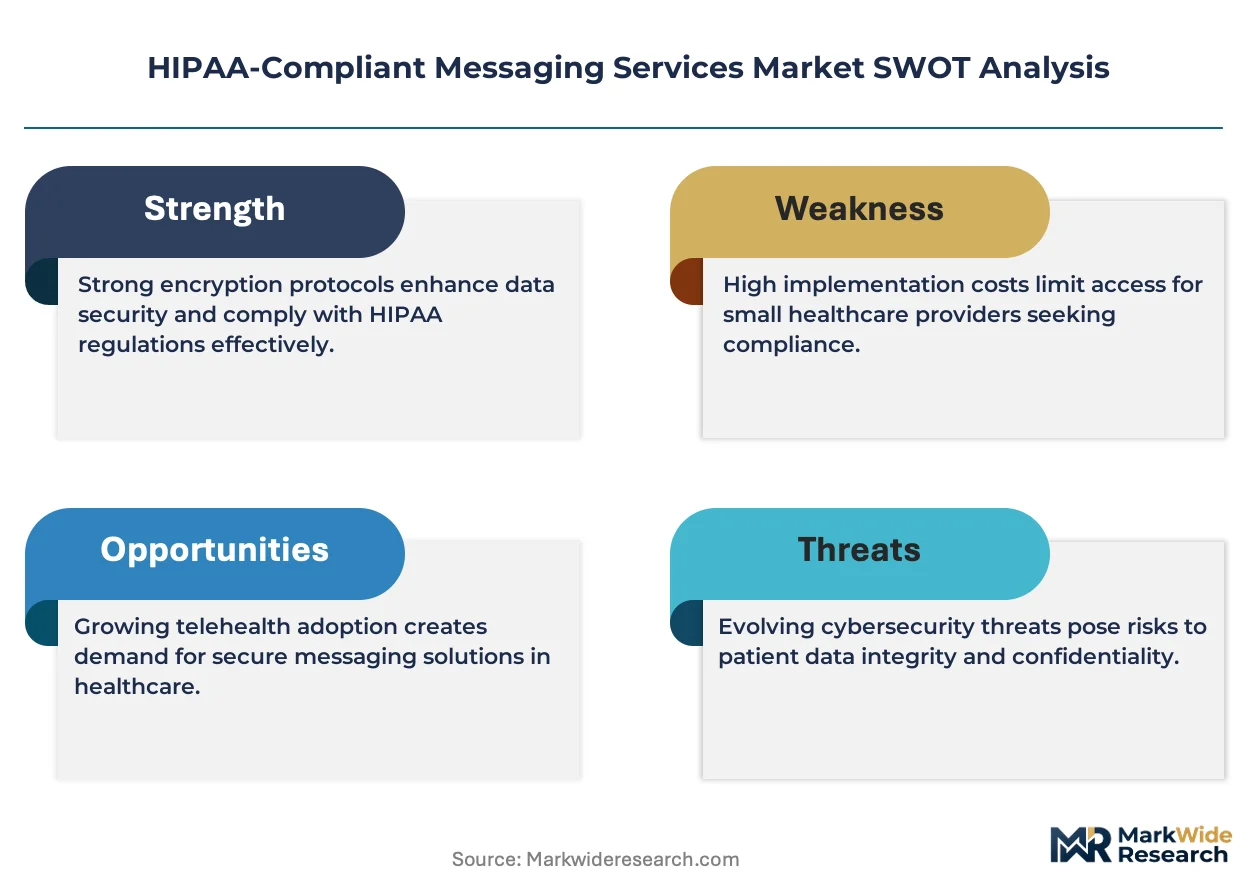
The migration from legacy pager infrastructure to cloud-native encrypted platforms is compressing replacement cycles across US hospital systems. This structural shift forces IT departments to consolidate fragmented communication tools into unified clinical collaboration suites.
Growth Catalysts
- HITECH Act Breach Notification:Direct financial liability provisions accelerate retirement of non-compliant consumer messaging apps in favor of audited secure platforms.
- Value-Based Care Reimbursement:Medicare's quality metrics incentivize automated patient outreach and care coordination workflows that require HIPAA-compliant engagement channels.
- Cloud Infrastructure Maturation:Scalable SaaS architectures reduce on-premise maintenance burdens for resource-constrained rural health systems.
Market Restraints
- Interoperability Fragmentation:Proprietary EHR integration protocols create vendor lock-in that limits platform switching flexibility.
- State Privacy Law Proliferation:California's CCPA and emerging state-level consent requirements impose compliance burdens beyond federal HIPAA minimums.
- Legacy Hardware Amortization:Capitalized pager network investments delay full cloud migration for budget-constrained critical access hospitals.
Strategic Opportunities
- Post-Acute Care Penetration:Skilled nursing facilities and home health agencies remain underserved by enterprise-grade secure messaging solutions.
- Remote Patient Monitoring Convergence:Integration of biometric data streams with encrypted messaging creates continuous care coordination platforms.
- Medicaid Expansion Tailwinds:State-level program growth generates demand for patient engagement tools serving newly insured populations.
Industry Challenges
- Clinical Workflow Integration:Nursing staff resistance to additional login credentials and interface training slows platform adoption.
- Audit Log Architecture:Message retention policies must balance OCR investigation requirements against storage cost escalation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HIPAA-Compliant Messaging Services Market |
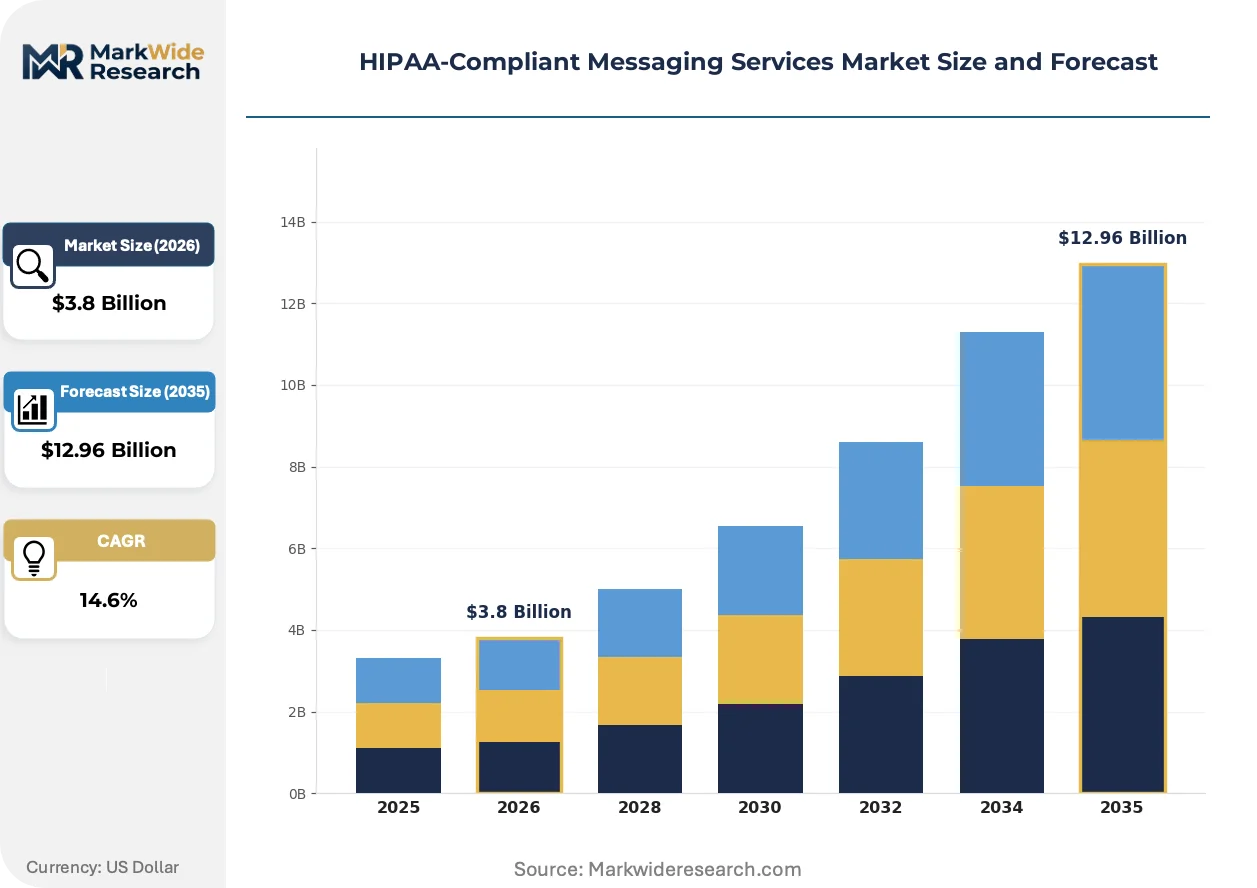
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Secure Messaging, Workflow Automation, Patient Engagement, Document Sharing Technology: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Applications End User: Healthcare Providers, Clinics, Hospitals, Telehealth Services Compliance Level: Full Compliance, Partial Compliance, Risk Assessment Tools, Certification Support |
| Companies Covered | TigerConnect, Hypercare, OnPage, QliqSOFT, Klara, Spok, OhMD, Conversive, Luma Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HIPAA-Compliant Messaging Services Market Shifts & Advancements
Artificial intelligence is embedding into clinical communication workflows, compressing response times and automating routine coordination tasks. These capabilities are reshaping vendor competitive positioning around intelligent routing rather than basic encryption.
Natural language processing is collapsing the distinction between structured clinical documentation and informal care team messaging. Large health systems including Kaiser Permanente and Mayo Clinic are deploying ambient clinical intelligence that captures bedside conversations into EHR-integrated secure threads. This convergence eliminates redundant documentation steps and accelerates care transitions.
FDA's guidance on clinical decision support software is tightening oversight of AI-embedded messaging features that trigger diagnostic or treatment recommendations. Platform vendors must now navigate 510(k) pathways for algorithmic alerting functions previously treated as administrative. Academic medical centers are delaying deployment of predictive sepsis alerts and similar tools pending regulatory clarity.
Physician practices are consolidating vendor relationships around unified communication suites rather than maintaining separate tools for internal coordination and patient outreach. Group purchasing organizations are negotiating enterprise licenses that bundle secure messaging with telehealth and scheduling modules. This preference consolidation favors platforms with broad feature depth over point solutions in ambulatory settings.
HIPAA-Compliant Messaging Services Market Segmentation
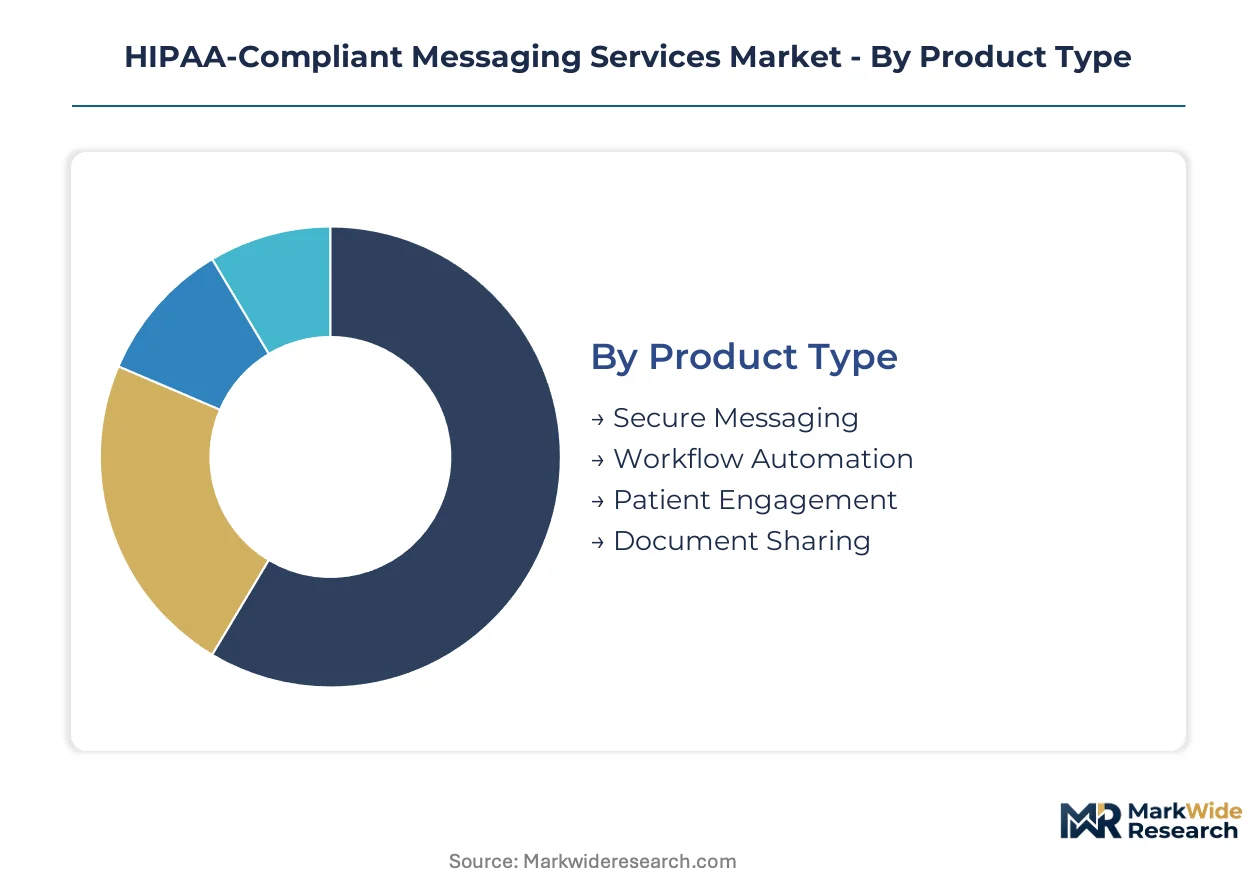
HIPAA-compliant messaging platforms serve divergent operational needs across clinical workflows, infrastructure constraints, and regulatory postures. Segmentation reveals how vendors architect solutions for distinct buyer priorities rather than uniform deployment patterns.
Product Type:
The use-case spectrum spans real-time clinical coordination, administrative automation, patient-facing outreach, and document exchange workflows.
- Secure Messaging:End-to-end encrypted channels replace unencrypted SMS and consumer applications for care team communication. Hospitals prioritize this segment to eliminate OCR breach liability from Shadow IT adoption. The dominant share belongs to Secure Messaging, while Patient Engagement is closing the gap fastest.
- Patient Engagement:Automated appointment reminders, medication adherence prompts, and post-discharge follow-up protocols integrate with EHR scheduling modules. Value-based care contracts from Medicare Advantage plans drive ambulatory investment in proactive outreach infrastructure.
- Workflow Automation:Intelligent routing algorithms accelerate specialist consults and critical lab result delivery through priority-escalation rules. Nursing staff resistance to additional interface training constrains penetration outside academic medical centers.
- Document Sharing:HIPAA-compliant image and document transmission replaces unsecured email for radiology reports and referral packets. Rural health systems leverage this capability to extend specialist access without dedicated teleradiology infrastructure.
Secure Messaging commands the largest platform expenditure, though Patient Engagement exhibits the steepest expansion trajectory as reimbursement models shift toward outcomes accountability.
Technology:
Deployment architecture selection reflects IT resource availability, legacy system amortization schedules, and cybersecurity risk tolerance across buyer segments.
- Cloud-Based:Multi-tenant SaaS platforms eliminate on-premise server maintenance and accelerate disaster recovery capabilities. Critical access hospitals in rural Texas and Montana adopt this model to overcome staffing constraints for 24/7 infrastructure monitoring.
- Hybrid Solutions:Sensitive patient data resides on-premise while collaboration features leverage cloud scalability. Large integrated delivery networks in California deploy this architecture to satisfy internal security governance committees.
- On-Premises:Dedicated hardware installations serve organizations with capitalized data center investments and stringent data localization requirements. State psychiatric facilities and correctional health systems favor this model for air-gapped network compliance.
- Mobile Applications:Native iOS and Android clients extend secure messaging to bring-your-own-device policies and community-based care teams. Home health agencies driving the fastest adoption as field nurses require real-time physician access during patient visits.
Cloud-Based deployments generate the majority of new vendor bookings, yet Hybrid Solutions are gaining share fastest among health systems navigating internal security review processes.
End User:
Buyer sophistication and procurement scale vary dramatically across institutional settings, from single-physician practices to multi-state health systems.
- Hospitals:Enterprise-grade deployments demand deep EHR integration, role-based access controls, and 99.999% uptime SLAs. The largest health systems in New York and Massachusetts consolidate communication tools into unified clinical collaboration suites.
- Telehealth Services:Virtual-first care models require asynchronous messaging alongside synchronous video to manage patient panels efficiently. Medicare reimbursement expansion for remote therapeutic monitoring accelerates platform procurement.
- Healthcare Providers:Physician practices and group purchasing organizations negotiate bundled licenses spanning secure messaging, telehealth, and scheduling modules. Consolidation around unified suites favors vendors with broad feature depth over point solutions.
- Clinics:Federally qualified health centers and urgent care chains prioritize patient engagement modules for no-show reduction and chronic disease management. Medicaid expansion states generate concentrated demand for outreach tools serving newly insured populations.
Hospitals anchor vendor revenue, though Telehealth Services are expanding most quickly as virtual care platforms scale beyond pandemic-era emergency adoption.
Compliance Level:
Regulatory posture segmentation reflects organizational maturity in risk management and OCR audit history.
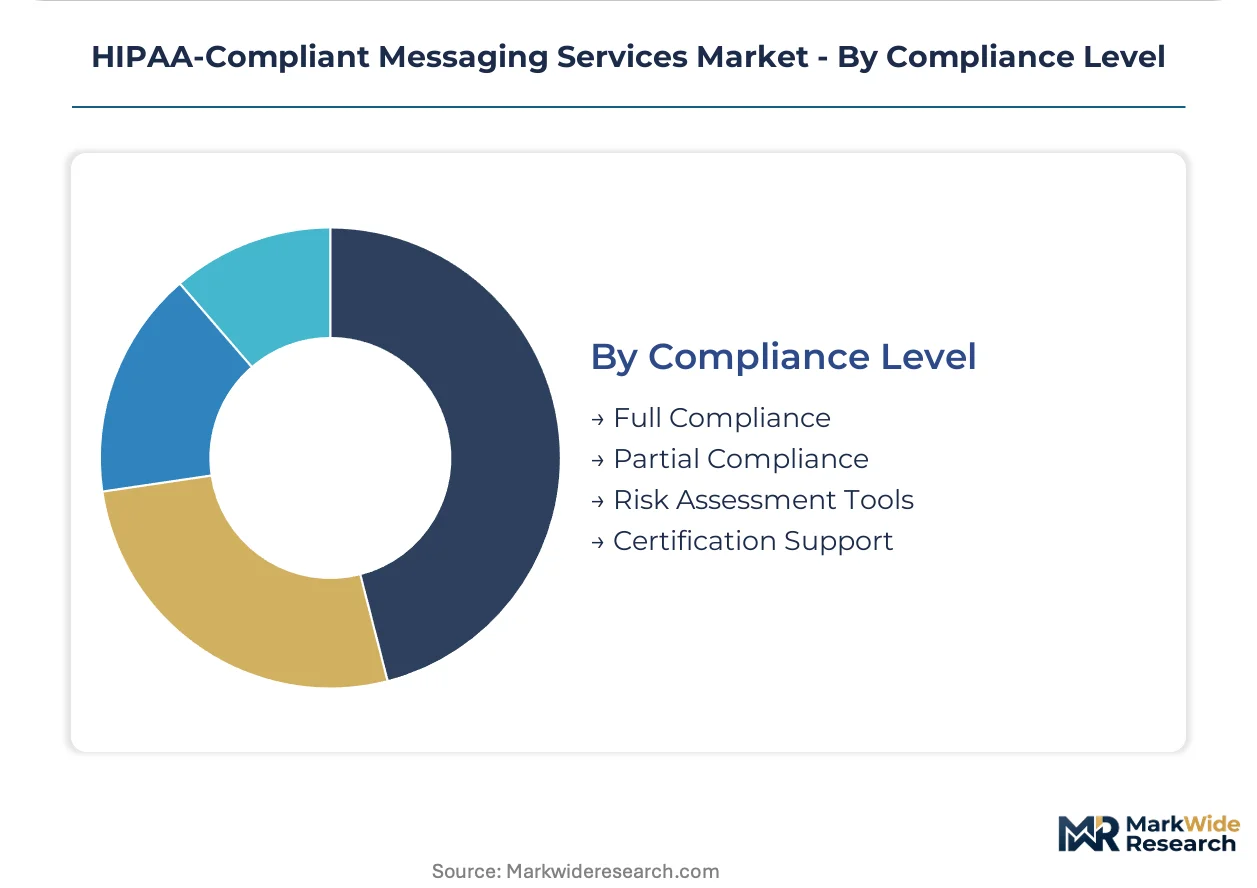
- Full Compliance:Platforms engineered to satisfy all HIPAA Security Rule technical safeguards including encryption, access controls, audit logging, and business associate agreements. Organizations with prior breach settlements mandate this tier to demonstrate good-faith remediation.
- Certification Support:Vendor-provided documentation and implementation guidance accelerates HITRUST or SOC 2 attestation processes. Mid-sized regional health systems leverage these services to satisfy payer contract requirements.
- Risk Assessment Tools:Built-in gap analysis and remediation workflows help organizations identify Shadow IT and non-compliant communication channels. Compliance officers at community hospitals use these features to prioritize IT security investments.
- Partial Compliance:Limited-feature deployments for administrative use cases that exclude protected health information transmission. Skilled nursing facilities adopt this tier for family communication while maintaining paper-based clinical documentation.
Full Compliance solutions dominate enterprise procurement, while Certification Support is climbing the fastest as mid-market buyers accelerate formal attestation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform vendors concentrate engineering resources in jurisdictions with stringent healthcare privacy enforcement and mature cloud infrastructure. Regulatory fragmentation across state and national boundaries shapes deployment architecture decisions.
United States
The Office for Civil Rights enforces HIPAA Security Rule penalties exceeding $1.5 million per violation category, compelling health systems to retire consumer messaging apps. The HITECH Act's breach notification provisions create direct financial liability that accelerates audited platform procurement. Large integrated delivery networks in New York and Massachusetts consolidate communication tools into unified clinical collaboration suites.
Germany
Federal data protection authorities interpret GDPR Article 9 health data provisions with strict consent requirements that exceed HIPAA technical safeguards. The Bundesdatenschutzgesetz mandates data localization for public health insurance fund processing. Medical technology clusters in Baden-Württemberg and Bavaria drive demand for hybrid deployment architectures that satisfy internal security governance committees.
United Kingdom
NHS Digital's Data Security and Protection Toolkit mandates encrypted communication standards for all organizations accessing patient records through national infrastructure. The National Data Guardian's guidance on instant messaging creates procurement specifications that favor platforms with native EHR integration. London-based academic medical centers pilot ambient clinical intelligence that captures bedside conversations into secure threads.
Canada
Health Canada's guidance on digital health technologies aligns with provincial privacy commissioner enforcement of PIPEDA and health-sector-specific statutes. Ontario's eHealth Ontario infrastructure creates interoperability requirements that favor vendors with established provincial integration partnerships. Toronto and Vancouver health networks drive enterprise-grade deployment demand across multi-site hospital systems.
Australia
The Therapeutic Goods Administration regulates clinical decision support features embedded within messaging platforms as medical devices. The Australian Digital Health Agency's interoperability frameworks mandate FHIR-compliant interfaces for secure care coordination. Sydney and Melbourne health districts consolidate vendor relationships around unified communication suites rather than fragmented point solutions.
HIPAA-Compliant Messaging Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying encryption modules and audit logging infrastructure. The vendor base organizes around three strategic archetypes: enterprise-grade suite providers with deep EHR integration, point-solution specialists focused on specific clinical workflows, and telehealth-native platforms that bundle messaging with virtual visit capabilities. Consolidation pressure favors acquisition of niche workflow tools by incumbent suite vendors seeking feature depth expansion.
Among established platform vendors, TigerConnect, Spok, and OhMD occupy distinct positioning tiers that exemplify market segmentation strategies. TigerConnect represents the enterprise integration archetype with health system-scale deployments. Spok anchors the critical alerting specialization segment through legacy infrastructure relationships. OhMD exemplifies the ambulatory-focused direct engagement model serving physician-patient texting workflows. These three vendors collectively illustrate how competitive differentiation concentrates around workflow depth rather than encryption baseline compliance.
| Leading Market Players |
|---|
| TigerConnect |
| Hypercare |
| OnPage |
| QliqSOFT |
| Klara |
| Spok |
| OhMD |
| Conversive |
| Luma Health |
| Others |
Supply & Pricing Matrix
Single-source dependency on AWS and Microsoft Azure for cloud infrastructure determines both pricing tier spreads and supply chain shape in HIPAA-compliant messaging services. The concentration of certified data center capacity in Northern Virginia and Oregon creates regional cost differentials that vendors pass through as geography-adjusted SaaS tiers.
Pricing Analysis
The HITECH Act's breach notification provisions dictate the pricing tier structure across the HIPAA-compliant messaging market. Three-tier pricing structure across enterprise, mid-market, and critical access levels segments buyers by EHR integration depth and audit log retention requirements. Price differentiation hinges on HITRUST certification status and dedicated account management tiers. Cost compression in the mid-market tier is intensifying because GPOs negotiate bundled licenses spanning telehealth and scheduling modules. Critical access hospitals in rural Montana exhibit highest price sensitivity, while integrated delivery networks in Massachusetts demonstrate lowest sensitivity due to breach liability risk.
Supply Chain Analysis
Tariff exposure between the United States and China for semiconductor components dominates supply chain risk assessment for on-premise encryption hardware. Cloud infrastructure draws from data center clusters in Virginia, Oregon, and Ohio, with backup capacity in Texas and Arizona. Raw material dependencies include cryptographic processors, solid-state storage arrays, and fiber optic transmission equipment. Single-source vulnerability persists for FIPS 140-2 validated hardware security modules manufactured by a concentrated vendor base. Distribution runs through direct enterprise sales teams supplemented by channel partners serving ambulatory practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HIPAA-compliant messaging services constitute a high-growth disruption as ambient clinical intelligence collapses documentation and communication workflows. The FDA's tightening oversight of AI-embedded clinical decision support creates a regulatory inflection that separates compliant platforms from legacy entrants.
For Market Incumbents: Build switching-cost moats through deep EHR integration that embeds messaging into clinical workflow automation. Consolidate fragmented communication tools into unified suites before cloud-native challengers achieve enterprise scale. TigerConnect's health system deployments demonstrate how API depth repels point-solution substitution. Invest in HITRUST certification maintenance as payer contracts mandate attestation. For New Entrants and Emerging Players: Build out post-acute care penetration where skilled nursing facilities and home health agencies remain underserved by enterprise-grade platforms. Target Medicaid expansion states generating demand for patient engagement tools serving newly insured populations. Develop native mobile-first architectures for field-based nursing workflows rather than retrofitting hospital-centric designs. For Investors and Strategic Acquirers: Workflow automation specialists with proven FDA 510(k) pathways represent the highest-conviction acquisition target archetype. Long-term viability over the next decade rests on AI integration depth rather than encryption baseline compliance. Monitor FDA guidance clarity on clinical decision support software as the signal indicating which platform vendors can deploy predictive alerting without regulatory delay.| Strategic Initiative | Industry Significance |
|---|---|
| HITRUST Certification Investment | Accelerates enterprise procurement cycles by satisfying payer contract requirements. |
| EHR Integration Partnership | Epic and Cerner native embedding creates switching costs that repel challenger platforms. |
| Post-Acute Care Expansion | Skilled nursing facility penetration captures Medicare reimbursement tailwinds. |
| AI Clinical Decision Support | FDA 510(k) pathway completion separates compliant platforms from administrative-only tools. |
| Medicaid State Contracting | Federally qualified health center procurement concentrates in expansion states. |
Research Methodology
Initial hypotheses were tested against primary input from hospital CIOs, GPO contracts managers, biomedical engineers, and telehealth platform architects and refined through secondary validation. Primary interviews with health system IT directors and ambulatory practice administrators supplied deployment timeline and procurement criteria data. Secondary sources included CMS Medicare reimbursement databases, HHS breach notification reports, hospital procurement records, and FDA 510(k) submission filings. Bottom-up sizing of vendor bookings and top-down triangulation against health IT expenditure surveys converged on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization scale, EHR integration complexity, compliance tier, and regional regulatory enforcement pattern. CAGRs were derived from fitted growth curves calibrated to historical adoption rates and policy inflection points. Forecast inputs incorporated HITECH Act penalty escalation schedules and Medicare Advantage quality metric weightings.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native challengers or regulatory acceleration by the FDA would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
South Africa Digital Twin Market
Digital Solutions
Thin Client Market
Digital Solutions
Barcode Software Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Weather Information Technologies Market