
 Barcode Software Market | 2026-2036
Barcode Software Market Size, Share, and Industry Trends Forecast 2026-2036
Barcode Software Market Analysis
Enterprise-grade compliance tier is rotating toward the center of buyer evaluation criteria as pharmaceutical and food traceability mandates tighten. BarTender leverages deep specialization in regulated label design to anchor premium positioning. SOS Inventory Software LLC competes through native integration with QuickBooks and Xero accounting ecosystems. Sortly Inc. differentiates via visual inventory interfaces that reduce training overhead for small and mid-sized operations.
Barcode software comprises applications that generate, encode, decode, and manage machine-readable symbologies using ISO/IEC 15415 print quality specifications and GS1 application identifiers for supply chain interoperability. Its primary purpose is eliminating manual data entry errors while enabling real-time asset tracking across distributed operations. Cloud solutions command expanding share as subscription economics displace perpetual license models and API connectivity becomes non-negotiable. 2D barcode and QR code technologies lead technology adoption as they encode richer data sets for batch-level traceability. Retail and logistics end users represent the deepest margin pools due to volume density and recurring integration service needs.
FDA serialization mandates under the Drug Supply Chain Security Act and EU FMD (Falsified Medicines Directive) compliance deadlines reshape product roadmaps for vendors serving pharmaceutical clients. GS1 standards and ISO/IEC 15434 data syntax frameworks determine interoperability thresholds for cross-border trade documentation. Stakeholders must monitor how FDA DSCSA enforcement phases and EU MDR device labeling expansion alter validation requirements for barcode generation platforms.
Market Dynamics
Cloud migration and API-first architectures are compressing procurement cycles while forcing incumbent vendors to rearchitect delivery models around subscription economics and real-time data exchange protocols.
Growth Catalysts
- FDA DSCSA Enforcement:Pharmaceutical serialization mandates in the United States compel wholesale distributors and manufacturers to deploy validated barcode generation platforms for unit-level traceability compliance.
- QuickBooks Ecosystem Penetration:Small business accounting software integration creates pull-through demand for inventory modules that embed native barcode functionality without standalone IT infrastructure.
- GS1 Standards Harmonization:Cross-border adoption of ISO/IEC 15434 data syntax frameworks enables single-platform label designs that satisfy multiple national customs authorities simultaneously.
Market Restraints
- Perpetual License Stranded Assets:Enterprises with capitalized on-premise deployments face write-down pressure when migrating to SaaS models, slowing replacement cycles in manufacturing verticals.
- Label Substrate Cost Volatility:Thermal transfer ribbon and synthetic media prices fluctuate with petrochemical feedstock indices, squeezing margins for high-volume print operations in logistics.
- Legacy Hardware Interoperability:Decades of installed base scanners and printers using proprietary command sets create technical debt that complicates cloud-native software rollouts.
Strategic Opportunities
- EU MDR Device Labeling Expansion:Medical device manufacturers must implement unique device identification (UDI) barcoding across Class I-III products, opening compliance software contracts.
- Indonesia Digital Tax Integration:Southeast Asian retail chains require QR-coded fiscal receipts that connect directly to national tax authority APIs, creating localized platform demand.
- Computer Vision Convergence:Smartphone camera-based scanning apps are displacing dedicated hardware in field service and last-mile delivery workflows, enabling software-only market entry.
Industry Challenges
- Validation Documentation Burden:Pharmaceutical and food clients require 21 CFR Part 11 compliant audit trails for every label template change, extending implementation timelines.
- Multi-Site Rollout Complexity:Enterprise deployments across distributed warehouses demand synchronized master data governance that strains mid-market vendor professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barcode Software Market |
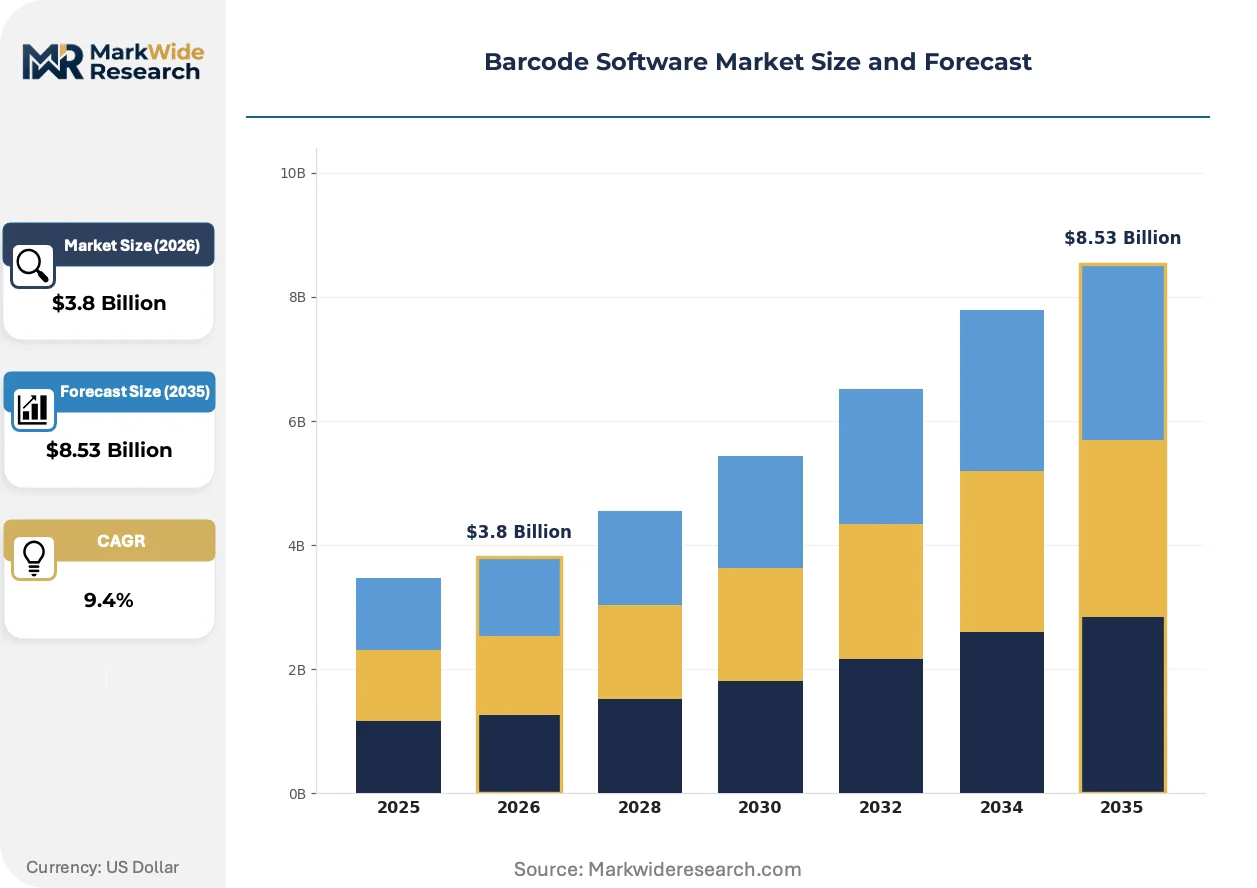
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Desktop Software, Cloud Solutions, Web-Based Applications Technology: 2D Barcode, QR Code, NFC, RFID End User: Retail, Logistics, Healthcare, Manufacturing Deployment: On-Premises, SaaS, Open Source, Hybrid |
| Companies Covered | SOS Inventory Software LLC, Label Flow, Ordoro, HandiFox, Finale Inventory, Sortly Inc., Wasp InventoryCloud, VeriPic Inc., BarTender, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barcode Software Market Emerging Trajectories
Real-time inventory visibility requirements are compressing the gap between data capture and enterprise resource planning systems, forcing architectural decisions that favor edge computing and event-driven synchronization.
2D symbology adoption is fragmenting the traditional linear barcode installed base as pharmaceutical batch records, medical device sterilization logs, and food allergen declarations require data payloads exceeding Code 128 capacity. Retail pharmacies and hospital pharmacies in Germany and Japan are replacing legacy scanners to capture GS1 DataMatrix codes at the unit dose level. This fragmentation is compressing hardware refresh cycles while elevating software licensing tiers that include advanced encoding algorithms.
EU Falsified Medicines Directive verification requirements are mandating end-to-end serialization repositories that connect manufacturer barcode systems to national medicine verification organizations. Pharmaceutical contract packagers in Italy and Spain must validate line-level barcode printers against centralized database connectivity specifications. Small molecule generic manufacturers are responding by consolidating vendor relationships to reduce validation documentation duplication across multiple European markets.
Subscription pricing models are displacing perpetual licenses in mid-market procurement evaluations as finance teams prioritize operational expenditure treatment and vendor-managed infrastructure responsibility. Third-party logistics providers in the United States and Netherlands are unbundling label design from print management, sourcing cloud-based template libraries while retaining on-premise production control. This bifurcation is most visible among e-commerce fulfillment operators managing seasonal volume spikes without capital commitment to peak capacity.
Barcode Software Market Segmentation
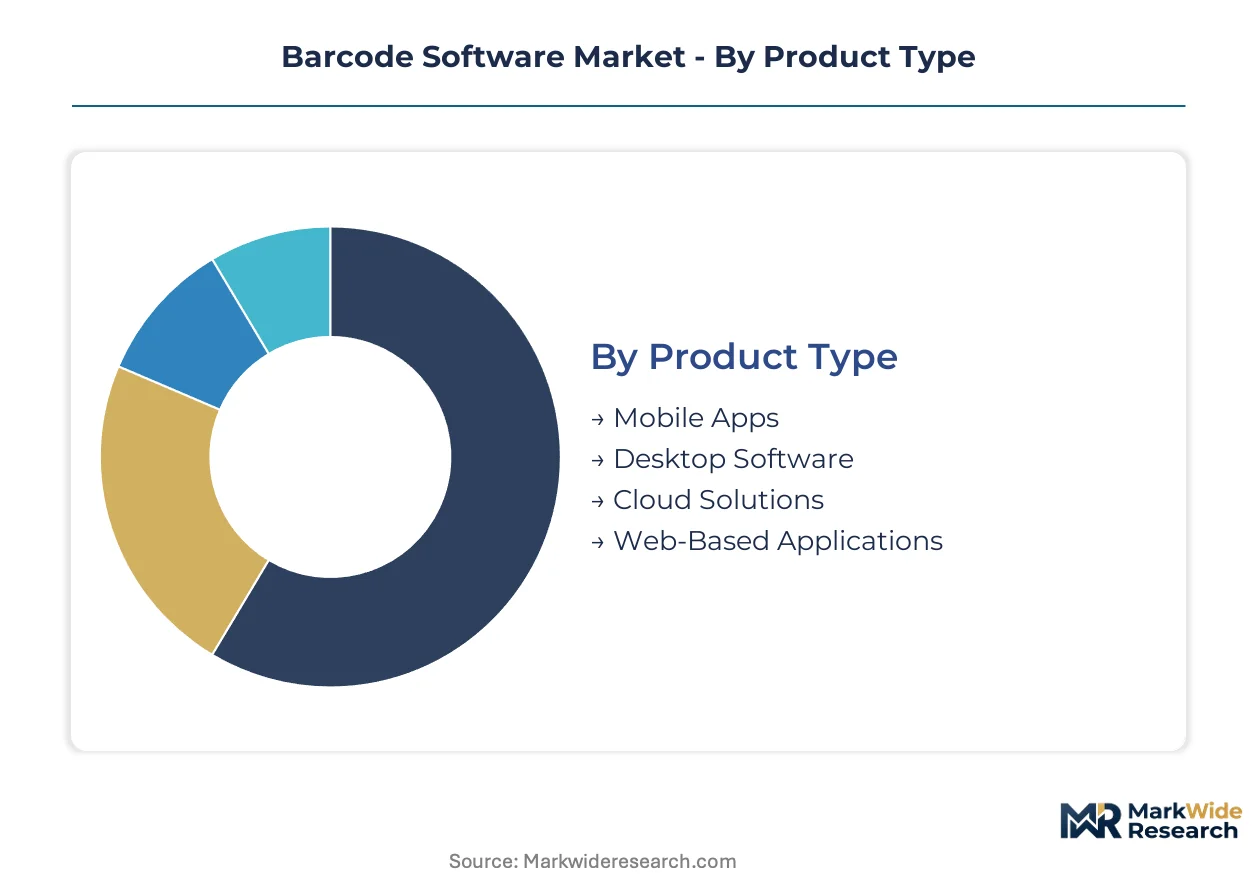
Barcode software segmentation reflects divergent compliance burdens across deployment architectures and symbology standards. Pharmaceutical serialization mandates and retail inventory digitization create divergent technical requirements that vendors must address through specialized product configurations.
Product Type:
FDA DSCSA validation protocols and EU FMD repository connectivity requirements split procurement criteria between regulated and non-regulated deployment modes.
- Cloud Solutions:Multi-tenant architectures with API-first design patterns enable real-time GS1 data pool synchronization for pharmaceutical traceability. US wholesale distributors and German hospital pharmacies are consolidating vendor relationships around subscription platforms that automate 21 CFR Part 11 audit trail generation.
- Desktop Software:Perpetual license models with offline template libraries serve manufacturing verticals with air-gapped production environments. Japanese automotive suppliers and US defense contractors favor localized installations where network segmentation prevents cloud data egress.
- Mobile Apps:Smartphone-native scanning with computer vision algorithms displaces dedicated hardware in field service workflows.
- Web-Based Applications:Browser-delivered label design tools reduce IT provisioning overhead for mid-market logistics operators.
Cloud Solutions handles the majority of new contract value; Mobile Apps is gaining share fastest among asset-light operators.
Technology:
Data payload capacity determines symbology selection as batch-level traceability requirements exceed linear barcode limitations.
- 2D Barcode:GS1 DataMatrix and PDF417 implementations encode sterilization dates, lot numbers, and serial numbers in pharmaceutical unit-dose packaging. Italian and Spanish contract packagers are replacing legacy Code 128 systems to meet EU FMD verification mandates.
- QR Code:Open-standard implementations with URL redirection support consumer-facing product authentication and warranty registration. Indonesian retail chains deploy QR-coded fiscal receipts that connect directly to national tax authority APIs.
- RFID:Passive UHF inlays enable bulk scanning without line-of-sight for apparel and pharmaceutical distribution centers.
- NFC:ISO 14443-compliant tags support tap-to-authenticate medical device interactions in hospital settings.
2D Barcode carries the heaviest compliance-driven replacement cycle; QR Code is expanding most quickly through consumer-facing applications.
End User:
Margin structure and integration complexity vary sharply between high-volume retail deployments and validation-intensive pharmaceutical environments.
- Healthcare:Hospital pharmacies and medical device manufacturers require 21 CFR Part 11 compliant platforms with UDI barcode generation for FDA and EU MDR compliance. German and Japanese regulators enforce unique device identification across Class I-III products.
- Retail:Chain operators prioritize visual inventory interfaces and QuickBooks ecosystem integration for small-format stores. US and Netherlands third-party logistics providers unbundle label design from print management to manage seasonal volume spikes.
- Logistics:E-commerce fulfillment operators demand event-driven synchronization between scanning events and warehouse management systems.
- Manufacturing:Discrete producers balance perpetual license stranded assets against SaaS migration pressure.
Healthcare commands the steepest pricing tier due to validation documentation burdens; Retail generates the deepest volume pools through recurring integration service contracts.
Deployment:
Finance team preference for operational expenditure treatment is compressing procurement cycles toward vendor-managed infrastructure models.
- SaaS:Subscription economics with automatic ISO/IEC 15415 print quality specification updates reduce internal IT maintenance. Netherlands and US logistics operators favor unbundled cloud template libraries while retaining on-premise production control.
- On-Premises:Capitalized deployments with perpetual licenses persist in manufacturing verticals with decade-old scanner and printer installed bases. Legacy hardware interoperability constraints slow cloud-native rollouts.
- Hybrid:Split architectures with cloud-based design tools and local print servers address data residency requirements.
- Open Source:Community-maintained libraries with commercial support contracts serve cost-constrained development teams.
SaaS dominates new procurement evaluations; Hybrid is climbing fastest among multi-site enterprises with distributed warehouse networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical contract packagers export serialization-validated barcode platforms to Italian and Spanish distribution networks under EU FMD harmonization protocols. This trade corridor concentrates compliance-technology procurement in regulated European markets while US wholesale distributors absorb cloud-native solutions for FDA DSCSA enforcement phases.
United States
Hospital pharmacies and wholesale distributors deploy cloud-based barcode generation platforms to meet FDA DSCSA unit-level traceability mandates. The Drug Supply Chain Security Act enforcement timeline compels pharmaceutical manufacturers to validate label templates against 21 CFR Part 11 audit trail requirements. Indianapolis and Memphis logistics clusters host third-party operators unbundling cloud template libraries from on-premise print management.
Germany
Medical device manufacturers implement UDI barcode systems across Class I-III products under EU MDR labeling expansion deadlines. German hospital pharmacies replace legacy scanners to capture GS1 DataMatrix codes at unit-dose levels. The Rhine-Ruhr industrial corridor concentrates pharmaceutical contract packaging operations requiring centralized database connectivity to national medicine verification organizations.
Japan
Automotive suppliers favor perpetual-license desktop installations where network segmentation prevents cloud data egress. METI serialization guidelines for pharmaceutical distribution align with GS1 standards harmonization across Asia-Pacific trade lanes. The Chubu-Nagoya manufacturing belt hosts discrete producers balancing stranded on-premise assets against SaaS migration pressure.
Indonesia
Retail chains deploy QR-coded fiscal receipts connecting directly to national tax authority APIs under digital tax integration mandates. Open-standard QR implementations support consumer-facing product authentication without proprietary infrastructure. Jakarta and Surabaya distribution networks absorb smartphone-native scanning solutions for last-mile delivery workflows.
Netherlands
Third-party logistics operators unbundle label design from print management to manage seasonal e-commerce volume spikes without capital commitment. Rotterdam port logistics clusters demand event-driven synchronization between scanning events and warehouse management systems. Dutch operators favor hybrid architectures with cloud-based design tools and local print servers addressing data residency requirements.
Barcode Software Market Vendor Landscape
Listed leaders compete with private specialists across compliance-tier positioning and ecosystem integration depth. The vendor base organizes around three strategic archetypes: enterprise-grade validation platforms serving pharmaceutical serialization mandates, accounting-ecosystem-integrated inventory modules for small business penetration, and visual-interface solutions reducing training overhead for mid-market operations. M&A activity concentrates on API-first architecture acquisitions, while strategic partnerships target QuickBooks and Xero native integration depth.
Within the compliance-specialist tier, BarTender anchors premium positioning through regulated label design depth. SOS Inventory Software LLC and Sortly Inc. occupy distinct ecosystem-integration positions, with the former embedding into QuickBooks and Xero accounting platforms and the latter exemplifying visual inventory interface differentiation for small and mid-sized operations.
| Leading Market Players |
|---|
| SOS Inventory Software LLC |
| Label Flow |
| Ordoro |
| HandiFox |
| Finale Inventory |
| Sortly Inc. |
| Wasp InventoryCloud |
| VeriPic Inc. |
| BarTender |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR Part 11 validation requirements gate both vendor qualification and subscription tier differentiation simultaneously, forcing pharmaceutical buyers toward premium SaaS tiers while excluding uncertified competitors from regulated procurement shortlists. Cloud-native platforms command recurring revenue premiums against perpetual-license alternatives as compliance documentation burdens concentrate buyer value perception in validated audit trail capabilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with pharmaceutical serialization mandates pushing regulated deployments toward premium tiers bundled with validation support. Price differentiation rests on certification depth—FDA 21 CFR Part 11 versus ISO/IEC 15415 baseline—and geographic delivery cost for on-premise installations. Cost compression in mid-market SaaS tiers is intensifying because QuickBooks ecosystem competitors commoditize basic inventory modules. Small-format retail operators exhibit highest price sensitivity; hospital pharmacies and medical device manufacturers demonstrate lowest sensitivity due to compliance failure costs.
Supply Chain Analysis
Inventory lead times for thermal transfer ribbons and synthetic label substrates fluctuate with petrochemical feedstock indices, compressing margins for high-volume print operations. Component supply concentrates in Germany, Japan, and the United States for precision printhead manufacturing, while China dominates consumables production. Raw material dependencies include polyester film, wax-resin formulations, and siliconized release liners. Single-source vulnerability in thermal transfer ribbon supply threatens logistics operators during feedstock price spikes. Distribution runs through specialized industrial distributors and direct OEM relationships for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barcode software is approaching a platform-economics inflection as API-first architectures and QuickBooks ecosystem integration reshape competitive moats around interoperability depth rather than standalone feature sets.
For Market Incumbents: Secure API connectivity moats by embedding into accounting and ERP ecosystems before cloud-native challengers capture mid-market share. Consolidate validation documentation capabilities to defend pharmaceutical tier pricing against specialized compliance vendors. Prioritize backward integration into print quality certification services to capture recurring revenue streams. For New Entrants and Emerging Players: Mid-market visual inventory interfaces represent a service-layer gap where incumbents under-serve small-format retail and field service workflows. Indonesia's digital tax integration mandates and Southeast Asian last-mile delivery digitization offer the most penetrable geography. Pursue smartphone-native computer vision solutions to bypass hardware-dependent incumbent architectures. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy ERP vendors with stranded barcode modules lacking cloud migration roadmaps. Long-term viability favors platforms with GS1 standards harmonization capabilities across pharmaceutical and retail verticals. Monitor FDA DSCSA enforcement phase transitions as inflection indicators for compliance-software valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables real-time GS1 data pool synchronization for pharmaceutical traceability mandates. |
| QuickBooks Ecosystem Partnership | Captures small business procurement pull-through without standalone IT infrastructure investment. |
| Computer Vision Acquisition | Displaces dedicated scanning hardware in field service and last-mile delivery workflows. |
| EU MDR Compliance Certification | Opens medical device labeling contracts across Class I-III product categories. |
| Indonesia Digital Tax Localization | Addresses QR-coded fiscal receipt mandates connecting to national tax authority APIs. |
Methodological Framework
A standing panel of supply chain directors, pharmaceutical serialization engineers, retail IT procurement officers, and logistics platform architects provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against FDA enforcement guidance documents, GS1 implementation guidelines, EU MDR regulatory texts, and customs trade data. Bottom-up deployment estimates triangulated against top-down software spending benchmarks from SEC filings and hyperscaler ecosystem disclosures.
Consistency checks validated volume and value outputs against external procurement trend indicators and vendor revenue disclosures across the projection horizon. The analytical framework modeled deployment architecture, organization size, vertical compliance burden, integration complexity, and regional regulatory cluster. CAGRs were derived from segmented growth rate reconciliation against macroeconomic software spending patterns, with pharmaceutical serialization mandates and cloud migration curves serving as primary demand inputs.
Forecasts assume regulatory continuity in FDA DSCSA enforcement and EU MDR labeling expansion; material policy shifts would require re-modeling compliance-driven replacement cycles. Outputs reflect assumptions about cloud adoption velocity and legacy hardware refresh timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Delivery Management Software Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
Poland ICT Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Kenya ICT Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Workflow Management System Market
Digital Solutions
Location-Based Services (LBS) Market
Digital Solutions
Digital Signature Market
Digital Solutions
Global Mobile Content Management Market
Digital Solutions
Digital BSS Market
Digital Solutions
Digital Signage Market
Digital Solutions
Data Monetization Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Global Tracking As a Service Market