
 Thin Client Market | 2026-2036
Thin Client Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Client Market Intelligence
The EU AI Act is shifting compliance burdens for endpoint manufacturers selling into regulated European industries. Dell Technologies leverages its enterprise channel depth to sustain hardware-plus-software bundling in financial services. Fujitsu Ltd. anchors Japanese public-sector procurement through localized manufacturing and support infrastructure. HP Inc. differentiates via security-certified firmware stacks that compete on zero-trust architecture mandates.
A thin client is a stripped-down computing endpoint that offloads processing to centralized servers or cloud infrastructure, typically featuring ARM or x86 processors with minimal local storage and embedded operating systems purpose-built for remote protocol rendering. Its primary commercial purpose is to reduce total cost of ownership while centralizing data security and simplifying fleet management across distributed workforces. Desktop thin clients dominate current shipment volumes due to their established presence in call centers and back-office operations, while cloud thin clients represent the fastest-expanding configuration as organizations migrate persistent virtual desktops to elastic infrastructure. Zero clients command premium positioning in defense and classified government environments where firmware attack surfaces must approach absolute minimization.
The FCC shapes US market access through electromagnetic emissions and radio equipment certifications that thin client radios must clear before enterprise deployment. ETSI standards in Europe govern network interoperability and energy efficiency benchmarks that constrain hardware design choices. BIS certification requirements in India create localization hurdles for imported endpoint fleets. Stakeholders must weigh regulatory fragmentation against the operational savings of unified global procurement templates.
Market Dynamics
Healthcare data sovereignty requirements are compressing thin client procurement cycles as providers replace consumer-grade endpoints with centrally managed alternatives ahead of EU AI Act enforcement deadlines.
Growth Catalysts
- EU AI Act:Endpoint manufacturers serving European healthcare and finance sectors face mandatory conformity assessments for devices processing sensitive workloads, accelerating certified thin client refresh cycles.
- ARM architecture migration:Low-power processor designs enable fanless form factors that satisfy energy efficiency benchmarks in ETSI standards while reducing total cost of ownership for distributed call center deployments.
- German manufacturing concentration:IGEL Technology's regional supply base anchors procurement decisions across DACH healthcare systems, creating localized demand gravity for firmware-hardened endpoints.
Market Restraints
- Memory pricing volatility:DDR5 module costs fluctuate with semiconductor foundry capacity allocation, compressing hardware margins for entry-level thin client configurations.
- Single-source firmware risk:Embedded OS licensing concentrates among three vendors, creating supply vulnerability if any provider discontinues long-term support commitments.
- Zero client substitution:Defense and intelligence agencies increasingly specify absolute-minimization endpoints that eliminate local attack surfaces entirely, cannibalizing premium thin client segments.
Strategic Opportunities
- India BIS certification pathway:Localized testing infrastructure for electromagnetic compatibility creates first-mover advantage for vendors establishing compliant manufacturing partnerships ahead of public-sector digitization tenders.
- Cloud thin client convergence:Elastic virtual desktop infrastructure from hyperscale providers pairs with lightweight endpoints to displace persistent VDI in enterprise accounts seeking consumption-based pricing.
- Edge AI inference offloading:Thin clients with neural processing units enable localized pre-processing of sensor data in industrial IoT deployments before transmission to centralized analytics platforms.
Industry Challenges
- Firmware security certification backlog:Common Criteria evaluation timelines extend 18-24 months for EAL4+ ratings, delaying product launches in government segments requiring validated cryptography modules.
- Legacy protocol integration:Financial services back-office systems rely on proprietary terminal emulation that requires custom client development, fragmenting engineering resources across one-off implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Client Market |
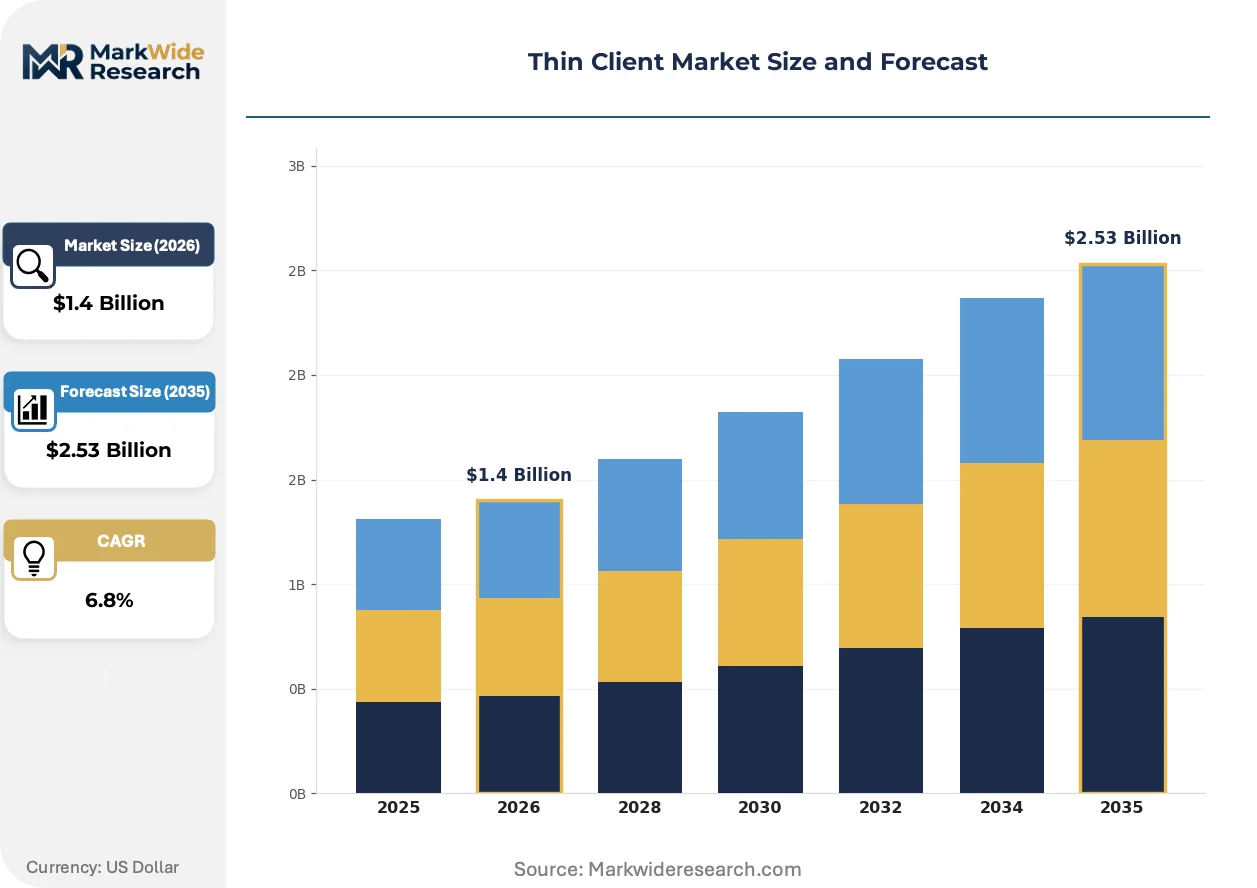
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Thin Clients, Mobile Thin Clients, Zero Clients, Cloud Thin Clients Deployment Mode: Cloud-Based, On-Premises, Hybrid, Virtual Desktop Infrastructure Application: Government, Education, Finance, Manufacturing, Telecommunication End User: Small & Medium Enterprises, Large Corporations, Managed Service Providers, Educational Institutions |
| Companies Covered | IGEL Technology, Fujitsu Ltd., Dell Technologies, 10ZiG Technology, NComputing, HP Inc., Samsung Electronics, ClearCube Technology, Lenovo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Client Market Strategic Shifts & Innovations
Thin client architecture is fragmenting into specialized configurations as endpoint responsibilities split between raw protocol rendering and localized security enforcement. This specialization is compressing vendor consolidation timelines.
System-on-chip designs integrating CPU, GPU, and dedicated security processors into single-package solutions are modularizing hardware platform development. Medical device manufacturers specify these integrated packages for bedside terminals requiring IEC 62304 software lifecycle compliance. Component standardization is compressing time-to-market for new endpoint variants while reducing qualification overhead.
REACH substance restrictions on halogenated flame retardants in printed circuit boards force material substitutions across European-bound shipments. Manufacturers reformulating enclosure plastics face extended thermal validation cycles to maintain MTBF ratings. Healthcare procurement teams in Germany and France now require full material disclosure documentation ahead of contract award.
Enterprise buyers unbundle endpoint hardware from management software licensing, reversing decade-long bundling conventions. Large financial services accounts negotiate separate SaaS contracts for device orchestration platforms while sourcing hardware through competitive tenders. This disintermediation is most pronounced in London and Frankfurt trading floors where refresh cycles compress below 24 months.
Thin Client Market Segmentation
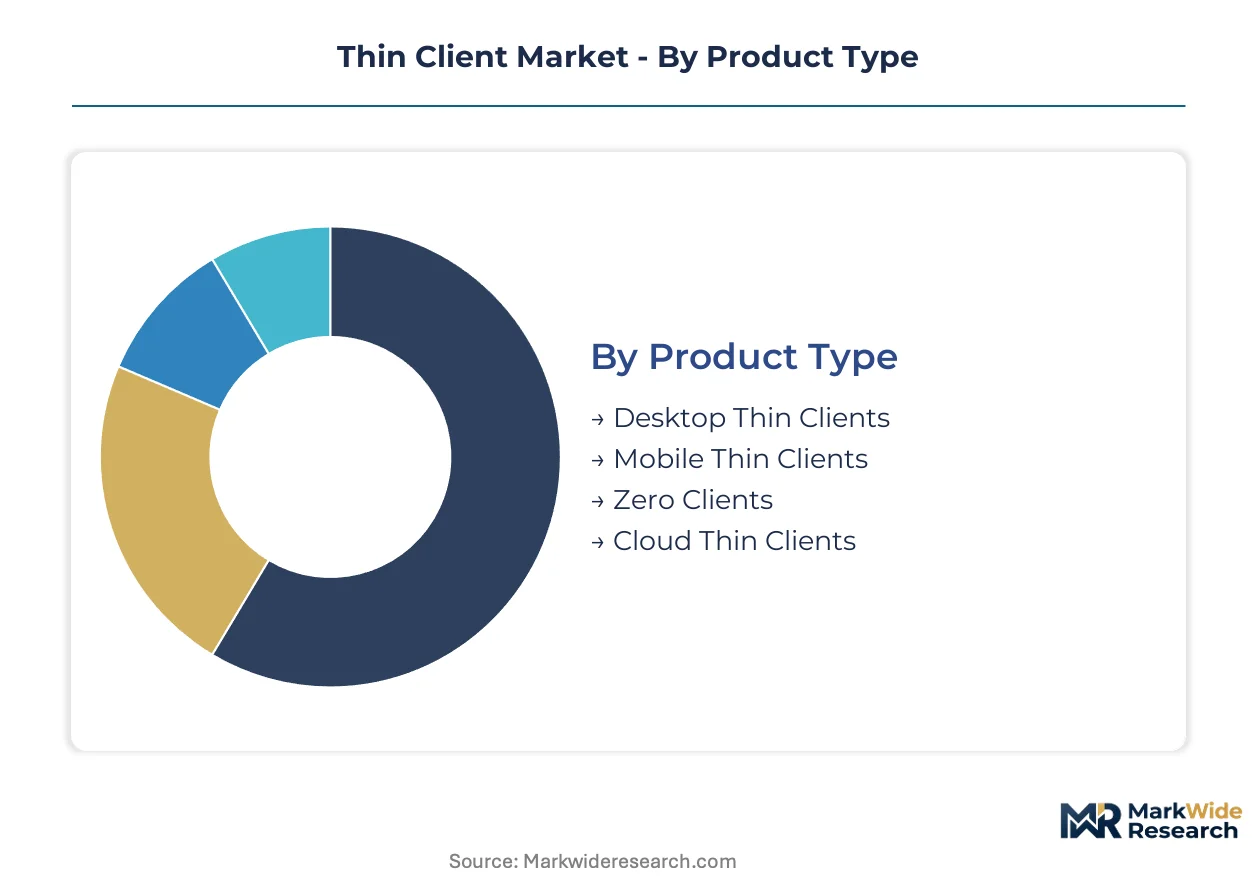
Thin client procurement patterns diverge sharply across deployment contexts, with refresh cycles in regulated industries running 40% shorter than commodity enterprise accounts. Segmentation reveals where firmware certification investments translate to pricing power versus margin compression.
Product Type:
Upgrade cycles vary dramatically by form factor, with desktop replacements driven by Windows embedded OS end-of-life schedules while cloud configurations refresh on hyperscale contract renewals.
- Desktop Thin Clients:Fixed-position endpoints with x86 or ARM processors, minimal local storage, and embedded operating systems optimized for Citrix or VMware protocol rendering. Call center operators in India and the Philippines deploy these in 10,000-unit fleets where ETSI energy efficiency compliance reduces cooling loads in tropical facilities.
- Cloud Thin Clients:Stateless devices engineered for elastic virtual desktop infrastructure with firmware that auto-provisions from cloud orchestration layers. German healthcare networks expanding telemedicine infrastructure specify these for clinic workstations requiring instant recovery from centralized image management.
- Mobile Thin Clients:Battery-powered laptops or tablets with hardened wireless stacks for field workforce connectivity.
- Zero Clients:Firmware-minimalized endpoints with no local OS, processing only encrypted pixel streams from host systems.
Volume placements concentrate in Desktop Thin Clients; the faster expansion belongs to Cloud Thin Clients.
Deployment Mode:
Cost tier separation determines procurement channel, with cloud-based deployments shifting CapEx to OpEx while on-premises configurations retain capital budget ownership for security-sensitive accounts.
- Cloud-Based:Fully managed endpoint fleets where device firmware maintains persistent tunnels to Azure, AWS, or Google Cloud virtual desktop services. UK financial services firms migrating trading floor infrastructure favor this model for consumption-aligned spending during regulatory reporting peaks.
- On-Premises:Self-hosted virtualization stacks with dedicated thin client brokers inside corporate data centers. Japanese manufacturing conglomerates with intellectual property protection mandates maintain these configurations for design engineering workstations.
- Hybrid:Split workloads with sensitive applications on-premises and general productivity in cloud instances.
- Virtual Desktop Infrastructure:Persistent or non-persistent desktop pools served through dedicated broker infrastructure.
Customer preference clusters in Cloud-Based for new deployments; Hybrid captures the steepest expansion trajectory among existing infrastructure conversions.
Application:
Application-specific compliance requirements create segment-specific pricing tiers, with government and finance commanding 25-40% premiums for Common Criteria certified firmware stacks.
- Government:Classified and unclassified deployments requiring FIPS 140-2 or EAL4+ validated cryptography modules. US federal agencies specify these for SCIF environments where supply chain provenance documentation spans component-level bill of materials.
- Finance:Trading floor and back-office configurations with sub-20 millisecond latency requirements for Bloomberg terminal emulation. Frankfurt and London investment banks negotiate separate hardware and software contracts here, compressing refresh below 24 months.
- Education:Computer lab and library deployments prioritizing total cost of ownership over security certification depth.
- Manufacturing:Shop-floor terminals integrating with SCADA systems and industrial IoT sensor networks.
- Telecommunication:Customer service centers and network operations centers requiring 99.999% availability.
Contract value concentrates in Finance; Education generates the highest unit velocity.
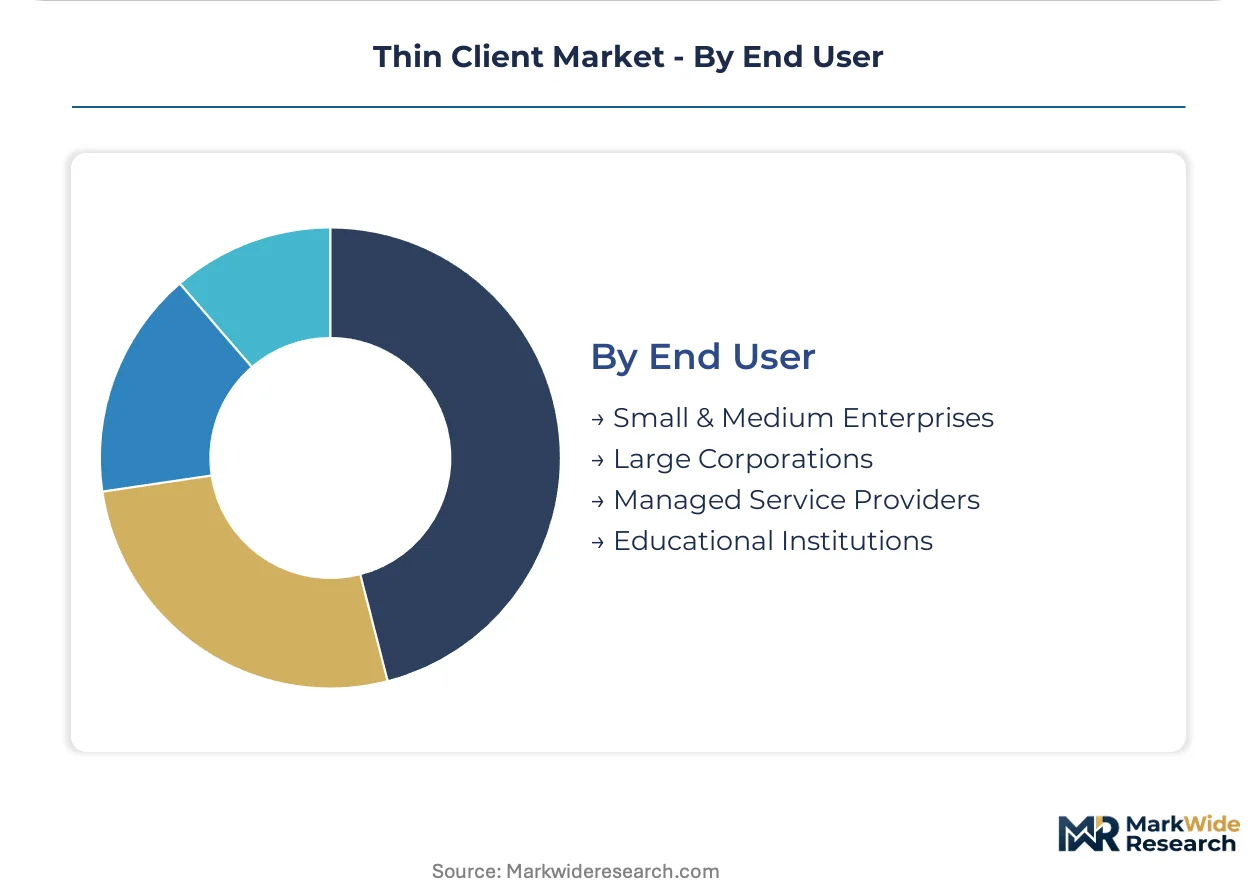
End User:
Customer scale determines support model economics, with large corporations demanding dedicated technical account managers while small and medium enterprises accept standardized support tiers.
- Large Corporations:Fortune 500 and equivalent enterprises with 10,000+ endpoint fleets requiring custom image management and staged rollout orchestration. Managed service providers like Wipro and Infosys embed these deployments inside broader workplace transformation contracts for US healthcare systems.
- Small & Medium Enterprises:Mid-market accounts with 100-5,000 seats sourcing through value-added resellers and accepting standard firmware configurations. French regional hospital networks in this tier prioritize IGEL's German-manufactured supply base for EU AI Act readiness.
- Managed Service Providers:Multi-tenant hosting operations delivering desktop-as-a-service to downstream clients.
- Educational Institutions:K-12 and university systems with seasonal procurement patterns tied to fiscal year budgets.
Revenue concentration sits with Large Corporations; Managed Service Providers are climbing fastest as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Special Investment Regions and Tamil Nadu's Electronics Manufacturing Clusters concentrate thin client assembly capacity for domestic and export markets. Tax incentives under India's PLI scheme for IT hardware redirect component sourcing toward localized supply chains.
United States
Federal healthcare digitization mandates drive VA hospital system refresh cycles. FCC electromagnetic certification requirements shape radio module design for enterprise wireless stacks. Austin and Raleigh-Durham clusters host firmware development centers serving financial services compliance needs.
Germany
IGEL Technology's Augsburg manufacturing base anchors DACH healthcare procurement decisions. EU AI Act conformity assessments compress refresh timelines for hospital endpoint fleets. Bavarian medical device clusters specify IEC 62304-compliant firmware for bedside terminal integrations.
India
BIS certification requirements for electromagnetic compatibility accelerate localized testing infrastructure buildout. PLI scheme incentives attract assembly investments from Taiwanese ODMs. Noida and Chennai electronics corridors concentrate surface-mount production for ARM-based thin client motherboards.
Japan
METI cybersecurity labeling requirements for IoT endpoints extend to thin client firmware validation. Fujitsu's Kawasaki facilities anchor public-sector procurement through localized support infrastructure. Osaka manufacturing clusters supply fanless enclosures for industrial IoT shop-floor deployments.
United Kingdom
NCSC device security principles reshape financial services endpoint specifications. London trading floors unbundle hardware from software licensing, compressing refresh below 24 months. Thames Valley technology corridors host cloud thin client integration labs for hyperscale virtual desktop partnerships.
Thin Client Market Key Industry Players
German producers anchor firmware-hardened tiers; Taiwanese and Chinese fabricators hold cost-optimized volume positions. Market structure splits between consolidated enterprise bundlers and specialized endpoint pure-plays. Three archetypes dominate: semiconductor-integrated hardware vendors, embedded OS licensors, and managed service enablers. Competitive moves center on disintermediation of hardware-software bundles and geographic certification pre-positioning ahead of regional enforcement deadlines.
Within the firmware-specialist tier, IGEL Technology exemplifies regional supply-base anchoring strategies. Fujitsu Ltd. occupies a position bridging public-sector procurement relationships with localized manufacturing footprints. Dell Technologies sits within the enterprise bundling archetype, representing channel-depth approaches that sustain integrated hardware-software offerings amid unbundling pressures.
| Leading Market Players |
|---|
| IGEL Technology |
| Fujitsu Ltd. |
| Dell Technologies |
| 10ZiG Technology |
| NComputing |
| HP Inc. |
| Samsung Electronics |
| ClearCube Technology |
| Lenovo Group |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between Common Criteria EAL4+ endpoints and commodity unvalidated hardware manifests in pricing spreads exceeding 40 percent, with supply chains bifurcating between German firmware-specialist facilities and Taiwanese cost-optimized assembly corridors. This tier separation compresses margin recovery timelines for mid-market vendors caught between compliance investment requirements and spot-market price floors.
Pricing Analysis
Short-lead-time premiums for EU AI Act-certified endpoints command 15-25 percent markups over standard delivery windows, while spot inventory of uncertified legacy units trades at distressed clearance levels. Three-tier pricing structure across premium certified, standard enterprise, and economy education tiers dominates procurement negotiations, with certification depth and firmware validation status as primary price differentiation drivers. Cost compression in the economy tier is intensifying because DDR5 memory module volatility erodes hardware margins below sustainable thresholds. Education sector buyers exhibit highest price sensitivity, while defense and classified government accounts demonstrate near-zero elasticity for validated cryptography modules.
Supply Chain Analysis
Regional distribution centers in Augsburg, Shenzhen, and Austin orchestrate hub-and-spoke fulfillment patterns that align certified firmware inventory with EU AI Act enforcement timelines. Manufacturing concentration spans Germany for healthcare-grade endpoints, Taiwan for ARM-based motherboard fabrication, and India for PLI-incentivized domestic assembly serving public-sector tenders. Component sourcing draws from South Korean DDR5 foundries, Chinese enclosure molding operations, and Japanese fanless thermal management suppliers. Single-source vulnerability in embedded OS licensing creates supply chain risk across all tiers. Distribution runs through value-added resellers in Europe, direct enterprise sales in North America, and systems integrator partnerships in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin client market consolidation accelerates as EU AI Act compliance costs force sub-scale firmware developers toward acquisition or exit, compressing vendor viability thresholds below 500,000 annual unit shipments.
For Market Incumbents: Extend firmware certification depth into medical device IEC 62304 compliance to capture Bavarian hospital network refresh cycles, while consolidating channel control through exclusive managed service provider partnerships that lock out competing hardware vendors. Zero client substitution in defense segments and hyperscaler cloud thin client convergence represent immediate threats requiring defensive R&D reallocation toward neural processing unit integration for edge AI workloads. For New Entrants and Emerging Players: ARM-based fanless system-on-chip designs offer technology-first wedge into Indian BIS certification pathways ahead of public-sector digitization tenders, where localized testing infrastructure creates first-mover advantage for compliant manufacturing partnerships. White-space concentration sits with cloud thin client configurations for UK financial services trading floors seeking consumption-based pricing models, with go-to-market execution through London-based hyperscale integration labs enabling rapid proof-of-concept validation. For Investors and Strategic Acquirers: Re-rating potential sits with firmware-specialist pure-plays given EU AI Act enforcement acceleration and healthcare data sovereignty mandate expansion across DACH markets. Long-term viability framing favors acquisition targets with captive German manufacturing footprints and established EAL4+ evaluation pipelines, as these assets compound pricing power across successive compliance cycles. Monitor Common Criteria evaluation backlog clearance rates as inflection indicator for certified endpoint supply constraints and corresponding margin expansion windows.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Certification Acceleration | EU AI Act conformity assessments compress 18-24 month EAL4+ timelines for healthcare endpoint eligibility. |
| ARM Architecture Migration | Fanless system-on-chip designs satisfy ETSI energy benchmarks while reducing tropical call center cooling costs. |
| India BIS Certification Pre-Positioning | Localized electromagnetic compatibility testing infrastructure captures PLI-incentivized public-sector tender flow. |
| Cloud Thin Client Partnership | Hyperscaler virtual desktop integration displaces persistent VDI in London and Frankfurt financial services accounts. |
| Edge AI Inference Integration | Neural processing units enable localized sensor pre-processing for industrial IoT shop-floor deployments. |
Research Approach
Multi-period observation of thin client shipment volumes, certification pipeline backlogs, and hyperscaler virtual desktop infrastructure capex disclosures anchored the trend analysis, supplemented by interviews with endpoint procurement directors at German hospital networks, firmware engineering leads at Augsburg manufacturing facilities, and cloud solutions architects at UK financial services firms. Secondary validation drew from FCC equipment authorization databases, ETSI energy efficiency compliance registries, BIS certification announcements, and SEC filings of publicly traded endpoint vendors. Bottom-up unit economics modeling triangulated against top-down market sizing from virtualization software license disclosures.
Input-output matrix framing connected ARM processor foundry capacity allocation, DDR5 module pricing indices, and embedded OS licensing terms to endpoint shipment forecasts across the projection horizon. Segmentation dimensions modeled include product type tier, deployment mode architecture, application compliance requirement, and end-user scale category, with regional regulatory cluster as the industry-specific overlay. CAGRs were derived from elasticity-adjusted replacement cycle analysis and cloud migration penetration curves, incorporating EU AI Act enforcement timeline assumptions and India PLI scheme incentive phase-out schedules as boundary conditions.
Several conditions sit outside the modeled scope, including unannounced semiconductor foundry capacity expansion, abrupt embedded OS vendor consolidation, and geopolitical disruption to Taiwan Strait component flows. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and hyperscaler virtual desktop pricing stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Graph Technology Market
Digital Solutions
Computer Aided Engineering Market
Digital Solutions
Data Monetization Solutions for Life Science Companies Market
Digital Solutions
AQI App Market
Digital Solutions
South Africa ICT Market
Digital Solutions
Digital Certificates Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Qatar ICT Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Device As a Service (Daas) Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Lead Generation Solutions Market