
 Digital Dispenser Systems Market | 2026-2036
Digital Dispenser Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Dispenser Systems Market Outlook
Hospital procurement channels is reconfiguring how digital dispenser systems reach end users, with group purchasing organizations now demanding cloud-connected platforms that integrate with enterprise resource planning systems. Nordson Corporation leverages its precision fluid management heritage to dominate industrial adhesive dispensing segments, while Omnicell, Inc. anchors the acute care pharmacy automation space through sustained investment in inventory analytics. Graco Inc. competes across manufacturing floor applications where programmable volume control and repeatability specifications determine vendor selection.
Digital dispenser systems encompass electromechanical units that meter, track, and log the release of liquids, solids, or gases through software-controlled valves, pumps, or robotic mechanisms, typically achieving dosing accuracies within one percent and maintaining audit trails for regulatory compliance. Their primary purpose spans pharmaceutical dispensing, industrial adhesive application, and food portion control where traceability and waste reduction carry operational weight. Smart dispensers lead product type evolution as embedded sensors and machine learning algorithms enable predictive maintenance and real-time inventory optimization. Healthcare facilities represent the deepest end-user margin pool given stringent compliance requirements and recurring consumable revenue streams, while cloud-based deployment architectures are displacing standalone systems in multi-site retail pharmacy chains seeking centralized oversight.
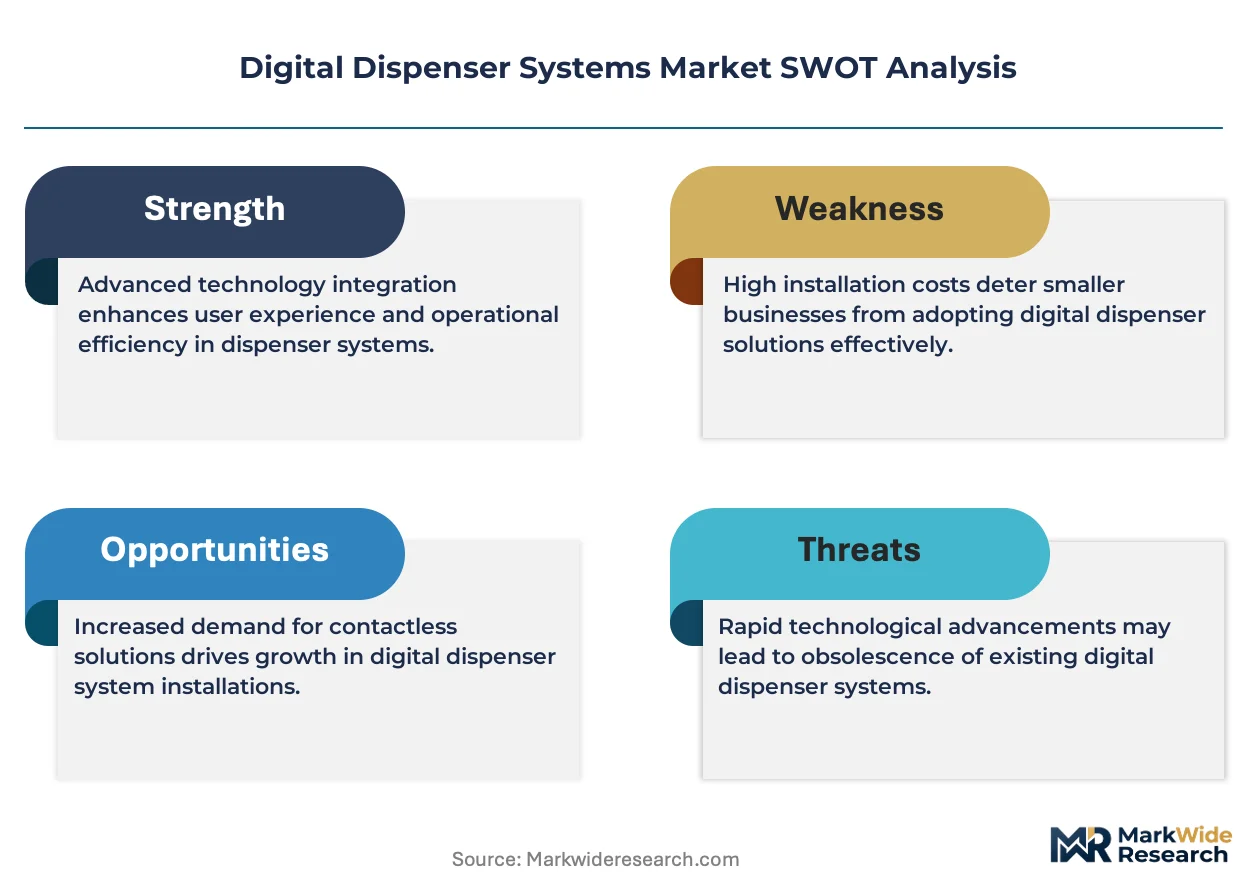
The FDA enforces Unique Device Identification and drug supply chain security mandates that directly shape dispenser system design requirements for serialization and electronic record-keeping. In Europe, EMA medical device regulations and REACH chemical compliance frameworks constrain material choices and software validation protocols for manufacturers serving EU markets. Stakeholders must monitor how emerging cybersecurity standards for connected health devices will reshape product development roadmaps and certification timelines across jurisdictions.
Market Dynamics
Healthcare systems are consolidating pharmacy operations into centralized distribution hubs, forcing dispenser manufacturers to engineer multi-site inventory synchronization and cloud-native architectures that replace standalone unit deployments.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Mandates for unit-level traceability are compelling hospital pharmacies to upgrade legacy dispensing cabinets with serialization-enabled systems that capture every dose movement.
- Industrial adhesive automation:Electric vehicle battery pack assembly lines in Germany and South Korea are specifying precision fluid dispensers that eliminate manual application variability and reduce material waste.
- Machine learning integration:Predictive algorithms embedded in smart dispensers are cutting downtime for pharmaceutical distribution centers by forecasting component failures before they trigger maintenance events.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate microcontroller fabrication for dispenser control boards, exposing OEMs to allocation delays during capacity constraints.
- Stainless steel price volatility:Grade 316L sheet metal constitutes 25-35% of hardware costs for pharmaceutical-grade cabinets, with nickel content fluctuations compressing gross margins unpredictably.
- Legacy system interoperability:Hospital information systems running on decade-old HL7 v2.x protocols resist seamless integration with modern REST API dispenser architectures, extending sales cycles.
Strategic Opportunities
- Retail pharmacy central fill:US chains are consolidating dispensing into regional hubs, creating demand for high-throughput robotic systems that process 500+ scripts hourly with minimal pharmacist oversight.
- EU MDR compliance services:Device manufacturers can bundle software validation documentation and post-market surveillance tools with hardware sales to capture recurring revenue from EU hospital customers.
- Edge-to-cloud convergence:Dispensers combining local AI inference with centralized analytics are opening subscription pricing models for predictive inventory management in multi-site healthcare networks.
Industry Challenges
- Cybersecurity certification timelines:FDA premarket guidance for connected health devices now requires penetration testing and SBOM documentation, extending product launch schedules by 8-14 months.
- Mechatronics talent scarcity:The intersection of precision fluid dynamics, embedded firmware, and pharmaceutical compliance regulations limits the available engineering workforce for advanced dispenser development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Dispenser Systems Market |
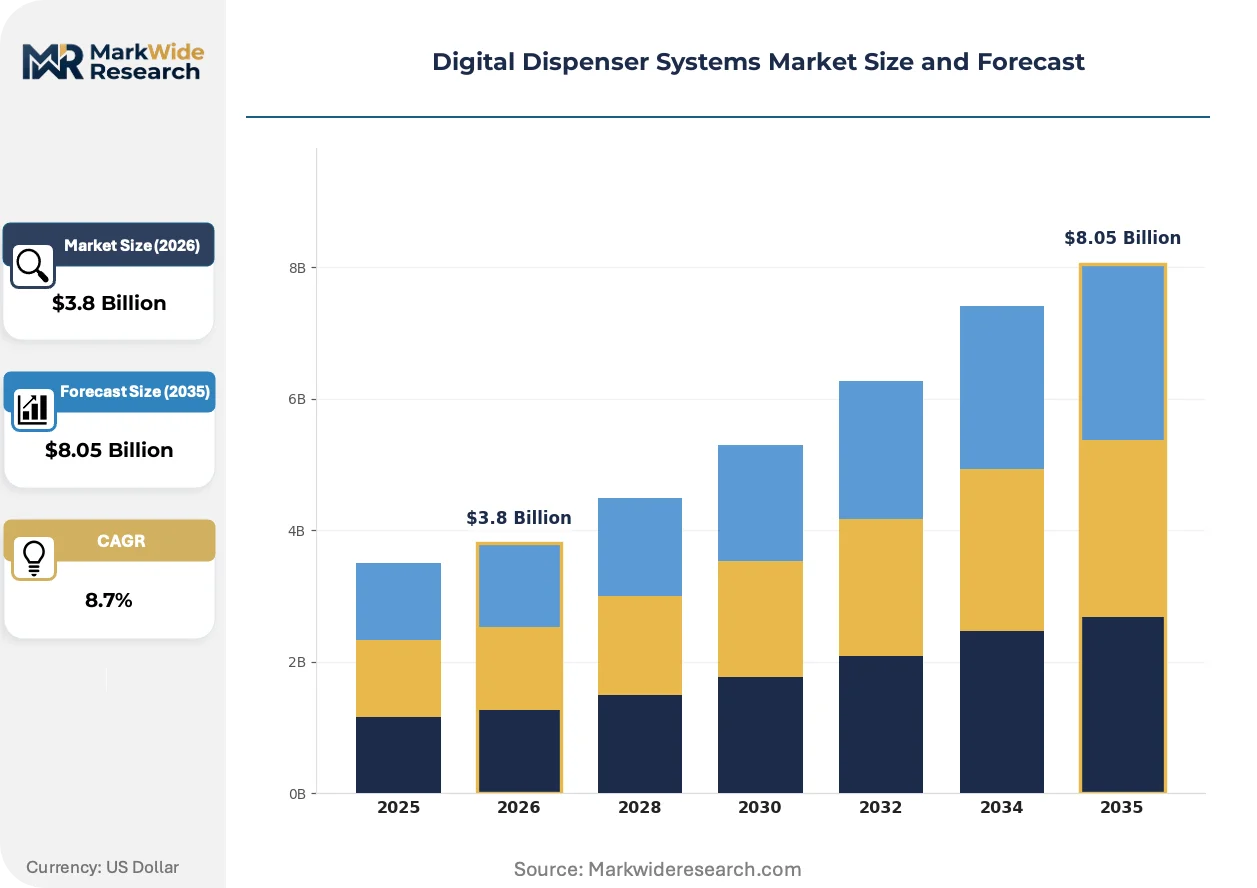
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Dispensers, Manual Dispensers, Smart Dispensers, Digital Interface Dispensers End User: Healthcare Facilities, Retail Pharmacies, Food & Beverage Industry, Laboratories Deployment: On-Premise, Cloud-Based, Hybrid, Standalone Functionality: Inventory Management, Compliance Tracking, User Authentication, Remote Monitoring |
| Companies Covered | Nordson Corporation, Graco Inc., Omnicell, Inc., Becton, Dickinson and Company, McKesson Corporation, Illinois Tool Works, AptarGroup Inc., ScriptPro LLC, Mycronic AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Dispenser Systems Market Strategic Shifts
Electromechanical dispensing architectures are yielding to software-defined platforms where firmware updates reconfigure dosing parameters without hardware replacement, compressing product lifecycles and reshaping vendor-customer relationships.
Ultrasonic piezoelectric dispensing heads are rendering obsolete pneumatic piston mechanisms in micro-liter pharmaceutical dosing applications. Contract manufacturing organizations in Switzerland and Massachusetts are specifying these units for high-potency active ingredient handling where cross-contamination risks demand disposable fluid paths. The shift is compressing maintenance intervals from quarterly to annual while eliminating compressed air infrastructure from cleanroom designs.
EMA's Medical Device Regulation (MDR) Annex I requirements for post-market clinical follow-up are forcing dispenser OEMs to embed automated adverse event logging directly into device firmware. Manufacturers serving EU hospitals must now architect systems that capture usage anomalies and transmit structured reports to notified bodies without manual intervention. German hospital procurement teams are prioritizing vendors with pre-validated MDR technical documentation packages.
Group purchasing organizations are consolidating vendor panels and demanding outcome-based contracts that tie dispenser payments to measurable reductions in medication errors or inventory carrying costs. Three major US hospital systems have shifted from capital purchase models to per-dose dispensing fees, transferring utilization risk to equipment suppliers. This restructuring is most advanced in the Southeast and Midwest regions where GPO consolidation has concentrated buying power among four dominant organizations.
Digital Dispenser Systems Market Segmentation
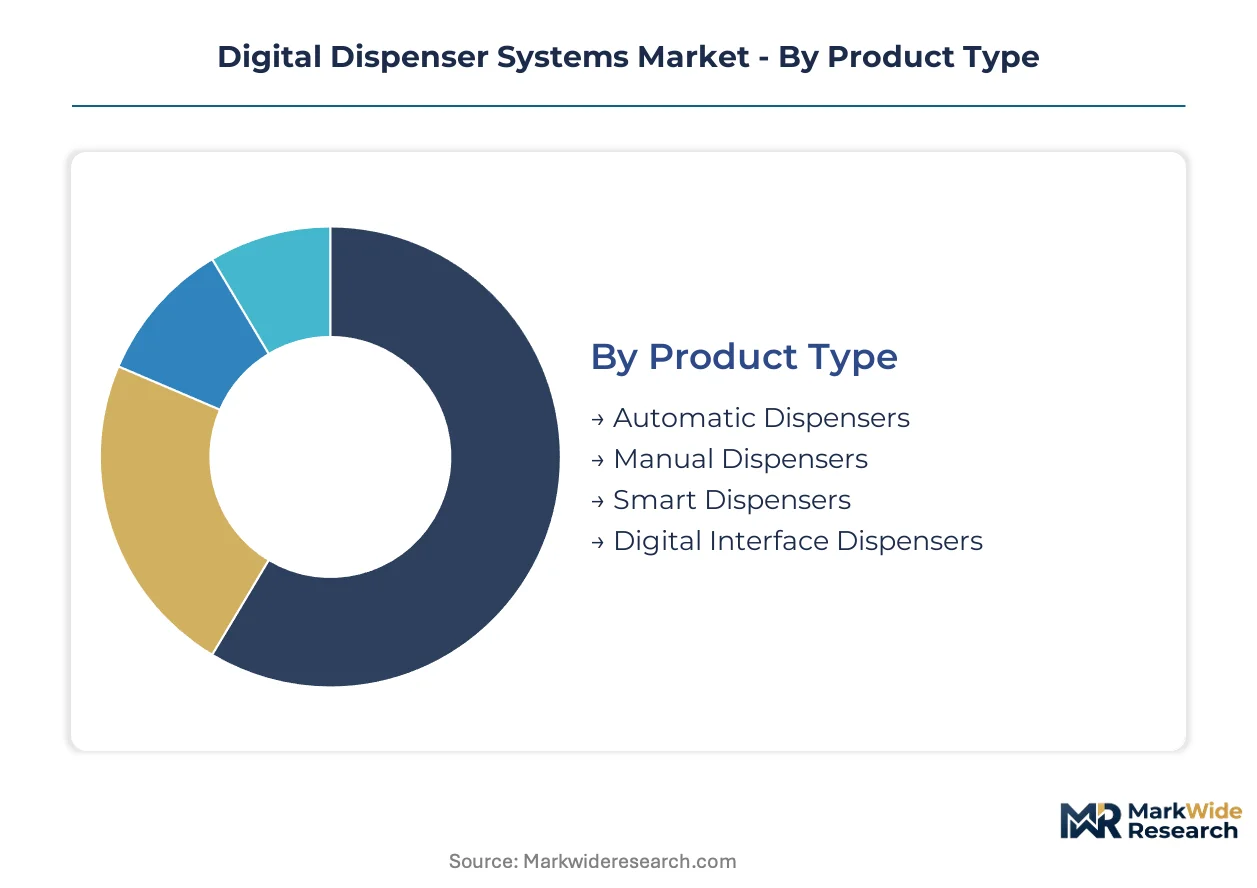
Segmentation in digital dispenser systems reveals how technology maturity, regulatory pressure, and operational scale fragment purchasing decisions across healthcare and industrial verticals. Understanding these divides exposes where hardware margins concentrate versus where software subscriptions capture recurring revenue.
Product Type:
Mature pneumatic and electromechanical architectures now coexist with emerging AI-enabled platforms, creating a bifurcated procurement landscape where replacement cycles and validation burdens diverge sharply.
- Smart Dispensers:Embedded sensors and machine learning algorithms enable predictive maintenance and real-time inventory optimization. Hospital systems in Germany and the United States are prioritizing these units for multi-site medication distribution hubs where downtime costs exceed equipment purchase price.
- Automatic Dispensers:Electromechanical units with programmable dosing parameters and electronic audit trails dominate pharmaceutical manufacturing and acute care pharmacy automation. FDA drug supply chain security mandates are accelerating replacement of legacy units lacking serialization capabilities.
- Manual Dispensers:Basic mechanical units with digital readouts persist in cost-constrained laboratories and small-scale food production where regulatory traceability requirements remain minimal.
- Digital Interface Dispensers:Touchscreen-controlled systems with barcode scanning and user logging serve mid-tier retail pharmacies seeking compliance documentation without full automation investment.
Automatic dispensers retain volume leadership; smart dispensers hold the steepest expansion curve.
End User:
Customer type determines pricing power, with consolidated health systems demanding outcome-based contracts while fragmented food service operators accept standard hardware margins.
- Healthcare Facilities:Hospital pharmacies and centralized distribution centers require FDA-compliant serialization, HL7 integration, and 99.9% uptime guarantees. These specifications justify premium pricing and long-term service agreements.
- Retail Pharmacies:Chain operators in the United States are consolidating dispensing into regional hubs, creating demand for high-throughput robotic systems. Central fill operations prioritize throughput over individual unit flexibility.
- Food & Beverage Industry:Portion control applications in quick-service restaurants and catering operations emphasize hygiene certification and recipe consistency over traceability depth.
- Laboratories:Research and quality control facilities demand precision micro-liter dosing with disposable fluid paths to prevent cross-contamination between high-potency compounds.
Healthcare facilities command the deepest margin pool; retail pharmacy central fill operations are gaining share fastest.
Deployment:
Architecture choices reflect IT infrastructure maturity, with cloud-native systems displacing standalone units where enterprise resource planning integration has already been standardized.
- Cloud-Based:Browser-accessible platforms with centralized analytics enable multi-site inventory synchronization. Group purchasing organizations now require these architectures for enterprise-wide contracts.
- Hybrid:Local control boards with encrypted cloud telemetry balance real-time responsiveness with centralized oversight. German hospital procurement teams favor this model for MDR-compliant post-market surveillance.
- On-Premise:Air-gapped installations persist in defense and nuclear research facilities where cybersecurity protocols prohibit external connectivity.
- Standalone:Self-contained units with local databases serve single-site operations with limited IT support, though this segment contracts as cloud economics improve.
Cloud-based deployments are displacing standalone systems fastest; hybrid architectures retain the largest installed base.
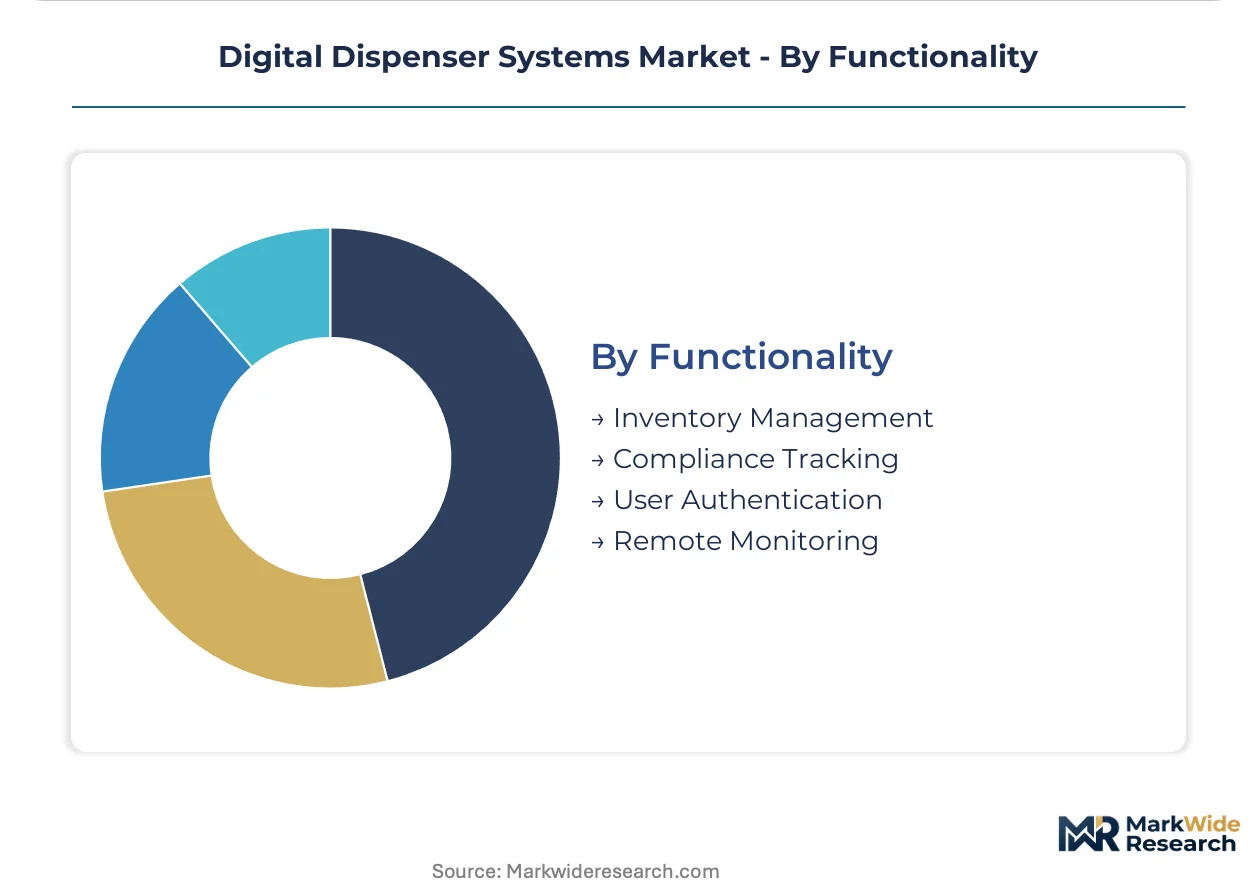
Functionality:
Feature bundling follows regulatory enforcement intensity, with compliance modules now table stakes in pharmaceutical applications while remaining optional in industrial segments.
- Compliance Tracking:Automated serialization, electronic signatures, and audit trail generation address FDA Drug Supply Chain Security Act and EU MDR requirements. This functionality is non-negotiable for pharmaceutical dispensing.
- Inventory Management:Real-time stock level monitoring with predictive reorder algorithms reduces carrying costs and stockout frequency. Retail pharmacy chains specify these capabilities for central fill operations.
- User Authentication:Biometric or RFID-based access control prevents unauthorized dispensing and supports DEA controlled substance regulations in the United States.
- Remote Monitoring:Telemetry dashboards enabling predictive maintenance and usage analytics are expanding from healthcare into industrial adhesive dispensing applications.
Compliance tracking anchors pharmaceutical procurement; inventory management is climbing the fastest in retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of drug supply chain security mandates is accelerating dispenser system upgrades across the United States, while EU MDR compliance deadlines are concentrating procurement activity in Germany and neighboring markets.
United States
Hospital systems in Texas and Florida are consolidating pharmacy operations into regional hubs, demanding cloud-connected dispenser platforms. FDA Drug Supply Chain Security Act serialization requirements are compelling acute care facilities to replace legacy cabinets. The Southeast GPO corridor spanning Atlanta and Charlotte is driving outcome-based contracting models.
Germany
Baden-Württemberg's pharmaceutical manufacturing cluster is specifying ultrasonic piezoelectric dispensers for high-potency active ingredient handling. EU MDR Annex I post-market surveillance requirements are embedding automated adverse event logging into device firmware. Munich-based hospital procurement teams are prioritizing vendors with pre-validated technical documentation packages.
China
Electric vehicle battery assembly lines in Shenzhen and Shanghai are adopting precision fluid dispensers to eliminate manual adhesive application variability. NMPA medical device traceability regulations are shaping serialization module requirements for pharmaceutical-grade systems. The Yangtze River Delta manufacturing belt is absorbing the highest volume of industrial dispensing equipment imports.
Switzerland
Contract manufacturing organizations in Basel are specifying disposable fluid path dispensers to prevent cross-contamination between high-potency compounds. Swissmedic device registration requirements are extending validation timelines for connected health platforms. The Greater Zurich Area precision engineering cluster is advancing micro-liter dosing capabilities for laboratory applications.
South Korea
Semiconductor packaging facilities in Gyeonggi Province are integrating smart dispensers with predictive maintenance algorithms. MFDS pharmaceutical manufacturing guidelines are mandating electronic batch records for dispensing equipment. The Busan-Ulsan industrial corridor is expanding adhesive automation for shipbuilding and battery assembly applications.
Digital Dispenser Systems Market Competitive Environment
Healthcare technology specialists and industrial fluid management conglomerates split the market along regulatory intensity lines. The vendor landscape organizes into three strategic tiers: acute care pharmacy automation providers, precision industrial dispensing engineers, and diversified manufacturing conglomerates with cross-sector fluid control portfolios. Consolidation pressure is intensifying through vertical integration moves and cloud-native platform acquisitions.
Within the healthcare automation tier, Omnicell, Inc. and Becton, Dickinson and Company exemplify the compliance-heavy acute care positioning, while Nordson Corporation anchors the industrial adhesive dispensing archetype. Graco Inc. occupies a position bridging manufacturing floor applications with programmable volume control specifications. These three entities represent the dominant strategic archetypes without exhausting the competitive field.
| Leading Market Players |
|---|
| Nordson Corporation |
| Graco Inc. |
| Omnicell, Inc. |
| Becton, Dickinson and Company |
| McKesson Corporation |
| Illinois Tool Works |
| AptarGroup Inc. |
| ScriptPro LLC |
| Mycronic AB |
| Others |
Value Chain & Pricing Dynamics
Taiwan and South Korea's dominance in microcontroller fabrication for dispenser control boards concentrates upstream bargaining power among semiconductor foundries, pushing hardware OEMs toward software subscription models to escape commodity margin compression in cabinet manufacturing.
Pricing Analysis
US-Germany price spreads of 15-25% separate premium FDA-validated systems from standard CE-marked units. Pricing stratifies across FDA 510(k)-cleared, CE-MDR-certified, and uncertified economy tiers. Cost compression in stainless steel-intensive hardware tiers is intensifying because nickel price volatility erodes predictability. Consolidated hospital systems exhibit lowest price sensitivity; small retail pharmacies and food service operators show highest.
Supply Chain Analysis
Contract manufacturing concentrates among Swiss precision engineering houses and Massachusetts-based medical device CMs with cleanroom capabilities. Hardware assembly draws from Taiwan, Germany, and China; control electronics rest on South Korean and Taiwanese semiconductor supply. Single-source vulnerability in 316L stainless steel sheet exposes producers to nickel market swings. Distribution runs through group purchasing organizations and direct OEM sales to hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cloud-native and legacy standalone architectures creates niche opportunities for specialized vendors as healthcare systems bifurcate procurement between centralized hub automation and point-of-care flexibility.
For Market Incumbents: Harden cloud platform moats through backward integration into predictive analytics engines, insulating against pure-play SaaS entrants. Lock in GPO panel positions by pre-validating MDR technical documentation bundles for German hospital procurement teams. Priority lever: captive AI inference chip supply from Taiwan foundry partnerships.
For New Entrants and Emerging Players: Mid-tier retail pharmacy central fill operations in the US Southeast represent the most penetrable entry point, as incumbent hardware vendors lag software-native architecture deployment. Disposable fluid path dispensers for Swiss CMO high-potency compound handling offer premium margin capture. Go-to-market angle: outcome-based per-dose contracts transferring utilization risk from buyers.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated precision fluid dynamics specialists with embedded firmware capabilities and existing FDA 510(k) clearances. Long-term viability hinges on cybersecurity certification velocity as FDA premarket guidance extends launch timelines. Signal to watch: penetration testing and SBOM documentation completion rates among target portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables GPO-mandated ERP integration and multi-site inventory synchronization for hospital networks. |
| MDR Pre-Validation Investment | Accelerates German hospital procurement cycles by embedding automated adverse event logging firmware. |
| Ultrasonic Piezoelectric Transition | Eliminates compressed air infrastructure from cleanroom designs while compressing maintenance intervals. |
| Backward Integration into Analytics | Captures recurring subscription revenue from predictive inventory management in healthcare networks. |
| Semiconductor Supply Partnership | Secures microcontroller allocation from Taiwan and South Korea foundries during capacity constraints. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submissions, hospital GPO contract databases, and SEC equipment manufacturer disclosures. Interviews with hospital pharmacy directors, biomedical engineers, GPO contracts managers, and precision fluid dynamics R&D heads inform demand-side validation. Bottom-up unit shipment estimates triangulate against top-down healthcare IT capex allocations.
Forecast inputs span product type evolution, deployment architecture migration, end-user consolidation patterns, and regulatory enforcement intensity across the analysis window. Segmentation dimensions modeled include compliance tier, functionality bundle, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and greenfield automation penetration curves, with semiconductor supply constraints and stainless steel price volatility as sensitivity inputs.
Practitioners should monitor FDA cybersecurity guidance finalization, EU MDR notified body capacity, and Taiwan foundry allocation announcements for early signals of forecast revision. Semiconductor lead time normalization and nickel price stabilization would accelerate hardware replacement cycles. Quarterly review of GPO contract terms and MDR validation completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Application Performance Management Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
Load Balancer Market
Digital Solutions
Core Graphics Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Weather App Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
Conference Room Solutions Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Digital String Encoder Market