
 Weather Information Technologies Market | 2026-2036
Weather Information Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Weather Information Technologies Market Intelligence
EU CSRD disclosure mandates are pivoting how transport and logistics operators justify meteorological procurement budgets. Vaisala leverages its sensor manufacturing depth to anchor European aviation contracts. IBM competes through integrated cloud analytics platforms that merge forecasting with enterprise resource planning. StormGeo specializes in maritime route optimization, sustaining premium positioning among shipping lines that face fuel cost volatility.
Weather information technologies encompass hardware, software, and services that capture, transmit, and analyze atmospheric parameters including temperature, humidity, barometric pressure, wind velocity, and precipitation density to support operational decision-making. Remote sensing systems and weather sensors constitute the foundational hardware layer, while machine learning algorithms embedded in forecasting software transform raw telemetry into actionable predictions. Satellite technology leads in coverage breadth for maritime and aerospace end users, whereas IoT devices represent the fastest-expanding segment as agricultural operators deploy distributed ground sensor networks. Cloud-based solutions capture growing margin pools by reducing capital barriers for small and mid-sized emergency services agencies.
FAA certification requirements govern aviation weather system deployment in the United States, while EASA standards shape European aerospace procurement specifications. The EU AI Act introduces algorithmic transparency obligations that affect machine learning-driven forecasting platforms sold across member states. Stakeholders must monitor how divergent regulatory timelines for AI governance between Brussels and Washington reshape product development roadmaps and market access strategies.
Market Dynamics
EU CSRD disclosure mandates and FAA NextGen modernization are compressing procurement cycles for atmospheric monitoring systems across transport fleets, forcing vendors to recalibrate sensor platforms for dual-jurisdiction compliance.
Growth Catalysts
- EU Green Deal emissions tracking:Transport operators in Germany and the Netherlands now embed meteorological data into carbon disclosure workflows, expanding sensor network contracts.
- Precision agriculture sensor densification:Farmers in the US Corn Belt deploy distributed IoT ground stations to optimize irrigation timing against evapotranspiration models.
- Aviation real-time turbulence detection:Long-haul carriers retrofit fleets with lidar and radar-based atmospheric monitoring to reduce fuel burn from altitude deviations.
Market Restraints
- Semiconductor input cost volatility:MEMS barometric pressure sensors depend on specialized foundry capacity concentrated in Taiwan, creating procurement uncertainty.
- Satellite launch capacity bottlenecks:Low-earth orbit weather constellation deployment faces queue constraints at Cape Canaveral and Kourou launch sites.
- Radiosonde substitution by drones:Atmospheric profiling agencies in developed markets pilot uncrewed aerial systems for upper-air measurements, threatening traditional balloon-borne sensor demand.
Strategic Opportunities
- India agricultural microclimate networks:State-level farming cooperatives in Maharashtra and Punjab lack granular precipitation forecasting, opening ground station deployment.
- EU AI Act algorithmic transparency:Machine learning forecasting platforms that document training data provenance gain preferential procurement status across member state meteorological services.
- Edge computing convergence with 5G:Ultra-low latency telemetry processing enables port logistics operators in Rotterdam and Hamburg to integrate hyperlocal wind data into crane scheduling.
Industry Challenges
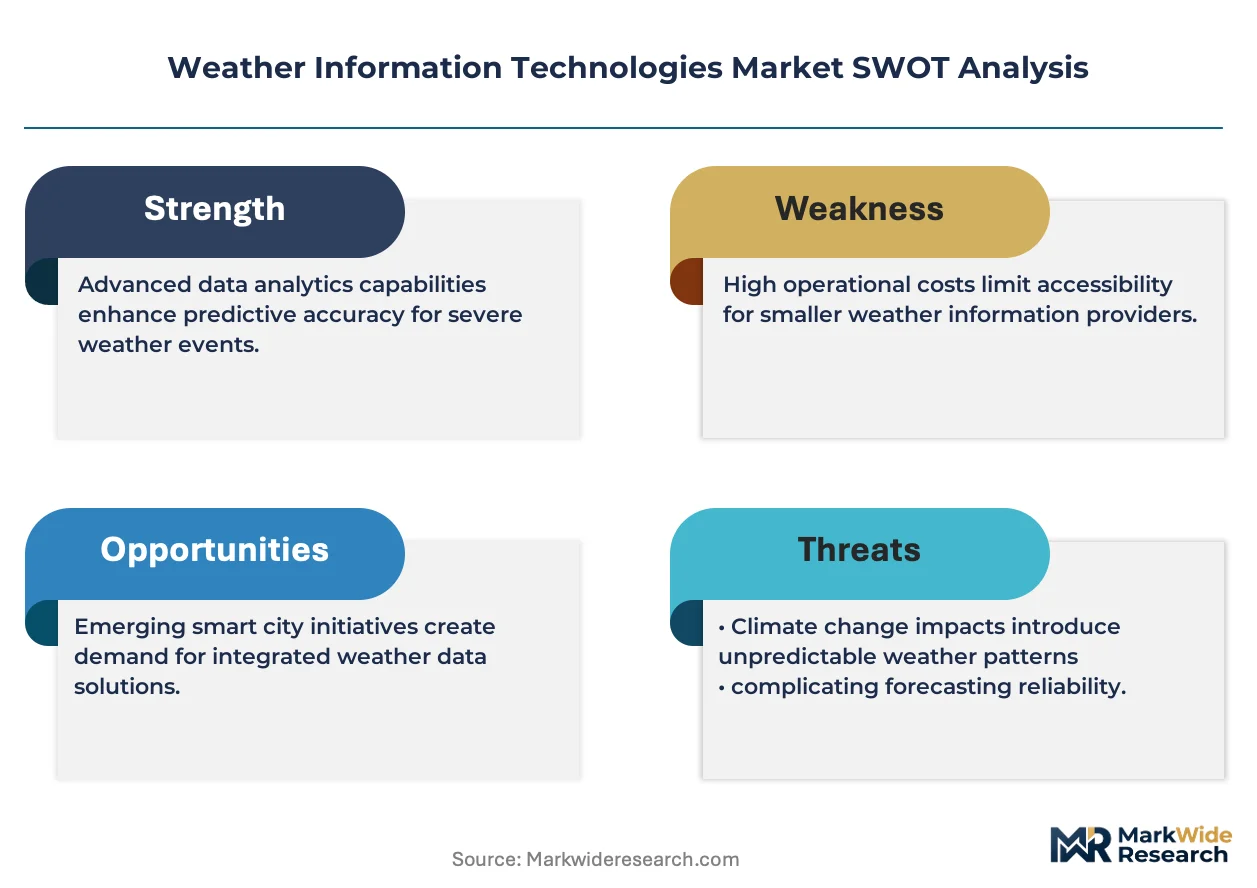
- Atmospheric data scientist scarcity:PhD-level expertise in numerical weather prediction and machine learning hybridization concentrates at national meteorological institutes, constraining vendor hiring pipelines.
- FAA TSO-C154c certification timelines:Aviation sensor manufacturers face 18-24 month validation queues for onboard turbulence detection systems, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weather Information Technologies Market |
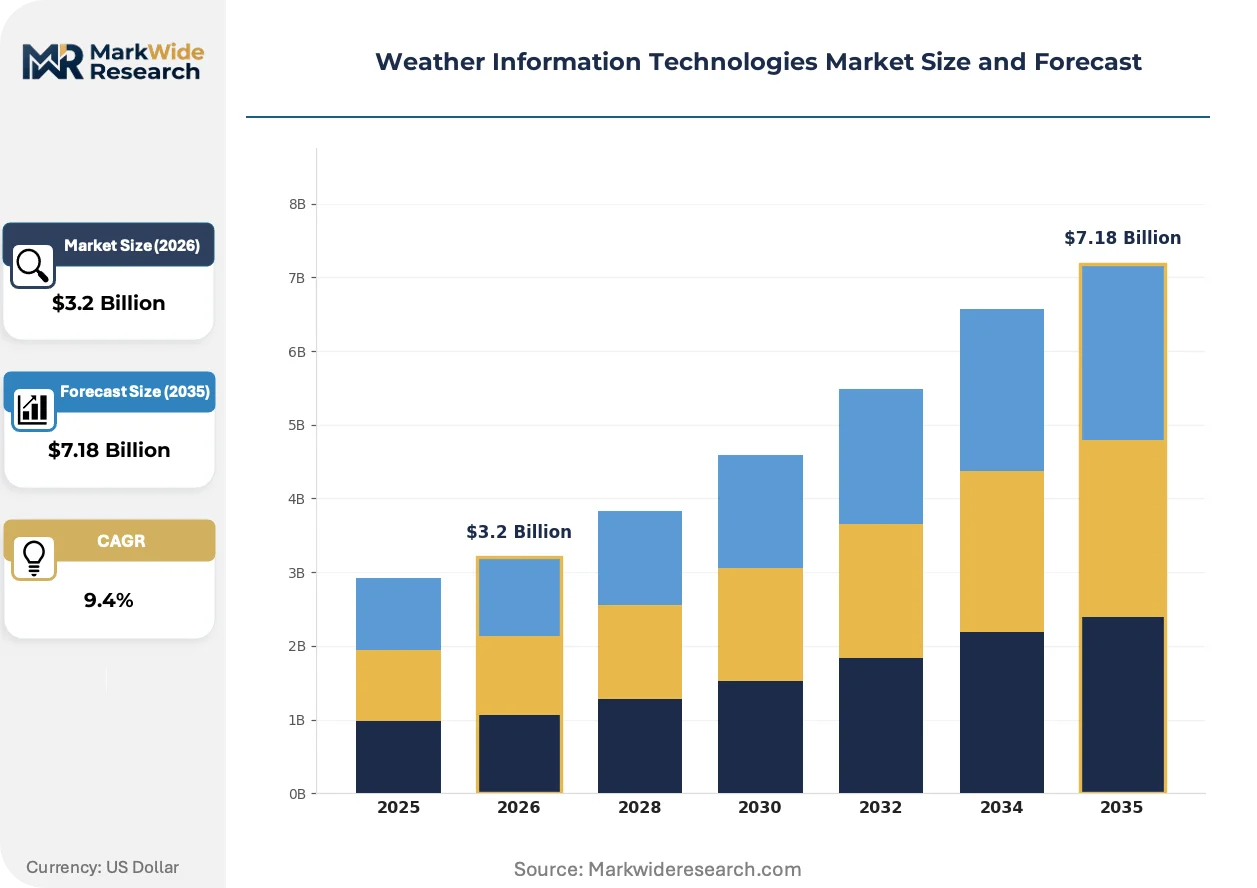
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $7.18 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weather Sensors, Remote Sensing Systems, Weather Forecasting Software, Data Analytics Tools Technology: Satellite Technology, Radar Systems, IoT Devices, Machine Learning Algorithms End User: Aerospace, Agriculture, Maritime, Emergency Services Deployment: Cloud-Based Solutions, On-Premise Systems, Hybrid Models, Mobile Applications |
| Companies Covered | Vaisala, The Weather Company LLC, AccuWeather Inc., DTN, StormGeo, Campbell Scientific Inc., IBM, Lockheed Martin Corporation, Columbia Weather Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weather Information Technologies Market Strategic Shifts & Innovations
Sensor hardware architectures and regulatory disclosure frameworks are restructuring how atmospheric data flows from capture to operational decision-making, compressing legacy value chain positions.
Edge-deployed AI inference chips from NVIDIA and Qualcomm are modularizing how agricultural sensor networks process raw telemetry. Farm operators in California's Central Valley now run precipitation prediction models directly on field-mounted gateways, eliminating round-trip latency to cloud data centers. This distributed architecture is modularizing the traditional hardware-software bundling that dominated precision agriculture procurement.
The EU AI Act's risk classification system for automated decision-making tools imposes documentation burdens on machine learning forecasting platforms sold across member states. Vendors must maintain algorithmic change logs and training data audit trails for high-risk applications including aviation route optimization. German transport operators now require these compliance attestations as standard procurement criteria, reshaping product development roadmaps.
Subscription-based sensor-as-a-service contracts displace capital-heavy ownership models among mid-sized Brazilian agricultural cooperatives. Equipment financiers in São Paulo underwrite ground station deployments against yield improvement guarantees, transferring operational risk from growers to technology providers. This financing innovation concentrates fastest in soybean-producing regions where weather volatility directly correlates with revenue variance.
Weather Information Technologies Market Segmentation
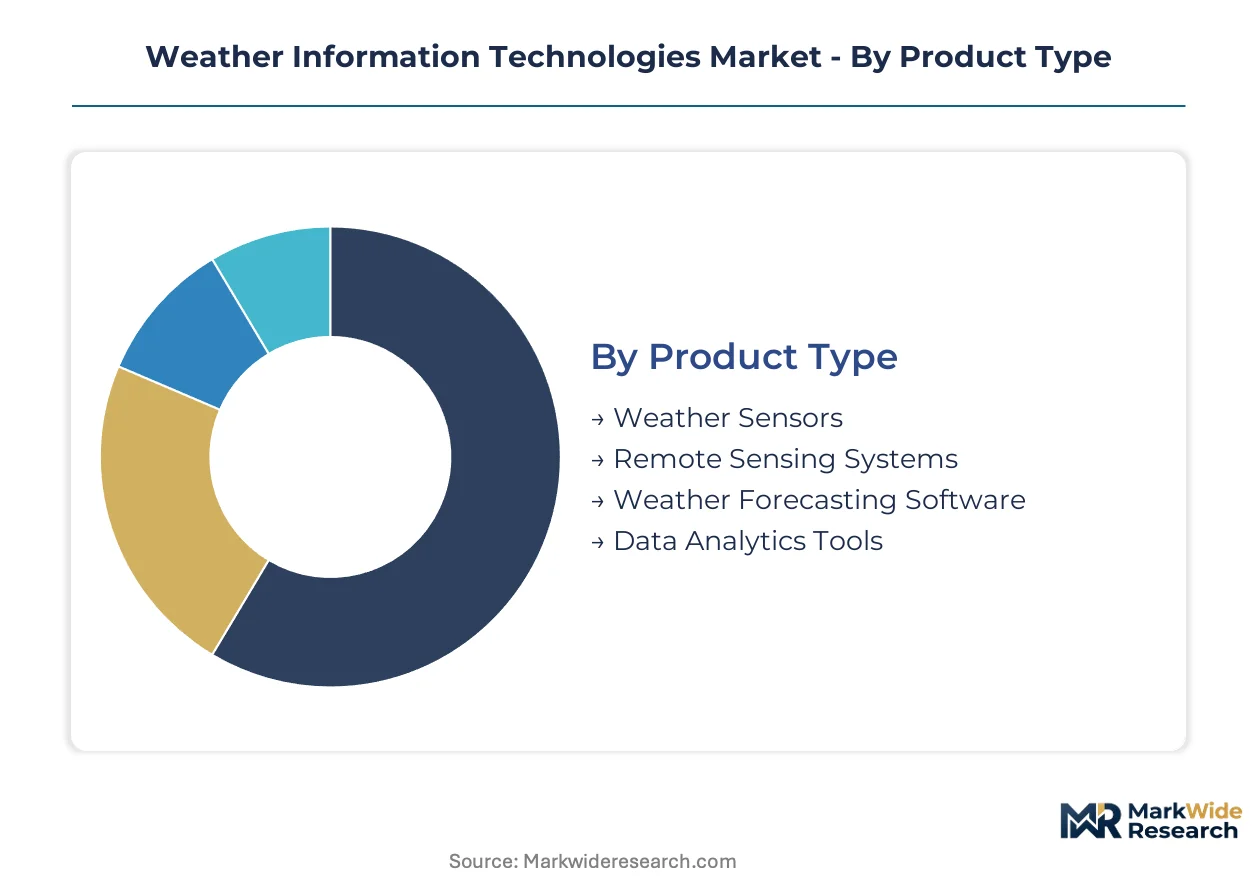
Segmentation in weather information technologies reveals how capital allocation, regulatory exposure, and operational complexity vary across hardware, software, and service layers. Procurement patterns diverge sharply between asset-heavy sensor networks and lightweight cloud analytics subscriptions.
Product Type:
Capital intensity peaks in sensor manufacturing and satellite ground infrastructure, while software platforms leverage marginal distribution economics.
- Weather Sensors:MEMS-based barometric pressure and humidity transducers require specialized foundry partnerships and calibration facilities. German precision agriculture clusters and Rotterdam port logistics operators drive densification of ground-based sensor networks under EU Green Deal disclosure mandates.
- Remote Sensing Systems:Lidar and radar atmospheric profilers demand aerospace-grade certification and satellite launch coordination. Long-haul aviation retrofit programs in the United States absorb the majority of turbulence detection system procurement as FAA NextGen modernization compresses fleet upgrade timelines.
- Weather Forecasting Software:Numerical prediction models run on cloud compute instances with minimal marginal cost per additional subscriber.
- Data Analytics Tools:Visualization dashboards and API-accessible telemetry streams serve emergency services agencies with limited capital budgets.
Remote Sensing Systems absorb the bulk of installed capacity; Weather Sensors are expanding most quickly.
Technology:
Technology selection hinges on coverage requirements versus latency sensitivity, with orbital assets serving maritime domains and terrestrial networks dominating agricultural microclimate monitoring.
- Satellite Technology:Low-earth orbit constellations deliver synoptic coverage for oceanic shipping routes and transcontinental flight corridors. Launch capacity constraints at Cape Canaveral and Kourou create deployment bottlenecks for next-generation weather satellite programs.
- IoT Devices:Distributed ground sensor networks transmit precipitation and soil moisture telemetry over cellular or LoRaWAN protocols. Maharashtra and Punjab farming cooperatives in India pilot subscription-based deployments against yield improvement guarantees.
- Radar Systems:Doppler precipitation radar installations require national meteorological service coordination and spectrum allocation.
- Machine Learning Algorithms:Neural network precipitation nowcasting runs inference workloads on edge-deployed NVIDIA and Qualcomm chips in California's Central Valley.
Satellite Technology carries the heaviest infrastructure burden; IoT Devices are climbing the fastest.
End User:
End-user procurement cycles range from multi-year aviation certification programs to annual agricultural equipment financing arrangements.
- Aerospace:Onboard atmospheric monitoring systems require FAA TSO-C154c or EASA equivalent certification with 18-24 month validation queues. Real-time turbulence detection retrofits target fuel burn reduction through altitude optimization on transoceanic routes.
- Agriculture:Irrigation timing decisions depend on evapotranspiration models fed by distributed ground station networks. US Corn Belt operators deploy capital through equipment financiers rather than direct sensor ownership.
- Maritime:Route optimization services integrate hyperlocal wind data into voyage planning for fuel cost volatility management.
- Emergency Services:Cloud-based severe weather alerting platforms reduce capital barriers for mid-sized municipal agencies.
Aerospace dominates absolute procurement value; Agriculture is gaining share fastest.
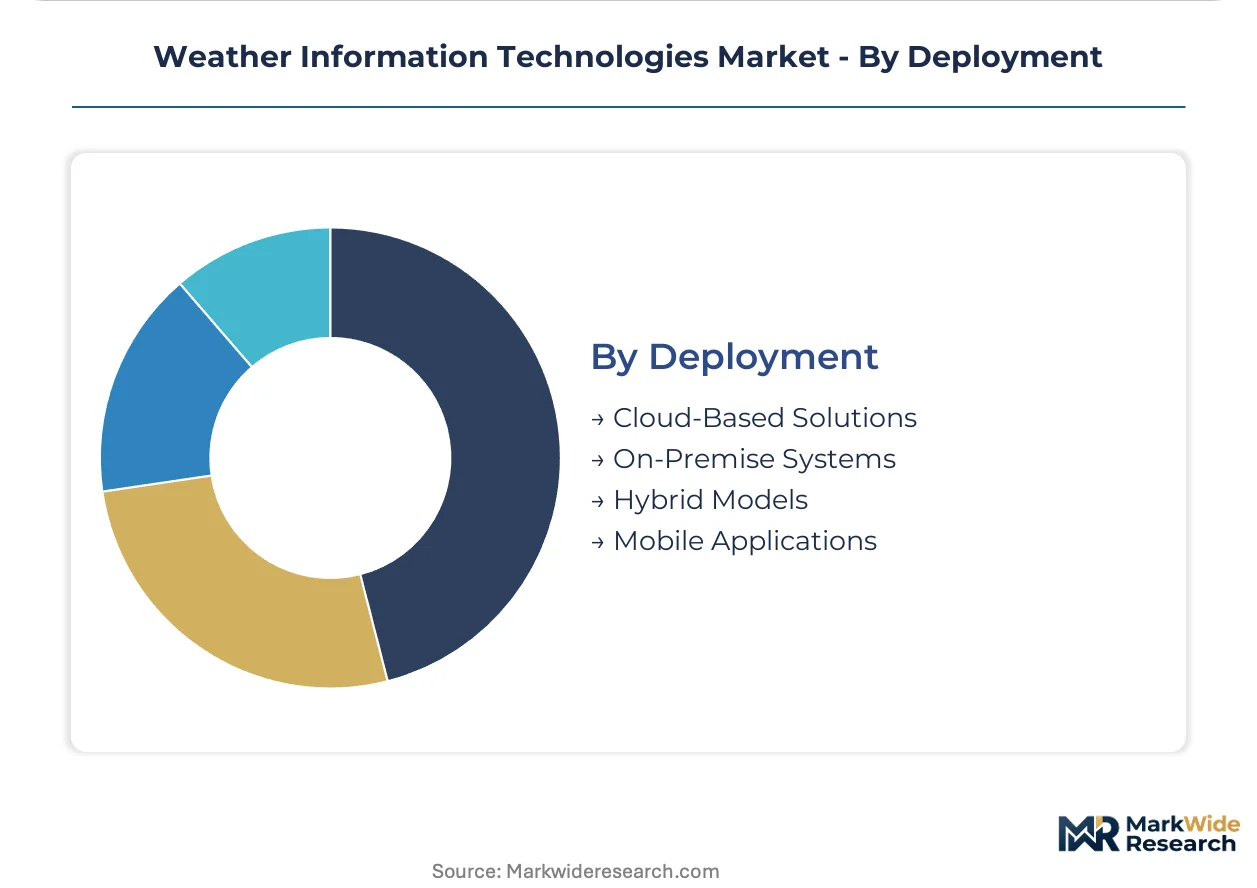
Deployment:
Deployment architecture determines operational control, data sovereignty exposure, and integration complexity with legacy enterprise systems.
- Cloud-Based Solutions:Subscription telemetry platforms eliminate upfront sensor capital for Brazilian agricultural cooperatives. São Paulo equipment financiers underwrite ground station deployments against yield performance, transferring operational risk from growers to technology providers.
- Hybrid Models:Edge inference gateways process raw telemetry locally while transmitting aggregated analytics to central cloud repositories. Port logistics operators in Rotterdam and Hamburg integrate hyperlocal wind data into crane scheduling through 5G-enabled ultra-low latency architectures.
- On-Premise Systems:National meteorological services maintain sovereign control over raw atmospheric data and algorithmic training pipelines.
- Mobile Applications:Consumer-grade precipitation alerting delivers minimal marginal revenue per user but extends brand reach.
Cloud-Based Solutions capture the widest subscriber base; Hybrid Models are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Rotterdam and Hamburg concentrate port logistics demand for hyperlocal meteorological systems. EU Green Deal disclosure mandates and FAA NextGen timelines compress procurement cycles across transport corridors. National meteorological services in Germany, the United States, India, China, and Brazil anchor sensor network deployment.
United States
FAA NextGen modernization drives aviation sensor retrofit programs across long-haul carrier fleets. TSO-C154c certification requirements govern onboard turbulence detection system validation. California's Central Valley agricultural operators deploy edge AI inference chips for precipitation prediction directly on field-mounted gateways.
Germany
EU CSRD mandates force transport operators to embed meteorological data into carbon disclosure workflows. EASA standards shape aerospace procurement specifications alongside Brussels algorithmic transparency rules. Precision agriculture clusters in Bavaria and port logistics operators in Hamburg densify ground-based sensor networks.
India
State-level farming cooperatives in Maharashtra and Punjab pilot subscription-based ground station deployments against yield improvement guarantees. The central agricultural regulator promotes microclimate network expansion through equipment financing structures. Andhra Pradesh and Gujarat port authorities integrate satellite-derived wind data into container crane scheduling.
China
Dual carbon goals accelerate emissions tracking requirements for transport and logistics fleets. National meteorological services maintain sovereign control over raw atmospheric data and algorithmic training pipelines. Yangtze River Delta manufacturing clusters absorb MEMS sensor production for regional precision agriculture networks.
Brazil
São Paulo equipment financiers underwrite ground station deployments against yield performance guarantees in soybean-producing regions. ANVISA regulatory frameworks govern agricultural technology certification timelines. Minas Gerais and Rio Grande do Sul farming cooperatives displace capital-heavy ownership models with sensor-as-a-service contracts.
Weather Information Technologies Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing, software platforms, and integrated service bundles. The vendor base organizes into three strategic archetypes: sensor hardware fabricators with aerospace certification depth, cloud analytics providers merging forecasting with enterprise resource planning, and maritime route optimization specialists commanding premium positioning among fuel-cost-sensitive shipping lines. Dominant competitive moves include vertical integration into specialized foundry partnerships for MEMS component security and algorithmic transparency documentation to satisfy EU AI Act procurement criteria.
Among diversified technology conglomerates, IBM and Lockheed Martin occupy positions spanning cloud infrastructure and aerospace systems integration. Vaisala and StormGeo exemplify focused specialists—Finnish sensor manufacturing depth anchors European aviation contracts, while Norwegian maritime expertise sustains premium route optimization services. Campbell Scientific and Columbia Weather Systems represent mid-scale instrumentation fabricators competing on calibration precision and regional service density.
| Leading Market Players |
|---|
| Vaisala |
| The Weather Company LLC |
| AccuWeather Inc. |
| DTN |
| StormGeo |
| Campbell Scientific Inc. |
| IBM |
| Lockheed Martin Corporation |
| Columbia Weather Systems Inc. |
| Others |
Cost & Logistics Intelligence
Long-haul aviation procurement programs compress vendor pricing power through multi-year certification-driven contracts, while agricultural cooperatives negotiate sensor-as-a-service subscriptions that transfer capital risk to equipment financiers. EU CSRD disclosure mandates elevate meteorological data to compliance-critical status, reducing price elasticity among transport operators facing emissions audit requirements.
Pricing Analysis
Lead-time premiums attach to aviation sensor platforms facing FAA TSO-C154c certification queues, while spot inventory discounts emerge for standardized MEMS components in agricultural IoT deployments. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified systems from industrial-grade sensors and consumer telemetry devices. Cost compression in MEMS foundry capacity is intensifying because Taiwan semiconductor allocation constraints extend delivery windows. Agricultural cooperatives exhibit highest price sensitivity, whereas aviation retrofit programs prioritize certification reliability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from EASA and FAA procurement specifications force aviation sensor manufacturers to qualify secondary MEMS foundry partners beyond Taiwan. Supply concentration centers on Taiwan for MEMS fabrication, Germany for precision calibration equipment, and China for rare earth magnet components in lidar assemblies. Raw material dependencies include specialized silicon wafers, aerospace-grade aluminum housings, and gallium nitride substrates. Single-source vulnerability persists in Taiwan foundry capacity for barometric pressure transducers. Distribution runs through authorized aerospace distributors for certified systems and direct-to-farmer channels for agricultural IoT networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge AI inference architectures are displacing cloud-dependent telemetry processing in precision agriculture, compressing legacy hardware-software bundling models. This technology transition demands recalibrated competitive positioning across sensor manufacturing and analytics platform layers.
For Market Incumbents: Deepen backward integration into MEMS foundry partnerships to secure semiconductor allocation against Taiwan capacity constraints. Expand algorithmic transparency documentation capabilities to satisfy EU AI Act procurement criteria for machine learning forecasting platforms. Prioritize EASA certification investment to defend European aviation retrofit contracts against integrated cloud analytics competitors. For New Entrants and Emerging Players: Cloud-native API platforms offer the lowest-friction entry path into mid-sized Brazilian agricultural cooperatives seeking subscription-based microclimate monitoring. Target Maharashtra and Punjab farming regions where state-level equipment financing structures reduce customer acquisition costs. Pursue white-label partnerships with São Paulo equipment financiers to embed sensors within yield-guarantee contracts. For Investors and Strategic Acquirers: The window for entry favors specialists with dual aerospace-agricultural certification capabilities rather than pure-play software vendors. Long-term viability hinges on regulatory compliance depth across FAA, EASA, and emerging EU AI Act jurisdictions. Monitor India state-level farming cooperative procurement volumes as inflection indicator for agricultural sensor densification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Documentation | EU AI Act compliance attestation unlocks preferential procurement status across German transport operators. |
| MEMS Foundry Partnership Expansion | Taiwan semiconductor allocation security reduces aviation sensor delivery risk against 18-24 month certification timelines. |
| Edge AI Inference Chip Integration | NVIDIA and Qualcomm gateway deployment eliminates cloud latency for California Central Valley precipitation prediction. |
| Sensor-as-a-Service Financing Structure | São Paulo equipment financiers transfer operational risk from Brazilian soybean growers to technology providers. |
| Dual-Jurisdiction Certification Investment | Simultaneous FAA-EASA validation compresses time-to-revenue for long-haul carrier retrofit programs. |
Research Approach
Independent corroboration across aviation procurement officers, agricultural cooperative managers, meteorological service directors, and semiconductor supply planners underwrites the qualitative findings. Primary interviews with FAA certification specialists, EASA technical auditors, and port logistics operators in Rotterdam and Hamburg informed regulatory compliance dynamics. Secondary validation drew from FAA TSO certification databases, EU CSRD implementation guidance, semiconductor trade flow records, and national meteorological service procurement disclosures. Bottom-up sensor deployment counts triangulate against top-down transport fleet emissions tracking requirements.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions include product type, technology architecture, end-user vertical, and deployment model. CAGRs derive from fitted growth curves against historical procurement cycle data. Industry-specific forecast inputs incorporate satellite launch queue constraints at Cape Canaveral and Kourou, plus EU AI Act implementation timelines affecting machine learning platform adoption.
Inputs from aviation certification databases and agricultural equipment financing registries were available through the study window; gaps in real-time MEMS foundry utilization data introduce uncertainty bands around hardware deployment forecasts. Deviation in Taiwan semiconductor allocation policy or FAA TSO-C154c validation timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Microservices Architecture Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
France Digital Twin Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
United Kingdom ICT Market
Digital Solutions
Global Media (Video) Processing Solutions Market
Digital Solutions
Business As a Service Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
Product Information Management Market