
 Car Cleaning Products Market | 2026-2036
Car Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
Car Cleaning Products Market Outlook
Professional-grade ceramic-coating compatibility is collapsing the boundary between consumer and commercial car cleaning tiers. 3M Company leverages its industrial adhesives heritage to sustain chemistry leadership in paint-safe compounds. Turtle Wax anchors mass-market shelf presence through big-box retail partnerships. Meguiar's Inc. differentiates via enthusiast-channel depth and pro-detailer certification programs.
Car cleaning products comprise surfactant-based, solvent-based, and polymer-enhanced formulations engineered to remove contaminants, restore finish clarity, and protect vehicle substrates without degrading clear-coat or interior trim materials; pH-neutral shampoo concentrates typically operate between 6.5 and 7.5 to prevent etching. The exterior application segment dominates volume as weathering exposure drives repeat purchase cycles, while the detailing segment captures disproportionate margin through kit bundling and labor attachment. Liquid formulations lead in absolute tonnage, though foam delivery systems are gaining share in automated car wash installations for reduced water consumption.
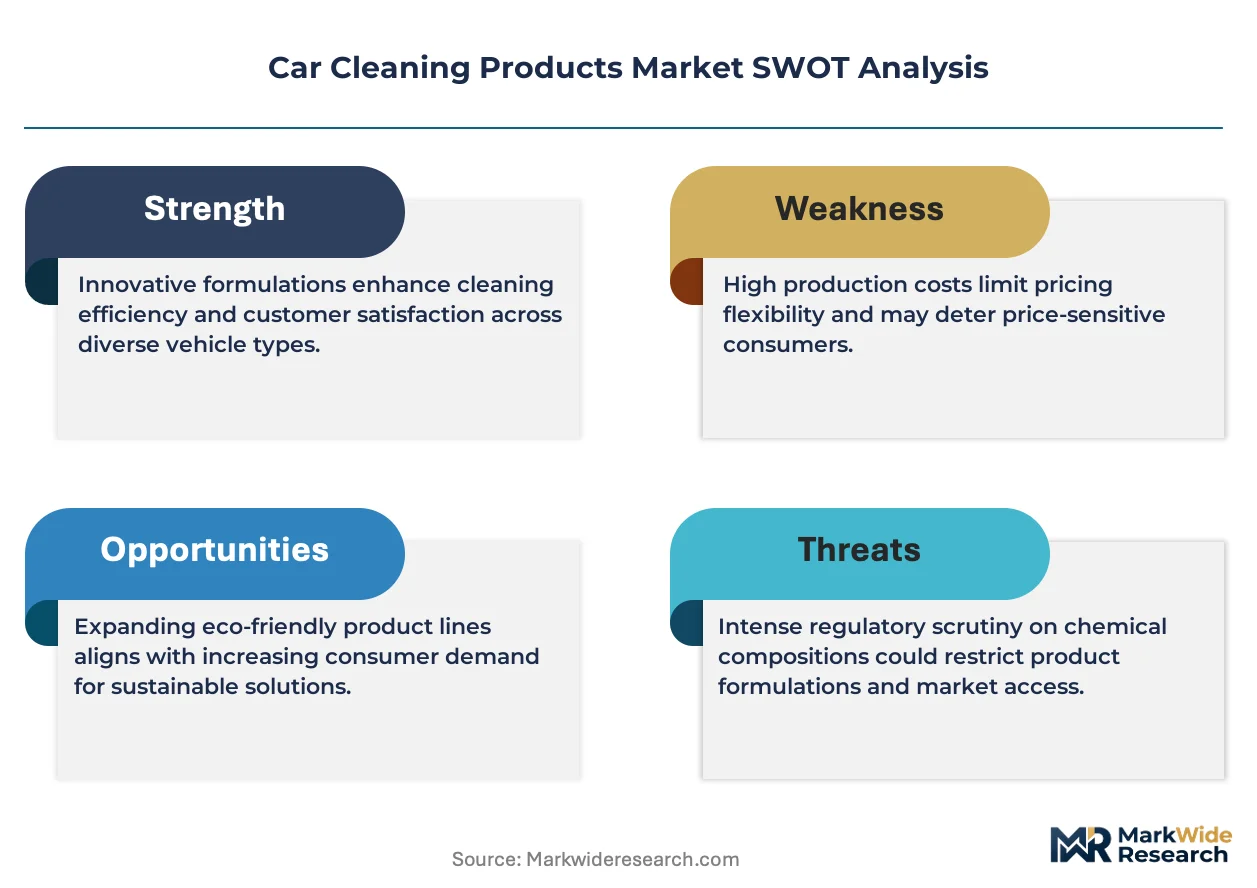
EPA oversight of volatile organic compound limits under the Clean Air Act shapes aerosol propellant choices and solvent selection for US manufacturers, while REACH compliance in Europe mandates full substance disclosure and hazard communication across the supply chain. California's DTSC Safer Consumer Products program actively lists automotive maintenance chemicals for priority evaluation, pressuring formulators toward green chemistry substitutions. Stakeholders must monitor pending EPA rulemakings on per- and polyfluoroalkyl substances, as fluorinated polymers in paint sealants face prospective restriction.
Market Dynamics
California's DTSC Safer Consumer Products program is forcing wholesale reformulation of solvent-based degreasers and paint sealants, collapsing legacy surfactant chemistries while opening patent windows for bio-based alternatives. This regulatory compression is reshaping R&D allocation across the entire supply base.
Growth Catalysts
- Professional Detailing Expansion:High-end ceramic coating services in Stuttgart and Munich are driving concentrated demand for pH-neutral shampoo concentrates and polymer-enhanced protectants.
- REACH Compliance Disclosure:Full substance transparency mandates across Europe are accelerating supplier consolidation toward certified green chemistry formulators.
- Waterless Cleaning Chemistry:Surfactant innovations enabling rinse-free application are capturing share in drought-prone US Southwest municipalities facing usage restrictions.
Market Restraints
- Petrochemical Feedstock Volatility:Polymer-enhanced sealants depend on ethylene oxide derivatives whose pricing swings compress margin predictability for mid-tier compounders.
- Aerosol Propellant Constraints:EPA Clean Air Act VOC limits restrict hydrofluorocarbon options, forcing costly retooling of spray-delivery packaging lines.
- Fluorinated Polymer Substitution Risk:Pending EPA PFAS rulemakings threaten paint sealant durability claims, with silicone alternatives offering inferior longevity.
Strategic Opportunities
- Subscription Detailing Kits:Direct-to-consumer bundling of seasonal protectants and microfiber systems is bypassing big-box retail margin extraction.
- Automated Car Wash Integration:Foam-delivery chemistry optimized for frictionless tunnel systems offers volume scale in Germany's aftermarket cluster.
- Biodegradable Surfactant Patents:Early filing positions in alkyl polyglucoside derivatives create defensible IP around California-compliant formulations.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in surfactant-polymer compatibility at pH-neutral ranges is concentrating among aging specialists near retirement.
- Multi-Jurisdiction Certification Lag:Simultaneous EPA, REACH, and state-level DTSC approvals extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Cleaning Products Market |
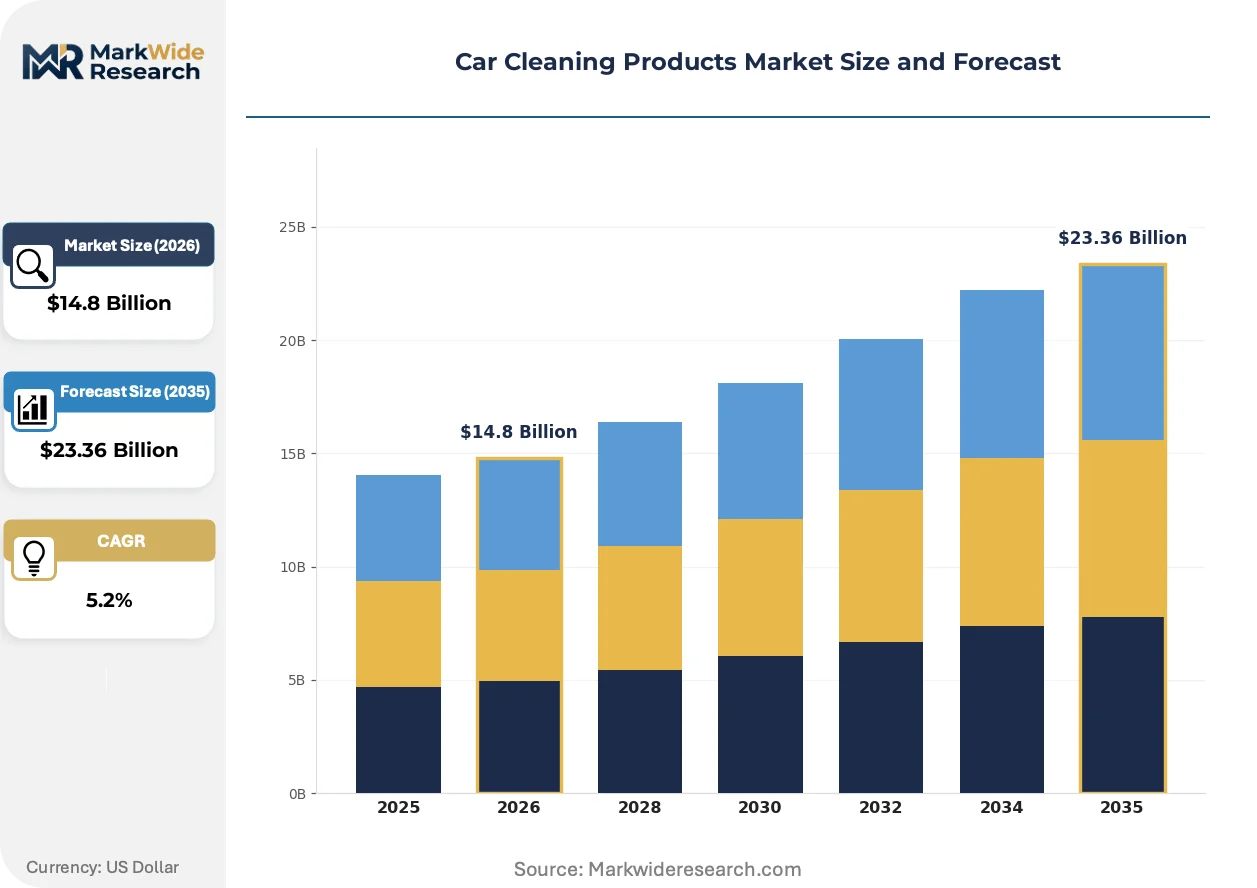
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.36 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Wax, Spray, Polish Application: Interior, Exterior, Detailing, Maintenance Form: Aerosol, Liquid, Gel, Foam End User: Consumers, Detailers, Car Washes, Dealers |
| Companies Covered | Armor All, Chemical Guys, Turtle Wax, Autoglym, Mothers Polishes Waxes Cleaners, 3M Company, Sonax GmbH, Simoniz USA, Meguiar's Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Cleaning Products Market Strategic Shifts
Formulation science is converging with automated application hardware and regulatory compliance systems, collapsing the traditional separation between chemical performance and delivery mechanism engineering.
Waterless surfactant chemistry is miniaturizing the car cleaning workflow from multi-step wash-rinse-dry sequences to single-application wipe systems. Professional mobile detailers in water-restricted California municipalities are adopting these concentrates at accelerating rates. This compression is miniaturizing equipment footprints and enabling service models previously confined to fixed-bay operations.
REACH substance disclosure requirements are forcing full supply chain transparency for solvent-based degreasers and interior cleaners. Formulators must now document hazard classifications for every constituent compound above 0.1% concentration. The exterior application segment is responding by accelerating alkyl polyglucoside substitutions ahead of sunset dates for ethoxylated alcohols.
Buyer concentration among national car wash chains is disintermediating traditional distributor networks in the automated installation channel. These operators now contract directly with compounders for custom foam-viscosity formulations. Germany's Stuttgart-Munich corridor exhibits this pattern most acutely, with tunnel operators specifying proprietary surfactant blends unavailable through retail channels.
Car Cleaning Products Market Segmentation
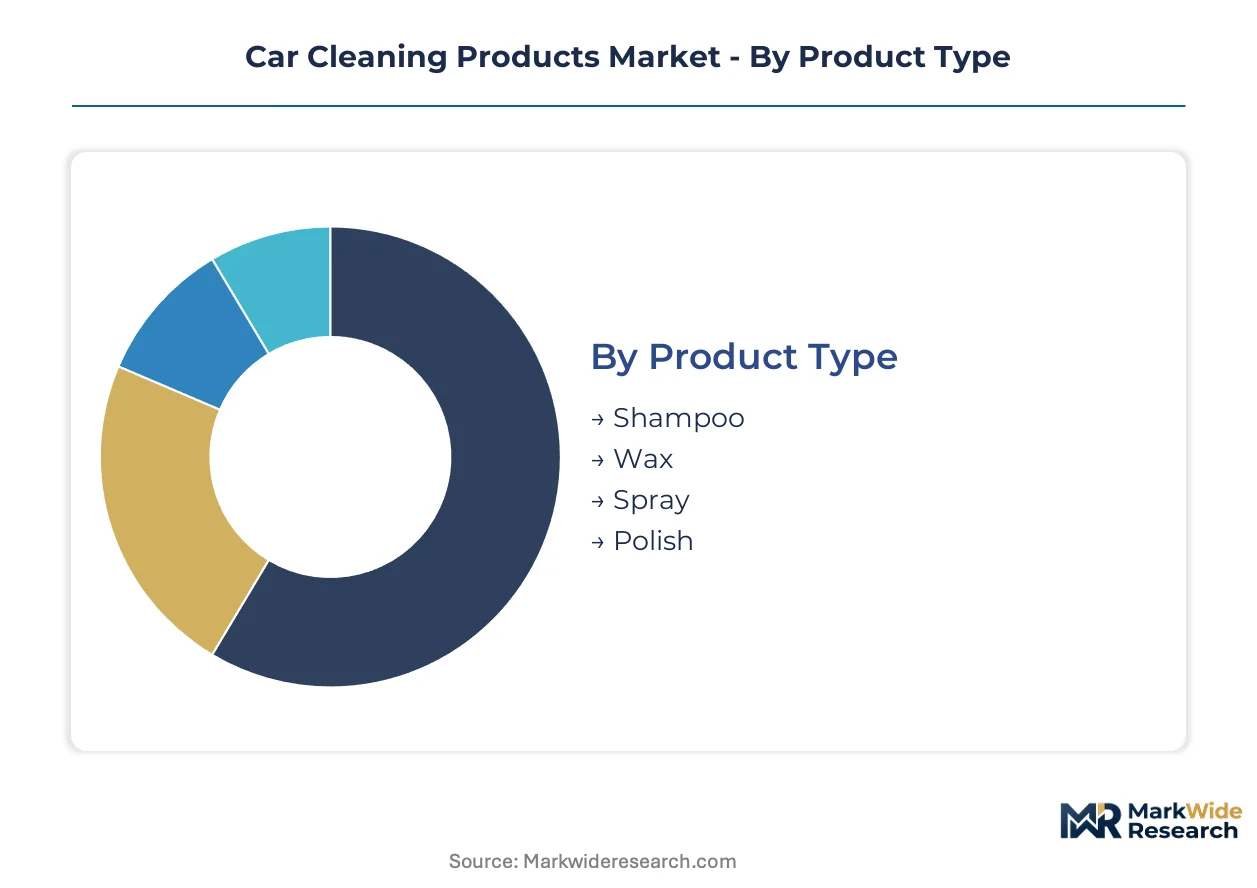
Car cleaning products fragment across four intersecting dimensions that determine formulation chemistry, packaging format, and channel strategy. Each segmentation axis carries distinct margin profiles and regulatory exposure, forcing manufacturers to prioritize specific combinations rather than full-matrix coverage.
Product Type:
Shampoo dominates domestic consumption in Germany's Stuttgart-Munich corridor, while wax and polish formulations travel farther to export markets.
- Shampoo:pH-neutral concentrates between 6.5 and 7.5 prevent clear-coat etching through chelating surfactants. Stuttgart's professional detailing studios drive concentrated demand for gallon-format concentrates that dilute 128:1.
- Wax:Polymer-enhanced sealants incorporating carnauba or synthetic hydrocarbons command premium shelf positioning. California's DTSC Safer Consumer Products program is forcing reformulation away from solvent-borne paste waxes toward water-based emulsions.
- Spray:Quick-detailer formulations in trigger-spray packaging capture impulse purchases at automotive retail.
- Polish:Abrasive compounds with diminishing abrasives restore oxidized clear-coat through mechanical correction.
Shampoo holds the largest share; momentum sits with wax as ceramic-coating compatibility becomes a baseline specification.
Application:
Exterior formulations generate volume through weather-driven repeat purchase cycles, while detailing applications concentrate margin in labor-attached service bundles.
- Exterior:Surfactant-based cleaners combat road film, brake dust, and environmental contaminants across painted panels, glass, and wheel surfaces. Automated car wash tunnels in Germany specify proprietary foam-viscosity formulations unavailable through retail channels.
- Detailing:Multi-step correction protocols combining clay bar treatment, compound leveling, and sealant protection capture disproportionate margin through kit bundling. REACH substance disclosure mandates are accelerating supplier consolidation toward certified green chemistry formulators.
- Interior:Vinyl, leather, and fabric cleaners address UV degradation and soiling of cabin materials.
- Maintenance:Quick-application protectants extend service intervals between full detailing sessions.
Exterior commands absolute tonnage; detailing climbs the fastest as professional service attachment deepens.
Form:
Liquid formulations anchor mass-market economics through established filling infrastructure, while foam systems demand specialized production investment.
- Liquid:Concentrates and ready-to-use solutions dominate retail shelf space and professional bulk purchasing. EPA Clean Air Act VOC compliance is simpler to achieve in non-pressurized delivery formats.
- Foam:Pre-soak and tunnel-wash chemistry optimized for frictionless application reduces water consumption in automated installations. Germany's national car wash chains now contract directly with compounders for custom surfactant blends.
- Aerosol:Pressurized delivery of quick-detailers and wheel cleaners faces propellant constraints under EPA hydrofluorocarbon restrictions.
- Gel:Thickened formulations cling to vertical surfaces during dwell time for wheel and tire cleaning.
Liquid maintains production scale leadership; foam gains share fastest through automated wash integration.
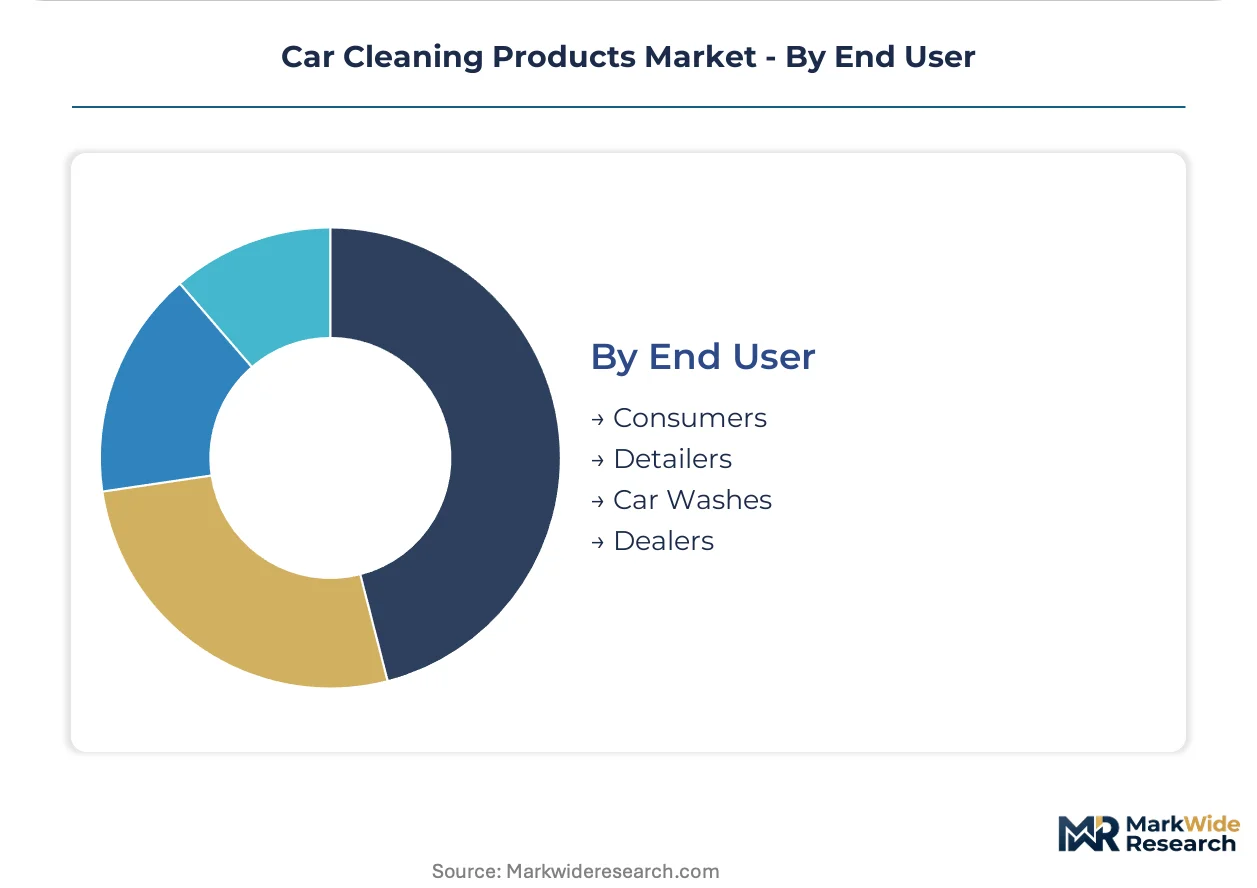
End User:
Consumer purchasing concentrates in big-box retail and e-commerce channels, while professional segments demand technical documentation and bulk logistics.
- Car Washes:National tunnel operators specify proprietary chemistry with direct compounder relationships, bypassing traditional distributor networks. California municipalities with water restrictions are adopting waterless surfactant systems at accelerating rates.
- Detailers:Mobile and fixed-bay professionals require pH-neutral certification and ceramic-coating compatibility documentation. The segment exhibits highest loyalty to brands with pro-detailer certification programs.
- Consumers:DIY purchasers respond to seasonal merchandising and bundled kit offerings through automotive retail and mass-market channels.
- Dealers:New and used vehicle preparation services demand high-volume, cost-optimized formulations with rapid throughput.
Car washes capture volume concentration; detailers drive formulation innovation and margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemistry clusters concentrate in Germany's automotive belt, California's regulatory corridor, and Japan's precision manufacturing zones. Each geography imposes distinct compliance burdens that reshape surfactant sourcing and packaging investments.
United States
Professional mobile detailing services in Los Angeles and San Diego municipalities are accelerating waterless surfactant adoption under municipal usage restrictions. EPA Clean Air Act oversight constrains hydrofluorocarbon propellant selections for aerosol wheel cleaners. California's DTSC Safer Consumer Products program actively lists automotive maintenance chemicals for priority evaluation, forcing reformulation timelines in Sacramento's regulatory orbit.
Germany
Stuttgart and Munich anchor Europe's densest concentration of professional ceramic coating studios, driving concentrated demand for pH-neutral gallon concentrates. REACH compliance mandates full substance disclosure above 0.1% concentration across the supply chain. The Baden-Württemberg automotive cluster exhibits direct contracting between national car wash tunnel operators and compounders for proprietary foam-viscosity formulations.
Japan
Premium vehicle ownership in Tokyo and Osaka metropolitan areas sustains demand for paint-safe compounds with JIS-standard compatibility documentation. METI oversees chemical substance management under the Act on the Evaluation of Chemical Substances. The Kanto region hosts specialized formulators serving domestic OEM dealer preparation networks with rapid-throughput requirements.
China
Automated car wash chain expansion in Shanghai and Guangzhou is absorbing imported surfactant concentrates for frictionless tunnel systems. MEE enforcement of dual carbon goals is pressuring domestic compounders toward biodegradable alkyl polyglucoside substitutions. The Yangtze River Delta exhibits fastest adoption of foam-delivery chemistry optimized for water consumption reduction.
United Kingdom
Enthusiast-channel depth in London and Birmingham sustains demand for multi-step correction kits with ceramic-coating compatibility claims. HSE alignment with REACH substance disclosure extends hazard communication obligations to professional detailer certification programs. The Midlands distribution corridor channels imported German formulations toward independent valeting operations.
Car Cleaning Products Market Competitive Environment
Concentration sits with diversified chemical conglomerates and heritage automotive care specialists. The vendor base spans three functional tiers: mass-market retail anchors, professional-channel certification holders, and industrial-adhesives diversifiers. Strategic moves center on direct-to-consumer subscription bundling and automated wash tunnel supply contracts.
Within the heritage specialist tier, Turtle Wax and Meguiar's Inc. exemplify divergent channel strategies—one anchoring big-box shelf presence through retail partnerships, the other cultivating pro-detailer loyalty via certification depth. 3M Company occupies a position reflecting industrial chemistry heritage applied to paint-safe compound development. Chemical Guys and Mothers Polishes Waxes Cleaners represent enthusiast-channel specialists with concentrated digital-native followings. Sonax GmbH anchors German-origin formulation credibility in European professional circles.
| Leading Market Players |
|---|
| Armor All |
| Chemical Guys |
| Turtle Wax |
| Autoglym |
| Mothers Polishes Waxes Cleaners |
| 3M Company |
| Sonax GmbH |
| Simoniz USA |
| Meguiar's Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day formulation certification timelines in California's DTSC pipeline compress inventory turns for compounders serving West Coast professional detailers, concentrating pricing power with certified green chemistry suppliers while forcing mid-tier manufacturers into spot-market surfactant sourcing at volatile ethylene oxide derivative rates.
Pricing Analysis
California's DTSC Safer Consumer Products program dictates the pricing tier structure across the car cleaning products landscape. Three-tier pricing separates ceramic-coating compatible formulations from standard pH-neutral concentrates from economy solvent-based cleaners, with certification grade and volume scale as the primary price differentiation drivers. Pricing pressure stems from petrochemical feedstock volatility, particularly ethylene oxide derivative swings that compress margin predictability. Car wash chains exhibit lowest price sensitivity due to direct compounder contracting, while independent retailers face highest sensitivity amid big-box retail margin extraction.
Supply Chain Analysis
Germany and the United States anchor surfactant formulation and polymer-enhanced sealant production for professional detailing channels. Raw material dependencies center on ethylene oxide derivatives, alkyl polyglucoside feedstocks, and carnauba wax imports from Brazil. Single-source vulnerability sits with bio-based surfactant patents concentrated among aging specialist formulators near retirement. Distribution runs through direct compounder relationships with national car wash chains, bypassing traditional distributor networks in the automated installation channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemists capable of surfactant-polymer compatibility at pH-neutral ranges represent the scarcest capability layer in this market, with expertise concentrating among specialists approaching retirement and limited pipeline replenishment from academic programs.
For Market Incumbents: Compound certification depth in ceramic-coating compatibility to defend against private-label entrants from industrial adhesives diversifiers. Deepen backward integration into alkyl polyglucoside feedstock sourcing to secure California compliance ahead of DTSC sunset dates. Prioritize captive supply of biodegradable surfactant precursors to insulate margin from petrochemical volatility. For New Entrants and Emerging Players: Anchor in waterless surfactant chemistry for drought-restricted California municipalities, where municipal usage restrictions have created the most penetrable service segment. Target mobile detailing operators seeking equipment footprint miniaturization. Pursue direct-to-consumer subscription bundling of seasonal protectants to bypass established retail shelf control. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with neglected automotive care divisions holding dormant formulation libraries and established professional channel relationships. Long-term viability hinges on regulatory compliance capability rather than brand equity alone. Watch for EPA PFAS rulemaking finalization as the critical inflection signal for paint sealant chemistry restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Surfactant Patent Filing | Early positions in alkyl polyglucoside derivatives create defensible IP around California DTSC compliance requirements. |
| Direct-to-Consumer Subscription Launch | Bypasses big-box retail margin extraction while capturing recurring revenue from enthusiast and professional detailer segments. |
| Automated Car Wash Supply Contract | Custom foam-viscosity formulations for tunnel operators in Germany's Stuttgart-Munich corridor secure volume scale. |
| Professional Detailer Certification Program | Deepens loyalty among mobile and fixed-bay operators who require pH-neutral documentation and ceramic-coating compatibility. |
| Waterless Chemistry R&D Investment | Surfactant innovations enabling rinse-free application address municipal restrictions in California's Los Angeles and San Diego markets. |
Study Parameters
A spread of perspectives from formulation chemists, professional detailer certification program directors, car wash chain procurement managers, and automotive retail category buyers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA rulemaking dockets, REACH substance registration databases, California DTSC priority product listings, and trade customs data for surfactant feedstock flows. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, form, and end user dimensions.
Segmentation dimensions modeled include product chemistry tier, delivery mechanism format, professional versus consumer channel, and regional regulatory cluster across the analysis window. CAGRs derived from trend extrapolation of professional detailing service expansion rates, ceramic coating adoption curves, and automated car wash installation growth. Forecast inputs incorporated surfactant innovation diffusion patterns and multi-jurisdiction certification lag timelines.
Material uncertainties — EPA PFAS rulemaking finalization, ethylene oxide derivative price volatility, and formulation chemist retirement waves — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation schedules and technology substitution rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market